
 Japan Hydropower Market | 2026-2036
Japan Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Hydropower Market Foresight
JIS B 8223 qualification for hydroelectric turbine pressure equipment is rotating the competitive field toward manufacturers with certified forging and welding capabilities. Toshiba Energy Systems & Solutions Corporation leverages its domestic turbine foundry network to anchor large-scale pumped storage contracts. J-POWER Group sustains operational dominance across 50-plus facilities through integrated river basin management. Hitachi Mitsubishi Hydro Corporation differentiates on bulb turbine retrofits for low-head run-of-river sites.
Hydropower in Japan encompasses electricity generation from gravitational water flow through turbine-generator sets, with installed units ranging from sub-megawatt micro installations to 1,000 MW-plus pumped storage facilities operating at heads between 20 and 500 meters. The technology serves baseload balancing, grid frequency regulation, and seasonal storage for an electricity system with limited interregional transmission capacity. Pumped storage systems command the largest capital allocation pools given their role in absorbing solar oversupply from Kyushu and Hokkaido. Small scale run-of-river installations compete for limited grid connection capacity in mountainous watersheds. Francis turbine technology occupies the broadest application envelope across medium-head storage and run-of-river plants.
METI's Strategic Energy Plan and the Agency for Natural Resources and Energy set capacity targets and grid codes that determine which projects secure development permits. JIS standards and the Electric Business Act establish equipment safety and interconnection rules that filter market access for foreign turbine suppliers. Stakeholders must monitor prefectural river basin committees where environmental flow requirements and dam safety re-certification schedules determine redevelopment economics.
Market Dynamics
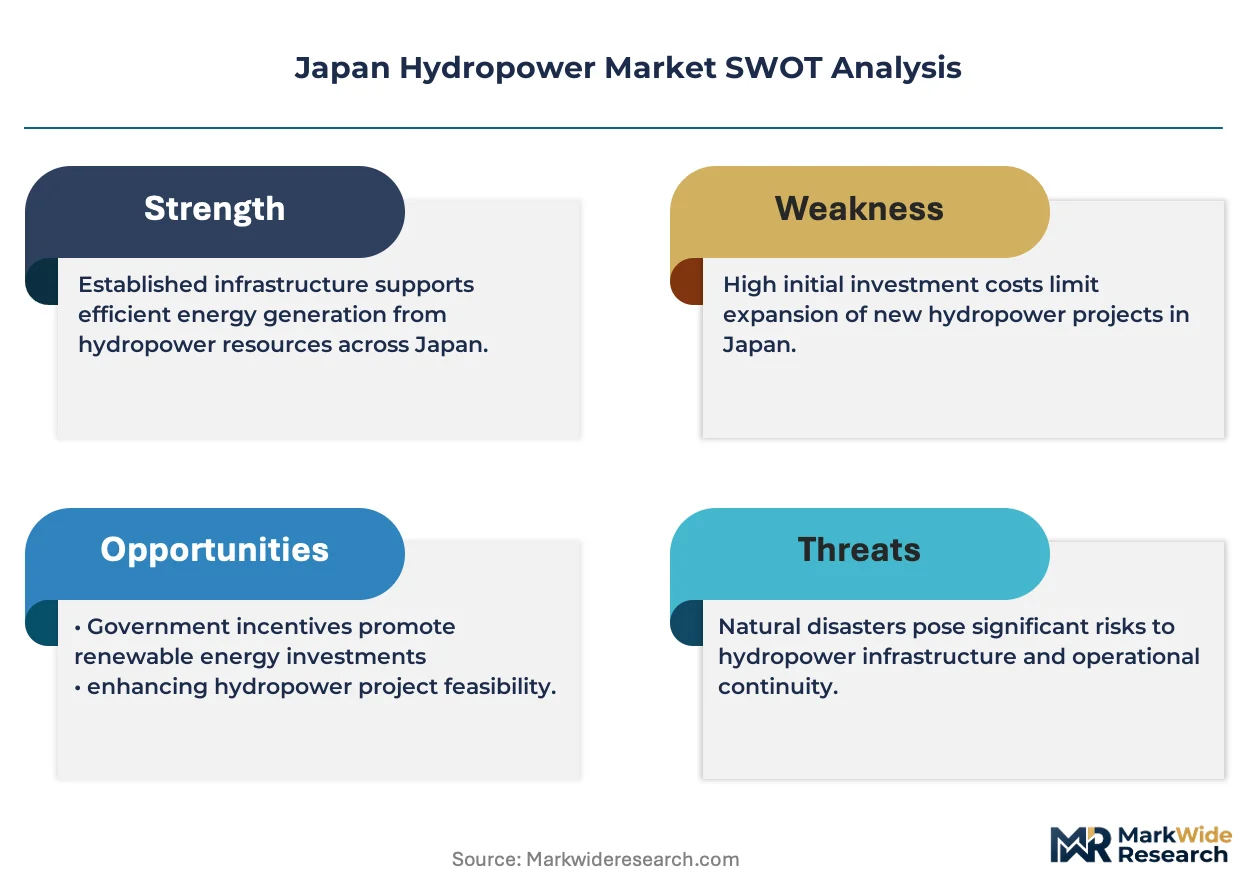
METI's feed-in tariff revisions and grid code updates are compressing development timelines for pumped storage projects while redirecting capital toward retrofit opportunities at aging dam sites across Hokkaido and Tohoku.
Growth Catalysts
- Kyushu solar oversupply:Excess photovoltaic generation is forcing regional utilities to procure frequency-regulating pumped storage capacity. METI's capacity market mechanisms reward fast-ramping hydro assets with multi-year contracts.
- JIS B 8223 certification pathway:Standardized pressure equipment qualification is reducing turbine procurement risk for municipal utilities. Certified domestic suppliers now qualify for streamlined environmental permitting.
- Tohoku earthquake resilience mandates:Prefectural governments are requiring distributed generation assets for critical infrastructure. Small-scale run-of-river installations meet blackout recovery targets for hospitals and emergency services.
Market Restraints
- Steel and copper price volatility:Turbine forgings and generator windings face input cost swings that erode fixed-price EPC contract margins. Domestic foundries pass alloy surcharges through with 90-day lags.
- Single-source dependency for large runners:Cast steel turbine components above 5 meters diameter rely on two domestic forging groups. Equipment buyers face limited negotiation leverage on delivery schedules.
- Environmental flow requirements:River basin committees in Gifu and Nagano prefectures are tightening minimum discharge rules that reduce plant capacity factors at existing run-of-river sites.
Strategic Opportunities
- Hokkaido wind-hydro hybrid sites:Untapped watersheds with existing road access offer co-location potential for wind farms with small pumped storage. METI's renewable energy auctions award grid priority to hybrid configurations.
- Digital twin integration:Convergence of IoT sensors and physics-based simulation is enabling predictive maintenance contracts. Equipment suppliers can capture 15-year service revenue streams alongside turbine sales.
- Direct corporate PPAs:Data center operators in Osaka and Tokyo are contracting directly with hydro generators for 24/7 renewable matching. This bypasses utility intermediaries and commands price premiums.
Industry Challenges
- Welding inspector certification backlog:JIS-qualified pressure vessel welders face 18-month training pipelines. Project delays accumulate when specialized labor cannot be redeployed across concurrent retrofits.
- Legacy control system integration:1980s-era SCADA architectures at J-POWER facilities require custom protocol bridges for modern grid codes. Cybersecurity hardening adds unbudgeted engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Hydropower Market |
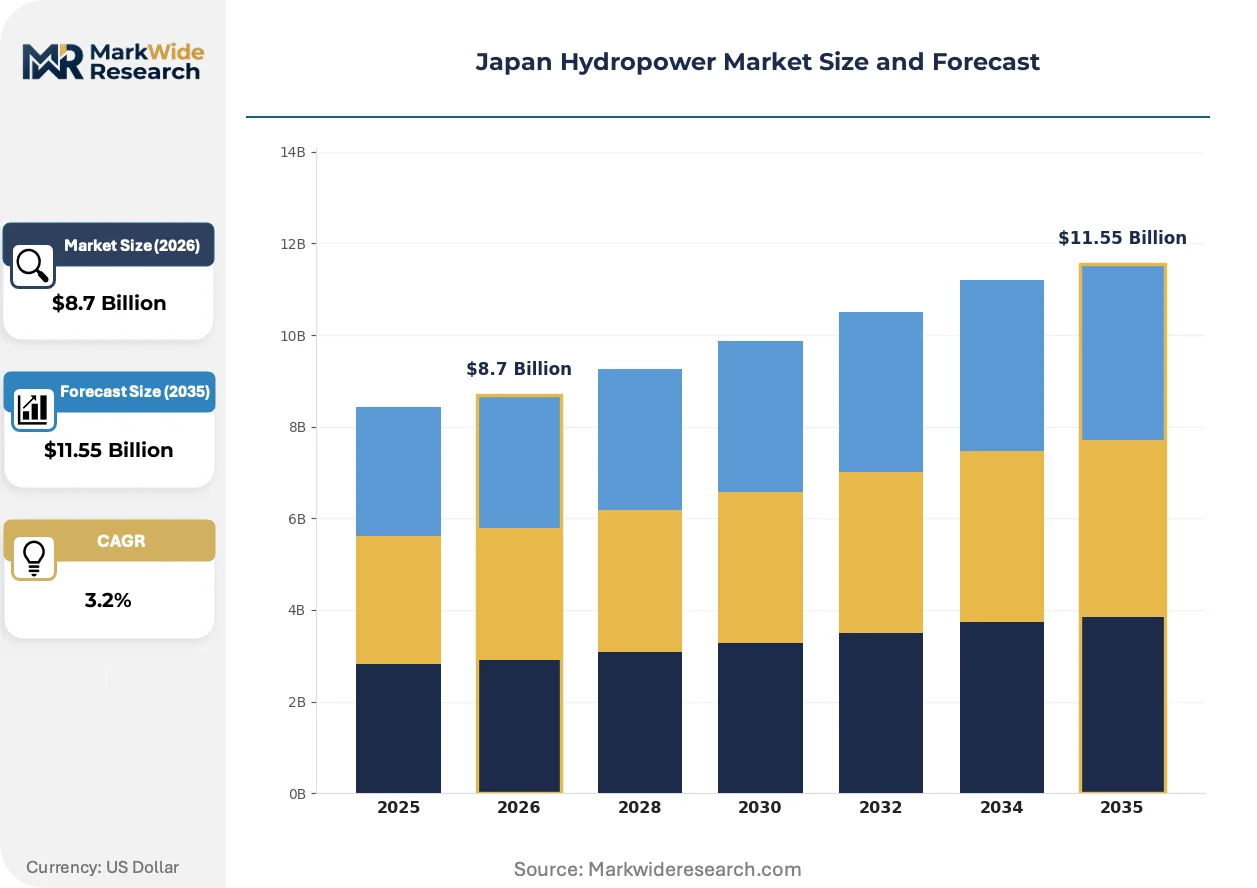
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.55 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Run-of-River, Storage, Pumped Storage, Small Scale End User: Utilities, Independent Power Producers, Industrial Users, Government Technology: Francis Turbine, Kaplan Turbine, Pelton Wheel, Bulb Turbine Market Segment: Residential, Commercial, Industrial, Agricultural |
| Companies Covered | Tohoku Electric Power Co., Inc., Hokkaido Electric Power Co., Inc., J-POWER Group, Toshiba Energy Systems & Solutions Corporation, Hitachi Mitsubishi Hydro Corporation, Tokyo Electric Power Company, Kansai Electric Power Co., Inc., Renewable Japan Co., Ltd., Chubu Electric Power Co., Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Hydropower Market Shifts & Advancements
Digitalization of turbine monitoring and grid-responsive automation are compressing maintenance cycles while enabling new revenue streams from ancillary services. Equipment suppliers are repositioning around software-enabled performance guarantees.
Variable-speed pumped storage technology is displacing fixed-speed units in new-build procurements. Tokyo Electric Power and Chubu Electric are specifying doubly-fed induction machines for their 2024-2028 project pipelines. This technology captures wider head-range efficiency gains and is displacing conventional Francis pump-turbines in competitive tenders.
METI's 5th Strategic Energy Plan introduced carbon intensity benchmarks for grid-connected generation. The regulation forces existing hydro operators to document lifecycle emissions for reservoir methane and construction concrete. Prefectural environmental assessments now require 30-year carbon accounting, affecting redevelopment economics at concrete-gravity dams in Shikoku.
Long-term service agreements are replacing transactional spare parts sales for turbine runners and wicket gates. Kansai Electric and Hokuriku Electric are unbundling maintenance from capital procurement, awarding 10-year performance contracts to OEMs. This shift concentrates risk with equipment suppliers and is most visible in the Kansai region's 2023-2025 rehabilitation wave.
Japan Hydropower Market Segmentation
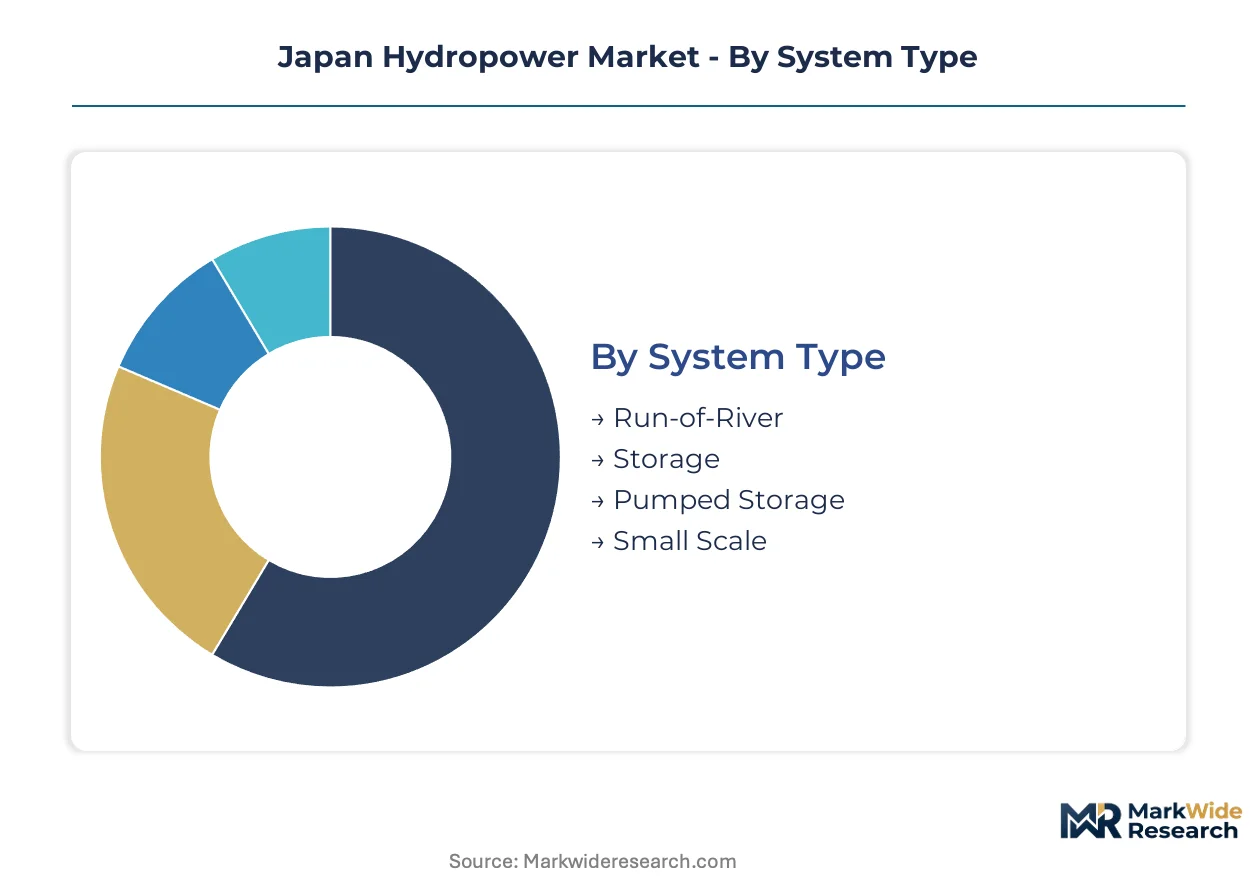
Segmentation in the Japan hydropower market reflects how METI regulations and prefectural permitting create distinct investment profiles across system configurations and customer types. Each segment carries unique JIS certification requirements and grid interconnection standards that determine project economics.
System Type:
METI's capacity market mechanisms and feed-in tariff tiers differentiate capital allocation across system configurations, with pumped storage commanding premium procurement terms for frequency regulation services.
- Pumped Storage:Closed-loop systems with upper and lower reservoirs enable rapid ramping for grid balancing. Tokyo Electric Power and Chubu Electric are expanding procurement in Hokkaido and Tohoku to absorb renewable oversupply from Kyushu solar farms. METI's multi-year ancillary service contracts provide revenue certainty for these capital-intensive installations.
- Run-of-River:Diversion schemes without significant impoundment suit mountainous watersheds in Gifu and Nagano prefectures. Environmental flow requirements from river basin committees are tightening minimum discharge rules, compressing capacity factors at existing facilities.
- Storage:Conventional reservoir plants with seasonal regulation capabilities serve baseload balancing for utilities with limited interregional transmission capacity.
- Small Scale:Sub-megawatt installations qualify for streamlined environmental permitting and municipal procurement programs targeting distributed resilience.
Pumped storage handles the majority of throughput; small scale is gaining share fastest among new permits.
End User:
Customer concentration varies by project scale, with utilities dominating large infrastructure and industrial users emerging for behind-the-meter configurations.
- Utilities:Regional power companies including Tokyo Electric Power, Chubu Electric, and Kansai Electric control grid interconnection capacity and dispatch priority. These entities specify turbine technology and maintenance terms in long-term service agreements.
- Independent Power Producers:Non-utility developers compete for limited grid access in mountainous prefectures with existing dam infrastructure. METI's renewable energy auctions award grid priority to hybrid wind-hydro configurations.
- Industrial Users:Data center operators in Osaka and Tokyo are contracting directly with hydro generators for 24/7 renewable matching, bypassing utility intermediaries.
- Government:Prefectural agencies procure distributed generation for critical infrastructure resilience under Tohoku earthquake recovery mandates.
Utilities retain dominant procurement volume; independent power producers are expanding most quickly in direct corporate PPA structures.
Technology:
Turbine selection depends on head range and operational flexibility requirements, with JIS B 8223 certification filtering supplier qualification.
- Francis Turbine:Reaction turbines with spiral casing configurations dominate medium-head applications from 20 to 500 meters. The technology occupies the broadest application envelope across storage and run-of-river plants in Japan's mountainous terrain.
- Bulb Turbine:Horizontal-axis units suit low-head run-of-river sites with limited civil works space. Hitachi Mitsubishi Hydro Corporation differentiates on retrofit packages for aging diversion schemes.
- Kaplan Turbine:Adjustable-blade propeller designs optimize efficiency across variable flow conditions in river diversion projects.
- Pelton Wheel:Impulse turbines with bucket runners serve high-head applications above 300 meters in steep watersheds.
Francis technology commands the largest installed base; bulb turbine retrofits are climbing fastest on share as low-head sites face redevelopment pressure.
Market Segment:
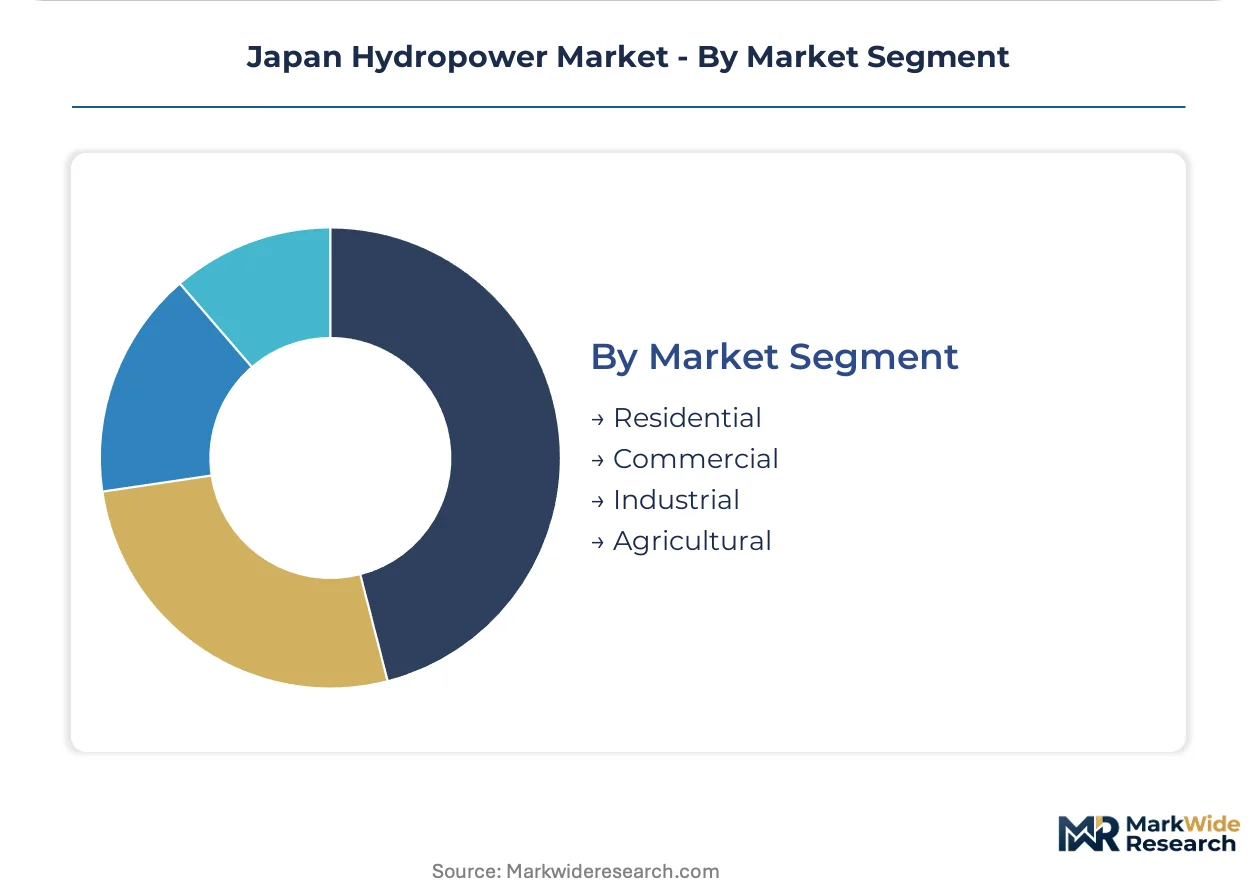
End-use demand concentration tracks industrial load centers and agricultural irrigation patterns across Japan's island geography.
- Industrial:Manufacturing clusters in Osaka and Nagoya require baseload power with frequency stability for precision equipment. Direct corporate PPAs from data center and semiconductor facilities are reshaping procurement channels.
- Commercial:Retail and office loads in Tokyo and Osaka metropolitan areas drive renewable matching requirements for ESG disclosure.
- Residential:Distributed small-scale hydro serves rural communities in Hokkaido and Tohoku with limited grid redundancy.
- Agricultural:Irrigation district cooperatives in Shikoku and Kyushu operate legacy micro-hydro for pumping and processing loads.
Industrial load centers absorb the dominant share of generation capacity; commercial direct contracting is expanding most quickly as corporate renewable targets tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's capacity market mechanisms and feed-in tariff revisions are redistributing hydropower investment toward prefectures with existing dam infrastructure and renewable oversupply absorption needs.
Hokkaido
Municipal utilities in Hokkaido are expanding pumped storage procurement to absorb wind generation oversupply from coastal developments. METI's renewable energy auctions award grid priority to hybrid wind-hydro configurations in this northern island. Sapporo and surrounding watersheds concentrate new small-scale run-of-river permits targeting distributed resilience mandates.
Tohoku
Prefectural governments across Tohoku are requiring distributed generation assets for critical infrastructure under earthquake recovery programs. Small-scale hydro installations meet blackout recovery targets for hospitals and emergency services in Sendai and Fukushima corridors. River basin committees are streamlining environmental permitting for retrofit projects at aging concrete-gravity dams.
Kanto/Tokyo
Data center operators in Tokyo metropolitan areas are contracting directly with hydro generators for 24/7 renewable matching, bypassing utility intermediaries. Tokyo Electric Power specifies variable-speed pumped storage technology in 2024-2028 procurement pipelines. The capital region's limited interregional transmission capacity reinforces demand for fast-ramping frequency regulation assets.
Kansai/Osaka
Kansai Electric and regional utilities are unbundling maintenance from capital procurement, awarding 10-year performance contracts to OEMs. Osaka's manufacturing clusters require baseload power with frequency stability for precision semiconductor equipment. The 2023-2025 rehabilitation wave concentrates in this western region's legacy Francis turbine installations.
Kyushu
Excess photovoltaic generation from Kyushu solar farms is forcing regional utilities to procure frequency-regulating pumped storage capacity. METI's multi-year ancillary service contracts provide revenue certainty for capital-intensive installations absorbing this oversupply. Fukuoka and surrounding prefectures face grid congestion that elevates the value of rapid-ramp hydro assets.
Japan Hydropower Market Competitive Landscape
Player mix skews toward integrated regional utilities with captive generation portfolios and specialized turbine manufacturers with JIS-certified forging capabilities. The competitive structure concentrates around entities controlling grid interconnection capacity and dispatch priority. Two strategic archetypes dominate: utility-affiliated equipment suppliers leveraging domestic foundry networks, and independent power producers securing limited grid access through hybrid renewable configurations. Competitive moves center on long-term service agreement unbundling and digital twin integration for predictive maintenance revenue capture.
Among utility-affiliated operators, Tokyo Electric Power Company, Kansai Electric Power Co., Inc., and Chubu Electric Power Co., Inc. represent the integrated generation-and-distribution archetype that controls interconnection capacity and dispatch sequencing. Within the specialized equipment tier, Toshiba Energy Systems & Solutions Corporation and Hitachi Mitsubishi Hydro Corporation occupy positions defined by JIS B 8223 certification pathways and domestic turbine foundry access. J-POWER Group exemplifies the independent power producer model with operational concentration across multiple river basins. These named entities serve as anchors for understanding how METI regulations and prefectural permitting filter market participation.
| Leading Market Players |
|---|
| Tohoku Electric Power Co., Inc. |
| Hokkaido Electric Power Co., Inc. |
| J-POWER Group |
| Toshiba Energy Systems & Solutions Corporation |
| Hitachi Mitsubishi Hydro Corporation |
| Tokyo Electric Power Company |
| Kansai Electric Power Co., Inc. |
| Renewable Japan Co., Ltd. |
| Chubu Electric Power Co., Inc. |
| Others |
Supply & Pricing Matrix
Long-term service agreements with unbundled maintenance terms lock in turbine OEM revenue visibility while insulating municipal utilities from steel and copper alloy surcharge volatility. METI's multi-year ancillary service contracts for pumped storage operators create parallel price predictability for frequency-regulation capacity.
Pricing Analysis
Certification level under JIS B 8223 creates the primary spread between premium domestic forgings and standard-tier imported pressure equipment. Three-tier pricing structure across JIS-certified premium, domestically-sourced standard, and economy-grade imported tiers stratifies procurement pools. Cost compression in the standard tier is intensifying as steel alloy surcharges transmit with 90-day lags from domestic foundries. Municipal utilities exhibit highest price sensitivity; Tokyo Electric Power and Chubu Electric demonstrate lowest sensitivity due to captive grid interconnection capacity.
Supply Chain Analysis
Japan anchors precision turbine forging for large-diameter runners above 5 meters, while South Korea and Germany supply specialized generator windings and control system components. Domestic supply draws from cast steel forgings, copper alloy windings, and custom SCADA architectures. Single-source vulnerability concentrates in the two domestic forging groups capable of 5-meter-plus turbine runners. Distribution runs through utility-affiliated EPC contractors with JIS-certified welding inspector networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin-enabled predictive maintenance contracts are expanding faster than hardware sales, converting one-time turbine transactions into 15-year recurring service revenue streams for equipment suppliers.
For Market Incumbents: Compound defensive positioning by deepening backward integration into captive forging capacity and securing JIS B 8223 certification pathways for municipal utility procurement pools. Variable-speed pumped storage technology from emerging entrants threatens fixed-speed unit margins; reinforce grid-code compliance capabilities as the primary lever against substitution. For New Entrants and Emerging Players: Lead with bulb turbine retrofit packages for low-head run-of-river sites in Gifu and Nagano prefectures, where environmental flow requirements have compressed capacity factors at aging facilities. Hokkaido wind-hydro hybrid configurations offer the most penetrable white space under METI's renewable energy auction grid priority rules. Pursue direct corporate PPA channels with Osaka data center operators bypassing utility intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among turbine OEMs with unbundled 10-year performance contracts in the Kansai rehabilitation wave. Long-term viability over the 5-10 year window favors entities controlling JIS-certified domestic foundry networks. Watch for inflection when prefectural river basin committees accelerate dam safety re-certification schedules forcing redevelopment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Agreement Unbundling | Kansai Electric's 10-year performance contracts concentrate risk with OEMs and shift revenue from transactional parts to predictive maintenance. |
| Variable-Speed Pumped Storage Buildout | Tokyo Electric Power and Chubu Electric specifications for doubly-fed induction machines capture wider head-range efficiency gains. |
| Digital Twin Integration | IoT sensor convergence with physics-based simulation enables 15-year predictive maintenance contracts alongside turbine sales. |
| JIS B 8223 Certification Investment | Standardized pressure equipment qualification reduces procurement risk and streamlines environmental permitting for certified suppliers. |
| Direct Corporate PPA Structuring | Data center operators in Osaka and Tokyo contract directly with hydro generators for 24/7 renewable matching at price premiums. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration across primary fieldwork. Secondary validation drew from METI Strategic Energy Plan filings, Agency for Natural Resources and Energy capacity databases, prefectural river basin committee records, and JIS standards documentation. Bottom-up project pipelines were triangulated against top-down regulatory capacity targets.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include system type, end user archetype, turbine technology, and regional prefectural cluster. CAGRs were derived from installed capacity trajectories, feed-in tariff revision impacts, and METI auction award patterns. Forecast inputs incorporated steel and copper price volatility assumptions and environmental flow requirement tightening schedules.
The analysis sits within stated boundaries; outcomes outside METI regulatory continuity or sustained renewable oversupply conditions would require recalibration. Forecasts reflect documented assumptions about prefectural permitting timelines and foundry capacity expansion. Recalibration cycles align with material shifts in feed-in tariff tiers and river basin committee discharge rule revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Standard Modular Hydropower Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
Run of River Power Market
Hydropower Systems
Europe Hydro Turbine Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Wave and Tidal Energy Market
Hydropower Systems
France Tidal Power Market