
 South Africa Distributed Solar Energy Market | 2026-2036
South Africa Distributed Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Distributed Solar Energy Market Analytics
Grid-tied commercial-grade system specifications is redrawing competitive boundaries in the South Africa distributed solar sector. JA Solar Holdings leverages vertical integration across cell manufacturing to sustain cost competitiveness in utility-scale module supply. Scatec Solar Africa anchors its position through end-to-end project development across Southern African markets. BrightBlack Energy differentiates via specialized financing structures targeting underserved commercial segments.
Distributed solar energy encompasses decentralized photovoltaic generation systems typically rated below 1 MW, installed at or near consumption points with grid-interactive inverters synchronizing at 50 Hz to national standards. These systems convert irradiance through monocrystalline or polycrystalline silicon cells into alternating current for direct building load offset or net-metered export. Photovoltaic technology dominates installed capacity given modularity and declining module costs, while energy storage integration represents the fastest-expanding margin pool as lithium-ion battery pairing addresses load-shedding resilience needs. Rooftop installation leads deployment volumes across residential and commercial end users, though ground-mounted arrays capture industrial agricultural loads where land availability permits optimal tilt angles.
South Africa's National Energy Regulator governs licensing thresholds and grid connection codes under the Electricity Regulation Act, while the South African Bureau of Standards enforces SANS photovoltaic system safety and performance certifications. The Department of Mineral Resources and Energy administers the Renewable Energy Independent Power Producer Procurement Programme, which sets procurement quotas directly influencing distributed project pipelines. Stakeholders must monitor embedded generation tariff revisions and municipal net metering framework implementations that will determine payback periods for commercial investors.
Market Dynamics
Eskom's load-shedding crisis has collapsed the payback period calculus for commercial solar buyers, converting energy security from a secondary benefit into the primary procurement driver across Gauteng industrial corridors.
Growth Catalysts
- REIPPPP Embedded Generation Reforms:The Department of Mineral Resources and Energy raised licensing thresholds for distributed projects, eliminating bureaucratic bottlenecks that previously stalled sub-10 MW commercial installations.
- Johannesburg-Pretoria Industrial Load Concentration:Manufacturing clusters in Gauteng province face 200+ annual outage hours, forcing facility managers to treat solar-plus-storage as operational infrastructure rather than sustainability optics.
- Lithium-Ion Battery Cost Compression:Cell price declines are pairing photovoltaic arrays with four-hour storage configurations, enabling commercial offtakers to ride through Stage 6 load-shedding without diesel generator fallback.
Market Restraints
- Module Import Tariff Volatility:South African Revenue Service anti-dumping duties on Chinese crystalline silicon panels create 15-25% input cost swings that distort project finance assumptions.
- Transformer and Inverter Supply Bottlenecks:Grid-interactive hardware concentrates through a handful of European and East Asian suppliers, exposing procurement timelines to six-month lead time extensions.
- Municipal Net Metering Fragmentation:City of Johannesburg, Cape Town, and eThekwini operate incompatible billing frameworks, preventing standardized commercial rollout across provincial boundaries.
Strategic Opportunities
- Eastern Cape Agricultural Ground-Mount Deployment:Citrus and wine estates in Sundays River Valley and Stellenbosch corridors hold unexploited land banks with irradiance profiles matching Gauteng commercial returns.
- Section 12B Tax Acceleration:National Treasury depreciation allowances permit 100% first-year write-offs for renewable energy assets below 1 MW, compressing investor hurdle rates for distributed portfolios.
- Virtual Wheeling Framework Activation:NERSA-approved peer-to-peer energy trading protocols allow commercial landlords to monetize rooftop surplus across tenant portfolios without physical grid reconfiguration.
Industry Challenges
- SANS Certification Backlogs:South African Bureau of Standards photovoltaic safety testing queues extend 14-18 weeks, delaying commercial commissioning and triggering liquidated damages clauses in engineering contracts.
- Electrical Engineering Skill Scarcity:Grid code compliance specialists with NERSA registration credentials command 40% wage premiums, constraining installer scaling across the Cape Winelands and KwaZulu-Natal industrial zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Distributed Solar Energy Market |
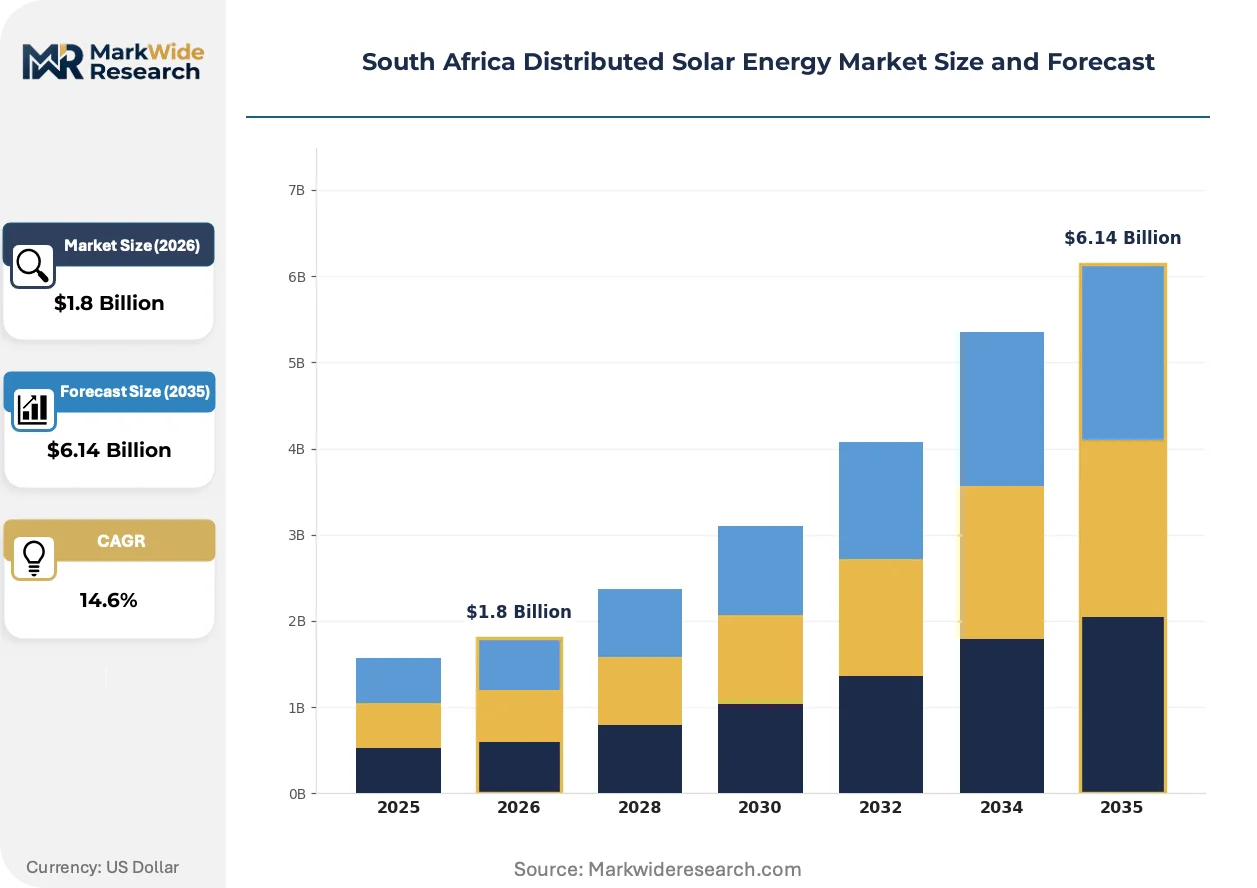
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, Hybrid Systems, Energy Storage Product Type: Solar Panels, Inverters, Monitoring Systems, Mounting Structures End User: Residential, Commercial, Industrial, Agricultural Installation Type: Rooftop, Ground-mounted, Floating, Community-based |
| Companies Covered | Asunim Solar South Africa (Pty) Ltd, PiA Solar SA (Pty) Ltd, JA Solar Holdings, BrightBlack Energy, Solareff (Pty) Ltd, GENERGY, Solar Energy Group (Pty) Ltd, Scatec Solar Africa, Valsa Trading (Pty) Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Distributed Solar Energy Market Evolving Landscape
Module-level power electronics and containerized battery integration are collapsing the distinction between residential and commercial system architectures, enabling product platforms that scale across kilowatt and megawatt deployments without redesign.
Bifacial monocrystalline modules with half-cut cell architectures are fragmenting the historical premium-utility segmentation that separated rooftop commercial from ground-mount utility procurement. Warehouse operators in Midrand and Port Elizabeth logistics parks are specifying these configurations for flat-roof east-west arrays where albedo reflection boosts yield 8-12% over monofacial equivalents. The technology is fragmenting installer specialization, as residential contractors now bid commercial-scale projects without dedicated utility-scale engineering teams.
NERSA's 2023 licensing threshold revision and pending municipal net metering regulations are compressing regulatory arbitrage opportunities that previously favored specific provinces. The Department of Mineral Resources and Energy's embedded generation rules now permit commercial offtakers to wheel excess generation across municipal boundaries, triggering Cape Town-based financiers to underwrite projects in Nelson Mandela Bay. Industrial buyers in the automotive supply chain are restructuring power purchase agreements to capture these geographic flexibilities.
Aggregators are consolidating fragmented commercial rooftop portfolios into single offtake structures that qualify for institutional capital deployment. Property funds in Sandton and Umhlanga are bundling multi-tenant installations into standardized special purpose vehicles, displacing the bilateral landlord-tenant solar lease model that dominated 2018-2022 procurement. This bundling is most advanced in the logistics and cold storage verticals, where predictable baseload profiles attract pension fund allocation.
South Africa Distributed Solar Energy Market Segmentation
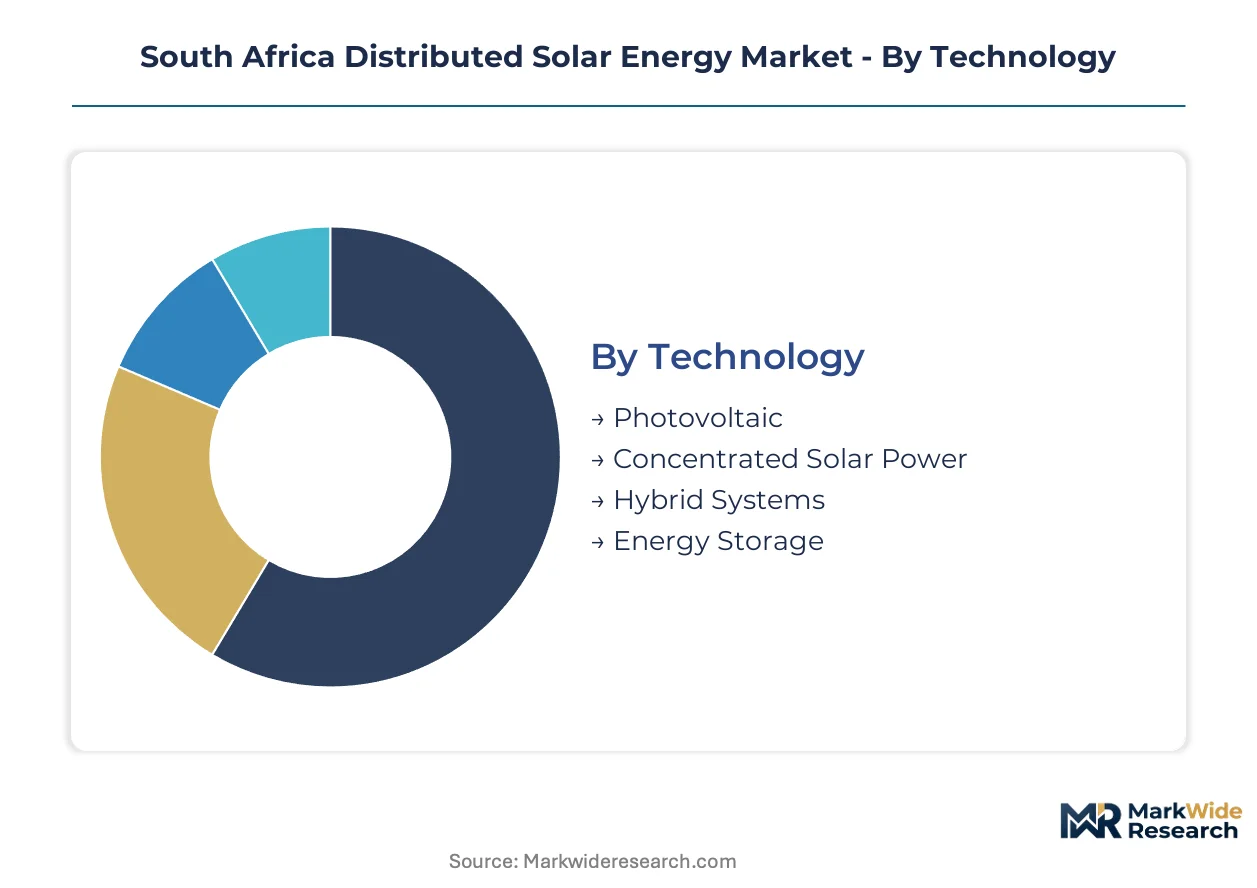
Segmentation in South Africa's distributed solar market reveals how load-shedding resilience demands reshape procurement patterns across technology tiers and installation configurations. Distinct margin pools emerge in storage-integrated systems versus standalone photovoltaic deployments, with regulatory thresholds further fragmenting addressable customer profiles.
Technology:
Margin concentration tracks directly to system complexity and grid-interactive capabilities, with hybrid configurations commanding premium pricing over single-technology deployments.
- Photovoltaic:Monocrystalline and polycrystalline silicon cells convert irradiance through modular arrays rated below 1 MW, dominating Gauteng industrial corridor deployments where manufacturing clusters prioritize rapid commissioning over storage integration. Midrand warehouse operators specify these systems for flat-roof east-west configurations where albedo reflection boosts yield.
- Energy Storage:Lithium-ion battery pairing with four-hour duration configurations enables commercial offtakers to ride through Stage 6 load-shedding without diesel fallback, capturing the steepest expansion trajectory as cell price declines compress payback periods across Johannesburg-Pretoria logistics parks.
- Hybrid Systems:Combined photovoltaic and storage architectures with integrated inverters address municipal net metering fragmentation.
- Concentrated Solar Power:Parabolic trough and tower configurations with thermal storage suit agricultural processing loads in Sundays River Valley citrus estates.
Photovoltaic holds installed capacity. Energy Storage is rotating up the share rankings.
Product Type:
Supply bottlenecks in grid-interactive hardware reshape competitive boundaries between integrated system providers and component specialists.
- Solar Panels:Bifacial monocrystalline modules with half-cut cell architectures fragment historical premium-utility segmentation, enabling Port Elizabeth logistics contractors to bid commercial-scale projects without dedicated utility-scale engineering teams. Anti-dumping duties on Chinese crystalline silicon panels create 15-25% input cost swings.
- Inverters:Grid-interactive hardware synchronizing at 50 Hz to national standards concentrates through European and East Asian suppliers, exposing procurement timelines to six-month lead time extensions that trigger liquidated damages clauses in engineering contracts.
- Mounting Structures:Fixed-tilt and tracking systems for rooftop and ground-mount configurations.
- Monitoring Systems:Module-level power electronics with remote diagnostics capabilities.
Solar Panels anchor procurement volumes. Inverters are climbing the fastest as supply constraints elevate strategic importance.
End User:
Customer type determines financing structure sophistication, with commercial property funds pioneering aggregated portfolio approaches unavailable to residential segments.
- Commercial:Multi-tenant installations in Sandton and Umhlanga property funds bundle fragmented rooftop portfolios into standardized special purpose vehicles, displacing bilateral landlord-tenant solar lease models through institutional capital deployment. Section 12B tax acceleration permits 100% first-year write-offs for assets below 1 MW.
- Industrial:Automotive supply chain buyers in Gauteng province restructure power purchase agreements to capture NERSA-approved virtual wheeling flexibilities across municipal boundaries.
- Agricultural:Citrus and wine estates in Stellenbosch corridors exploit unexploited land banks with irradiance profiles matching commercial returns.
- Residential:Single-family rooftop installations concentrated in Cape Town and eThekwini municipal boundaries.
Commercial holds installed capacity. Industrial is rotating up the share rankings.
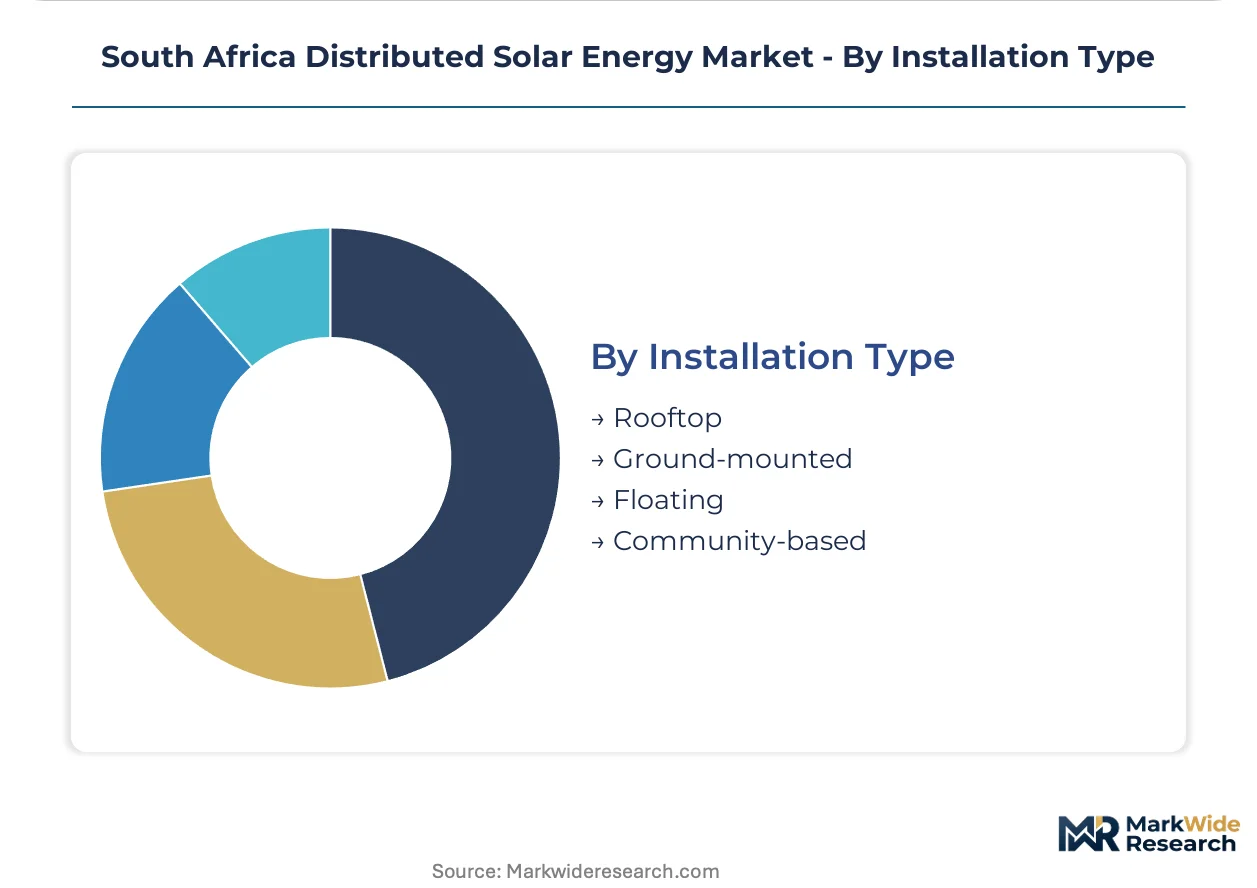
Installation Type:
Site constraints and land availability dictate optimal tilt angles and system sizing, with rooftop deployment leading volumes despite ground-mount yield advantages.
- Rooftop:Flat-roof east-west arrays on Midrand and Port Elizabeth logistics facilities deploy bifacial configurations where albedo reflection boosts yield 8-12% over monofacial equivalents, fragmenting installer specialization as residential contractors scale into commercial bids.
- Ground-mounted:Eastern Cape agricultural estates in Sundays River Valley hold unexploited land banks permitting optimal tilt angles where irradiance profiles match Gauteng commercial returns.
- Community-based:Shared solar arrays with multiple offtakers under standardized billing frameworks.
- Floating:Reservoir and dam-mounted photovoltaic systems for water treatment facilities.
Rooftop holds installed capacity. Ground-mounted is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's distributed solar sector exhibits pronounced internal trade flows, with Gauteng province importing installation capacity from Western Cape engineering clusters while Eastern Cape agricultural estates supply land-backed generation assets to national offtakers.
Gauteng Province
Johannesburg-Pretoria industrial corridors anchor procurement volumes as manufacturing clusters face 200+ annual outage hours. The Department of Mineral Resources and Energy's embedded generation rules permit commercial offtakers to wheel excess generation across municipal boundaries. Midrand warehouse operators deploy bifacial configurations for flat-roof east-west arrays where albedo reflection boosts yield.
Western Cape
Cape Town-based financiers underwrite projects in Nelson Mandela Bay following NERSA's 2023 licensing threshold revision. The City of Cape Town operates distinct net metering frameworks incompatible with Johannesburg and eThekwini systems. Stellenbosch wine estates exploit unexploited land banks with irradiance profiles matching commercial returns in agricultural ground-mount deployments.
KwaZulu-Natal
eThekwini municipality's billing framework fragments standardization attempts across provincial boundaries. Electrical engineering skill scarcity concentrates grid code compliance specialists with NERSA registration credentials. Umhlanga property funds bundle multi-tenant installations into standardized special purpose vehicles for institutional capital deployment.
Eastern Cape
Sundays River Valley citrus estates hold unexploited land banks permitting optimal tilt angles where irradiance profiles match Gauteng commercial returns. The South African Bureau of Standards enforces SANS photovoltaic system safety certifications with testing queues extending 14-18 weeks. Port Elizabeth logistics parks specify bifacial monocrystalline modules for commercial-scale projects.
South Africa Distributed Solar Energy Market Competitive Landscape
Concentration sits with vertically integrated module manufacturers and end-to-end project developers who control procurement timelines against inverter supply bottlenecks. The vendor base spans Chinese cell producers, regional EPC contractors, and specialized financiers targeting underserved segments. Three archetypes dominate: manufacturing-integrated suppliers, development-anchored integrators, and financing-focused aggregators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure transformer and hardware allocations.
Among manufacturing-integrated players, JA Solar Holdings exemplifies cost competitiveness through captive cell production. Scatec Solar Africa occupies a position as a development-anchored integrator with Southern African market coverage. BrightBlack Energy represents the financing-focused archetype, targeting commercial segments with specialized capital structures. These three firms anchor the competitive structure while regional contractors like Solareff and PiA Solar SA compete on installation velocity and local regulatory navigation.
| Leading Market Players |
|---|
| Asunim Solar South Africa (Pty) Ltd |
| PiA Solar SA (Pty) Ltd |
| JA Solar Holdings |
| BrightBlack Energy |
| Solareff (Pty) Ltd |
| GENERGY |
| Solar Energy Group (Pty) Ltd |
| Scatec Solar Africa |
| Valsa Trading (Pty) Ltd |
| Others |
Value Network & Pricing Analysis
Lithium-ion battery substitution for diesel backup generators redraws procurement geography across Gauteng industrial corridors while compressing lifecycle cost economics for commercial offtakers. This technology displacement simultaneously elevates Chinese cell manufacturers to price-setting positions and exposes South African installers to currency-denominated input volatility.
Pricing Analysis
Industrial OEM buyers anchor project-based contract pricing across Johannesburg-Pretoria logistics parks, with three-tier pricing structure across premium, standard, and economy levels determined by NERSA registration status and SANS certification tier. Price differentiation tracks inverter sourcing geography and installation warranty duration. Cost compression in standard-tier systems intensifies as residential contractors scale into commercial bids without dedicated utility-scale engineering teams. Municipal net metering fragmentation renders Cape Town-based buyers least price-sensitive due to wheeling flexibility premiums.
Supply Chain Analysis
China and Vietnam anchor crystalline silicon module fabrication, while South Korea and Japan concentrate lithium-ion cell production for storage-integrated deployments. South African EPC contractors draw from East Asian inverter suppliers and European transformer manufacturers, creating six-month procurement lead time exposure. Single-source vulnerability concentrates in grid-interactive hardware where NERSA registration requirements limit substitute sourcing. Distribution runs through regional contractor networks with direct-to-installer relationships displacing traditional wholesaler intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects through virtual wheeling frameworks that transform rooftop generation into tradable network assets, with NERSA-approved peer-to-peer protocols enabling interoperability between previously siloed municipal jurisdictions.
For Market Incumbents: Fortify captive inverter allocation agreements with East Asian suppliers to defend commissioning timelines against transformer supply bottlenecks. Deepen backward integration into mounting structure fabrication to offset anti-dumping duty exposure on Chinese crystalline silicon panels. Prioritize SANS certification pre-approval investments to compress 14-18 week testing queues that trigger liquidated damages clauses. For New Entrants and Emerging Players: Specialized financing structures for multi-tenant commercial portfolios represent the most penetrable service-layer gap, with Sandton and Umhlanga property funds seeking aggregated special purpose vehicle structures that displace bilateral landlord-tenant solar lease models. Eastern Cape agricultural ground-mount deployments offer geographic white-space with Sundays River Valley citrus estates holding unexploited land banks. Pursue Section 12B tax acceleration advisory capabilities as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed EPC contractors who aggregated commercial rooftop portfolios during 2018-2022 bilateral lease dominance. Long-term viability centers on virtual wheeling framework participation rights and NERSA licensing credential portability across municipal boundaries. Watch for embedded generation tariff revisions as inflection indicators that would re-rate distributed project hurdle rates.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Restructuring | Captures NERSA virtual wheeling flexibilities across Johannesburg-Pretoria municipal boundaries. |
| Backward Integration into Mounting Systems | Offsets South African Revenue Service anti-dumping duty exposure on imported hardware. |
| Section 12B Tax Structuring Capability | Compresses investor hurdle rates through National Treasury 100% first-year depreciation allowances. |
| SANS Certification Pre-Investment | Eliminates 14-18 week South African Bureau of Standards testing queue delays. |
| Virtual Wheeling Platform Activation | Monetizes rooftop surplus across tenant portfolios without physical grid reconfiguration. |
Research Methodology
The analysis maps photovoltaic, energy storage, hybrid system, and concentrated solar power sub-sectors, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators across primary interviews with secondary triangulation against IEA reports, EIA data, project development databases, and NERSA regulatory filings. Bottom-up installation volume estimates reconcile with top-down procurement pipeline assessments across Gauteng, Western Cape, KwaZulu-Natal, and Eastern Cape provinces.
Consistency checks validated volume and value outputs against external benchmarks throughout the projection horizon across technology, product type, end user, and installation type segmentation dimensions. CAGRs derived from installed capacity build-up modeling incorporate lithium-ion battery cost compression curves, municipal net metering framework adoption rates, and REIPPPP embedded generation threshold revisions as industry-specific forecast inputs.
Forecasts assume regulatory continuity in NERSA licensing regimes and National Treasury depreciation allowances; material policy shifts in municipal net metering frameworks or anti-dumping duty schedules would require re-modeling. Specific risks include Eskom load-shedding intensity variation, SANS certification queue extensions, and transformer supply lead time volatility. Recalibration cycles align with material shifts in REIPPPP procurement quotas and embedded generation tariff structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Brazil Renewable Energy Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
Belarus Renewable Energy Market
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
South Africa Wind Energy Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Hybrid Solar Wind System Market
Renewable Energy
Netherlands Renewable Energy Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
Wind Turbine Inspection Services Market