
 China Solar Energy Market | 2026-2036
China Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
China Solar Energy Market Outlook
The China solar energy sector is pivoting between premium N-type monocrystalline output and commodity-grade P-type capacity as cell efficiency benchmarks diverge. LONGi Solar leverages vertical integration from wafer to module to sustain margin capture across the technology transition. JinkoSolar anchors its position through differentiated TOPCon cell architectures. JA Solar competes on manufacturing scale in Jiangsu and Anhui production corridors.
China solar energy encompasses photovoltaic power generation systems that convert sunlight into electricity through semiconductor junctions, with monocrystalline silicon cells achieving conversion efficiencies above 24% in mass production. The technology serves grid-connected electricity supply, distributed commercial rooftop installations, and off-grid rural electrification across China's western territories. Photovoltaic cells and solar panels dominate installed value, though inverters represent a concentrated margin pool given power electronics complexity and replacement cycles. Bifacial technology adoption is accelerating fastest among utility end users seeking enhanced energy yield from albedo reflection. Grid-tied installations occupy the structural majority of capacity additions, while hybrid systems gain traction in commercial segments seeking resilience against curtailment risk.
MIIT governs solar manufacturing standards through GB certification requirements and industrial policy directives, while NEEA administers renewable energy quota obligations that compel provincial grid operators to prioritize solar dispatch. The National Development and Reform Commission shapes project economics through benchmark tariff benchmarks and cross-provincial power trading mechanisms. Stakeholders must monitor how China's dual carbon goals translate into annual installation targets and polysilicon capacity allocation policies.
Market Dynamics
The migration from P-type to N-type monocrystalline cell architectures is compressing manufacturing margins and forcing capacity retooling across the sector. This technology transition intersects with MIIT's GB certification requirements and provincial grid parity mandates to reshape competitive economics.
Growth Catalysts
- Dual Carbon Goals:China's national carbon neutrality targets compel provincial grid operators under NEEA renewable energy quotas to accelerate solar dispatch prioritization across western provinces.
- Grid Parity Economics:Benchmark tariff elimination in Xinjiang and Inner Mongolia eliminates subsidy dependence and attracts independent power producer investment into gigawatt-scale clusters.
- TOPCon Cell Migration:Tunnel oxide passivated contact architectures are displacing PERC dominance as mass production efficiency thresholds exceed 24.5% conversion rates.
Market Restraints
- Polysilicon Input Volatility:Metallurgical-grade silicon price swings and Xinjiang polysilicon concentration create margin squeeze risks for wafer producers without captive supply.
- Interconnection Queue Congestion:State Grid Corporation transmission bottlenecks in Qinghai and Gansu delay project commissioning and extend capital recovery timelines.
- Land Use Competition:Agricultural land classification restrictions under Ministry of Natural Resources guidelines limit available acreage for utility-scale deployment in eastern provinces.
Strategic Opportunities
- Agrivoltaic Integration:Dual-use solar installations combining photovoltaic generation with crop cultivation open deployment pathways in Shandong and Henan where flat agricultural land dominates.
- Cross-Provincial Power Trading:NDRC market liberalization mechanisms enable western generation assets to access higher-priced eastern demand centers through long-distance transmission contracts.
- Bifacial-Plus-Tracking Systems:Albedo capture technology convergence with single-axis trackers is expanding addressable market for high-irradiance desert applications in Ningxia.
Industry Challenges
- Cell Process Engineering Talent:Scarcity of specialists in TOPCon and heterojunction manufacturing processes constrains yield ramp rates at new production facilities.
- Module Recycling Infrastructure:End-of-life photovoltaic panel collection and semiconductor recovery capabilities remain underdeveloped relative to installed base growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Solar Energy Market |
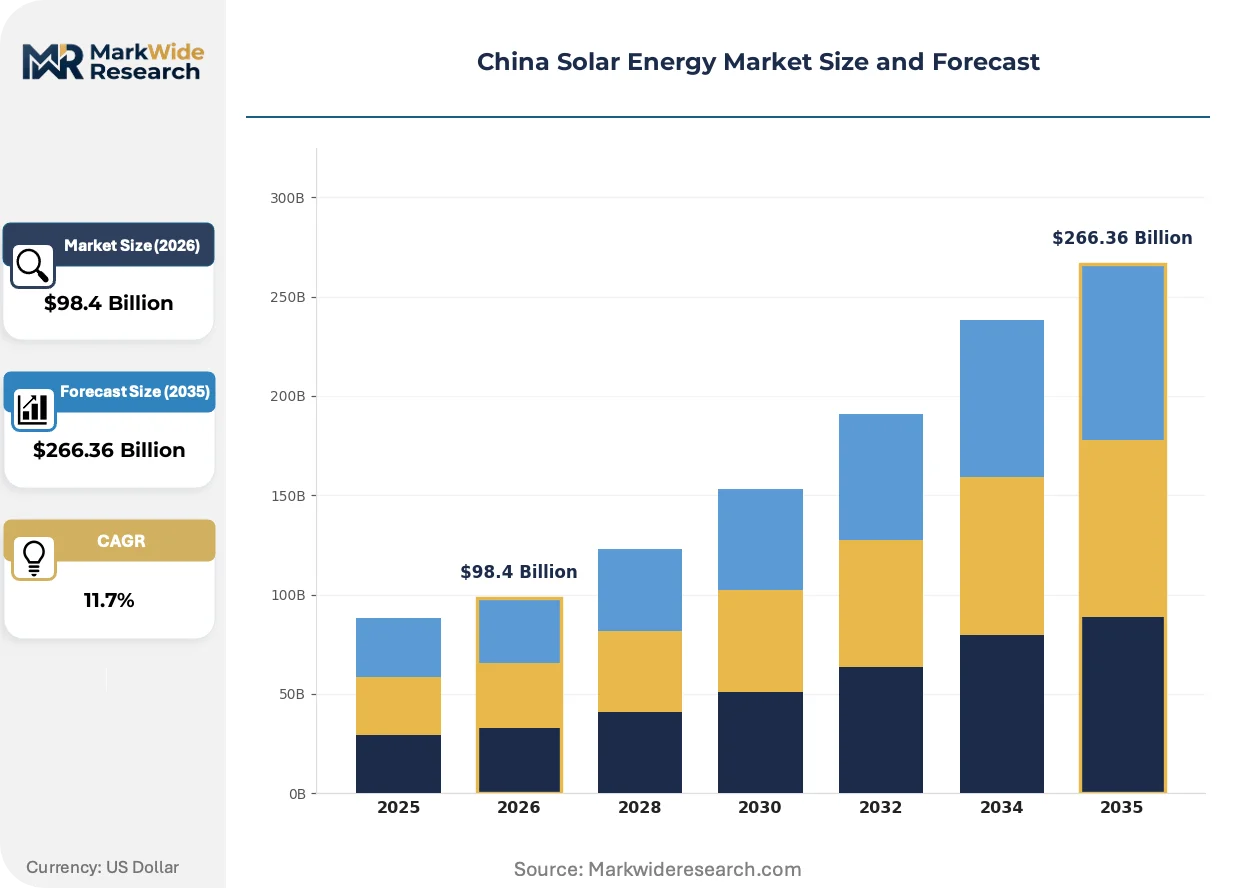
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $266.36 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Cells, Solar Panels, Inverters, Mounting Systems Installation Type: Grid-Tied, Off-Grid, Hybrid, Rooftop End User: Residential, Commercial, Industrial, Utility Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial |
| Companies Covered | LONGi Solar, Xinyi Solar Holdings Ltd, JinkoSolar Holding Co., Ltd., JA Solar, Chint New Energy, Trina Solar Co. Ltd, Shanghai Aiko Solar Energy Co. Ltd, GCL-SI, Tongwei Solar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Solar Energy Market Strategic Shifts
Intelligent manufacturing systems are penetrating cell and module production lines, compressing defect rates and accelerating throughput. Automation convergence with quality analytics is redefining operational benchmarks across the value chain.
PERC cell technology is automating defect detection and process optimization through machine vision integration at diffusion and passivation stages. Tier-one manufacturers deploy these systems to sustain yield rates above 98% during the technology transition. The automation of inline metrology is compressing feedback loops from hours to minutes, enabling real-time parameter adjustment.
MIIT's updated GB/T standards for photovoltaic module reliability are mandating enhanced testing protocols for potential-induced degradation and thermal cycling resistance. These requirements are forcing module producers to reformulate encapsulant materials and junction box designs. The regulatory pressure concentrates most acutely on distributed rooftop segments where installation density amplifies failure risk.
Power purchase agreement structures are fragmenting procurement patterns across the utility sector. State-owned generation groups are unbundling engineering-procurement-construction contracts from long-term operations and maintenance agreements, creating specialized vendor tiers. This behavioral shift is most visible in Inner Mongolia where project scale attracts independent asset managers seeking operational control separation.
China Solar Energy Market Segmentation
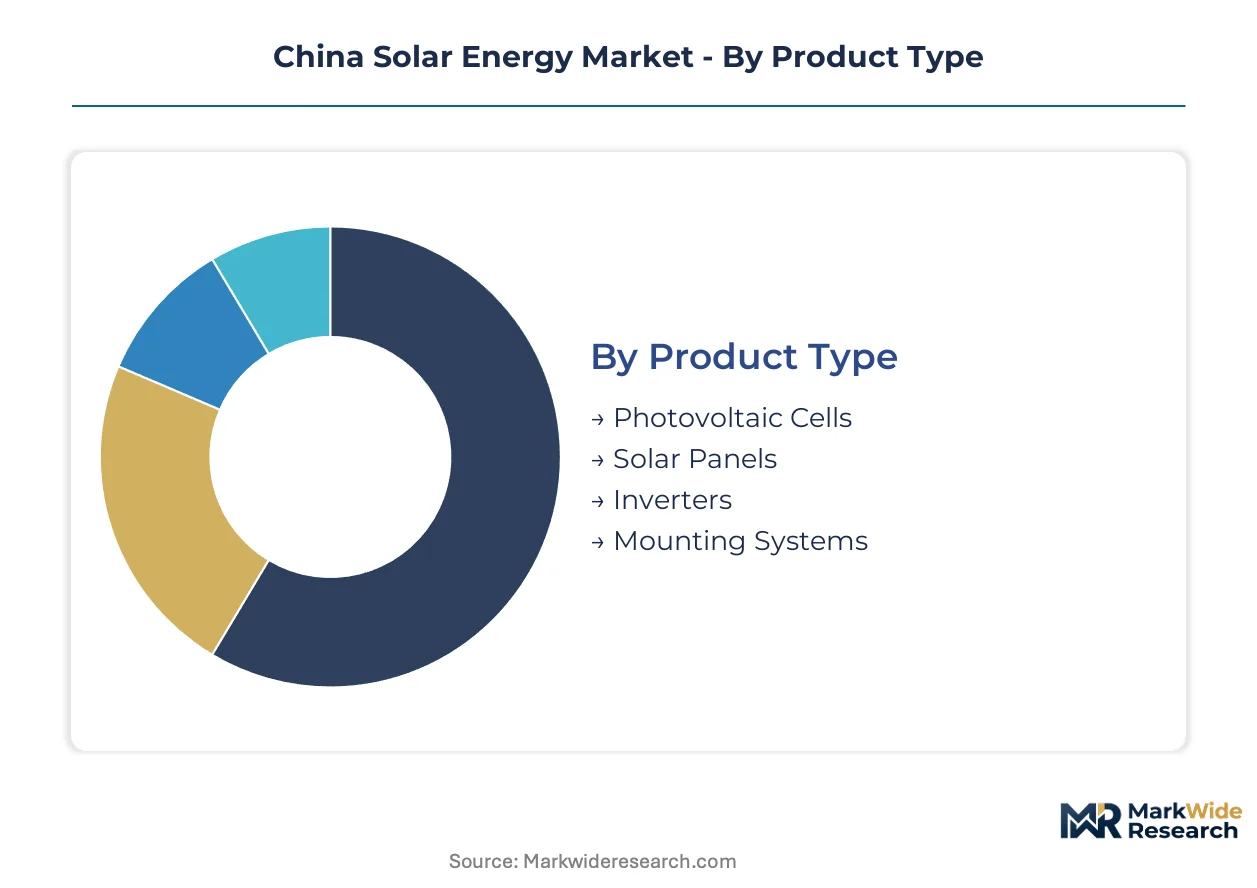
Technology transitions and policy mandates are fragmenting procurement patterns across China's solar value chain. Capital allocation now diverges sharply between commodity-grade capacity and next-generation cell architectures requiring specialized equipment.
Product Type:
Capital intensity peaks at wafer-to-cell conversion stages where furnace and diffusion equipment dominate facility investment. Module assembly requires lower upfront outlays but compresses margins through scale competition.
- Photovoltaic Cells:Semiconductor junction devices fabricated from silicon ingots achieve conversion efficiencies above 24% in mass production. Xinjiang and Inner Mongolia polysilicon feedstock supplies concentrate cell manufacturing in western provinces where energy costs support metallurgical-grade silicon refining. N-type TOPCon migration is forcing retooling investments at existing PERC facilities.
- Solar Panels:Laminated assemblies of cells, encapsulants, and tempered glass frames deliver standardized output ratings for utility-scale deployment. Jiangsu and Anhui production corridors house the highest concentration of module capacity serving both domestic installation and export demand. Bifacial glass-glass architectures command premium positioning for desert applications.
- Inverters:Power electronics systems convert DC panel output to grid-synchronous AC frequency.
- Mounting Systems:Structural hardware secures panel orientation and load distribution across terrain types.
Most installed capacity flows through Solar Panels. Expansion is steepest in Photovoltaic Cells.
Installation Type:
Grid interconnection requirements and storage integration costs create tiered investment profiles across deployment modes.
- Grid-Tied:Direct utility interconnection without battery storage represents the dominant deployment architecture. Western provinces concentrate gigawatt-scale clusters where State Grid Corporation transmission infrastructure enables long-distance power evacuation. NDRC benchmark tariff elimination in Xinjiang and Inner Mongolia accelerates independent power producer entry.
- Hybrid:Battery-coupled systems combine photovoltaic generation with electrochemical storage for resilience against curtailment. Commercial segments in eastern provinces adopt these configurations where grid congestion risks and time-of-use pricing differentials improve project economics. Lithium iron phosphate cell supply from Fujian and Hunan supports domestic integration.
- Off-Grid:Standalone systems serve rural electrification without utility infrastructure.
- Rooftop:Distributed commercial and residential mounting on built structures.
Grid-Tied captures the dominant share of annual additions. Hybrid configurations are climbing the fastest as storage costs decline.
End User:
Procurement scale and contract duration separate utility-scale investment from distributed commercial patterns.
- Utility:State-owned generation groups and independent power producers deploy gigawatt-scale projects under 20-25 year power purchase agreements. Inner Mongolia and Qinghai host the largest project clusters where land availability and irradiance levels support capacity factors above 1,500 equivalent hours. Unbundling of EPC contracts from O&M agreements is fragmenting vendor relationships.
- Industrial:Manufacturing facilities and data centers pursue self-consumption models with behind-the-meter installation. Jiangsu and Guangdong provinces concentrate demand from electronics and automotive assembly plants seeking renewable energy certificates for export compliance. Corporate renewable energy procurement targets are accelerating direct contracting.
- Residential:Individual household rooftop systems.
- Commercial:Small and medium enterprise distributed installations.
Utility procurement dominates capital deployment. Industrial self-consumption is gaining share fastest.
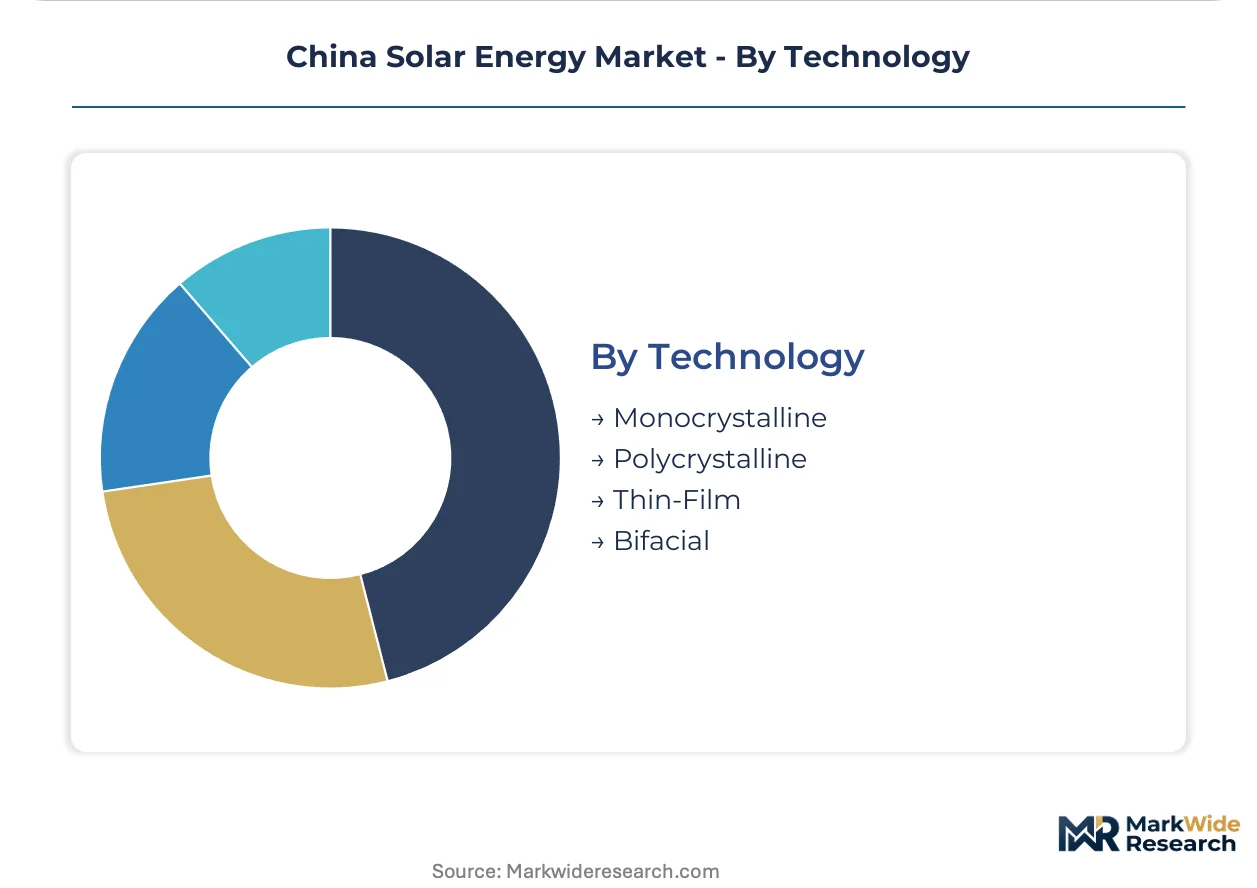
Technology:
Cell efficiency benchmarks and manufacturing process complexity differentiate competitive positioning across material platforms.
- Monocrystalline:Single-crystal silicon wafers achieve the highest mass-production conversion efficiencies through uniform lattice structure. LONGi Solar and JinkoSolar anchor capacity in this segment where Czochralski ingot growth and diamond wire sawing have displaced multicrystalline alternatives. N-type substrates are displacing P-type dominance as tunnel oxide passivated contact architectures mature.
- Bifacial:Dual-sided light capture enables albedo reflection harvesting from ground surfaces. Desert applications in Ningxia and Xinjiang concentrate demand where sand and gravel substrates enhance rear-side yield. Single-axis tracker convergence expands addressable market for utility end users.
- Polycrystalline:Cast multicrystalline silicon with lower efficiency and cost position.
- Thin-Film:Cadmium telluride and copper indium gallium selenide alternative semiconductors.
Monocrystalline production accounts for the dominant technology share. Bifacial adoption is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools concentrated in Jiangsu and Anhui production corridors anchor China's solar manufacturing base. Provincial energy bureaus across western territories accelerate utility-scale deployment through land allocation and grid interconnection prioritization. The analysis examines five sub-regions where project economics and manufacturing capacity converge.
Xinjiang
Urumqi and Hami host gigawatt-scale project clusters where land availability exceeds 2,000 annual equivalent sun hours. The National Development and Reform Commission eliminated benchmark tariffs here in 2021, attracting independent power producers through pure market pricing. Polysilicon refining capacity concentrates in Shihezi and Kuitun, supplying metallurgical-grade silicon to wafer manufacturers nationwide.
Inner Mongolia
Ordos and Baotou corridors command attention from state-owned generation groups seeking 20-year power purchase agreements. NEEA renewable energy quotas compel provincial grid operators to prioritize solar dispatch across these high-irradiance zones. The region's coal-to-renewables transition is concentrating bifacial-plus-tracking installations on former mining reclamation lands.
Qinghai
Golmud and Delingha anchor China's highest-capacity-factor solar resource, exceeding 1,600 equivalent hours annually. State Grid Corporation transmission bottlenecks here delay project commissioning despite superior resource quality. Hybrid battery-coupled systems are gaining traction where curtailment risks intersect with lithium iron phosphate supply from neighboring Gansu corridors.
Jiangsu
Suzhou and Changzhou production corridors concentrate cell and module assembly capacity serving export demand. MIIT GB certification requirements mandate enhanced testing protocols that local manufacturers have operationalized through automated inline metrology. The province's precision manufacturing ecosystem supports N-type TOPCon migration through specialized diffusion equipment supply chains.
Anhui
Hefei and Chuzhou manufacturing bases leverage Yangtze River Delta logistics infrastructure for domestic distribution. Provincial industrial policy directs capital toward intelligent manufacturing systems that compress defect rates below 2% at cell production lines. The region's engineering universities feed process engineering talent into heterojunction and tunnel oxide passivated contact research facilities.
China Solar Energy Market Competitive Environment
Top-tier vendors anchor mass production scale, while mid-tier specialists concentrate on technology differentiation and regional market penetration. The competitive structure stratifies across three archetypes: vertically integrated wafer-to-module producers controlling polysilicon supply, pure-play cell technology innovators, and project development specialists unbundling engineering-procurement-construction from operations. Dominant competitive moves include backward integration into metallurgical-grade silicon refining and strategic partnerships securing long-term power purchase agreements.
Among Chinese-originated manufacturers, LONGi Solar, JinkoSolar Holding Co., Ltd., and JA Solar exemplify distinct strategic positioning within the sector. LONGi Solar occupies a position representing vertical integration from ingot growth through module assembly. JinkoSolar Holding Co., Ltd. sits within the technology-driven tier emphasizing cell architecture differentiation. JA Solar anchors scale-focused manufacturing in the Yangtze River Delta production corridor. These three entities collectively represent the competitive archetypes reshaping procurement patterns across utility and industrial end-user segments.
| Leading Market Players |
|---|
| LONGi Solar |
| Xinyi Solar Holdings Ltd |
| JinkoSolar Holding Co., Ltd. |
| JA Solar |
| Chint New Energy |
| Trina Solar Co. Ltd |
| Shanghai Aiko Solar Energy Co. Ltd |
| GCL-SI |
| Tongwei Solar |
| Others |
Value Chain & Pricing Dynamics
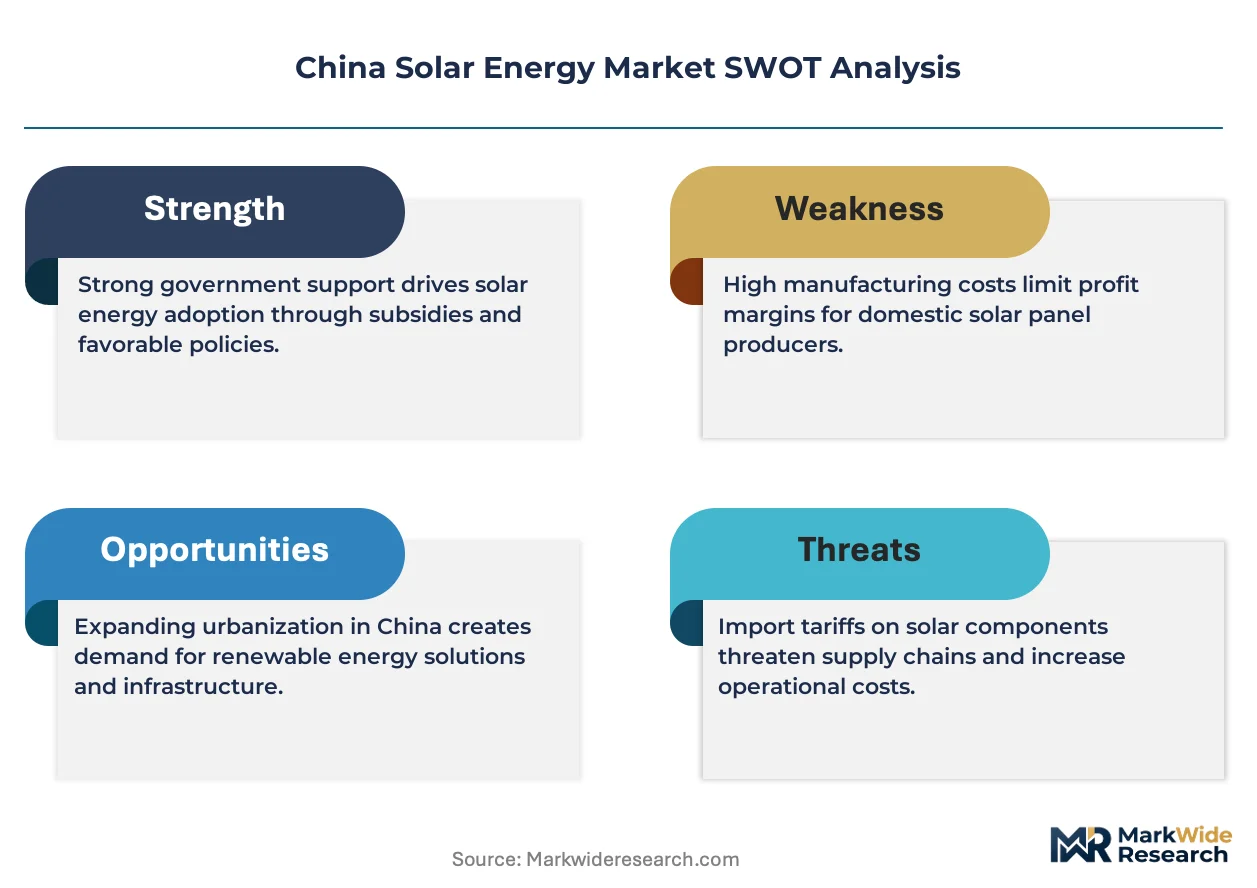
Polysilicon ingot costs cascade from Xinjiang metallurgical-grade silicon refiners through wafer manufacturers to module assemblers, with N-type TOPCon cell premiums separating Jiangsu production corridors from commodity-grade P-type output in Anhui. This input-cost transmission concentrates pricing power among polysilicon-integrated producers while squeezing margin capture at module-only tiers.
Pricing Analysis
Engineering-procurement-construction unbundling from long-term operations and maintenance agreements fragments procurement structures across utility-scale deployment. Price differentiation stems from GB certification tier and bifacial glass-glass architecture premiums. Cost compression in commodity P-type modules is intensifying because of capacity overhang from PERC retooling delays. State-owned generation groups exhibit lowest price sensitivity; distributed commercial installers face acute margin pressure.
Supply Chain Analysis
Metallurgical-grade silicon supply rests on Xinjiang and Inner Mongolia energy-intensive refining corridors feeding wafer growth facilities nationwide. High-purity polysilicon ingots, diamond wire sawing equipment, and tunnel oxide passivation tools constitute critical input dependencies. Single-source vulnerability concentrates in Xinjiang polysilicon where NDRC production quotas create allocation uncertainty. Distribution runs through Yangtze River Delta port infrastructure serving export demand alongside State Grid Corporation transmission corridors for domestic project delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China solar energy functions as a stable compounder where dual carbon goals translate into installation floor guarantees regardless of polysilicon price cycles. This policy-backed demand visibility supports long-term capital deployment across manufacturing and project development tiers.
For Market Incumbents: To counter N-type TOPCon technology migration squeezing PERC asset values, LONGi Solar and JinkoSolar should accelerate backward integration into metallurgical-grade silicon refining and secure captive polysilicon allocation under NDRC capacity directives. Channel control through unbundled O&M contract retention preserves recurring revenue streams against independent asset manager encroachment.
For New Entrants and Emerging Players: A 15-20% price-point gap between premium N-type bifacial modules and economy-grade P-type output creates entry space for heterojunction cell specialists targeting industrial self-consumption segments in Jiangsu and Guangdong. Agrivoltaic dual-use installations in Shandong offer the most penetrable white-space geography. Go-to-market positioning should emphasize MIIT GB certification acceleration to bypass incumbent testing queue advantages.
For Investors and Strategic Acquirers: Consolidation pressure builds where TOPCon retooling capex requirements exceed RMB 500 million for single-facility conversion, forcing mid-tier PERC producers toward distressed asset sales. Long-term viability frames around 5-10 year technology transition windows where cell efficiency leadership determines survival. Acquisition targets should display heterojunction or tunnel oxide passivated contact pilot lines with yield rates above 95%. The signal to watch is MIIT polysilicon capacity allocation policy shifts that redistribute feedstock access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Refining | Xinjiang energy cost advantages secure captive metallurgical-grade silicon supply against NDRC quota volatility. |
| TOPCon Cell Capacity Conversion | MIIT GB certification requirements favor N-type architectures exceeding 24.5% mass production efficiency thresholds. |
| Bifacial-Plus-Tracker System Deployment | Ningxia desert applications leverage albedo capture convergence with single-axis tracking for enhanced yield. |
| Cross-Provincial Power Trading Contracts | NDRC market liberalization enables western generation assets to access premium-priced eastern demand centers. |
| Agrivoltaic Dual-Use Installation Development | Ministry of Natural Resources land classification restrictions open deployment pathways on flat agricultural acreage in Henan. |
Study Parameters
Coverage spans Xinjiang, Inner Mongolia, Qinghai, Jiangsu, and Anhui, with primary inputs from each province's manufacturing bases and project development corridors. The approach combines interviews with utility planning officers at State Grid Corporation, IPP project developers in Ordos and Golmud, EPC contractors serving western provinces, and polysilicon procurement leads at tier-one cell manufacturers. Secondary validation draws from MIIT GB standard filings, NDRC tariff benchmark announcements, NEEA renewable energy quota disclosures, and provincial energy bureau installation statistics. Bottom-up project pipeline aggregation triangulates against top-down manufacturing capacity surveys.
Rate-of-change decomposition separates volume expansion from value-per-watt shifts across the analysis window. Segmentation dimensions include cell technology architecture, installation type, end-user procurement scale, and regional grid interconnection tier. CAGRs derive from polynomial trend fitting of historical installation data adjusted for technology substitution elasticities. Forecast inputs incorporate polysilicon price normalization trajectories and N-type cell migration adoption curves.
Caveats apply where MIIT industrial policy revisions or State Grid Corporation transmission buildout delays could materially shift the outlook. Forecasts reflect assumptions around dual carbon goal continuity and cross-provincial power trading mechanism implementation. A small set of triggers—NDRC benchmark tariff reinstatement, Xinjiang polysilicon export restrictions, or heterojunction cell breakthrough cost parity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
Biogas Upgrading Technology Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Solar District Heating Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
Solar Navigation Light Market
Renewable Energy
Belarus Renewable Energy Market