
 Rectenna Market | 2026-2036
Rectenna Market Size, Share, and Industry Trends Forecast 2026-2036
Rectenna Market Intelligence
Single-source semiconductor procurement is decoupling from legacy RF component supply chains as rectenna manufacturers diversify substrate sourcing. Panasonic leverages captive GaN-on-SiC foundry partnerships to secure wafer supply. Murata Manufacturing anchors its position through ceramic packaging integration that reduces parasitic losses. Texas Instruments competes by embedding rectenna control logic into existing power management IC portfolios.
A rectenna converts electromagnetic radiation into direct current through an antenna-coupled rectifier assembly, typically achieving conversion efficiencies above 80% at 2.45 GHz with Schottky diode architectures. Microwave technology dominates current deployments due to mature magnetron infrastructure and standardized ISM band allocations. Energy harvesting applications represent the fastest-expanding segment, driven by IoT sensor networks requiring ambient RF scavenging. Multi-band product types command premium positioning by addressing variable frequency environments across telecommunications and aerospace end users.
FCC Part 15 rules govern unlicensed RF power transmission in the United States, while ETSI EN 302 567 shapes European wireless power density limits; both frameworks directly constrain rectenna system design and market access pathways. ISO/IEC 63086 standards for wireless power interoperability create compliance benchmarks that manufacturers must satisfy for cross-border equipment certification. Stakeholders should monitor evolving spectrum reallocations and efficiency mandates that will determine which rectenna architectures achieve commercial scale.
Market Dynamics
Gallium nitride semiconductor fabrication is concentrating rectenna supply chains around captive foundry partnerships, as substrate quality directly determines RF-to-DC conversion efficiency at microwave frequencies.
Growth Catalysts
- FCC Part 15 unlicensed transmission rules:The US framework permits ISM band power beaming without spectrum licensing, reducing deployment barriers for consumer electronics integration.
- IoT sensor networks:Ambient RF energy harvesting demand from distributed environmental monitors is pulling multi-band rectenna architectures into volume production.
- METI-backed commercialization programs:Japan's Ministry of Economy, Trade and Industry funding is accelerating laboratory-to-factory transitions for wireless power transfer systems.
Market Restraints
- GaN-on-SiC substrate concentration:Wafer supply bottlenecks from limited high-quality silicon carbide growers constrain rectifier diode output volumes.
- ETSI EN 302 567 power density ceilings:European transmission limits cap system design freedom, forcing hardware derating that elevates unit economics.
- Magnetron infrastructure lock-in:Legacy microwave hardware investments at industrial sites delay adoption of solid-state RF generator alternatives.
Strategic Opportunities
- India BIS certification harmonization:Emerging wireless power standards alignment creates first-mover positioning for rectenna OEMs seeking import substitution contracts.
- 5G small cell backhaul:Beamforming antenna convergence with rectenna arrays enables self-powered network infrastructure in dense urban deployments.
- Aerospace satellite power beaming:Space-to-ground microwave transmission trials are opening qualification pathways for radiation-hardened rectenna modules.
Industry Challenges
- RF/mmWave engineering talent scarcity:Specialized antenna design and impedance matching expertise sits with defense contractors, limiting commercial sector hiring pipelines.
- ISO/IEC 63086 interoperability testing timelines:Multi-vendor certification cycles extend product launch schedules by 8-14 months.
- Legacy power management IC integration:Rectenna control logic must interface with existing PMIC architectures without board redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rectenna Market |
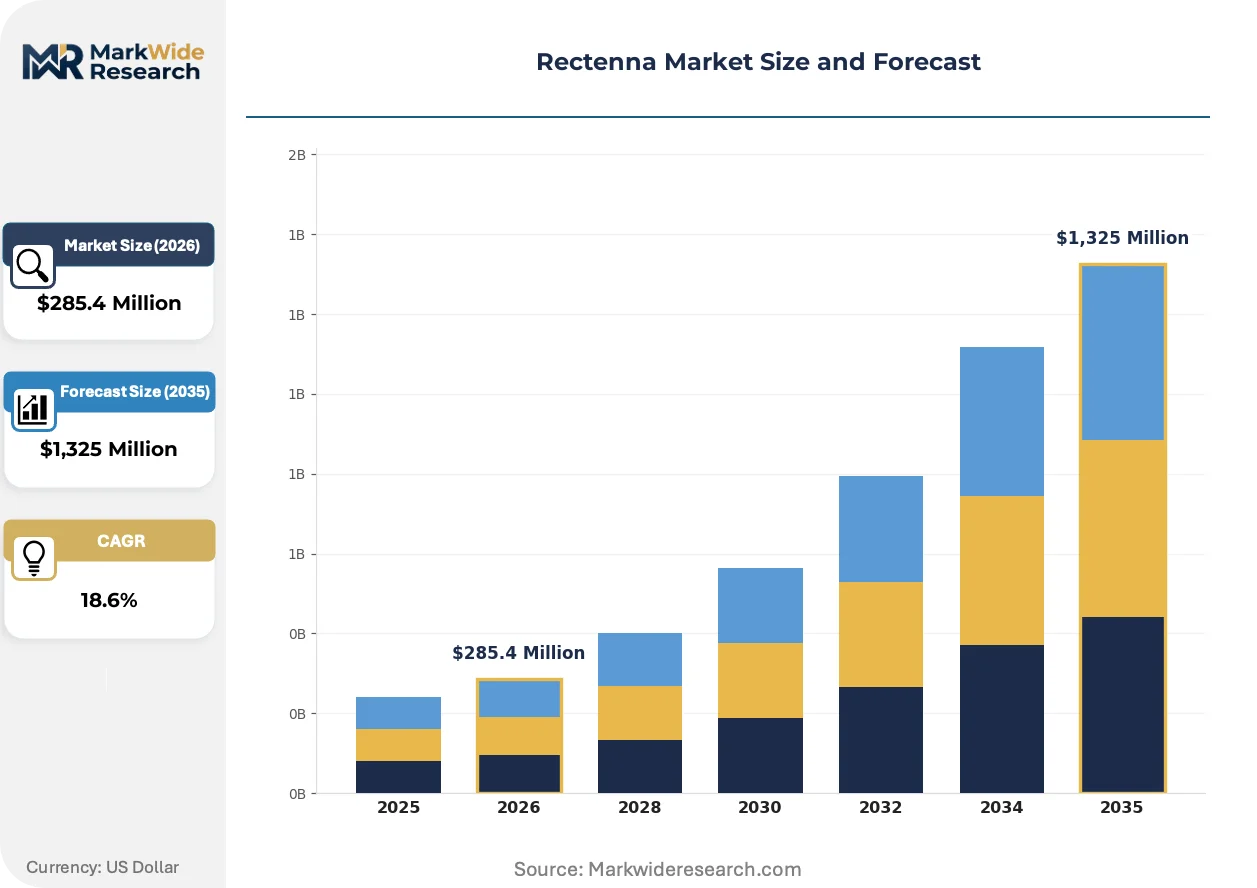
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,325 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Microwave, Millimeter Wave, Terahertz, Optical, Triboelectric Application: Wireless Power Transfer, Energy Harvesting, RFID Systems, Satellite Communication, Sensor Networks Product Type: Single-band, Multi-band, Broadband, Tunable, Array End User: Consumer Electronics, Aerospace, Defense, Telecommunication, Environmental Monitoring |
| Companies Covered | API Technologies, AVX Antenna, CoolCAD Electronics, Panasonic, Powercast Corporation, Murata Manufacturing, Ducommun, Texas Instruments, Antenova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rectenna Market Strategic Shifts & Innovations
Semiconductor material transitions and regulatory clarity around unlicensed spectrum access are compressing rectenna commercialization timelines across telecommunications, aerospace, and consumer electronics verticals.
GaN-on-diamond substrates are expanding into high-power rectenna applications where thermal management limits Schottky diode performance. Satellite manufacturers and radar system integrators are piloting these wafers for 10 kW-class power beaming demonstrations. The material is expanding into markets previously reserved for liquid-cooled silicon carbide assemblies, compressing thermal subsystem footprints by half.
Japan's METI has issued specific guidance on microwave power transmission safety zones, clarifying liability frameworks that previously stalled commercial deployments. Industrial equipment suppliers now reference these exposure protocols in product specifications. Manufacturing automation vendors in Osaka and Nagoya are incorporating the standards into wireless charging infrastructure for automated guided vehicles.
Buyer procurement of rectenna modules is consolidating around qualified supplier lists that prioritize ISO/IEC 63086 pre-certification. Tier-one automotive and aerospace OEMs are disqualifying uncertified vendors from RFQ processes. This behavioral shift is most visible in Germany, where automotive suppliers now require third-party interoperability documentation before design-in approval.
Rectenna Market Segmentation
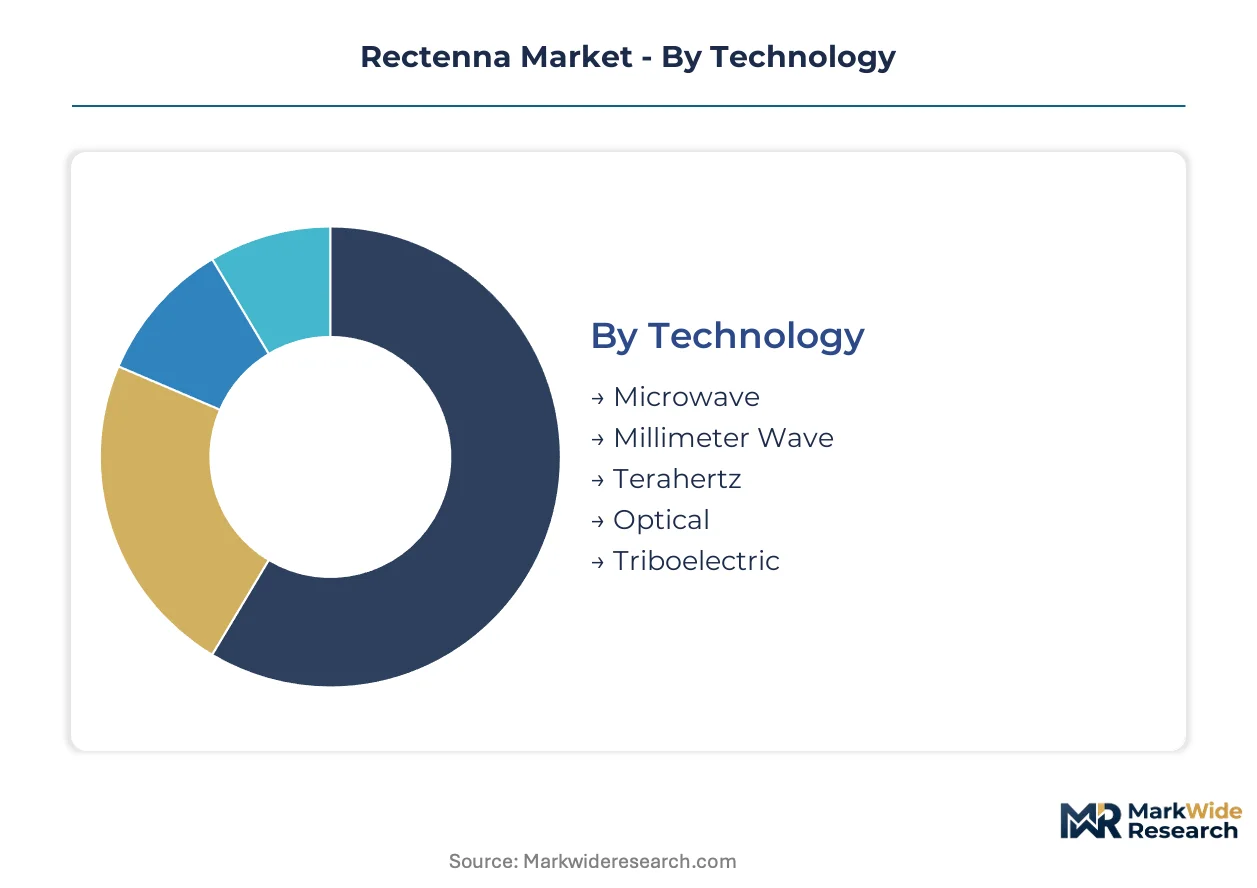
Rectenna architectures diverge sharply across frequency bands and deployment contexts, with substrate material choices and regulatory band allocations determining which configurations achieve commercial scale. Understanding these segment boundaries clarifies where GaN-on-SiC supply constraints bite hardest and which end-use verticals can absorb premium pricing.
Technology:
Supply concentration around GaN-on-SiC foundries favors microwave and millimeter-wave architectures with mature packaging ecosystems, while terahertz and optical approaches remain captive to specialized substrate growers with limited capacity.
- Microwave:Dominant commercial architecture operating at 2.45 GHz and 5.8 GHz ISM bands using Schottky diode rectifiers on silicon or GaAs substrates. Industrial automation vendors in Japan's Aichi Prefecture specify these modules for automated guided vehicle charging infrastructure, constrained by magnetron replacement cycles rather than rectenna availability.
- Millimeter Wave:GaN HEMT-based designs at 24-77 GHz enabling compact antenna apertures for 5G small cell backhaul. South Korean network equipment manufacturers are qualifying these for dense urban deployments where beamforming convergence with rectenna arrays eliminates cable runs.
- Terahertz:Experimental rectifiers using plasma-wave devices in InGaAs channels for 100 GHz+ operation. Defense research laboratories in the United States hold most qualified design expertise.
- Optical:Infrared laser power beaming with GaAs photovoltaic receivers. Space agencies are flight-qualifying these for satellite-to-satellite energy transfer demonstrations.
- Triboelectric:Hybrid mechanical-RF harvesters converting vibration and ambient electromagnetic energy simultaneously. Niche deployment in structural health monitoring of bridges in Germany.
Today's leader: Microwave. Tomorrow's challenger: Millimeter Wave.
Application:
Cost tier stratification separates capital-intensive wireless power transfer infrastructure from low-unit-cost energy harvesting modules, with volume economics determining which segments attract foundry investment.
- Wireless Power Transfer:Directed RF beaming for industrial equipment and consumer device charging. Japanese automotive suppliers in Toyota City are integrating these into factory automation, paying premium prices for METI-compliant safety certification.
- Energy Harvesting:Ambient RF scavenging from broadcast towers and cellular base stations to power distributed sensors. IoT network operators in Germany's Ruhr Valley are deploying multi-band rectenna arrays to eliminate battery maintenance in environmental monitors.
- RFID Systems:Passive tag energization in supply chain tracking. Retail logistics providers in the Netherlands specify single-band Schottky designs for container yard management.
- Satellite Communication:Space-to-ground power transmission and inter-satellite links. Aerospace prime contractors in France are qualifying radiation-hardened rectenna modules for geostationary relay platforms.
- Sensor Networks:Mesh topology self-powering for agricultural and structural monitoring. Australian mining operators are piloting these for remote equipment health diagnostics.
Volume concentrates in Wireless Power Transfer. Steepest expansion trajectory: Energy Harvesting.
Product Type:
Customer type segmentation distinguishes qualified-supplier procurement by tier-one OEMs from price-sensitive design-ins by mid-tier integrators, with ISO/IEC 63086 certification acting as the sorting mechanism.
- Single-band:Fixed-frequency designs optimized for dedicated ISM band operation with minimal matching network complexity. Mass-market consumer electronics manufacturers in Shenzhen specify these for cost-constrained wireless charging accessories.
- Multi-band:Concurrent rectification across 900 MHz, 2.4 GHz, and 5.8 GHz with switchable impedance networks. Telecommunication infrastructure vendors in Finland are selecting these for base station backup power to address variable ambient RF environments.
- Broadband:Log-periodic or spiral antenna configurations spanning decade-plus bandwidths. Spectrum monitoring equipment suppliers in the United Kingdom integrate these for electronic warfare test sets.
- Tunable:Varactor-diode or MEMS-adjusted matching networks adapting to instantaneous frequency availability. Research laboratories in Switzerland are prototyping these for cognitive radio energy harvesting.
- Array:Spatially combined rectenna elements with corporate feeding for watt-scale output. Satellite manufacturers in California are qualifying these for space solar power demonstration missions.
Certification advantage sits with Multi-band. Technology risk concentrates in Tunable.
End User:
Geography drives divergent adoption timelines, with regulatory clarity and industrial policy determining which national markets absorb first commercial volumes.
- Consumer Electronics:Smartphone peripheral and wearable device charging accessories. Japanese retailers in Tokyo and Osaka are stocking METI-labeled wireless power products ahead of other Asia-Pacific markets.
- Aerospace:Aircraft power distribution and satellite subsystems. French and German prime contractors are co-funding rectenna qualification for European Space Agency programs.
- Defense:Covert power beaming and unmanned vehicle energization. Classified programs in the United States and Israel dominate qualified supplier relationships.
- Telecommunication:Base station backup and small cell self-powering. South Korean carriers are deploying rectenna-equipped 5G infrastructure in Seoul metropolitan corridors.
- Environmental Monitoring:Distributed sensor networks for pollution and climate tracking. German federal environmental agencies are specifying multi-band harvesters for Rhine Valley water quality stations.
Policy support anchors Consumer Electronics in Japan. Defense procurement sustains premium pricing elsewhere.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Aichi Prefecture anchors industrial rectenna deployment through Toyota City's factory automation ecosystem. METI-funded commercialization programs accelerate laboratory-to-factory transitions. Regulatory clarity on microwave power transmission safety zones has unlocked procurement from manufacturing automation vendors in Osaka and Nagoya.
United States
Defense research laboratories in Maryland and California hold qualified terahertz rectenna design expertise. FCC Part 15 rules permit ISM band power beaming without spectrum licensing, reducing deployment barriers for consumer electronics integration. Aerospace prime contractors in California are qualifying array configurations for space solar power demonstration missions.
Germany
Automotive suppliers in Stuttgart and Munich now require ISO/IEC 63086 third-party interoperability documentation before design-in approval. ETSI EN 302 567 power density ceilings cap system design freedom, forcing hardware derating. IoT network operators in the Ruhr Valley deploy multi-band rectenna arrays to eliminate battery maintenance in environmental monitors.
South Korea
Network equipment manufacturers in Seoul are qualifying millimeter-wave rectenna designs for dense urban 5G deployments. Beamforming antenna convergence with rectenna arrays eliminates cable runs in small cell backhaul. MFDS-equivalent spectrum regulators coordinate with carriers on 24-77 GHz band allocations for infrastructure self-powering.
France
Aerospace prime contractors in Toulouse co-fund rectenna qualification for European Space Agency satellite programs. Radiation-hardened module testing proceeds through CNES-backed facilities. The country's national space regulator aligns procurement standards with ESA technical requirements for geostationary relay platforms.
Rectenna Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue adjacent energy harvesting applications. The vendor base distributes across captive foundry operators, ceramic packaging specialists, and power management IC integrators. Two strategic archetypes dominate: GaN substrate partners securing wafer supply through vertical manufacturing ties, and module houses embedding rectenna control into existing semiconductor portfolios. Competitive moves concentrate on foundry partnership formation and ISO/IEC 63086 pre-certification acceleration.
Within the captive foundry tier, Panasonic and Murata Manufacturing exemplify substrate-to-package integration strategies. Texas Instruments occupies a position bridging power management IC portfolios with rectenna control logic embedding. These three anchors represent divergent approaches to supply security—captive GaN-on-SiC access, ceramic packaging specialization, and silicon-centric integration economics.
| Leading Market Players |
|---|
| API Technologies |
| AVX Antenna |
| CoolCAD Electronics |
| Panasonic |
| Powercast Corporation |
| Murata Manufacturing |
| Ducommun |
| Texas Instruments |
| Antenova |
| Others |
Cost & Logistics Intelligence
Tier-one automotive and aerospace OEM procurement concentration anchors contract-based long-term offtake pricing with ISO/IEC 63086 certification premiums. Japanese manufacturing automation vendors absorb premium pricing for METI-compliant safety modules, while Shenzhen consumer electronics manufacturers drive cost compression in single-band Schottky designs.
Pricing Analysis
GaN-on-SiC wafer cost pass-through dominates module pricing, with substrate quality tiers separating premium radiation-hardened aerospace modules from standard industrial units. Price differentiation hinges on ISO/IEC 63086 pre-certification status and captive foundry access, with certified multi-band arrays commanding substantial premiums over uncertified alternatives. Pricing pressure intensifies in consumer electronics as Shenzhen manufacturers scale single-band production, while aerospace and defense segments sustain margin buffers through qualification barriers. Mid-tier integrators exhibit highest price sensitivity, whereas Japanese automotive suppliers demonstrate inelastic demand for METI-certified safety documentation.
Supply Chain Analysis
ISO/IEC 63086 certification gating concentrates qualified supplier lists around pre-certified module houses, with substrate supply drawing from Japan, South Korea, and the United States. GaN-on-SiC wafers, ceramic packaging substrates, and Schottky diode epitaxy constitute critical input dependencies. Single-source vulnerability in high-quality silicon carbide growers constrains rectifier output volumes during demand surges. Distribution runs through direct OEM qualification programs rather than open-channel sales, with tier-one automotive and aerospace buyers maintaining approved vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rectenna market compounds steadily through wireless power transfer infrastructure replacement cycles in factory automation. Regulatory clarity on unlicensed spectrum access in Japan and the United States provides predictable demand visibility.
For Market Incumbents: Extend GaN-on-SiC foundry partnerships into exclusive supply agreements before substrate scarcity intensifies. Deepen captive wafer access through equity stakes in emerging silicon carbide growers. Accelerate ISO/IEC 63086 pre-certification for multi-band arrays to disqualify emerging competitors from German automotive RFQ processes. Threat substitution from solid-state RF generators demands proactive magnetron replacement program capture.
For New Entrants and Emerging Players: Agricultural sensor network operators in Australia and mining equipment health monitors represent underserved buyer archetypes with limited incumbent penetration. Target energy harvesting applications in environmental monitoring where qualification barriers remain lower than aerospace tiers. Pursue BIS certification harmonization in India as a first-mover import substitution pathway, leveraging lower regulatory compliance costs versus European ETSI EN 302 567 markets.
For Investors and Strategic Acquirers: Power management IC semiconductor houses are the most active acquirer in this space, seeking rectenna control logic to embed within existing PMIC portfolios. Five-to-ten year viability rests on wireless power transfer adoption in industrial automation rather than consumer electronics margin compression. Acquisition target archetype: ceramic packaging specialists with ISO/IEC 63086 test capabilities and existing automotive supplier relationships. Watch for METI safety zone guidance expansion beyond Japan as inflection signal for regulatory clarity scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Foundry Partnership Expansion | Panasonic's captive wafer access secures supply priority during substrate shortages. |
| ISO/IEC 63086 Pre-Certification Acceleration | Murata's ceramic packaging integration reduces third-party test timeline burdens. |
| PMIC Control Logic Embedding | Texas Instruments bridges power management portfolios with rectenna module interfaces. |
| India BIS Certification Harmonization | First-mover positioning unlocks import substitution contracts in emerging wireless power standards. |
| 5G Small Cell Backhaul Integration | South Korean network equipment manufacturers eliminate cable runs through beamforming convergence. |
Research Approach
Bottom-up wireless power transfer and energy harvesting application modeling reconciled against top-down GaN substrate supply tracking forms the analytical core. Primary interviews with RF engineering directors at network equipment manufacturers, procurement leads at Japanese automotive suppliers, ceramic packaging specialists, and semiconductor foundry planners combined with secondary validation. FCC Part 15 docket filings, METI commercialization program disclosures, ETSI EN 302 567 regulatory texts, and ISO/IEC 63086 draft standards provided documentary anchors. Triangulation across these sources calibrated segment-level demand assumptions.
Historical trendline analysis of magnetron replacement cycles and solid-state RF generator adoption patterns informed projection frameworks. Segmentation dimensions modeled include frequency band architecture, application vertical, product type certification tier, and end-user geography across the analysis window. CAGRs derived from technology substitution curves and regulatory enablement timelines. GaN-on-SiC wafer supply elasticity and METI funding disbursement trajectories served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; microwave and millimeter-wave commercial deployments carry tighter precision than terahertz experimental categories. Forecasts reflect documented assumptions on regulatory clarity progression and substrate supply expansion. GaN-on-diamond substrate commercialization delays or ETSI power density ceiling revisions could materially alter trajectory. A model refresh is warranted upon material change in METI safety zone guidance adoption outside Japan.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
Solar Home Lights Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
China Wind Energy Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Indonesia Renewable Energy CAPEX Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
Nordic Countries Renewable Energy Market