
 North America Organic Dairy Market | 2026-2036
North America Organic Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Organic Dairy Market Intelligence
Supermarket shelf allocation for organic dairy is tilting toward private-label and cooperative brands as conventional retailers expand their natural-food set. Organic Valley leverages its farmer-owned cooperative structure to sustain premium farmgate prices and secure volume commitments from major chains. Horizon Organic competes through backward integration into organic feed supply and controlled herd management across multi-state operations. Danone North America differentiates its portfolio with specialized yogurt fermentation cultures and probiotic positioning that commands price premiums in the chilled dairy case.
Organic dairy encompasses milk and derivative products derived from livestock raised on certified organic feed without synthetic hormones or antibiotics, with pasture access mandates and third-party verification of compliance. The USDA National Organic Program stipulates minimum grazing requirements and prohibits genetically modified organisms in feed rations, creating a segregated supply chain from conventional dairy. Milk remains the volume anchor within product type segmentation, while yogurt captures disproportionate margin pools through functional health positioning and flavor innovation. Online retail represents the fastest-expanding sales channel as direct-to-consumer subscription models and grocery delivery platforms reduce friction for repeat organic purchases.
The USDA National Organic Program administers certification and enforcement, while the FDA governs pasteurization standards and labeling claims across interstate commerce. State-level organic programs in California and Wisconsin supplement federal oversight with additional inspection protocols and dairy-specific feed documentation requirements. Stakeholders must monitor evolving pasture-rule enforcement and potential feed-cost inflation as organic grain markets face competition from regenerative agriculture programs that do not require full organic certification.
Market Dynamics
The USDA National Organic Program's evolving pasture-access enforcement is compressing herd densities and forcing processors to reconfigure milk collection routes across dispersed grazing operations.
Growth Catalysts
- California Organic Feed Standards:The state's supplemental organic inspection protocols create quality premiums that sustain farmgate prices above conventional benchmarks. Processors source from California's Central Valley to secure volume commitments.
- Direct-to-Consumer Subscriptions:Online retail platforms reduce friction for repeat organic purchases. Household buyers lock in monthly delivery schedules that stabilize processor demand forecasting.
- Probiotic Functional Positioning:Yogurt fermentation cultures command price premiums in the chilled dairy case. Health-conscious consumers prioritize clean-label nutrition with digestive health claims.
Market Restraints
- Organic Grain Supply Concentration:Midwest organic feed mills face competition from regenerative agriculture programs that bypass full certification. Input cost volatility squeezes margins for non-integrated producers.
- Multi-State Herd Management Complexity:USDA grazing mandates require pasture documentation across dispersed operations. Compliance overhead scales disproportionately with geographic spread.
- Conventional Private-Label Expansion:Supermarket chains allocate shelf space to uncertified natural-positioned alternatives. Price-sensitive buyers substitute away from premium organic SKUs.
Strategic Opportunities
- Wisconsin Dairy Belt Processing Capacity:Underutilized organic-certified plants in the Upper Midwest offer expansion potential. Cooperatives can aggregate supply from transitioning conventional farms.
- Chilled Grocery Delivery Integration:Cold-chain logistics partnerships with major platforms enable same-day organic dairy fulfillment. Urban density in Toronto and Vancouver supports route economics.
- Regenerative-Organic Certification Convergence:Dual-standard protocols attract climate-conscious buyers without full USDA compliance. Early adopters capture premium positioning ahead of federal rule changes.
Industry Challenges
- Veterinary Protocol Documentation:Antibiotic prohibition requires alternative herd health management systems. Farm staff need training in preventive care and rapid culling decisions.
- Third-Party Audit Bottlenecks:Accredited certifier capacity constraints extend inspection timelines. Transitioning conventional dairies face 12-36 month certification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Organic Dairy Market |
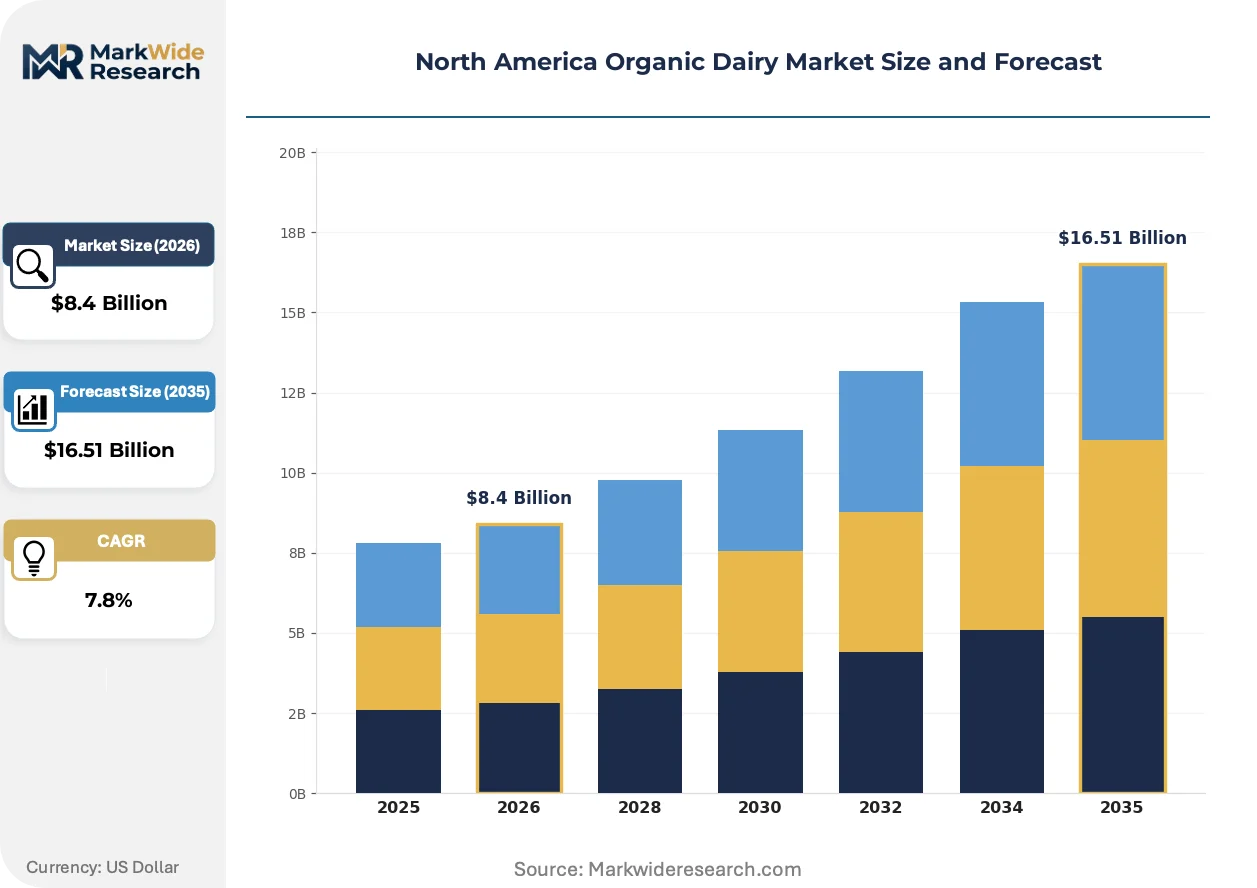
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Yogurt, Cheese, Cream Sales Channel: Supermarkets, Online Retail, Health Food Stores, Distributors End User: Households, Hotels, Restaurants, Cafes Packaging Type: Bottles, Tetra Packs, Cartons, Pouches |
| Companies Covered | Organic Valley, Aurora Organic Dairy, Horizon Organic, Dairy Farmers of America, Danone North America, General Mills, Arla Foods, Saputo, CROPP Cooperative, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Organic Dairy Market Strategic Shifts & Innovations
Clean-label fermentation science and precision pasture management are reshaping how organic dairy processors differentiate shelf-stable and fresh portfolios.
Precision rotational grazing software is hybridizing satellite imagery with soil moisture sensors to optimize forage utilization. Mid-scale Wisconsin and Vermont operations deploy these systems to document USDA pasture compliance while reducing supplemental feed dependence. The technology is compressing the yield gap between intensive confinement and certified organic production models.
The USDA National Organic Program's 2023 Strengthening Organic Enforcement rule mandates supply chain traceability from farm to retail. Processors must verify organic status at every transaction point or face decertification. Small cooperatives in the Upper Midwest and Pacific Northwest are consolidating to spread compliance infrastructure costs across larger volume bases.
Subscription-based procurement is displacing intermittent supermarket purchasing among urban households with children. Direct-to-consumer platforms in California and Texas metropolitan areas bundle organic milk with complementary fresh perimeter categories. This channel shift is concentrating buyer relationships with vertically integrated brands that control their own cold-chain logistics.
North America Organic Dairy Market Segmentation
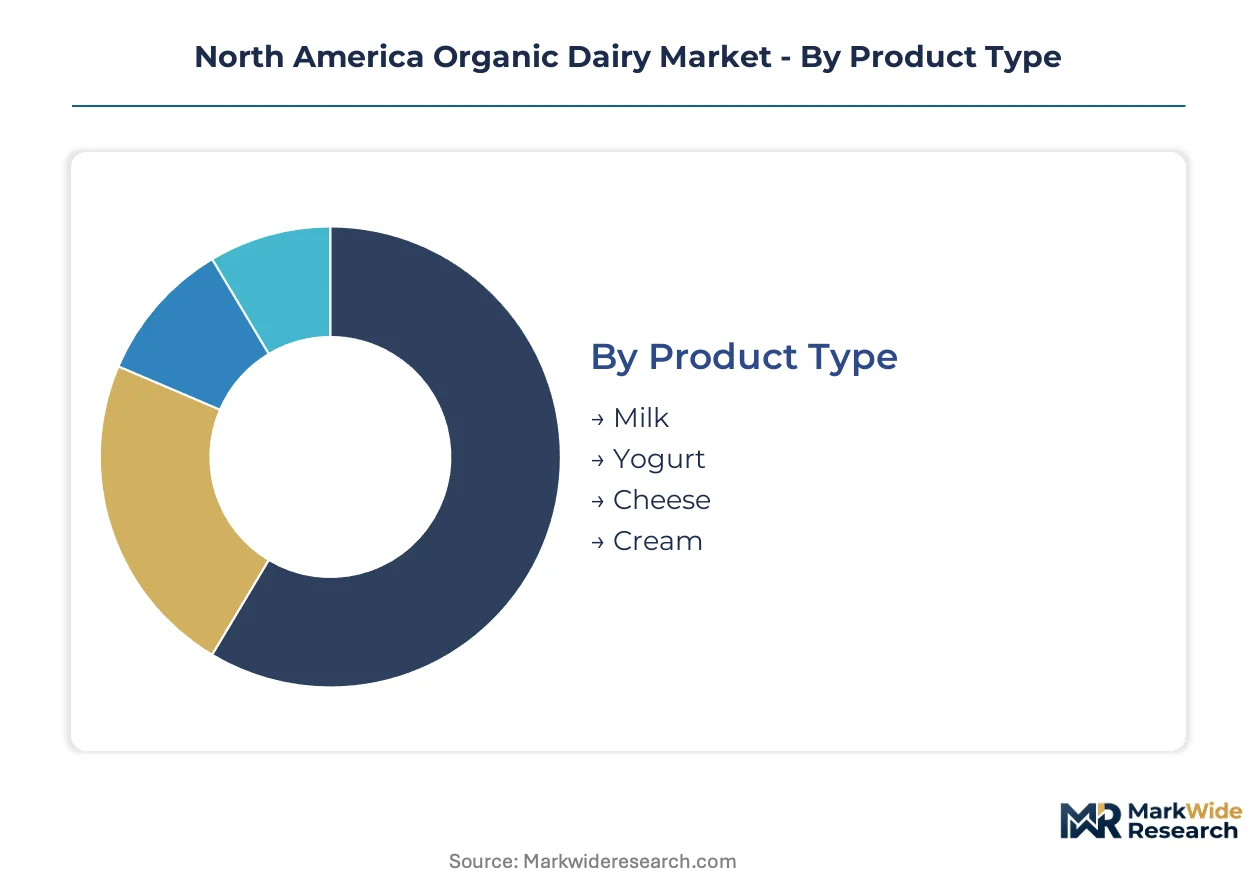
Organic dairy segmentation reveals how shelf velocity, certification complexity, and channel economics fragment revenue pools across product formats and purchase occasions. Understanding these divides exposes where margin concentrates versus where volume scales.
Product Type:
Milk turns inventory fastest with weekly household replenishment cycles, while cheese ages slowest with months-long maturation tying up working capital.
- Milk:Fluid whole and reduced-fat varieties anchor the category with standardized USDA organic certification. California's Central Valley and Wisconsin's dairy belt concentrate fluid milk processing capacity where organic feed supply chains are densest. Weekly purchase frequency and subscription auto-replenishment stabilize processor demand forecasting.
- Yogurt:Greek-style and drinkable formats command chilled case premiums through probiotic functional positioning. Health-conscious households in urban corridors prioritize digestive health claims and clean-label fermentation. Flavor innovation cycles accelerate faster than other categories.
- Cheese:Aged cheddar and mozzarella variants require extended curing periods and specialized affinage infrastructure.
- Cream:Heavy whipping and coffee creamer SKUs serve foodservice and at-home barista applications with shorter shelf lives than cheese.
Milk dominates installed base. Yogurt is where expansion concentrates.
Sales Channel:
Channel economics split between high-frequency supermarket trips and lower-friction digital replenishment with divergent margin structures.
- Supermarkets:Conventional grocers allocate expanding linear footage to private-label organic sets in perimeter dairy cases. Chains negotiate volume commitments with cooperatives like Organic Valley to secure promotional slotting fees. Cold-chain requirements limit direct store delivery radius.
- Online Retail:Subscription platforms and grocery delivery apps reduce purchase friction for repeat organic buyers. Urban density in Toronto, Vancouver, and Texas metropolitan areas supports same-day chilled fulfillment economics.
- Health Food Stores:Natural retailers curate premium SKUs with stricter ingredient standards than conventional grocers.
- Distributors:Foodservice and institutional buyers procure through broadline and specialty dairy distributors with pallet-scale minimums.
Supermarkets dominate installed base. Online retail is climbing the fastest.
End User:
Household purchase cycles run shortest at 7-10 days, while hospitality procurement stretches to monthly or quarterly contracts with price-locked terms.
- Households:Families with children drive organic fluid milk volume through WIC-eligible and subscription channels. Clean-label priorities override price sensitivity for core dairy staples. Repeat purchase rates exceed conventional dairy benchmarks.
- Hotels:Breakfast service and in-room mini-bar programs specify organic cream and individual yogurt portions for premium positioning.
- Restaurants:Farm-to-table concepts highlight organic provenance on menus to justify entrée premiums.
- Cafes:Specialty coffee chains specify organic milk for latte art and foam stability requirements.
Households dominate installed base. Cafes are gaining share fastest.
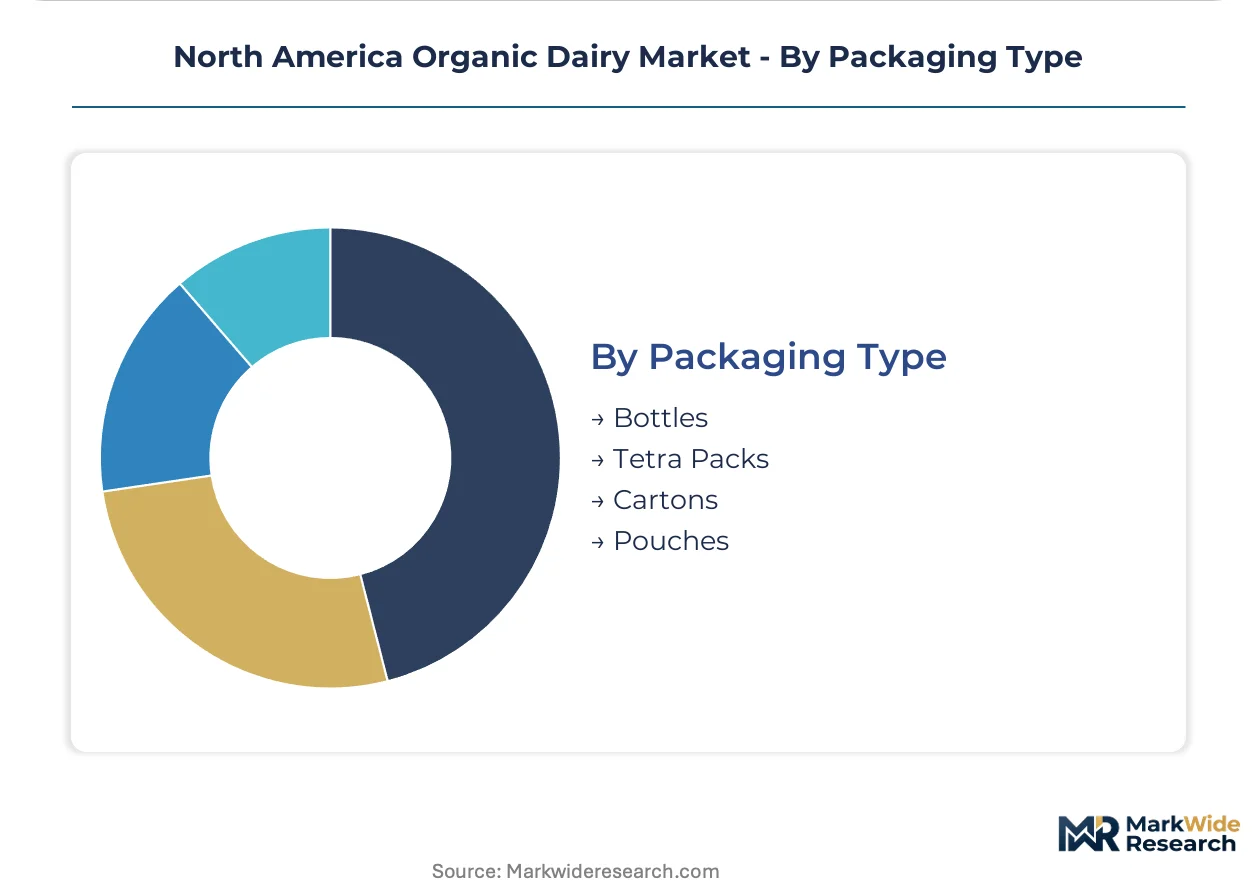
Packaging Type:
Bottles and cartons rotate through supply chains at different velocities based on recycling infrastructure and shelf-life extension requirements.
- Bottles:HDPE and PET formats dominate fluid milk with established municipal recycling streams. California and Wisconsin processors prefer bottles for local distribution where return logistics are economical.
- Tetra Packs:Aseptic cartons extend shelf life without refrigeration for export and emergency stockpiling applications.
- Cartons:Gable-top paperboard remains standard for half-gallon and gallon fluid milk in conventional retail.
- Pouches:Flexible stand-up formats reduce shipping cube for yogurt and drinkable dairy in direct-to-consumer channels.
Cartons dominate installed base. Pouches are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The USDA National Organic Program's certification standards create a unified regulatory baseline across the continent, while state and provincial incentives for sustainable agriculture drive regional production clustering. Mexico's expanding organic feed crop cultivation and Canada's Prairie Provinces grain production increasingly supply cross-border processor demand.
United States
California's Central Valley concentrates fluid milk processing capacity where organic alfalfa and corn silage supply chains are densest. The state's supplemental organic inspection protocols exceed federal minimums, creating quality premiums that sustain farmgate prices above national benchmarks. Wisconsin's dairy belt hosts underutilized organic-certified plants that cooperatives are retrofitting to aggregate supply from transitioning conventional farms.
Canada
Quebec and Ontario dairy cooperatives leverage supply management systems to stabilize organic milk prices amid volatile international feed markets. Health Canada's Canadian Food Inspection Agency enforces organic standards aligned with USDA equivalency agreements for seamless cross-border trade. The Prairie Provinces—Manitoba, Saskatchewan, and Alberta—supply organic grain and forage to US Midwest processors through integrated North American supply chains.
Mexico
Chihuahua and Sonora states expand organic alfalfa cultivation to serve California and Texas processor demand, capitalizing on lower land and labor costs. Mexico's Secretariat of Agriculture and Rural Development (SADER) operates organic certification programs recognized under US-Mexico-Canada Agreement provisions. Baja California's emerging dairy operations target export markets with proximity to San Diego and Los Angeles distribution hubs.
North America Organic Dairy Market Key Industry Players
On the supply side, the industry is bifurcated between farmer-owned cooperatives and corporate integrated processors, with mid-scale regional operators occupying niche positions between these poles. Cooperative structures dominate volume aggregation in the Upper Midwest and Pacific Northwest, while multinational dairy corporations control branded retail shelf space through backward integration into organic feed supply. Two strategic archetypes prevail: vertically integrated brands managing multi-state herd operations, and cooperative federations pooling supply from dispersed member farms. Competitive moves concentrate on cold-chain logistics partnerships with grocery delivery platforms and consolidation of underutilized organic-certified processing assets.
Within the cooperative archetype, Organic Valley and CROPP Cooperative exemplify farmer-owned structures that sustain premium farmgate prices through volume commitments from major retail chains. Among corporate integrated processors, Danone North America and Horizon Organic occupy positions defined by controlled supply chains and branded retail presence. Aurora Organic Dairy represents the large-scale specialist model with concentrated production facilities serving private-label supermarket programs. These three archetypes—cooperative federation, corporate brand integration, and large-scale private-label supply—capture distinct margin pools across conventional retail, natural food channels, and foodservice distribution.
| Leading Market Players |
|---|
| Organic Valley |
| Aurora Organic Dairy |
| Horizon Organic |
| Dairy Farmers of America |
| Danone North America |
| General Mills |
| Arla Foods |
| Saputo |
| CROPP Cooperative |
| Others |
Cost & Logistics Intelligence
Organic grain supply concentration in the Midwest creates input cost volatility that compresses farmgate margins and forces processors toward backward integration into captive feed production. This dependency shapes a three-tier pricing structure across premium cooperative brands, integrated corporate labels, and private-label economy tiers while driving geographic consolidation of milling capacity near major dairy belts.
Pricing Analysis
Certification level under USDA National Organic Program standards creates the primary spread between premium farmgate prices and conventional dairy benchmarks. Pricing stratifies across premium cooperative tiers, mid-market integrated brands, and economy private-label SKUs with volume scale and channel control as secondary differentiation drivers. Cost compression in the economy tier intensifies because regenerative agriculture programs bypass full organic certification while capturing similar consumer positioning. Foodservice buyers exhibit highest price sensitivity due to quarterly contract lock-ins, while subscription households demonstrate lowest sensitivity through auto-replenishment loyalty.
Supply Chain Analysis
Cross-border feed dependency between the United States and Canada dominates supply chain risk profiles for organic dairy processors. Raw material sourcing draws from Midwest organic grain mills, Prairie Provinces forage production, and California Central Valley alfalfa cultivation. Single-source vulnerability concentrates in organic corn and soybean meal imports subject to USMCA tariff fluctuations. Distribution runs through cold-chain partnerships with major grocery delivery platforms and cooperative-owned logistics networks serving conventional retail perimeter cases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
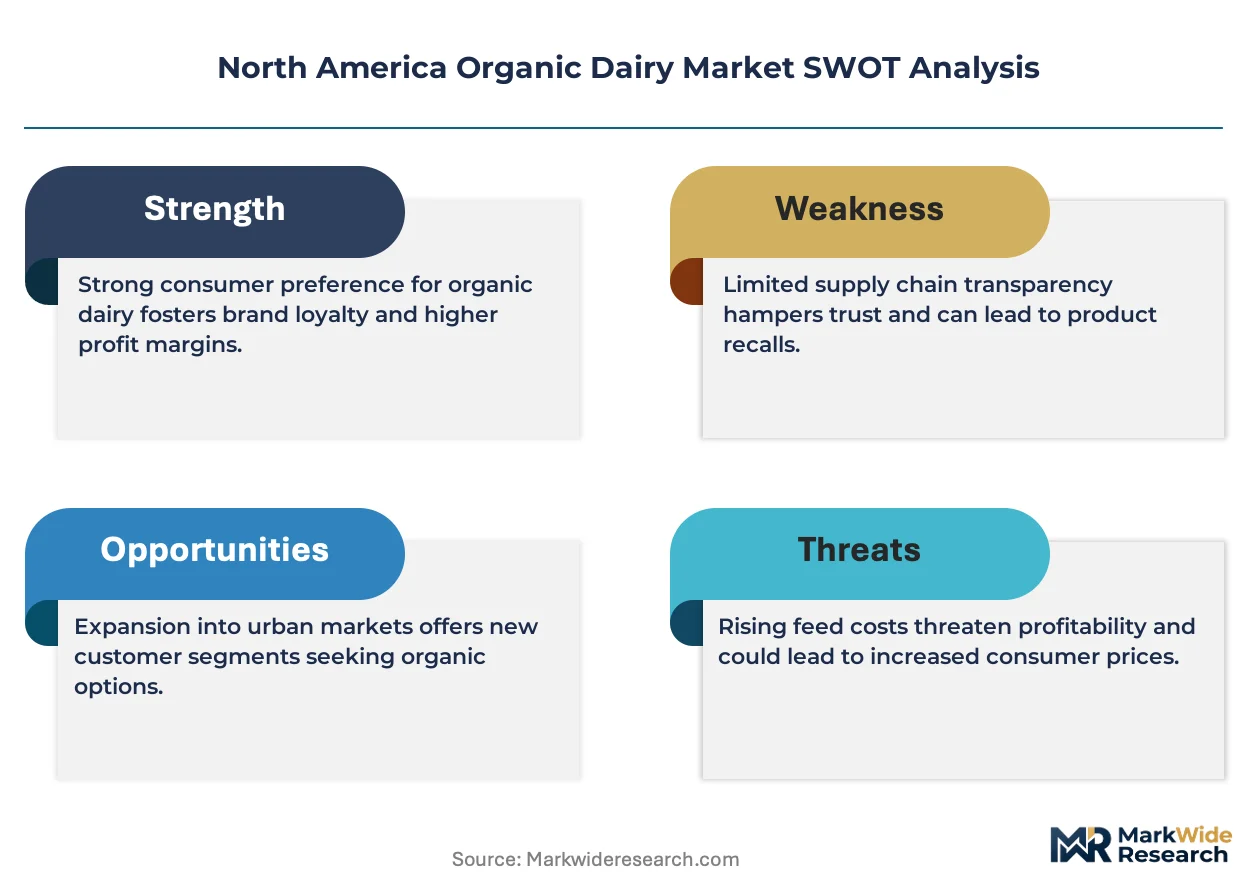
Plant-based dairy alternatives and uncertified natural-positioned private labels threaten organic dairy incumbents with substitution pressure that erodes shelf space allocation and price premiums. Defending against these substitutes requires preemptive moves to lock in channel control and certification credibility.
For Market Incumbents: Pre-empt private-label encroachment by securing multi-year volume commitments with conventional supermarket chains through promotional slotting fee structures. Consolidate underutilized organic-certified processing assets in Wisconsin's dairy belt to aggregate supply from transitioning conventional farms and achieve scale economies against plant-based competitors. Certification investment in dual-standard regenerative-organic protocols captures climate-conscious buyers ahead of federal rule changes. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription channels where urban household density supports route economics and reduces competitive friction with entrenched retail brands. Target Texas metropolitan areas and Pacific Northwest corridors with underpenetrated organic dairy penetration relative to California saturation. Deploy precision rotational grazing technology documentation as a go-to-market angle to demonstrate USDA compliance efficiency and supply chain transparency. For Investors and Strategic Acquirers: USDA National Organic Program's 2023 Strengthening Organic Enforcement rule reshapes the acquisition landscape by mandating supply chain traceability infrastructure that favors scaled operators over fragmented cooperatives. Long-term viability centers on vertically integrated processors with captive organic feed supply and multi-state herd management capabilities. Watch for pasture-rule enforcement actions as a signal indicator of regulatory burden shifts that could accelerate cooperative consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feed | Captive grain supply from Prairie Provinces and Midwest mills insulates processors from input cost volatility. |
| Cold-Chain Logistics Partnership | Same-day chilled fulfillment partnerships with grocery delivery platforms unlock urban household subscription economics. |
| Regenerative-Organic Dual Certification | Climate-conscious positioning attracts premium buyers without full USDA compliance burden during transition periods. |
| Cooperative Processing Asset Consolidation | Retrofitting underutilized Wisconsin plants aggregates supply from conventional farms entering organic transition. |
| Precision Grazing Technology Deployment | Satellite-based pasture documentation satisfies USDA enforcement while reducing supplemental feed dependence. |
Research Approach
A standing panel of dairy cooperative board members, organic certification inspectors, supermarket category buyers, and cold-chain logistics operators provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against USDA National Organic Program enforcement data, FDA pasteurization standard filings, and Nielsen retail audit tracking. Trade flow analysis from USMCA customs records and organic grain futures market data anchored supply-side assumptions. Bottom-up volume aggregation from processor capacity utilization and top-down demand estimation from household penetration rates were triangulated for convergence.
Scenario-bracketing around organic feed cost trajectories and pasture-rule enforcement intensity framed the analytical approach across the analysis window. Segmentation dimensions modeled include product type, sales channel, end-user category, and packaging format alongside geographic production cluster density. CAGRs were derived from trend extrapolation of historical penetration rates adjusted for channel shift acceleration in online retail. Industry-specific forecast inputs incorporated organic alfalfa yield variability and WIC program eligibility expansion patterns.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices and organic grain commodity pricing would shift the trajectory of farmgate margin recovery. Forecasts reflect documented assumptions regarding certification timeline delays and cross-border feed trade continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Fermented Dairy Products Market
Dairy Products
North America Sour Cream Market
Dairy Products
North America Dairy Market
Dairy Products
North America Whole Milk Powder Market
Dairy Products
Global Cream Cheese Market
Dairy Products
Cultured Whey Products Market
Dairy Products
Lactose Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Africa Yogurt Market
Dairy Products
Whole Milk Powder Market
Dairy Products
Lactic Butter Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
Canada Casein and Caseinate Market
Dairy Products
United States Dairy Market
Dairy Products
United Kingdom Casein and Caseinates Market