
 Skimmed Milk Market | 2026-2036
Skimmed Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Skimmed Milk Market Analysis
Market Context with Strategic Players
Dairy processing technician availability is rotating toward automation-heavy plants, tightening labor pools in traditional cooperatives. Fonterra Cooperative Group Ltd. leverages its New Zealand-origin supply base to sustain bulk powder exports across Asian food manufacturers. Nestle SA anchors European retail shelf presence through UHT liquid lines and infant nutrition formulations. Arla Foods amba competes on cooperative-owned milk sourcing, controlling procurement costs across Nordic and British farms.
Technical Definition and Structural Segments
Skimmed milk denotes cow's milk with fat content reduced below 0.5 percent through centrifugal separation, yielding a protein-dense liquid used in standardization, sports nutrition, and low-fat dairy manufacturing. Powdered skimmed milk dominates long-haul export economics due to reduced water weight and ambient storage compatibility, while liquid skimmed milk occupies premium refrigerated channels with shorter shelf-life constraints. Tetra Packs capture institutional volume through aseptic filling efficiency, whereas health food stores and online retailers concentrate growth for organic-certified and lactose-free variants among diet-specific households.
Regulatory Frame and Forward-Looking Close
EU F-Gas Regulation and REACH compliance shape refrigeration chemistry and packaging material selection across European processing facilities, while FDA Grade A Pasteurized Milk Ordinance governs interstate fluid milk standards in the United States. EFSA nutrition claims frameworks restrict how processors label fat-reduction benefits, directly influencing consumer-facing marketing and product positioning. Stakeholders must monitor evolving carbon accounting rules for dairy livestock and processing energy use, as these will increasingly determine facility licensing and export market access eligibility.
Market Dynamics
Centrifugal separation automation is displacing manual creamery labor across European cooperatives, compressing processing costs while tightening technician supply pools for legacy dairy equipment maintenance.
Growth Catalysts
- Sports Nutrition Formulation Demand:Protein-dense skimmed milk concentrate anchors ready-to-drink recovery beverages, with German and Dutch food manufacturers expanding procurement volumes for athlete-targeted product lines.
- EU F-Gas Regulation Compliance:Cold-chain efficiency mandates accelerate ammonia-based refrigeration retrofits in processing facilities, reducing energy intensity per liter of finished product.
- Asian Food Manufacturing Import Pull:Powdered skimmed milk dominates long-haul export economics to Southeast Asian confectionery and bakery producers seeking standardized protein inputs.
Market Restraints
- Feed Cost Volatility:Concentrated grain and hay input inflation across Nordic and British dairy farms compresses raw milk margins before processing stage.
- Refrigerant Chemistry Constraints:REACH compliance timelines restrict hydrofluorocarbon alternatives in European plants, delaying equipment replacement cycles.
- Oat Milk Substitution Threat:Barista-grade oat protein beverages capture shelf-space in German and French retail channels, displacing liquid skimmed milk in coffee applications.
Strategic Opportunities
- Lactose-Free Certification White Space:Enzymatic lactose hydrolysis capacity expansion targets diet-specific households in Netherlands and Belgium retail channels.
- Aseptic Tetra Pack Channel Innovation:Institutional volume capture through ambient-stable packaging reduces cold-chain dependency for school and hospital feeding programs.
- Organic-Certified Procurement Incentives:EU Green Deal agricultural transition payments encourage cooperative-owned farm conversions to certified organic milk supply.
Industry Challenges
- Automation Technician Scarcity:Dairy processing labor pools lack PLC programming and robotic maintenance skills for centrifugal separator overhaul.
- Grade A Pasteurization Compliance Timelines:FDA interstate fluid milk standards impose 72-hour testing windows that constrain cross-border US-Canada supply coordination.
- Legacy Cooperative Governance Friction:Member-owned voting structures slow capital deployment decisions for powder-drying capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skimmed Milk Market |
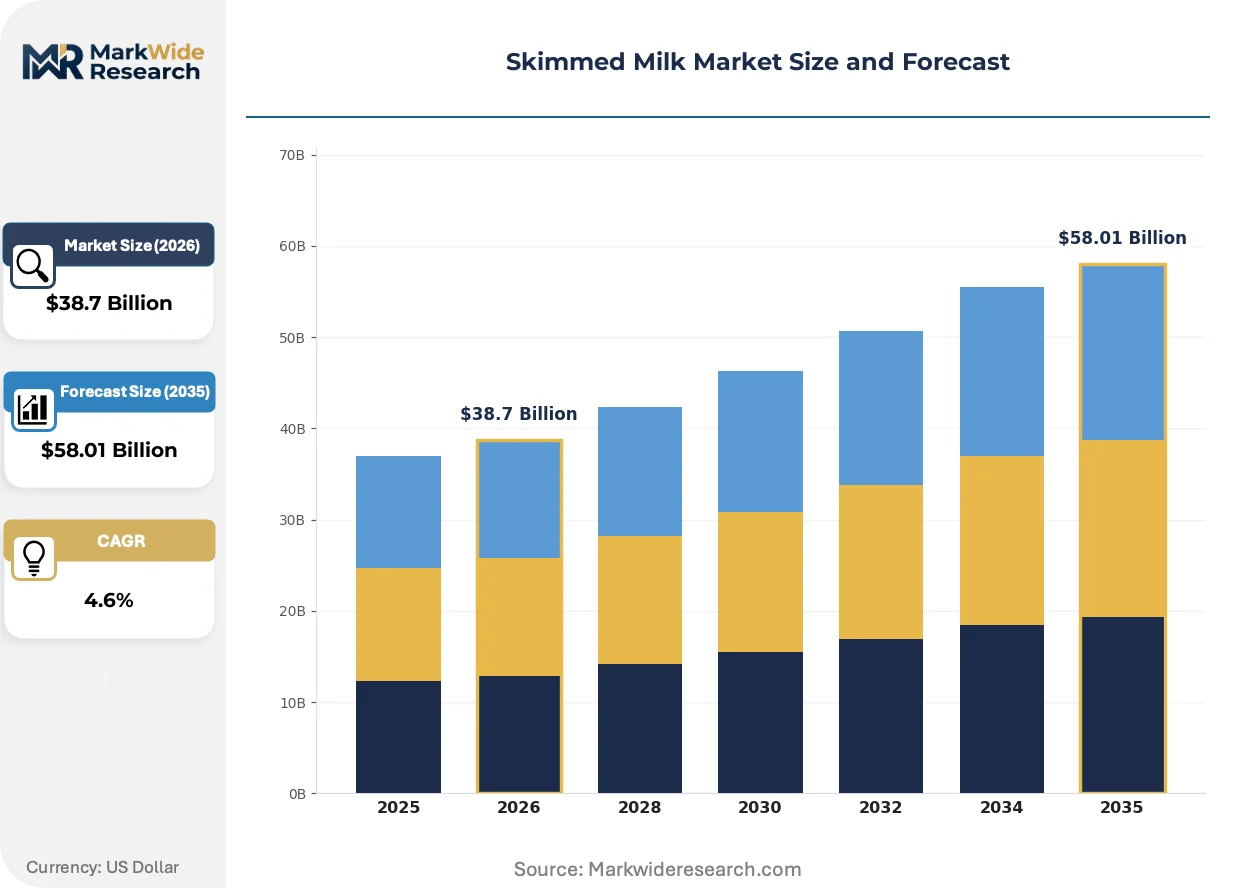
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Skimmed Milk, Powdered Skimmed Milk, Cream, Yogurt Packaging Type: Cartons, Bottles, Tetra Packs, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Health Food Stores End User: Households, Food Service Providers, Bakeries, Dairy Manufacturers |
| Companies Covered | Arla Foods amba, Fonterra Cooperative Group Ltd., Nestle SA, Dairy Farmers of America Inc., Saputo Inc., Agropur Dairy Cooperative, Royal FrieslandCampina NV, Lactalis Ingredients, Danone SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skimmed Milk Market Emerging Trajectories
Membrane filtration and enzymatic processing technologies are reconfiguring protein recovery economics, separating commodity fluid sales from high-margin ingredient extraction.
Microfiltration systems with ceramic membrane arrays is bifurcating the market between commodity fluid processors and specialized protein isolate manufacturers. Sports nutrition compounders in Germany and the Netherlands adopt these systems at accelerated replacement cycles. The technology is bifurcating competitive positioning between volume-driven cooperatives and margin-focused ingredient specialists.
REACH chemical registration requirements and EU F-Gas phase-down schedules force refrigerant inventory conversions across Danish and Swedish processing plants. Industrial ammonia refrigeration retrofits dominate new facility construction while existing HFC-dependent plants face accelerated obsolescence. Powdered skimmed milk exporters to Asian markets absorb compliance cost premiums through long-term contract renegotiation.
Direct-to-institution procurement contracts displace traditional distributor intermediaries in hospital and school feeding channels. German food service providers negotiate volume commitments directly with Arla Foods and FrieslandCampina for UHT liquid lines. This channel compression concentrates most visibly in Benelux metropolitan clusters where consolidated purchasing authorities dominate public sector nutrition programs.
Skimmed Milk Market Segmentation
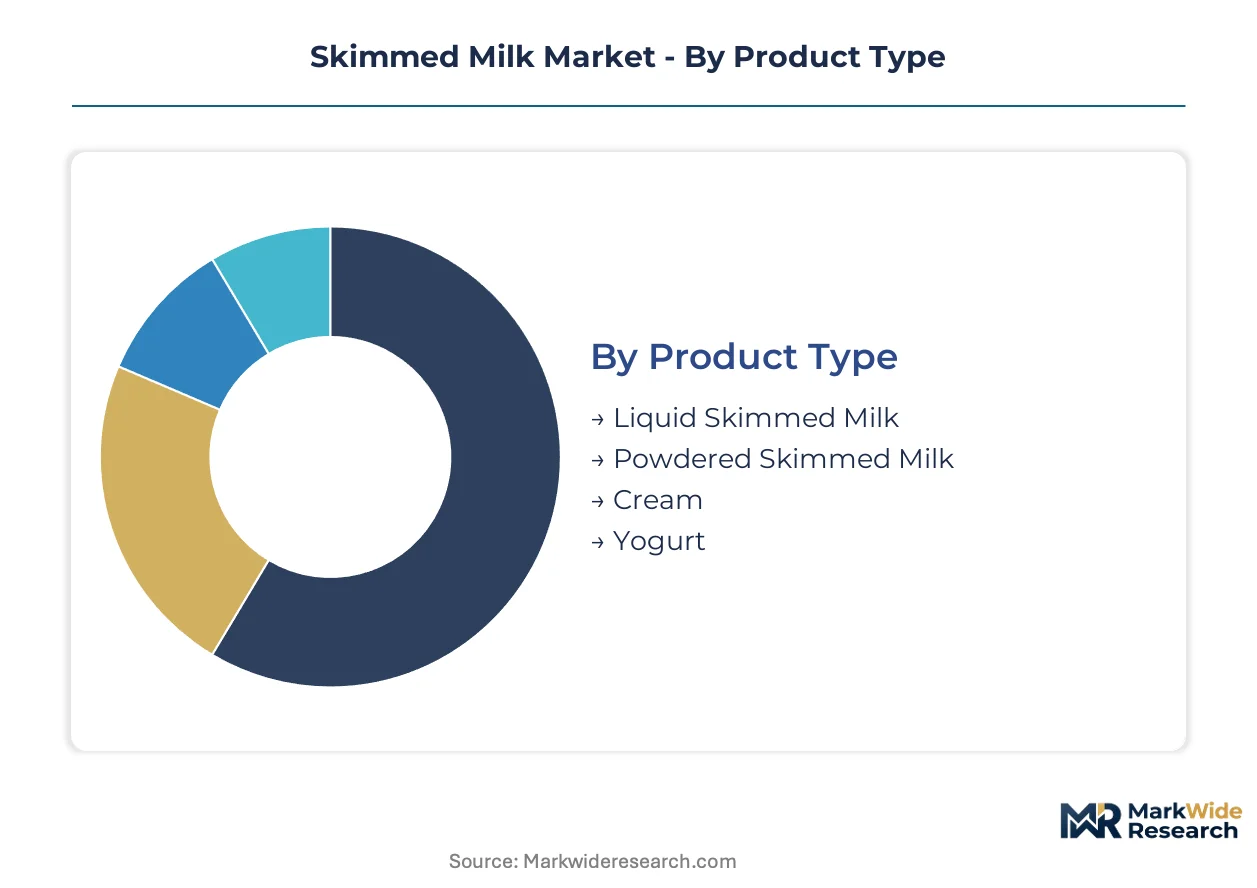
Segmentation in skimmed milk markets reveals divergent margin architectures across physical states, packaging technologies, and channel economics. Powdered formats command export premiums through reduced logistics burden, while liquid variants trade shelf-life constraints for refrigerated retail positioning.
Product Type:
Powdered skimmed milk captures the widest margin spread through protein concentration and ambient stability, while liquid formats compete on freshness positioning in premium domestic channels.
- Liquid Skimmed Milk:Fat-reduced fluid below 0.5 percent fat content serves immediate consumption and standardization applications in dairy manufacturing. German and Dutch retail chains concentrate procurement for private-label UHT lines, though refrigerated logistics compress operating margins versus dried alternatives.
- Powdered Skimmed Milk:Spray-dried protein concentrate enables Southeast Asian confectionery and bakery manufacturers to standardize formulations without cold-chain dependency. Bulk export contracts to Indonesian and Vietnamese food processors sustain volume leadership despite energy-intensive drying operations.
- Cream:Centrifugal separation byproduct with 18-40 percent butterfat content serves premium dessert and sauce manufacturing in French and Belgian food service channels.
- Yogurt:Fermented skimmed milk base with live cultures targets probiotic positioning in Netherlands health food retail.
The dominant share belongs to Powdered Skimmed Milk, while Liquid Skimmed Milk is closing the gap fastest through aseptic packaging innovation.
Packaging Type:
Packaging selection directly determines channel access and shelf-life extension economics, with aseptic technologies opening institutional procurement pathways unavailable to conventional formats.
- Tetra Packs:Multilayer aseptic cartons with aluminum barrier layers enable ambient distribution for school and hospital feeding programs. German food service providers negotiate direct volume commitments with processors, bypassing traditional distributor intermediaries in consolidated public sector purchasing.
- Bottles:HDPE and PET formats dominate German and French refrigerated retail shelves for fresh liquid skimmed milk with 7-14 day shelf life, carrying premium positioning over UHT alternatives.
- Cartons:Gable-top paperboard containers serve conventional retail distribution with shorter shelf-life parameters than aseptic alternatives.
- Pouches:Flexible film formats reduce material cost for bulk institutional delivery and food service portion control applications.
Tetra Packs command institutional volume leadership, though Bottles retain the steepest expansion trajectory through premium fresh-positioned retail lines.
Distribution Channel:
Channel selection reflects household purchasing behavior fragmentation between consolidated weekly shopping and convenience-driven replenishment patterns.
- Supermarkets:Hypermarket and supermarket chains aggregate the majority of German and French household volume through private-label skimmed milk lines and promotional pricing cycles.
- Online Retailers:Subscription-based delivery models capture Dutch and Belgian diet-specific households seeking organic-certified and lactose-free variants with direct-to-door replenishment.
- Convenience Stores:Urban proximity retail serves immediate-need replenishment in Benelux metropolitan clusters with limited SKU depth.
- Health Food Stores:Specialized retail concentrates organic and enzymatically treated lactose-free variants for intolerance-managed households in Netherlands and Belgium.
Supermarkets anchor volume concentration, while Online Retailers gain share most rapidly through subscription loyalty models.
End User:
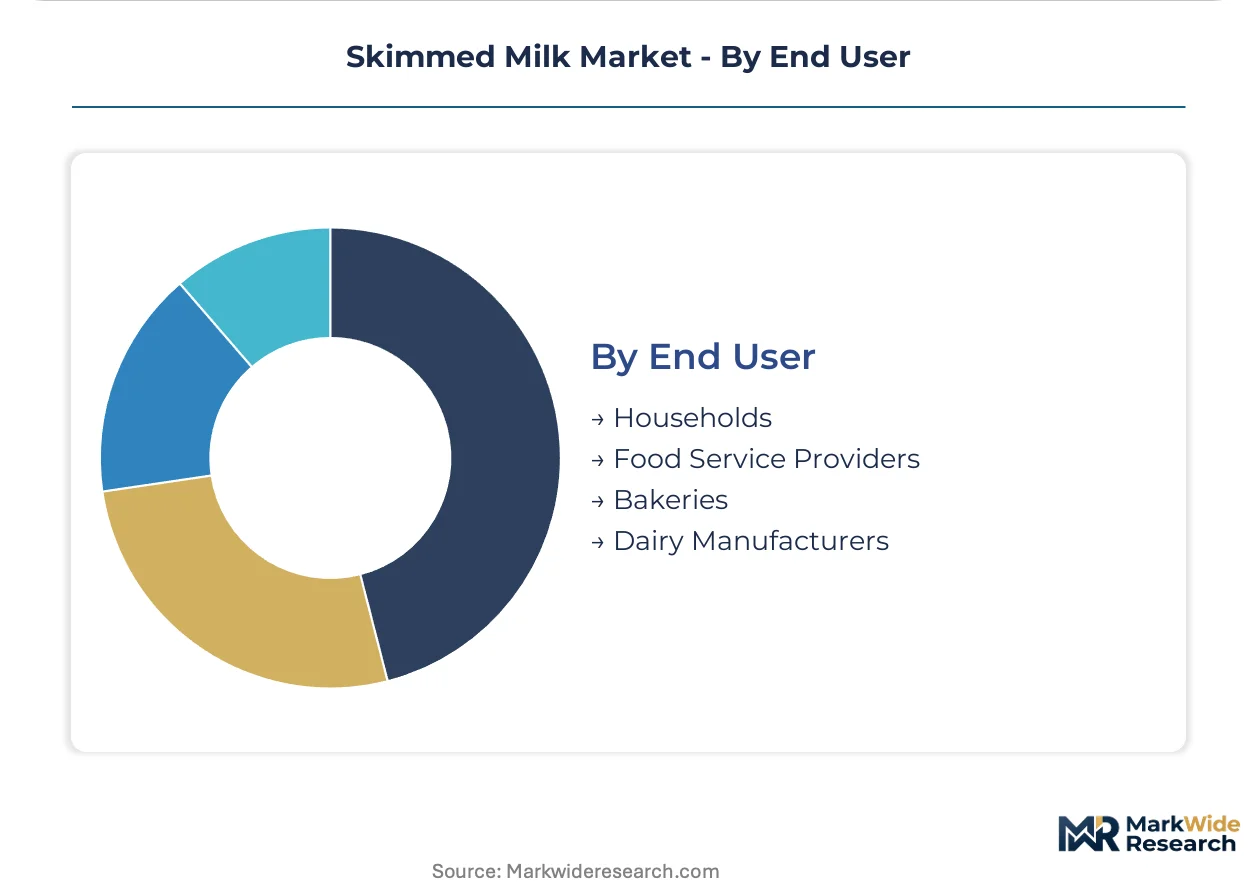
End-user segmentation separates commodity fluid consumption from value-added ingredient extraction, with food service and manufacturing channels driving specification differentiation.
- Dairy Manufacturers:Standardization and protein recovery operations in German and Dutch processing plants convert skimmed milk into cheese, casein, and whey derivatives for sports nutrition compounders.
- Food Service Providers:Restaurant, café, and institutional catering chains in France and Germany expand low-fat menu formulations, procuring UHT liquid lines through direct processor contracts.
- Households:Direct retail consumption concentrates in private-label purchasing for daily fluid milk replacement.
- Bakeries:Southeast Asian confectionery producers import powdered skimmed milk for standardized protein content in industrial-scale pastry manufacturing.
Dairy Manufacturers hold the largest procurement volume, while Food Service Providers are expanding their share fastest through low-fat menu reformulation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes liquid skimmed milk predominantly through retail UHT channels, whereas Southeast Asian markets import powdered formats for industrial food manufacturing, creating divergent logistics and cold-chain investment patterns across geographies.
Germany
Food service providers in Berlin and Munich expand low-fat menu procurement for institutional catering contracts. The EU F-Gas Regulation accelerates ammonia refrigeration retrofits across Bavarian processing plants. The Lower Saxony dairy belt concentrates spray-drying capacity for bulk powder export to Asian confectionery manufacturers.
Netherlands
Dutch retail chains drive lactose-free and organic-certified liquid milk demand through subscription delivery models. EFSA nutrition claims frameworks restrict fat-reduction labeling on consumer packaging. The Randstad metropolitan cluster hosts aseptic Tetra Pack filling lines serving hospital and school feeding programs.
France
French bakeries and dessert manufacturers sustain cream byproduct demand from centrifugal separation operations. REACH compliance timelines constrain hydrofluorocarbon refrigerant alternatives in processing equipment replacement cycles. The Brittany dairy cooperative region maintains specialized yogurt fermentation capacity for probiotic-positioned health food retail.
United States
Dairy Farmers of America member cooperatives supply standardized fluid milk for interstate cheese and casein manufacturing. The FDA Grade A Pasteurized Milk Ordinance imposes 72-hour testing windows that constrain cross-border coordination with Canadian processors. The Midwest dairy corridor spanning Wisconsin and Minnesota anchors powder-drying infrastructure for Southeast Asian export contracts.
New Zealand
Fonterra's cooperative structure sustains bulk whole milk powder and skimmed powder exports across Indonesian and Vietnamese food manufacturers. The country's pastoral dairy farming system operates without EU-equivalent F-Gas constraints on refrigeration chemistry. Canterbury and Southland processing regions concentrate spray-drying capacity for long-haul Asian market supply.
Skimmed Milk Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with cooperative governance structures and publicly traded multinationals occupying distinct competitive spaces. The market structure consolidates around scale-driven powder exporters, retail-brand anchors, and cooperative-owned procurement networks. Three archetypes dominate: Australasian-origin bulk commodity suppliers, European retail-brand multinationals, and North American cooperative federations. Capacity expansion in enzymatic processing and aseptic packaging lines represents the primary competitive move, alongside direct-to-institution contract negotiations that displace traditional distributor intermediaries.
Within the cooperative archetype, Arla Foods amba and Fonterra Cooperative Group Ltd. exemplify member-owned structures that control upstream farm-gate procurement costs across Nordic and Australasian supply bases respectively. Nestle SA occupies a position as the retail-brand anchor, leveraging European shelf presence through UHT liquid lines and infant nutrition formulations. These three entities represent divergent governance models—cooperative democracy, federated farmer ownership, and publicly traded multinational structure—each shaping capital deployment velocity and strategic flexibility differently.
| Leading Market Players |
|---|
| Arla Foods amba |
| Fonterra Cooperative Group Ltd. |
| Nestle SA |
| Dairy Farmers of America Inc. |
| Saputo Inc. |
| Agropur Dairy Cooperative |
| Royal FrieslandCampina NV |
| Lactalis Ingredients |
| Danone SA |
| Others |
Supply Flow & Price Mechanics
Oat protein concentrate substitution in German and French coffee applications simultaneously shifts procurement geography toward Nordic oat processing clusters and compresses pricing premiums for liquid skimmed milk in barista-grade channels. This displacement dynamic redirects food service contract negotiations toward powder-based recovery formulations while ambient-stable alternatives capture institutional volume previously tethered to refrigerated logistics.
Pricing Analysis
Contract-based long-term offtake agreements dominate bulk powder exports to Southeast Asian confectionery manufacturers, with spot market liquidity concentrated in European dairy spot exchanges for immediate standardization needs. Price differentiation rests on organic certification tier and volume scale, with EU Green Deal transition payments widening spreads between conventional and certified organic supply. Cost compression in liquid UHT tiers is intensifying because barista-grade oat beverages capture shelf-space in German retail. Food service providers exhibit highest price sensitivity due to direct processor negotiation leverage, while infant nutrition compounders absorb premiums for protein standardization consistency.
Supply Chain Analysis
New Zealand and Germany anchor spray-drying capacity for bulk powder export economics, with the Netherlands concentrating aseptic Tetra Pack filling infrastructure for institutional feeding programs. Raw material flows draw from concentrated grain and hay inputs across Nordic and British dairy farms, with centrifugal separation equipment and ceramic membrane arrays constituting critical processing components. Single-source vulnerability concentrates in Fonterra's Australasian-origin supply base for long-haul Asian market delivery. Distribution runs through direct-to-institution procurement contracts displacing traditional distributor intermediaries in Benelux metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic lactose hydrolysis services and subscription-based organic delivery models expand faster than commodity fluid sales, creating attach-rate opportunities for processors with captive processing capacity. This service layer recurs at higher margins than hardware-equivalent powder production.
For Market Incumbents: Shield powder-drying capacity utilization through long-term offtake renegotiation with Indonesian and Vietnamese food manufacturers facing oat milk substitution pressure in their home markets. Backward integration into cooperative-owned organic farm conversions captures EU Green Deal agricultural transition payments before subsidy pools deplete. Channel control through direct-to-institution contracts in German hospital and school feeding programs locks out distributor-dependent challengers. For New Entrants and Emerging Players: Differentiate on enzymatic lactose-free certification in Netherlands and Belgium retail channels where diet-specific households concentrate and incumbent capacity remains constrained. Target health food store distribution for organic-certified variants with subscription loyalty mechanics borrowed from Dutch online retail pioneers. A white-space opening exists in barista-grade protein standardization for sports nutrition compounders seeking German-origin supply chain provenance. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dairy ingredient specialists holding membrane filtration technology but lacking cooperative procurement scale for feed cost hedging. Five-to-ten year viability hinges on carbon accounting rule adaptation for livestock and processing energy use. The signal to watch is ammonia refrigeration retrofit completion rates across Danish and Swedish processing plants as proxy for regulatory compliance positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia Refrigeration Retrofit | EU F-Gas Regulation compliance secures facility licensing in Bavarian processing plants. |
| Enzymatic Lactose Hydrolysis Capacity Expansion | Dutch retail chains capture diet-specific household subscription loyalty in Randstad clusters. |
| Direct-to-Institution Procurement Contract | German food service providers bypass distributor intermediaries in consolidated public sector purchasing. |
| Organic Farm Conversion Incentive Program | EU Green Deal payments reduce cooperative procurement cost spreads for certified supply. |
| Ceramic Membrane Array Technology Adoption | German sports nutrition compounders accelerate replacement cycles for protein isolate extraction. |
Methodological Framework
Initial hypotheses were tested against primary input from dairy processing plant managers, cooperative procurement leads, food service category buyers, and sports nutrition formulation scientists and refined through secondary validation against Fonterra cooperative disclosures, Arla Foods sustainability reports, EU F-Gas Regulation implementation guidance, and EFSA nutrition claims framework documentation. Bottom-up volume modeling across spray-drying capacity and top-down macroeconomic triangulation anchored value estimates.
Variance-decomposition framing separates volume drivers from price elasticity effects across the projection horizon. Segmentation dimensions modeled include physical state, packaging technology, distribution channel, and end-user application with regional regulatory cluster overlays. CAGRs were derived from installed capacity utilization trajectories and protein standardization demand curves, with feed cost volatility and refrigerant chemistry compliance timelines serving as scenario-weighting inputs.
Forecasts assume regulatory continuity in EU F-Gas phase-down schedules and FDA Grade A Pasteurization Ordinance enforcement; material policy shifts in carbon accounting for dairy livestock would require re-modeling. Specific risks that could revise projections include accelerated oat milk substitution in German retail and REACH compliance timeline extensions for hydrofluorocarbon alternatives. Recalibration cycles align with material shifts in EU Green Deal agricultural transition payment structures and Asian food manufacturing import demand patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
Goat Milk Products Market
Dairy Products
Kefir Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
Yogurt Drink Market
Dairy Products
GCC Camel Dairy Market
Dairy Products
Germany Dairy Market
Dairy Products
North America Organic Dairy Market
Dairy Products
Dairy Foods Market
Dairy Products
China Milk Protein Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
Global Dairy Cream Market
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
Clotted Cream Market
Dairy Products
Greek Yogurt Market
Dairy Products
Milk Mineral Market