
 Anti-Spit Up Formula Market | 2026-2036
Anti-Spit Up Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Spit Up Formula Market Outlook
The gap between premium clinically positioned anti-spit up formulas and commodity standard infant nutrition is expanding. Nestlé leverages its pediatric nutrition heritage to sustain premium shelf placement across pharmacy and specialty retail channels. Abbott Laboratories anchors its position through hospital discharge programs that convert clinical endorsement into household purchasing. Danone competes in European markets with specialized hydrolyzed protein formulations.
Anti-spit up formula comprises infant nutrition products engineered with added rice starch, locust bean gum, or carob bean gum to increase viscosity and reduce regurgitation episodes, typically achieving a final osmolality below 350 mOsm/L to maintain gastric tolerance. Powder formats dominate volume due to lower per-feed cost and extended shelf stability, while ready-to-feed products capture disproportionate margin in hospital and travel segments. Hydrolyzed protein ingredient types are gaining fastest among infants with concurrent milk protein sensitivity, though thickening agents still occupy the largest share of product positioning.
The FDA enforces infant formula nutrient specifications and Good Manufacturing Practice requirements under the Federal Food, Drug, and Cosmetic Act, while China's SAMR mandates formula registration and on-site audit compliance for imported specialty products. The EU's EFSA scientific opinions on infant nutrition claims constrain how manufacturers communicate reflux-reduction benefits to consumers. Stakeholders must monitor whether regulators tighten labeling distinctions between standard and anti-reflux formulations.
Market Dynamics
The anti-spit up formula market is being reshaped by tightening regulatory convergence between the FDA's updated infant formula nutrient specifications and China's SAMR registration requirements for imported specialty products, which together are compressing formulation flexibility while elevating compliance costs for cross-border manufacturers.
Growth Catalysts
- Pediatric clinic endorsement:Hospital discharge programs in the United States are converting clinical recommendations into sustained household purchasing patterns for thickened formulas.
- EFSA scientific opinions:The European authority's guidance on infant nutrition claims is creating standardized frameworks that reduce regulatory uncertainty for compliant manufacturers.
- Hydrolyzed protein technology:Formulations addressing concurrent milk protein sensitivity are capturing expanded addressable demand among infants with multiple feeding intolerances.
Market Restraints
- Thickening agent supply concentration:Rice starch and locust bean gum sourcing clusters in Southeast Asian agricultural processing regions, exposing manufacturers to climate-driven harvest volatility.
- SAMR on-site audit requirements:China's mandatory facility inspections for imported specialty formulas extend registration timelines and increase capital deployment for market access.
- Standard infant formula substitution:Positioning against commodity nutrition products limits price elasticity and compresses margin expansion potential in price-sensitive segments.
Strategic Opportunities
- Ready-to-feed channel expansion:Hospital and travel segments offer disproportionate margin capture compared to powder formats, with pharmacy retail chains expanding shelf allocation.
- EFSA claim authorization pathways:Manufacturers achieving reflux-reduction claim validation can differentiate against competitors limited to generic thickening positioning.
- Pediatric subspecialty integration:Neonatal care unit formulary inclusion creates institutional lock-in that extends through early childhood feeding transitions.
Industry Challenges
- Formulation stability expertise:Maintaining viscosity consistency across temperature variations and shelf life requires specialized protein-carbohydrate interaction knowledge that outpaces general food science talent pools.
- Dual jurisdiction compliance:Simultaneous FDA and SAMR registration demands create documentation redundancy and timeline misalignment that strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Spit Up Formula Market |
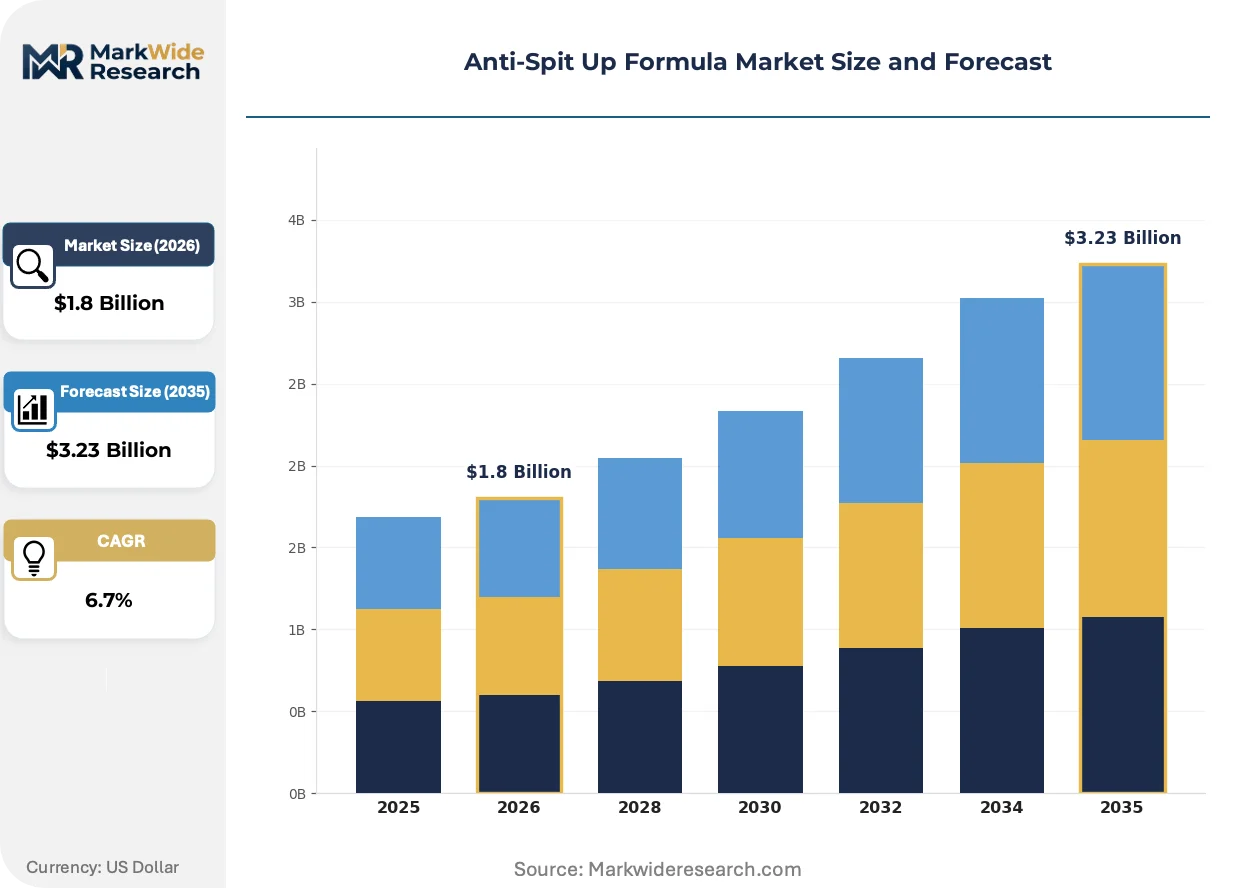
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Ready-to-Feed, Concentrate Ingredient Type: Probiotics, Hydrolyzed Proteins, Thickening Agents, Sensitive Formulas Age Group: Infants, Toddlers, Newborns, Children Packaging Type: Carton, Bottle, Sachet, Tub |
| Companies Covered | Nestlé, Abbott Laboratories, Reckitt Benckiser, Danone, Perrigo Company, Mead Johnson Nutrition, Arla Foods, FrieslandCampina, Yili Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Spit Up Formula Market Strategic Shifts
Formulation science and channel configuration are undergoing concurrent transformation as manufacturers respond to clinical evidence requirements and parental purchasing behavior shifts. The intersection of regulatory stringency and digital commerce access is redefining how specialty infant nutrition reaches end users.
Precision thickening systems using modified rice starch with controlled amylopectin branching are electrifying formulation stability, enabling consistent viscosity across wider temperature ranges than conventional locust bean gum bases. Pediatric nutrition specialists in academic medical centers are adopting these systems for severe reflux cases, compressing the performance gap between anti-spit up and standard formulas while maintaining gastric tolerance targets.
China's SAMR has implemented sequential on-site audit protocols for imported specialty formula registration, requiring manufacturing facility inspections before market authorization. This policy is extending time-to-revenue for new entrants and favoring established manufacturers with existing Chinese regulatory infrastructure, particularly affecting European and North American exporters seeking pediatric specialty positioning.
Subscription-based replenishment models through pharmacy e-commerce platforms are displacing traditional retail stocking patterns for anti-spit up formulas. Direct-to-parent delivery services in the United States are capturing recurring revenue streams that bypass conventional grocery and mass merchandiser intermediaries, with highest penetration among dual-income households managing infant feeding logistics.
Anti-Spit Up Formula Market Segmentation
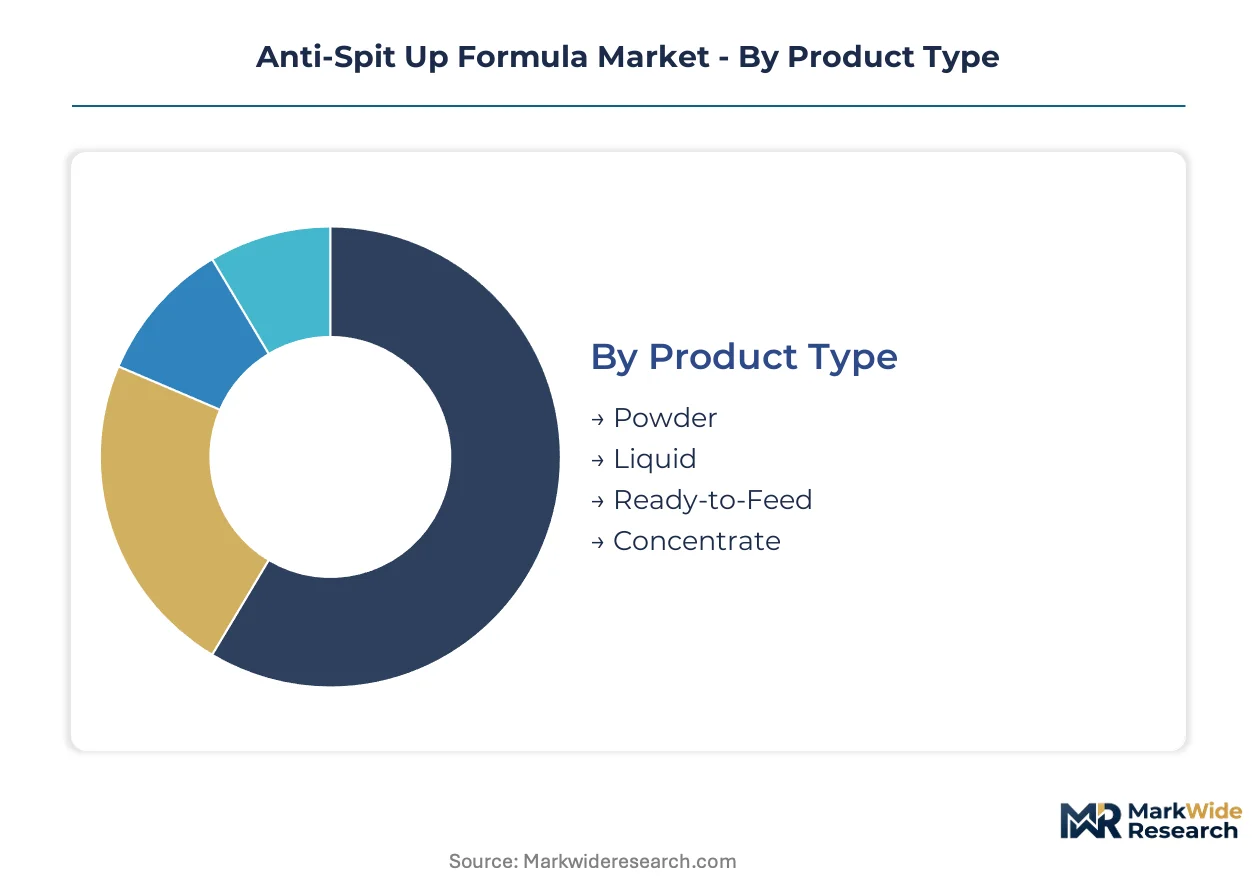
Anti-spit up formula segmentation reveals how formulation chemistry, delivery format, and developmental targeting intersect to create distinct commercial battlegrounds. Each dimension carries unique margin profiles and regulatory exposure that shape manufacturer portfolio strategy.
Product Type:
Powder production clusters in Midwestern dairy processing corridors and Dutch nutritional ingredient hubs, creating geographic concentration that influences regional cost structures.
- Powder:Dominated by modified rice starch and locust bean gum formulations with osmolality engineered below 350 mOsm/L. Household demand concentrates in United States pharmacy retail and European supermarket chains where per-feed cost sensitivity drives volume. Extended shelf stability of 18-24 months enables bulk purchasing and inventory efficiency for distributors.
- Ready-to-Feed:Sterile liquid formats achieving precise viscosity through aseptic processing lines. Hospital discharge programs in Texas and California pediatric networks convert clinical endorsement into sustained household purchasing; travel segment demand through airport retail and pharmacy e-commerce captures disproportionate margin per liter.
- Liquid:Refrigerated distribution requirements limit geographic reach to cold-chain capable markets. Concentrated manufacturing in Illinois and Wisconsin dairy corridors serves regional pharmacy networks.
- Concentrate:Dilution-required format occupying niche positioning between powder economy and ready-to-feed convenience. Limited shelf placement in United States mass merchandisers reflects consumer preference for single-step preparation.
Powder absorbs the bulk of installed capacity; ready-to-feed is expanding most quickly.
Ingredient Type:
Ingredient sourcing patterns trace back to Southeast Asian agricultural processing for thickening agents and European enzymatic hydrolysis facilities for protein modification.
- Thickening Agents:Rice starch and locust bean gum constitute the foundational viscosity technology. Climate-driven harvest volatility in Thai and Indonesian processing regions exposes manufacturers to input cost fluctuation; locust bean gum extraction from Moroccan and Spanish carob cultivation faces seasonal supply constraints.
- Hydrolyzed Proteins:Enzymatic cleavage of whey and casein reduces allergenic epitope exposure for infants with concurrent milk protein sensitivity. Demand concentrates in German and French pediatric allergy clinics where EFSA claim frameworks constrain direct reflux-reduction marketing.
- Probiotics:Lactobacillus and Bifidobacterium strains added for gut microbiome modulation. Strain-specific stability challenges across shelf life limit formulation flexibility; regulatory classification varies between food and supplement frameworks across jurisdictions.
- Sensitive Formulas:Multi-intolerance positioning combining hydrolyzed proteins with reduced lactose and hypoallergenic thickening. Premium pricing in United States specialty pharmacy channels reflects parental willingness to pay for clinical positioning.
Thickening agents command the largest production volume allocation; hydrolyzed proteins are gaining share fastest among specialty formulations.
Age Group:
Developmental feeding windows create distinct formulation specifications tied to gastric capacity and nutritional density requirements.
- Newborns:Preterm and low-birth-weight formulations with enhanced caloric density and reduced osmotic load. Neonatal intensive care unit formulary inclusion in Ohio and Pennsylvania academic medical centers creates institutional lock-in extending through early childhood transitions.
- Infants:Standard anti-reflux positioning for 0-12 month feeding intolerance. United States pediatric clinic endorsement patterns concentrate demand in pharmacy and specialty retail channels.
- Toddlers:Transition formulas addressing persistent regurgitation beyond standard infant windows. Limited dedicated product availability reflects category boundary with growing-up milks.
- Children:Niche positioning for neurodevelopmental or anatomical conditions extending reflux symptoms. Prescription pathway requirements in most jurisdictions constrain commercial scale.
Infant formulations absorb the bulk of manufacturing capacity; newborn specialty segments are climbing the fastest on a percentage basis.
Packaging Type:
Packaging configuration directly determines distribution channel access and shelf-life performance across climate variations.
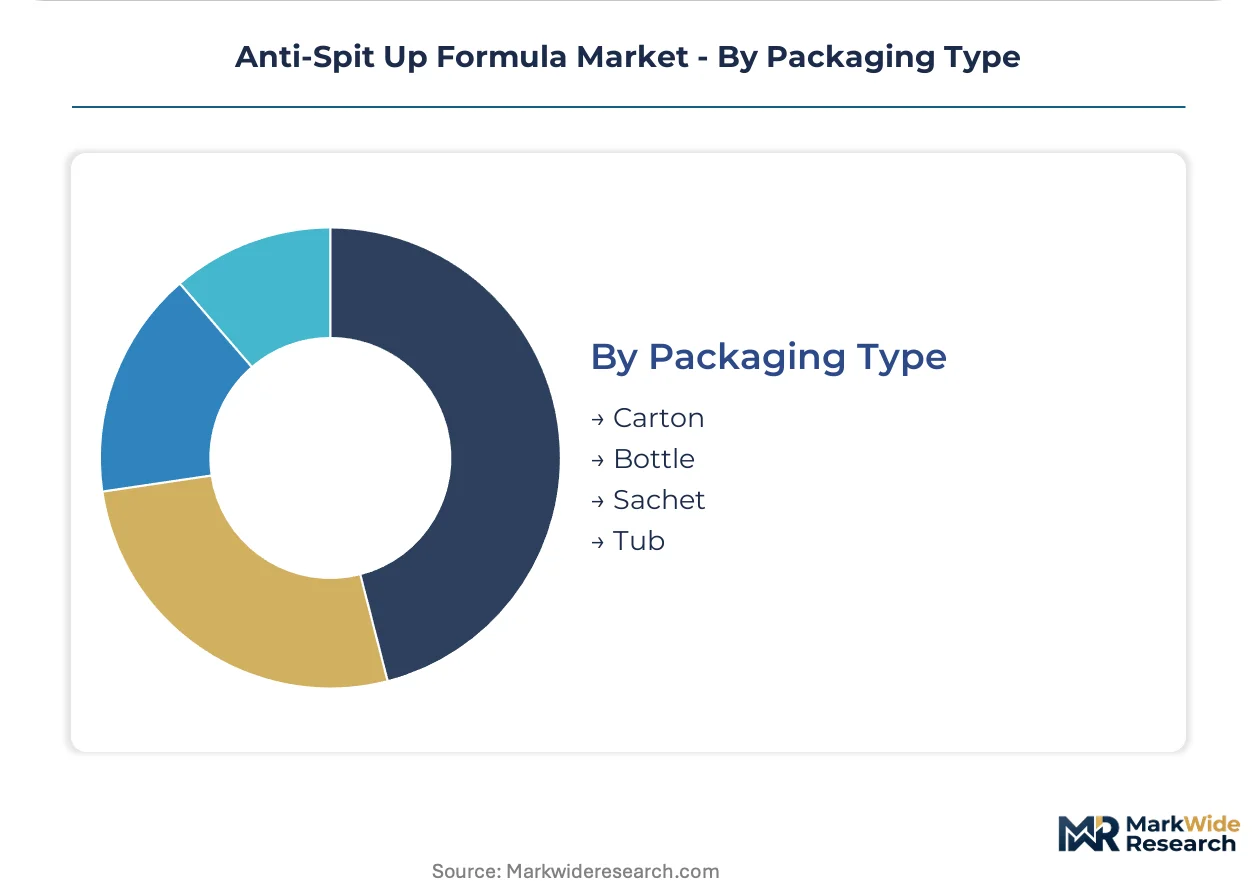
- Tub:Multi-serve powder containers dominating United States warehouse club and mass merchandiser volumes. HDPE and polypropylene formats with moisture-barrier seals; manufacturing concentration in Illinois and Ohio plastics corridors.
- Bottle:Ready-to-feed and liquid concentrate formats requiring sterile filling lines. Blow-molded PET and glass alternatives; European demand favors glass for environmental positioning while United States retail prioritizes shatter-resistant PET.
- Sachet:Single-serve powder portions capturing pharmacy and travel segment premium. Foil-laminate structures with precise dose measurement; Southeast Asian manufacturing hubs serve regional and export demand.
- Carton:Aseptic brick formats for liquid products in European and Asian markets. Tetra Pak and SIG Combibloc filling equipment requirements create capital barriers for new entrants.
Tub packaging absorbs the bulk of installed capacity; sachet formats are expanding most quickly in pharmacy e-commerce channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zeeland Province in the Netherlands anchors European pediatric nutrition manufacturing, with FrieslandCampina's specialized ingredient facilities supplying hydrolyzed protein bases to anti-reflux formulators across Germany and France. This coastal dairy corridor demonstrates how geographic concentration of upstream processing shapes downstream competitive access.
United States
Pediatric clinic endorsement patterns in Texas and California pediatric networks convert hospital discharge programs into sustained household purchasing for thickened formulas. The FDA enforces updated infant formula nutrient specifications under the Federal Food, Drug, and Cosmetic Act, tightening compliance thresholds for specialty positioning. Illinois and Ohio plastics manufacturing corridors dominate multi-serve tub packaging for pharmacy retail channels.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia adopt precision thickening systems with modified rice starch for severe reflux cases. EFSA scientific opinions on infant nutrition claims constrain direct reflux-reduction marketing, creating standardized frameworks that reduce regulatory uncertainty. Frankfurt's pharmacy retail chains expand shelf allocation for ready-to-feed formats targeting travel segments.
China
Dual-income households in Shanghai and Beijing drive subscription-based replenishment through pharmacy e-commerce platforms, displacing traditional retail stocking patterns. SAMR mandates sequential on-site audit protocols for imported specialty formula registration, extending time-to-revenue for new entrants. Yangtze River Delta manufacturing hubs concentrate domestic production capacity for standard infant nutrition.
France
Pediatric allergy clinics in Paris and Lyon concentrate demand for hydrolyzed protein formulations addressing concurrent milk protein sensitivity. ANSM oversight of specialized infant nutrition maintains strict claim authorization pathways that favor established manufacturers with regulatory infrastructure. Île-de-France distribution networks channel products through pharmacy retail rather than mass merchandiser intermediaries.
Australia
Neonatal care units in New South Wales and Victoria expand formulary inclusion of anti-reflux products for preterm and low-birth-weight infants. TGA registration requirements for specialty formulas align with international standards while maintaining independent facility inspection protocols. Sydney-based pharmacy e-commerce platforms capture recurring revenue through direct-to-parent delivery services.
Anti-Spit Up Formula Market Competitive Environment
Capital-heavy producers with integrated dairy processing and pediatric nutrition heritage compete with asset-light brand marketers licensing formulation technology from third-party ingredient suppliers. The market structure consolidates around three strategic archetypes: multinational nutrition conglomerates with hospital discharge program access, regional dairy cooperatives leveraging local sourcing advantages, and private-label manufacturers serving pharmacy retail chains. Dominant competitive moves include portfolio diversification into hydrolyzed protein segments and geographic expansion through SAMR registration infrastructure in China.
Among multinational nutrition conglomerates, Nestlé and Abbott Laboratories exemplify the hospital endorsement archetype, converting clinical recommendations into sustained household purchasing patterns. Danone occupies a position within the European hydrolyzed protein specialization tier, while FrieslandCampina anchors the dairy cooperative model with integrated ingredient supply. Mead Johnson Nutrition and Reckitt Benckiser sit within the premium clinically positioned segment, though their strategic emphasis diverges across geographic markets. Perrigo Company represents the private-label manufacturing archetype, supplying pharmacy retail chains with cost-optimized alternatives.
| Leading Market Players |
|---|
| Nestlé |
| Abbott Laboratories |
| Reckitt Benckiser |
| Danone |
| Perrigo Company |
| Mead Johnson Nutrition |
| Arla Foods |
| FrieslandCampina |
| Yili Group |
| Others |
Value Chain & Pricing Dynamics
Hospital discharge programs and neonatal intensive care units concentrate purchasing power for clinically positioned anti-spit up formulas, anchoring a value-based pricing model where clinical endorsement commands substantial premiums over commodity infant nutrition alternatives.
Pricing Analysis
Clinical outcome anchoring ties price premiums to measurable reflux-reduction efficacy in hospital settings. Pricing stratifies across premium clinically endorsed tiers, standard pharmacy retail positioning, and economy private-label alternatives, with differentiation driven by EFSA claim authorization status and hydrolyzed protein inclusion. Cost compression in standard tiers is intensifying because commodity infant formula substitution limits price elasticity. Dual-income households in United States pharmacy channels show lowest price sensitivity; mass merchandiser shoppers in European supermarket chains exhibit highest.
Supply Chain Analysis
Specialized food science talent pools in Illinois and Ohio dairy processing corridors constrain formulation stability expertise expansion. Manufacturing gravity centers on Dutch nutritional ingredient hubs and Midwestern dairy corridors, with thickening agent sourcing anchored in Thai and Indonesian rice starch processing and Moroccan carob cultivation. Raw material dependencies include modified rice starch, locust bean gum, and enzymatically hydrolyzed whey proteins. Single-source vulnerability in Southeast Asian agricultural processing exposes manufacturers to climate-driven harvest volatility. Distribution runs through pharmacy retail chains and direct-to-parent e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-spit up formula supply is tightening around SAMR registration infrastructure and precision thickening technology capabilities, with capacity bottlenecks in qualified manufacturing facilities propping pricing power for incumbents.
For Market Incumbents: Anticipate intensifying competition from private-label manufacturers by securing neonatal intensive care unit formulary lock-in through specialized newborn formulation development. Deepen backward integration into modified rice starch processing to reduce exposure to Southeast Asian harvest volatility. Prioritize EFSA reflux-reduction claim authorization to defend margin position against generic thickening competitors. For New Entrants and Emerging Players: Capture white-space opportunity in subscription-based replenishment models serving United States dual-income households through pharmacy e-commerce platforms. Target toddler transition segments where dedicated anti-reflux product availability remains limited. Pursue SAMR registration infrastructure partnerships with established Chinese domestic manufacturers to compress time-to-revenue. For Investors and Strategic Acquirers: The window for entry favors asset-light brand marketers with licensed formulation technology and established pharmacy retail channel access. Long-term viability rests on portfolio diversification into hydrolyzed protein segments addressing concurrent milk protein sensitivity. Monitor EFSA scientific opinion evolution on infant nutrition claims as inflection indicator for marketing differentiation potential.| Strategic Initiative | Industry Significance |
|---|---|
| SAMR Registration Infrastructure Investment | On-site audit compliance capabilities in China determine market access for imported specialty formulas. |
| Precision Thickening Technology Licensing | Modified rice starch formulations with controlled amylopectin branching command hospital formulary inclusion. |
| Pharmacy E-Commerce Platform Partnership | Direct-to-parent subscription models bypass conventional grocery intermediaries in United States markets. |
| EFSA Claim Authorization Pathway | Validated reflux-reduction marketing separates clinically positioned products from generic thickening alternatives. |
| Neonatal Care Unit Formulary Integration | Institutional lock-in through preterm and low-birth-weight formulations extends through early childhood transitions. |
Study Parameters
Independent corroboration across pediatric nutrition executives, regulatory affairs specialists at formula manufacturers, pharmacy retail category buyers, and neonatal care unit formulary directors underwrites the qualitative findings. Secondary validation draws from FDA infant formula filings, SAMR registration databases, EFSA scientific opinions, and pharmacy e-commerce platform transaction patterns. Bottom-up demand modeling across product type, ingredient technology, age group, and packaging configuration triangulates with top-down market sizing.
Comparable historical performance across the projection horizon anchored growth trajectory assumptions to verified adoption patterns in hospital discharge programs and subscription replenishment channels. Segmentation dimensions modeled include delivery format, protein modification technology, developmental feeding window, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating parental willingness-to-pay indices and clinical endorsement conversion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR audit protocol evolution, climate impacts on Southeast Asian rice starch harvests, and EFSA claim framework revisions. Forecasts reflect documented assumptions regarding pediatric clinic endorsement persistence and pharmacy e-commerce penetration trajectories. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Infant Formula Ingredients Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
Fortified Pet Food Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
Global Lactose-Free Infant Formula Market
Baby Food and Infant Formula
Infant Formula Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
South America Organic Baby Food Market
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market
Baby Food and Infant Formula
Baby Juice Market