
 Africa Yogurt Market | 2026-2036
Africa Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Yogurt Market Outlook
Urban household consumption is consolidating as the dominant demand pillar across African yogurt markets, displacing traditional institutional bulk purchasing. Danone Southern Africa leverages its chilled distribution network to anchor premium-positioned portfolios in Southern African retail corridors. Brookside Dairy competes through backward integration into Kenyan highland milk sourcing, sustaining cost advantages in East African markets. Chi Limited specializes in locally adapted flavor profiles, occupying a distinctive niche in Nigerian urban centers where Western formulations underperform.
Yogurt constitutes a fermented dairy product produced through bacterial culture of milk, typically containing live Lactobacillus delbrueckii subsp. bulgaricus and Streptococcus thermophilus at minimum viable counts of 10^7 CFU per gram at manufacture. The product functions as a shelf-stable or chilled protein delivery vehicle, with pH typically ranging 4.0-4.6, serving nutritional fortification and digestive health positioning in commercial applications. Flavored yogurt variants command the widest retail footprint across African supermarkets, though margin pools concentrate in Greek yogurt subcategories where protein density supports premium pricing. Tetra Pack configurations dominate rural and informal trade channels, while plastic container formats lead in urban supermarket and convenience store placements where refrigeration continuity is assured.
Nigeria's National Agency for Food and Drug Administration and Control enforces dairy fortification mandates that reshape product formulation requirements for imported and domestically manufactured yogurt alike. South Africa's Department of Health dairy regulations, aligned with CODEX standards, govern labeling claims and probiotic viability thresholds that determine market access for regional suppliers. Kenya's Dairy Board certification requirements for milk sourcing traceability add compliance layers that favor integrated processors over fragmented assemblers. Stakeholders must monitor evolving national fortification mandates and cold chain infrastructure commitments as the primary variables determining which product formats and price tiers achieve scalable distribution across the continent's heterogeneous retail landscape.
Market Dynamics
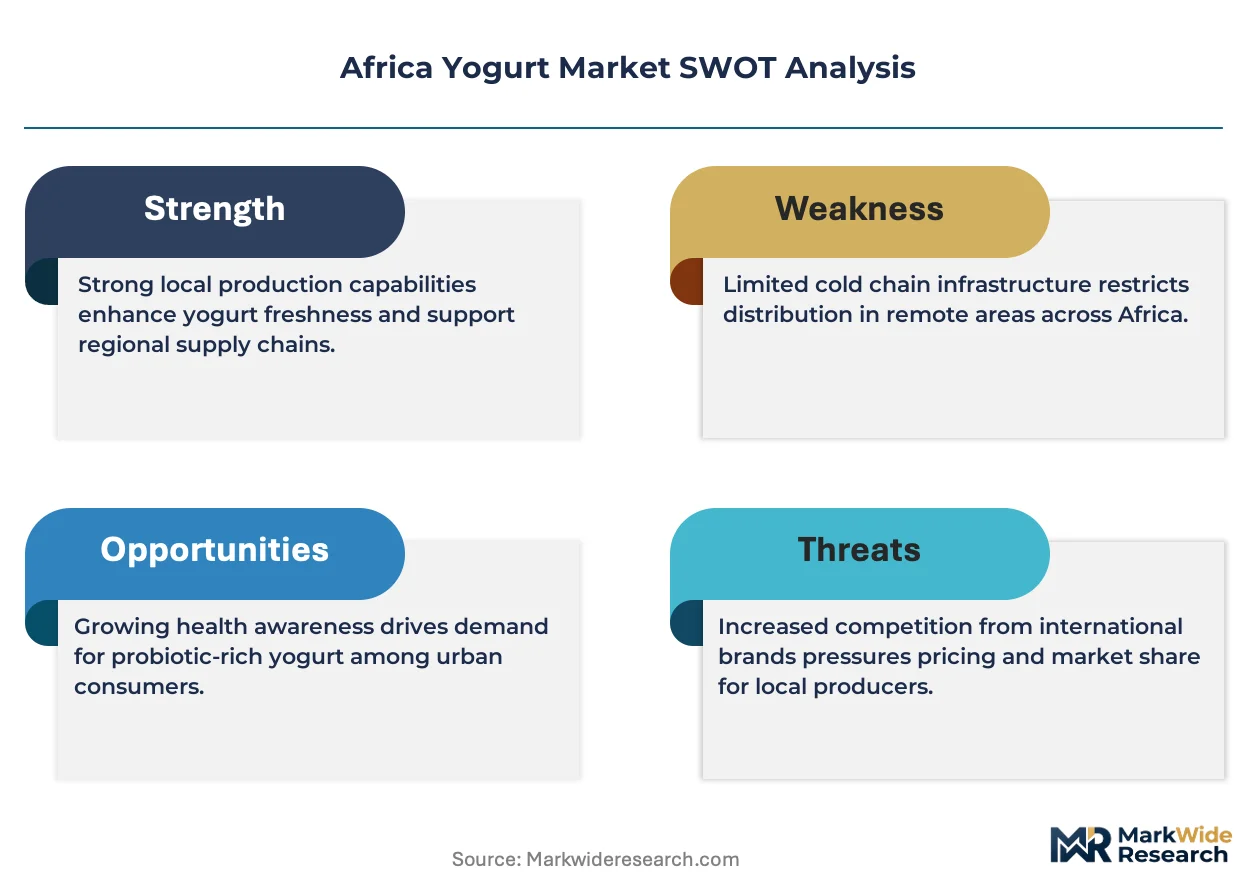
Cold chain infrastructure gaps and dairy fortification mandates are forcing manufacturers to reconfigure production footprints and distribution partnerships across African urban corridors. These structural pressures favor integrated processors with captive chilling capacity over fragmented assemblers dependent on third-party logistics.
Growth Catalysts
- NAFDAC Dairy Fortification Mandates:Nigeria's binding standards for micronutrient enrichment create compliant formulation pull-through that advantages certified domestic manufacturers over informal imports.
- Urban Household Protein Diversification:Middle-class consumers in Lagos, Nairobi, and Johannesburg are displacing traditional breakfast staples with chilled yogurt as a protein delivery vehicle.
- Retail Modernization:Supermarket expansion into secondary cities is compressing informal trade dependence and enabling branded product penetration.
Market Restraints
- Fresh Milk Input Volatility:Seasonal supply fluctuations in East African highlands compress processor margins and force formulation adjustments.
- Chilled Distribution Concentration:Third-party cold chain operators in West Africa create single-point failure risks for temperature-sensitive inventory.
- Powdered Milk Substitution:Reconstituted dairy alternatives in price-sensitive rural segments displace branded yogurt volume.
Strategic Opportunities
- Ethiopian Urban Expansion:Addis Ababa's underpenetrated modern retail channel offers first-mover positioning before infrastructure saturation.
- Probiotic Health Claims:CODEX-aligned viability thresholds enable premium positioning for products meeting Streptococcus thermophilus count standards.
- E-commerce Chilling Partnerships:Last-mile cold locker networks are emerging as a direct-to-consumer channel bypassing traditional retail gatekeepers.
Industry Challenges
- Microbiologist Talent Scarcity:Fermentation process control expertise remains concentrated in South Africa and Kenya, constraining quality scale-up elsewhere.
- NAFDAC Certification Timelines:Extended approval windows for new SKUs compress product launch velocity in Nigeria's largest addressable market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Yogurt Market |
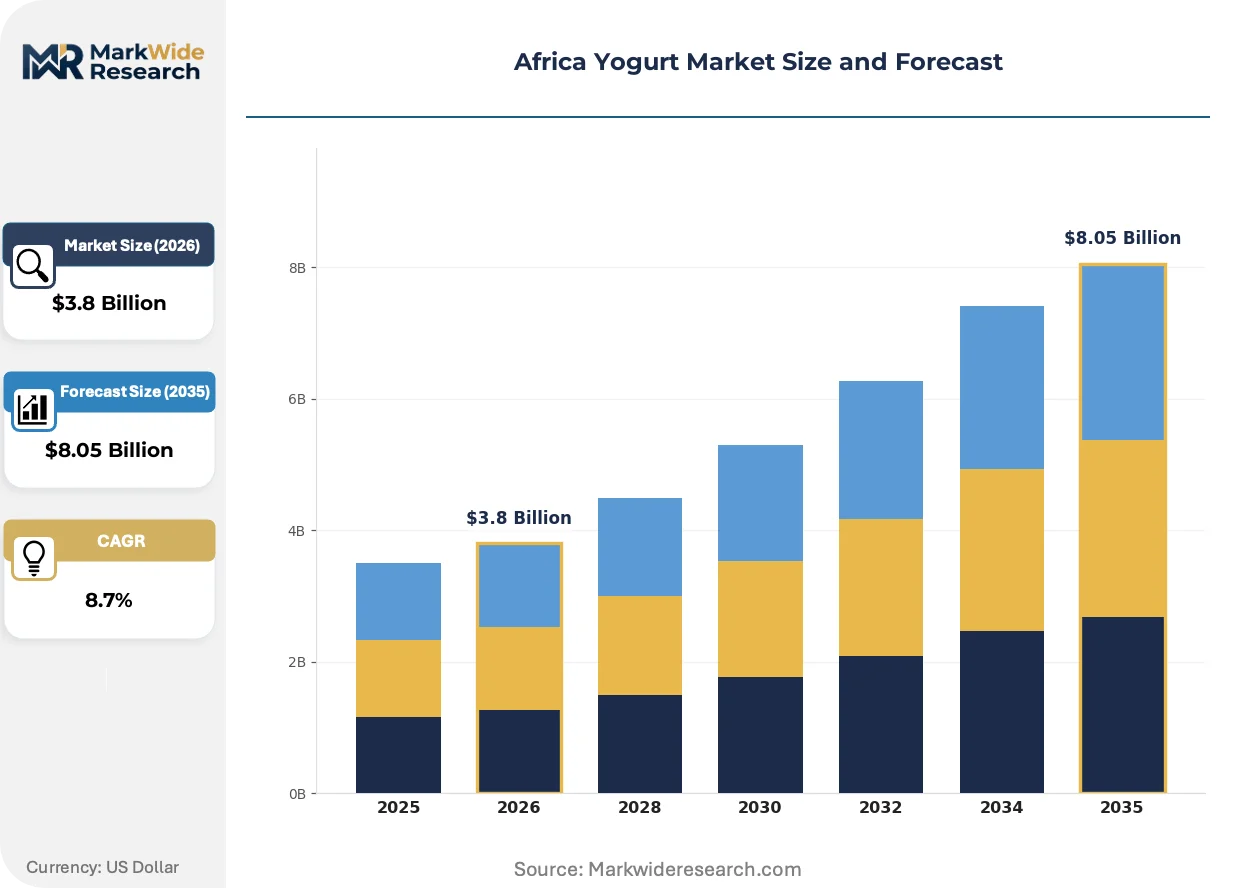
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Yogurt, Greek Yogurt, Flavored Yogurt, Organic Yogurt Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Shops End User: Households, Restaurants, Cafés, Institutional Buyers Packaging Type: Plastic Containers, Glass Jars, Tetra Packs, Pouches |
| Companies Covered | Viju Industries Nigeria Limited, Danone Southern Africa, Fage, Nestle, Chobani, Brookside Dairy, Chi Limited, Delamere, Soti Group, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Yogurt Market Strategic Shifts
Aseptic processing and modular chilling systems are compressing the capital threshold for yogurt manufacturing, enabling regional production dispersal beyond traditional dairy belt concentration. These shifts are fragmenting supply-side geography and shortening distribution radii.
Tetra Pak's aseptic filling technology is modularizing production economics for African processors. Mid-scale manufacturers in Ghana and Côte d'Ivoire are adopting these systems to bypass centralized chilling dependency. The technology is modularizing viable production footprints, enabling 10,000-liter daily outputs in secondary cities previously served by distant supply.
South Africa's Department of Health has aligned dairy regulations with CODEX probiotic viability standards, creating binding labeling thresholds for live culture claims. This regulatory convergence is compressing shelf-life extension strategies that rely on post-pasteurization treatment. Greek yogurt and high-protein variants face the tightest compliance scrutiny given their premium positioning on digestive health benefits.
Urban convenience stores are displacing traditional open-market dairy vendors as the primary yogurt purchase channel in Nigerian and Kenyan cities. Young professional households are consolidating weekly shopping into supermarket and convenience formats with assured refrigeration continuity. Lagos and Nairobi exhibit the most pronounced channel rotation, where informal wet-market yogurt sales are compressing to rural peripheries.
Africa Yogurt Market Segmentation
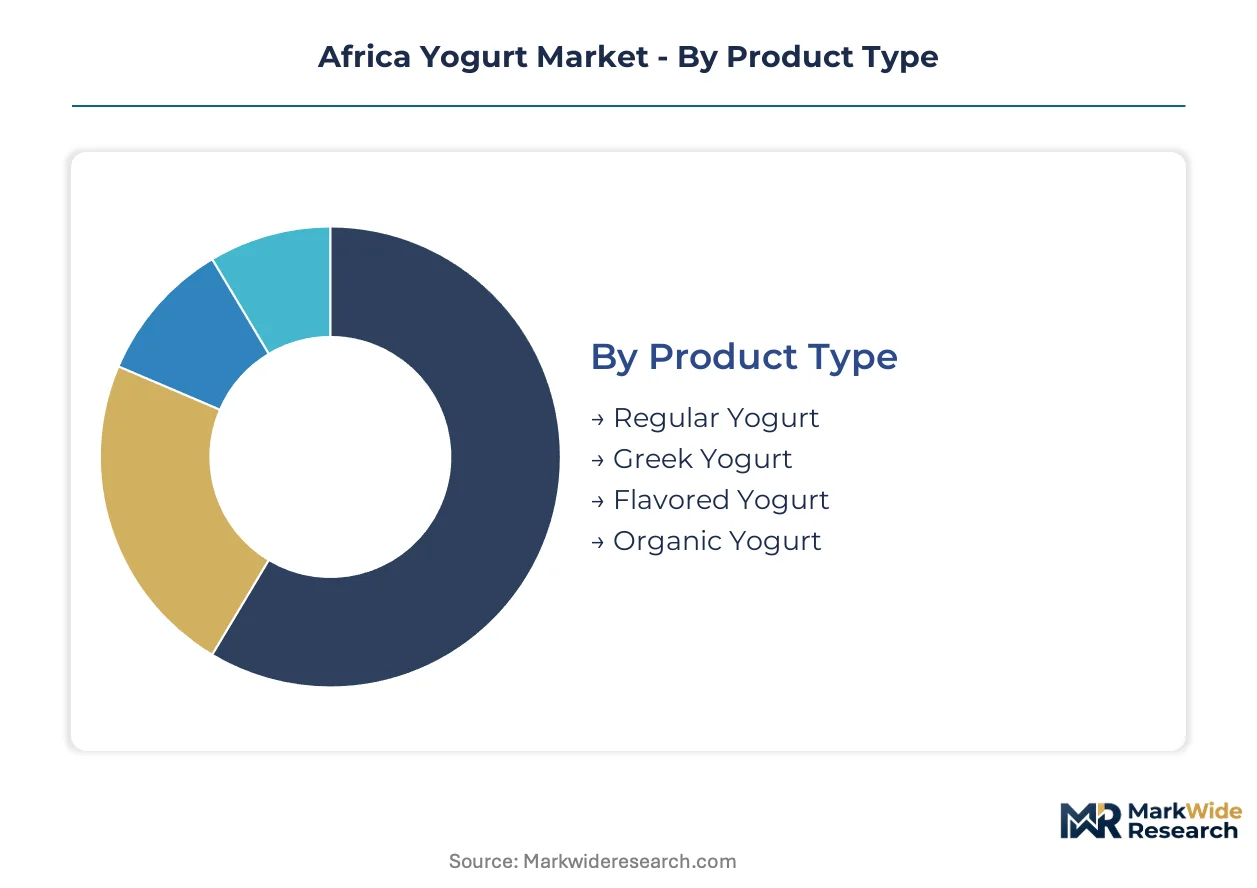
Yogurt manufacturers in Africa configure product portfolios around four intersecting dimensions that determine distribution economics and margin capture. Cold chain viability, retail format compatibility, and fortification compliance requirements vary sharply across these segment boundaries, forcing targeted production footprints rather than uniform national strategies.
Product Type:
Fermentation protocols and protein density specifications create distinct manufacturing investment profiles across yogurt categories.
- Regular Yogurt:Standard-set yogurt with 3-4% milk fat and live culture counts meeting CODEX minimums dominates volume in price-sensitive urban corridors. Lagos and Nairobi supermarkets move regular yogurt as a breakfast staple replacement, though margin compression from powdered milk reconstitution limits producer returns.
- Greek Yogurt:Strained yogurt achieving 8-10% protein density through whey separation commands premium shelf positioning in Johannesburg and Cape Town retail corridors. Danone Southern Africa anchors its portfolio here, leveraging chilled distribution continuity to justify price multiples over standard variants.
- Flavored Yogurt:Fruit-infused or vanilla formulations with added sugars and stabilizers occupy the widest retail footprint across African supermarkets. Chi Limited specializes in locally adapted profiles—ginger, hibiscus, and tropical fruit variants—where Western formulations underperform in Nigerian urban centers.
- Organic Yogurt:Certified organic milk sourcing with additive-free processing targets affluent households in Nairobi and Cape Town. Kenya's Dairy Board traceability requirements favor integrated processors with captive highland milk supply, constraining organic scale-up.
Regular yogurt leads on scale; Greek yogurt leads on momentum.
Distribution Channel:
Refrigeration continuity and consumer purchasing patterns fragment channel economics across Africa's heterogeneous retail landscape.
- Supermarkets:Branded chilled yogurt penetration concentrates in formal retail with assured cold chain integrity. Shoprite and Pick n Pay expansion into secondary South African and Nigerian cities is compressing informal trade dependence and enabling Greek yogurt and premium variant placement.
- Convenience Stores:Urban convenience formats with captive refrigeration are displacing open-market dairy vendors in Lagos and Nairobi. Young professional households consolidate weekly yogurt purchasing into these assured-cold formats, particularly for single-serve flavored and drinkable variants.
- Online Retailers:E-commerce platforms with last-mile cold locker partnerships are emerging as direct-to-consumer channels bypassing traditional retail gatekeepers. Jumia and Takealot pilot chilled delivery networks in Johannesburg and Lagos, though penetration remains constrained by delivery cost economics.
- Specialty Shops:Health-focused retailers and organic grocers target affluent consumers seeking probiotic-forward or organic-certified yogurt. These outlets concentrate in Cape Town's southern suburbs and Nairobi's Karen district, serving diaspora and upper-middle-class demand.
Supermarkets anchor volume capture; online retailers are expanding most quickly.
End User:
Consumption occasion and purchase frequency differentiate demand profiles across buyer categories.
- Households:Urban middle-class families in Lagos, Nairobi, and Johannesburg drive chilled yogurt adoption as protein diversification displaces traditional breakfast staples. Multi-pack purchasing and weekly supermarket trips characterize this segment.
- Restaurants:Food service procurement of bulk yogurt for marinades, dressings, and dessert applications concentrates in South African urban hospitality corridors. Greek yogurt's thickness commands premium placement in Cape Town and Johannesburg fine dining.
- Cafés:Smoothie and breakfast bowl applications favor high-protein Greek yogurt in Nairobi and Johannesburg specialty coffee chains. Java House and Vida e Caffè specify probiotic viability thresholds in procurement contracts.
- Institutional Buyers:Schools, hospitals, and corporate catering represent residual demand for long-life Tetra Pack yogurt in markets with refrigeration gaps. NAFDAC fortification mandates apply uniformly, constraining informal sourcing.
Households dominate absolute consumption; cafés are gaining share fastest.
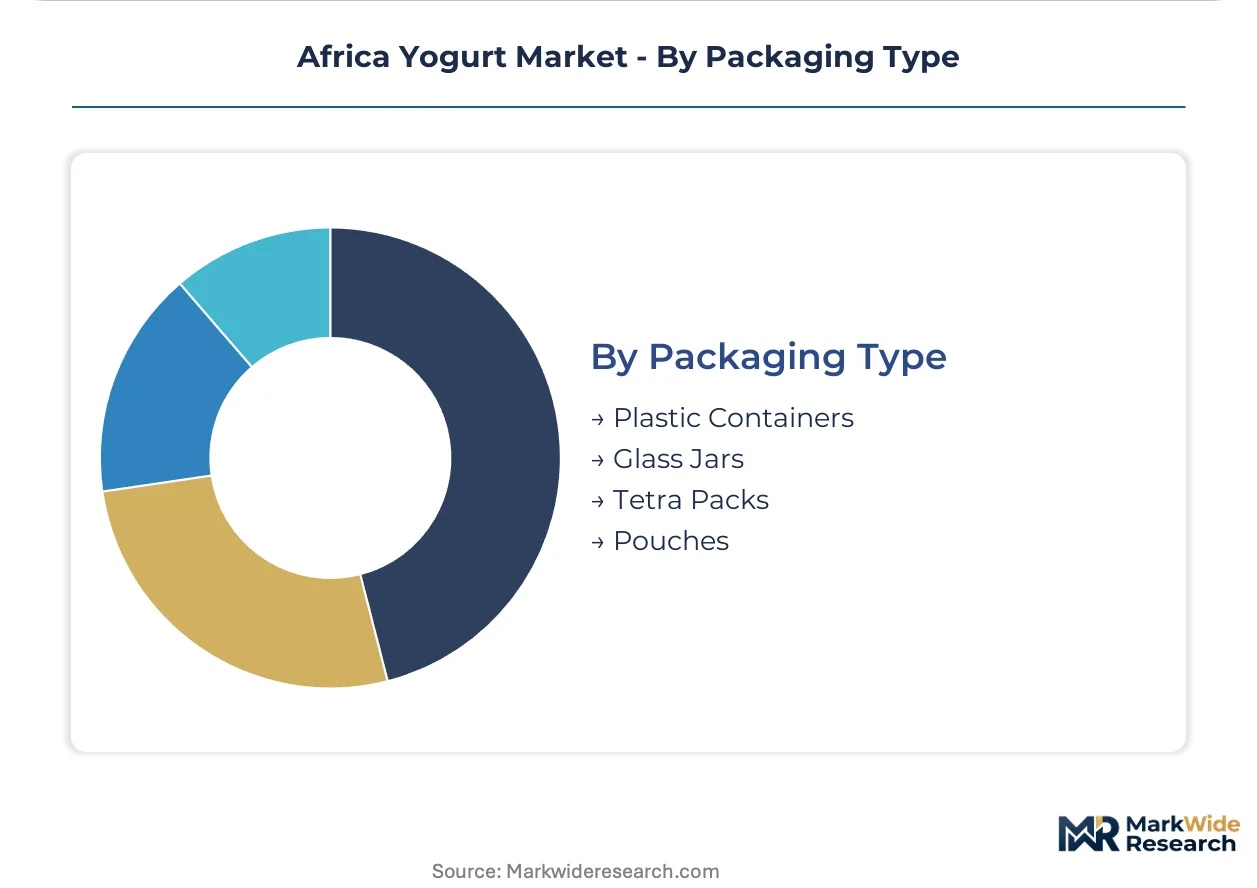
Packaging Type:
Material specifications and shelf-life engineering determine distribution radius and retail format compatibility.
- Plastic Containers:Polypropylene pots with tamper-evident lids lead urban supermarket and convenience store placement where refrigeration continuity is assured. Danone and Brookside Dairy favor this format for premium branded portfolios in Southern and East African cities.
- Glass Jars:Premium positioning for organic and artisanal yogurt variants targets environmentally conscious consumers in Cape Town and Nairobi. Returnable deposit systems and higher transport costs limit geographic scalability.
- Tetra Packs:Aseptic carton technology enables ambient distribution through rural and informal trade channels without cold chain dependency. Ghanaian and Ivorian processors adopt modular Tetra Pak filling systems to bypass centralized chilling infrastructure gaps.
- Pouches:Flexible film packaging for drinkable yogurt targets on-the-go consumption in Nigerian and Kenyan urban transport corridors. Lower per-unit cost and reduced refrigeration bulk favor convenience store placement.
Tetra Packs lead on reach; plastic containers lead on value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints across Africa as manufacturers migrate toward jurisdictions with streamlined compliance pathways and integrated cold chain infrastructure. Nigeria's NAFDAC mandates and South Africa's CODEX-aligned standards create divergent cost-of-compliance profiles that influence where regional supply concentrates.
Nigeria
Lagos and Abuja urban corridors drive chilled yogurt adoption as middle-class households displace traditional breakfast staples. NAFDAC dairy fortification mandates enforce micronutrient enrichment standards that advantage certified domestic processors over informal imports. Chi Limited anchors production in Lagos industrial zones with localized flavor development capabilities.
South Africa
Johannesburg and Cape Town retail modernization enables premium Greek yogurt placement through supermarket expansion. The Department of Health's CODEX-aligned probiotic viability thresholds govern labeling claims and constrain shelf-life extension strategies. Danone Southern Africa leverages its chilled distribution network across Gauteng and Western Cape provinces.
Kenya
Nairobi's urban convenience store channel rotation displaces open-market dairy vendors for assured-cold yogurt purchasing. Kenya Dairy Board certification requirements for milk sourcing traceability favor integrated processors with captive highland supply. Brookside Dairy maintains backward integration into Rift Valley milk sourcing to sustain cost advantages.
Ethiopia
Addis Ababa's underpenetrated modern retail channel offers first-mover positioning before infrastructure saturation. The Ethiopian Food and Drug Authority applies evolving dairy safety standards as formal sector participation expands. Modular Tetra Pak filling systems enable secondary city production dispersal beyond traditional supply concentration.
Ghana
Accra's emerging supermarket channel creates branded penetration opportunities as informal trade dependence compresses. National food safety agency fortification commitments reshape product formulation requirements for domestic and imported yogurt alike. Mid-scale manufacturers adopt aseptic processing technology to bypass centralized chilling infrastructure gaps.
Africa Yogurt Market Competitive Environment
Capacity expansion dominates the current landscape as integrated processors build captive chilling infrastructure to displace fragmented assemblers dependent on third-party logistics. The market structure concentrates around three tiers: multinational dairy conglomerates with continental distribution networks, regional integrated processors with backward milk supply control, and local specialists with adapted flavor portfolios. Strategic archetypes include scale-driven premium-positioned players, cost-optimized mass-market suppliers, and niche-focused local formulation experts. M&A activity and cold chain infrastructure partnerships constitute the dominant competitive moves reshaping market access.
Among Nigeria-based specialists, Viju Industries Nigeria Limited and Chi Limited occupy positions emphasizing localized product development for urban consumer preferences. Danone Southern Africa anchors the multinational tier with premium portfolio positioning across Southern African retail corridors. Brookside Dairy exemplifies the integrated regional processor archetype with captive Kenyan highland milk sourcing sustaining East African market presence.
| Leading Market Players |
|---|
| Viju Industries Nigeria Limited |
| Danone Southern Africa |
| Fage |
| Nestle |
| Chobani |
| Brookside Dairy |
| Chi Limited |
| Delamere |
| Soti Group |
| Others |
Value Chain & Pricing Dynamics
Backward integration into captive highland milk sourcing anchors both supply security and pricing power for integrated African yogurt processors. Danone Southern Africa and Brookside Dairy leverage this structural choice to compress input volatility and defend margin position against fragmented assemblers dependent on spot milk markets.
Pricing Analysis
Distributor margin layers in West African chilled networks absorb substantial cost before retail placement. Three-tier pricing structure across premium, standard, and economy levels stratifies around cold chain assurance and fortification certification. Price differentiation hinges on NAFDAC compliance status and volume scale commitments from supermarket buyers. Pricing pressure stems from powdered milk reconstitution in rural tiers, where informal substitutes erode branded volume. Households in Lagos and Nairobi exhibit highest price sensitivity, while Cape Town specialty shops tolerate premium multiples for organic-certified variants.
Supply Chain Analysis
Freight cost concentration in refrigerated last-mile legs constrains distribution radius for plastic-container formats. Supply concentrates in Kenya, South Africa, and Nigeria, where integrated processors draw from captive highland or peri-urban milk sheds. Raw material dependencies center on fresh milk supply, probiotic culture strains, and aseptic packaging materials. Single-source vulnerability runs through third-party cold chain operators in West Africa, where temperature excursion risks compound spoilage losses. Distribution runs through supermarket and convenience store channels in urban corridors, with Tetra Pack variants penetrating rural informal trade.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in African yogurt markets rests on cold chain cost compression and Greek yogurt premium-tier adoption. Aseptic processing technology dispersal and modular chilling systems enable capital-efficient scale-up beyond traditional dairy belt concentration.
For Market Incumbents: Cement chilled distribution continuity through captive logistics investment or exclusive third-party partnerships in Lagos and Johannesburg corridors. Defend against aseptic-format challengers by accelerating NAFDAC-compliant SKU velocity to compress approval timeline disadvantages. Prioritize backward integration into highland milk sourcing to buffer fresh input volatility and sustain cost advantages over fragmented assemblers. For New Entrants and Emerging Players: Begin with Ethiopian urban corridors where modern retail penetration remains underdeveloped and first-mover positioning precedes infrastructure saturation. Target drinkable yogurt pouches for Nigerian transport corridor convenience stores, where on-the-go consumption occasions outpace traditional sit-down formats. Pursue e-commerce cold locker partnerships in Johannesburg to bypass supermarket gatekeeper margins and capture direct-to-consumer premium. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale regional processors with captive chilling infrastructure because fragmented third-party logistics dependence creates acquisition synergies through network consolidation. Five-to-ten year viability favors integrated players with backward milk supply control and NAFDAC certification track records. Monitor NAFDAC approval velocity and Ethiopian retail modernization as inflection indicators for scalable market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Partnership | Danone Southern Africa leverages exclusive chilling agreements to anchor premium portfolio placement in Gauteng supermarkets. |
| Backward Integration into Milk Supply | Brookside Dairy's Rift Valley sourcing control buffers seasonal volatility and sustains East African cost advantages. |
| Localized Flavor Development | Chi Limited's ginger and hibiscus formulations capture Nigerian urban preferences where Western variants underperform. |
| Aseptic Processing Technology Adoption | Ghanaian mid-scale manufacturers deploy modular Tetra Pak systems to bypass centralized chilling infrastructure gaps. |
| E-commerce Cold Locker Network | Jumia's Johannesburg pilot enables direct-to-consumer delivery bypassing traditional retail margin extraction. |
Study Parameters
Multiple input streams — executive interviews with dairy processing plant managers, category buyer conversations at Shoprite and Pick n Pay, regulatory affairs discussions with NAFDAC and Kenya Dairy Board officials, and supply chain dialogues with cold chain logistics operators — were reconciled against secondary validation. Primary fieldwork encompassed fermentation process specialists, supermarket procurement leads, and Tetra Pak technical sales directors. Secondary sources included Kenya Dairy Board certification records, NAFDAC dairy fortification compliance filings, Nielsen retail audit data for Lagos and Nairobi, and customs trade statistics for milk powder imports. Bottom-up SKU-level volume builds and top-down category expenditure estimates were triangulated to anchor forecast integrity.
Data-stream reconciliation across product type, distribution channel, packaging format, and end-user segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation adjusted for infrastructure investment trajectories and regulatory enforcement intensity. Forecast inputs incorporated cold chain expansion timelines, NAFDAC certification velocity assumptions, and urban household protein diversification rates across Lagos, Nairobi, and Johannesburg metropolitan clusters.
Caveats apply where NAFDAC regulatory enforcement delays, Ethiopian political instability, or East African drought-induced milk supply contractions could materially shift the outlook. Forecasts embed assumptions about continued middle-class expansion and supermarket channel modernization that may revise under macroeconomic stress. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Sheep Milk Market
Dairy Products
India Dairy Market
Dairy Products
A2 Protein Milk Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Ghee Market
Dairy Products
South America Yogurt Market
Dairy Products
Organic Milk Protein Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Low-Fat Cheese Nutrition Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
Cheese Color Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Low-Calorie Butter Market
Dairy Products
China Dairy Market