
 Cashew Nut Butter Market | 2026-2036
Cashew Nut Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Cashew Nut Butter Market Analysis
The gap between premium and commodity tiers is realigning around ingredient sourcing transparency and processing methods. Bliss Nut Butters leverages single-origin supply chains to command shelf positioning in specialty retail. The J. M. Smucker Co. sustains mass-market volume through established grocery distribution networks. Once Again Nut Butter differentiates via employee-owned structure and long-standing organic certification credibility.
Cashew nut butter is a spreadable paste produced by grinding roasted or raw cashew kernels to a particle size typically below 20 microns, with optional additions of oils, salts, or sweeteners to achieve target viscosity and shelf stability; it serves as a functional ingredient in baking, a standalone condiment, and a protein-dense alternative to dairy-based spreads. Creamy variants dominate household penetration due to spreadability preferences, while organic certification captures disproportionate margin pools as consumers trade up for pesticide-free sourcing. Pouch and squeeze pack formats are gaining velocity in food service channels where portion control and reduced waste matter more than jar aesthetics.
The FDA governs allergen labeling and facility sanitation standards for nut butter production under FSMA, while USDA Organic certification shapes premium pricing eligibility and retail access; the EU's REACH framework and EFSA novel food assessments affect export-bound producers seeking European market entry. Stakeholders must track evolving organic certification costs and allergen threshold regulations as these determine which production scales remain economically viable.
Market Dynamics
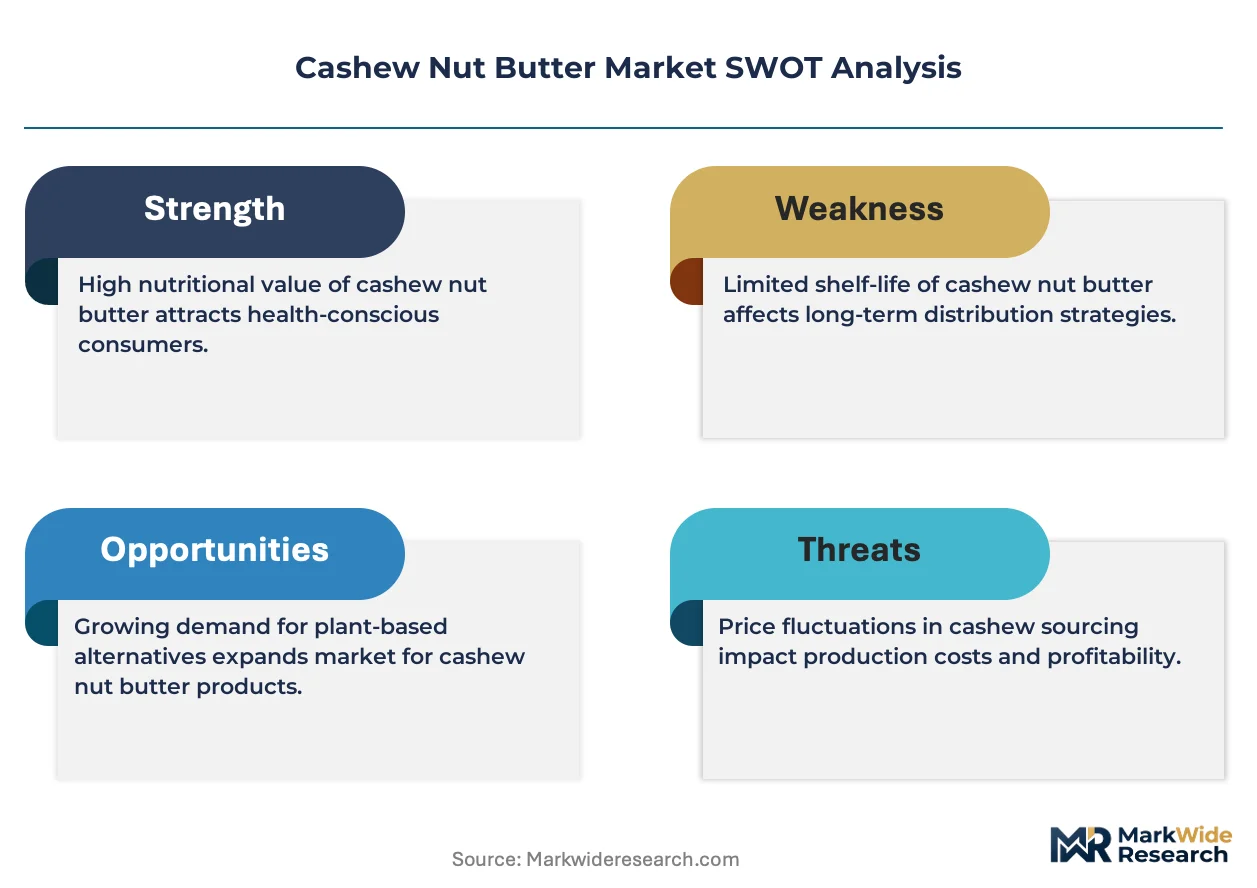
Clean-label certification requirements from USDA Organic and FDA allergen protocols are compressing margins for non-compliant processors while rewarding transparent supply chain operators with retail access and pricing power.
Growth Catalysts
- USDA Organic certification:Premium retail channels now mandate pesticide-free sourcing credentials, opening shelf space for compliant producers and locking out conventional alternatives.
- Direct-to-consumer channels:Specialty grocers and subscription platforms are expanding private-label cashew butter assortments, bypassing traditional distributor markups.
- Food service portion control:Pouch and squeeze pack formats reduce kitchen waste and labor costs, driving adoption in commercial baking and café operations.
Market Restraints
- Raw cashew kernel volatility:West African and Vietnamese supply concentration exposes processors to weather-driven price swings and currency fluctuation.
- FSMA facility compliance:FDA sanitation mandates require capital-intensive allergen segregation infrastructure that disadvantages small-scale producers.
- Peanut butter substitution:Lower-cost legume spreads retain dominant household penetration, limiting cashew butter volume expansion in price-sensitive segments.
Strategic Opportunities
- European REACH alignment:Export-bound producers satisfying EFSA novel food assessments can access premium EU retail channels with limited domestic competition.
- Functional ingredient positioning:Protein-fortified variants targeting sports nutrition and plant-based dairy alternatives command formulation partnerships with CPG brands.
- Single-origin storytelling:Traceable Indian or Brazilian sourcing narratives support three-tier pricing differentiation in specialty retail.
Industry Challenges
- Organic certification timelines:USDA transition periods and audit backlogs delay market entry for new suppliers by eighteen to thirty-six months.
- Roasting equipment retrofitting:Legacy facilities require thermal profile upgrades to achieve sub-20-micron particle consistency for creamy texture specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cashew Nut Butter Market |
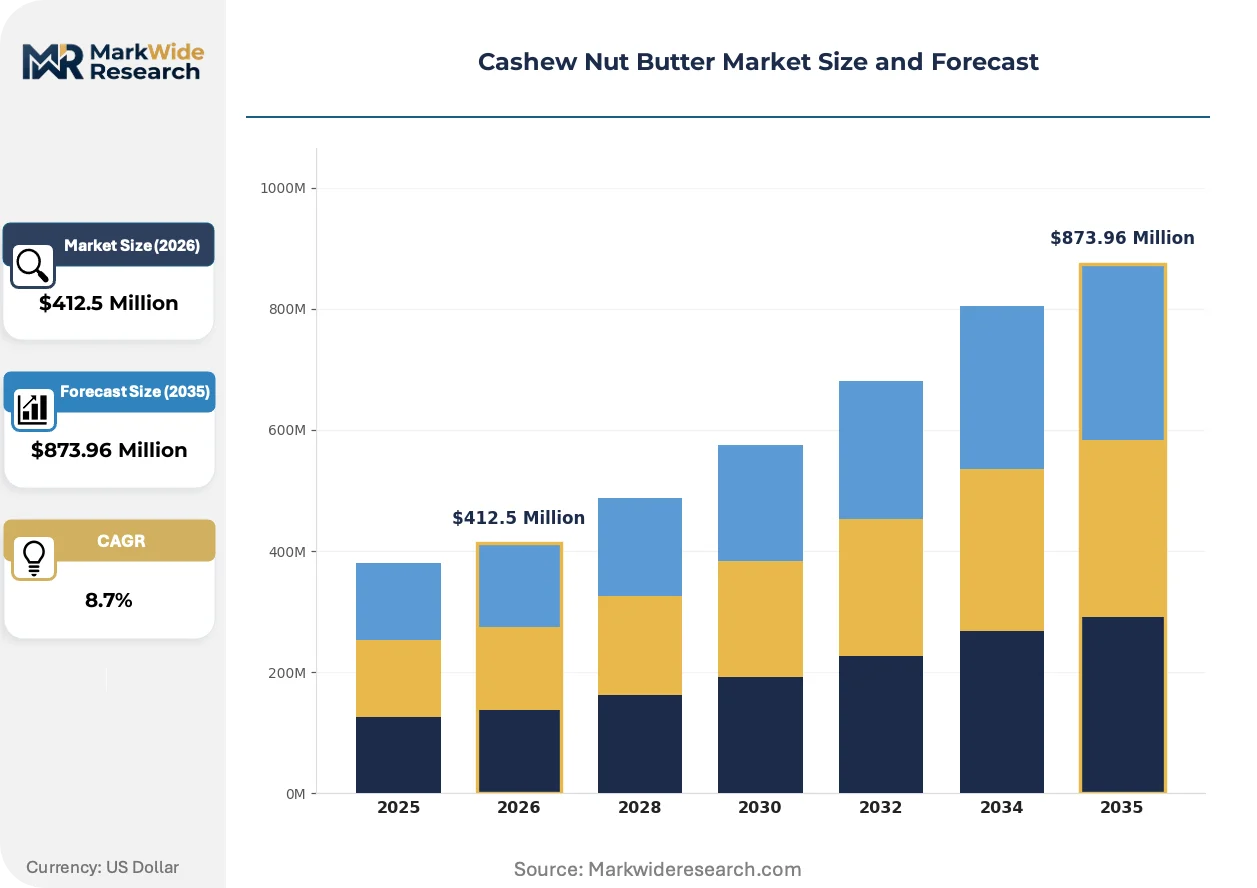
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creamy, Crunchy, Flavored, Organic End User: Households, Food Service, Health Stores, Restaurants Packaging Type: Jars, Pouches, Tubs, Squeeze Packs Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Bliss Nut Butters, East Wind Nut Butters, Hormel Foods Corporation, Nuflower Foods, Once Again Nut Butter, The J. M. Smucker Co., Pip & Nut, NuttZo Co, Hain Celestial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cashew Nut Butter Market Emerging Trajectories
Processing precision and packaging format innovation are compressing traditional quality-cost tradeoffs, enabling mid-tier producers to access premium positioning previously reserved for artisanal operators.
Stone grinding technology is expanding into mainstream production as equipment manufacturers scale down industrial systems for mid-cap facilities. Specialty retailers and co-manufacturers are adopting these systems to achieve particle size consistency without high-shear thermal degradation. This capability compression is expanding into private-label supply, eroding texture-based differentiation that previously separated premium and standard tiers.
EU F-Gas Regulation phase-down mandates are forcing refrigeration-dependent processors to retrofit cold-chain infrastructure or relocate to climates reducing energy intensity. Facilities in Northern Europe face accelerated capital deployment timelines to maintain organic certification storage requirements. German and Dutch producers are responding with solar-integrated climate control investments that double as marketing assets for sustainability credentials.
Ingredient transparency expectations are reshaping procurement relationships between retailers and cashew butter suppliers. Major grocery chains now require batch-level origin documentation and third-party pesticide testing, replacing spot-check audits with continuous verification systems. This behavioral shift is most visible in United States coastal metro markets where specialty grocers compete on clean-label assortment breadth.
Cashew Nut Butter Market Segmentation
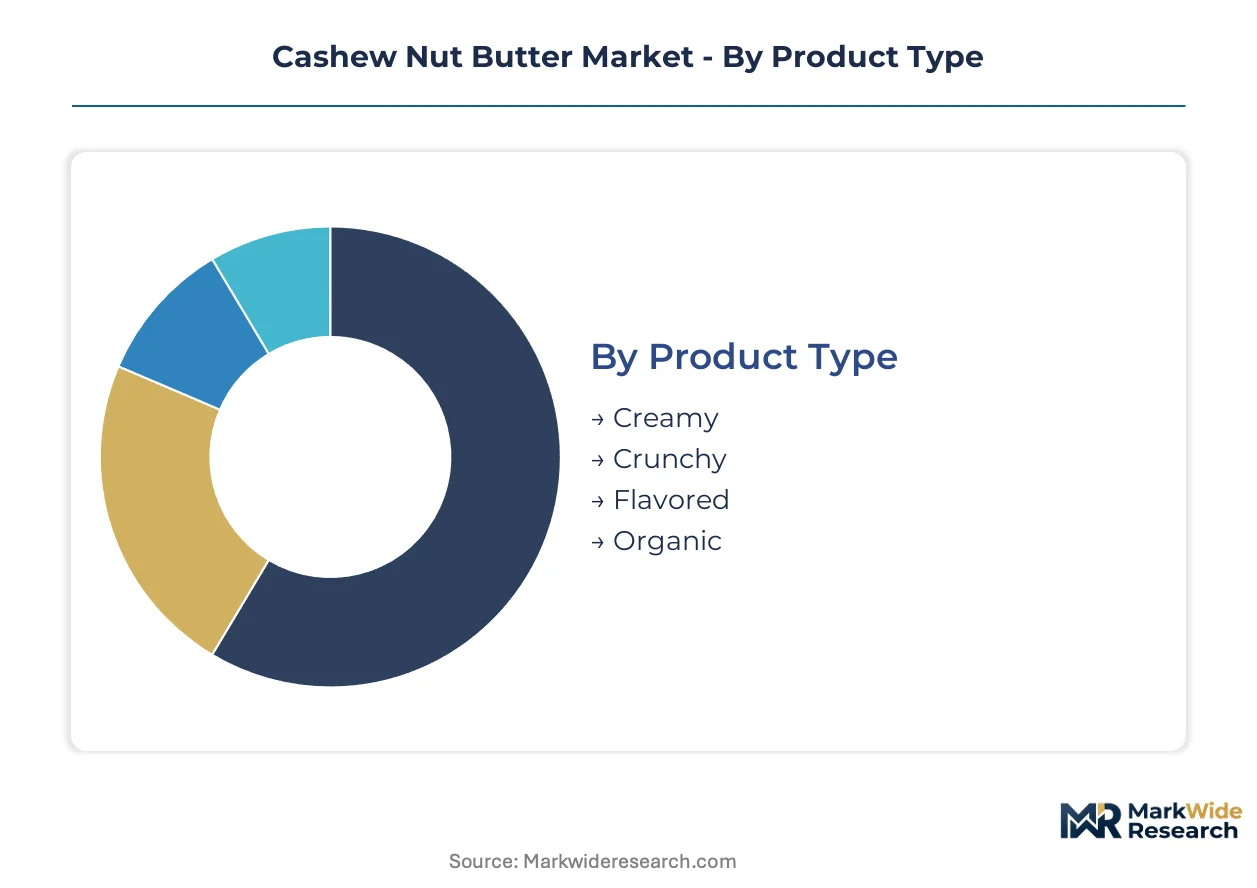
Cashew nut butter segmentation reveals how formulation standards, packaging innovation, and channel access requirements fragment addressable markets. Certification burdens and cold-chain infrastructure create divergent margin profiles across product tiers.
Product Type:
USDA Organic certification demands three-year transition periods and annual audits, while conventional variants face lower compliance thresholds but compressed retail pricing power.
- Creamy:Particle size specifications below 20 microns deliver spreadable viscosity for household toast and baking applications. United States households drive volume concentration, though FSMA facility compliance costs disadvantage small-batch producers.
- Organic:Pesticide-free sourcing credentials unlock specialty grocer shelf placement and subscription platform partnerships. USDA certification timelines stretch eighteen to thirty-six months, creating supply scarcity that supports three-tier pricing stratification.
- Crunchy:Textured formulations retain kernel fragments for sensory differentiation in artisanal positioning.
- Flavored:Vanilla, cinnamon, and chocolate infusions target café and direct-to-consumer channels.
Leading the category by volume: Creamy. Growing fastest: Organic.
End User:
Food service procurement prioritizes portion control and labor reduction over jar aesthetics, while health stores demand batch-level origin documentation.
- Food Service:Pouch and squeeze pack formats reduce kitchen waste and streamline portioning for commercial baking and café operations. United States metropolitan clusters concentrate demand, with Ecolab and similar sanitation auditors verifying HACCP compliance.
- Health Stores:Clean-label assortment breadth drives competitive positioning among specialty grocers in coastal United States markets. Third-party pesticide testing and single-origin storytelling command shelf space allocation.
- Households:Jar formats dominate pantry stocking for sandwich preparation and home baking.
- Restaurants:Bulk tub procurement supports menu integration as dairy-alternative spreads.
Highest margin capture: Health Stores. Steepest expansion trajectory: Food Service.
Packaging Type:
Cold-chain requirements for organic certification storage reshape format economics, with EU F-Gas Regulation phase-downs accelerating infrastructure investment timelines.
- Pouches:Flexible film construction reduces material cost and shipping weight for food service distributors. German and Dutch producers integrate solar climate control to satisfy organic storage mandates while marketing sustainability credentials.
- Squeeze Packs:Single-serve portions target sports nutrition and on-the-go consumption in United States direct-to-consumer channels. Portion precision supports subscription platform customization.
- Jars:Glass and PET containers retain household preference for pantry visibility and resealability.
- Tubs:Bulk formats serve restaurant and food manufacturing ingredient procurement.
Dominant by volume: Jars. Gaining share fastest: Squeeze Packs.
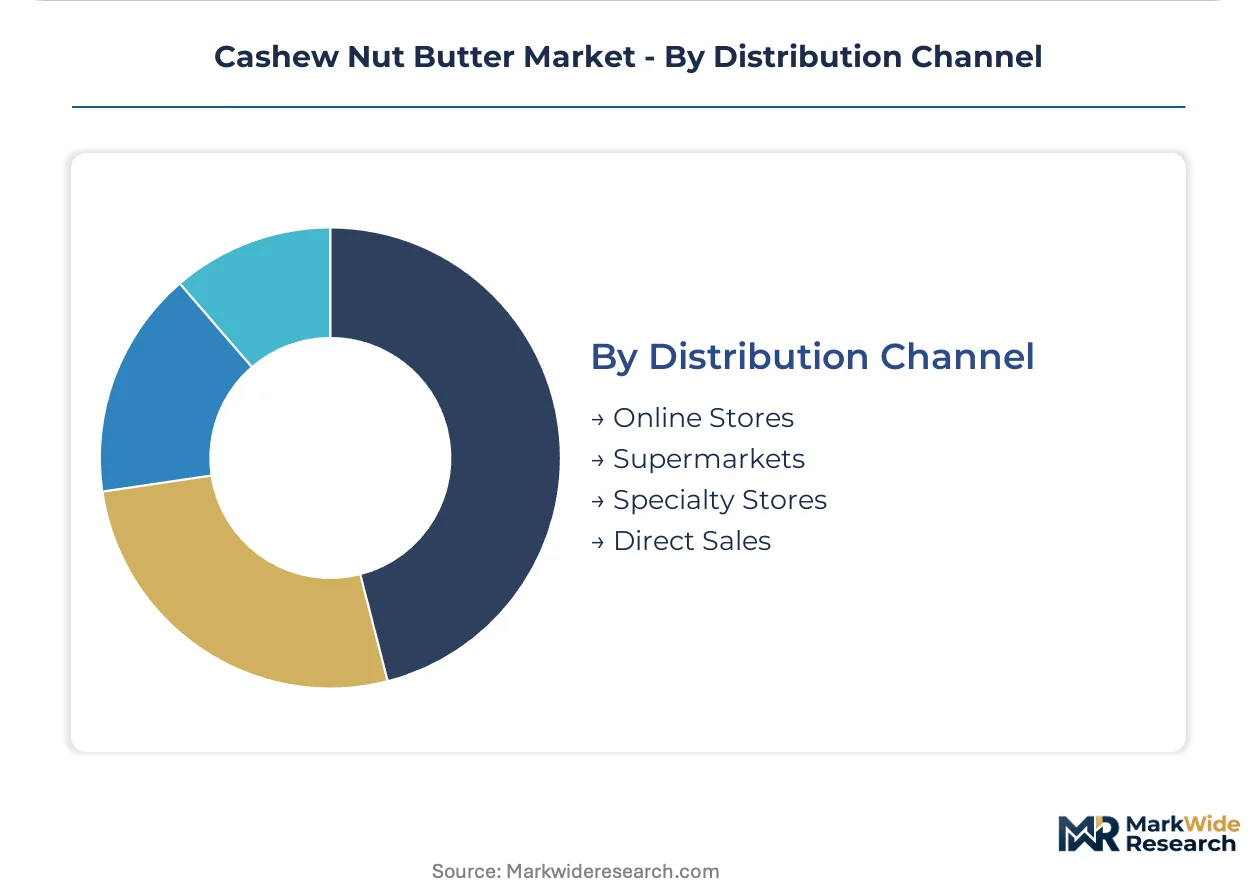
Distribution Channel:
Specialty store expansion and private-label proliferation are compressing traditional distributor markups, while online platforms bypass geographic constraints.
- Specialty Stores:Curated clean-label assortments in United States coastal metros compete on transparency depth rather than price. Whole Foods Market and regional equivalents mandate batch-level origin documentation.
- Online Stores:Subscription platforms and direct-to-consumer sites enable single-origin storytelling and recurring revenue capture. Amazon and Thrive Market expand private-label cashew butter assortments.
- Supermarkets:Mass-market volume sustains through established grocery distribution networks with conventional placement.
- Direct Sales:Farmers markets and brand-owned storefronts support premium positioning and customer education.
Highest volume throughput: Supermarkets. Most rapid channel expansion: Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco Bay Area specialty grocers anchor clean-label demand concentration, with coastal metro clusters across multiple countries now mandating batch-level origin documentation for cashew butter procurement.
United States
Specialty retailers in New York and Los Angeles drive premium-tier velocity through subscription platform partnerships. FDA FSMA sanitation mandates compress margins for non-compliant processors while rewarding transparent operators. Brooklyn-based co-manufacturers are retrofitting stone grinding equipment to achieve sub-20-micron particle specifications.
Germany
Organic certification storage requirements intersect with EU F-Gas Regulation phase-downs, accelerating solar-integrated climate control investments. EFSA novel food assessments shape export eligibility for German processors seeking premium retail placement. Hamburg-area distributors are consolidating private-label supply relationships with Vietnamese cashew kernel importers.
Netherlands
Rotterdam port logistics clusters facilitate West African cashew kernel transshipment for European processing. REACH framework compliance costs filter out small-scale entrants from export-bound production. Eindhoven-region cold-chain facilities are deploying ammonia-based refrigeration to satisfy organic storage mandates ahead of regulatory deadlines.
United Kingdom
London metropolitan specialty grocers compete on clean-label assortment breadth, requiring third-party pesticide testing documentation. Post-Brexit border protocols add compliance layers for EU-sourced organic kernels. Bristol-based direct-to-consumer brands are leveraging single-origin Indian sourcing narratives for premium positioning.
Vietnam
Binh Phuoc province processing clusters dominate raw cashew kernel output, supplying global butter manufacturers. Currency fluctuation and weather-driven crop volatility expose contract pricing structures. Ho Chi Minh City exporters are vertically integrating into roasting and paste production to capture margin pools previously lost to foreign processors.
Cashew Nut Butter Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. The vendor base separates into mass-market volume operators, mid-cap organic specialists, and artisanal single-origin players. Three archetypes dominate: established CPG conglomerates sustaining grocery distribution density, employee-owned cooperatives leveraging certification credibility, and direct-to-consumer brands exploiting traceability storytelling. Dominant competitive moves include strategic co-manufacturing partnerships and backward integration into kernel sourcing.
Within the employee-owned cooperative archetype, Once Again Nut Butter exemplifies long-standing organic certification credibility. Among mass-market CPG operators, The J. M. Smucker Co. and Hormel Foods Corporation occupy positions sustained through established grocery network density. On the artisanal-premium vector, Bliss Nut Butters represents single-origin supply chain differentiation targeting specialty retail shelf allocation.
| Leading Market Players |
|---|
| Bliss Nut Butters |
| East Wind Nut Butters |
| Hormel Foods Corporation |
| Nuflower Foods |
| Once Again Nut Butter |
| The J. M. Smucker Co. |
| Pip & Nut |
| NuttZo Co |
| Hain Celestial |
| Others |
Supply Flow & Price Mechanics
Raw cashew kernel costs originating in Vietnamese and West African growing regions cascade through three distinct pricing tiers before reaching United States retail shelves, with organic certification premiums widening spreads between conventional and specialty grades. Currency fluctuation in Vietnamese dong and West African franc zones transmits directly into processor contract negotiations, compressing margins for non-integrated operators unable to hedge commodity exposure.
Pricing Analysis
Value-based pricing anchored to USDA Organic certification status separates premium shelf placement from mass-market commodity positioning. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and single-origin traceability depth, with pesticide-free credentials commanding disproportionate margin capture. Cost compression in conventional tiers is intensifying because peanut butter substitution retains price-sensitive household penetration. Health stores demonstrate least price sensitivity due to clean-label assortment competition, while mass-market supermarkets face acute substitution pressure from lower-cost legume spreads.
Supply Chain Analysis
USDA Organic certification and FDA FSMA facility qualification gating filter processor participation, advantaging capital-heavy operators with audit-ready infrastructure. Supply concentrates in Vietnam, India, and Ivory Coast for raw kernel sourcing, with Binh Phuoc province clusters dominating global output. Processing draws from roasting equipment, cold-chain storage, and particle-size milling technology as critical inputs. Single-source vulnerability in West African weather-dependent crop cycles exposes contract pricing to harvest volatility. Distribution runs through specialty grocer networks and direct-to-consumer platforms for premium tiers, conventional grocery distributors for mass-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from FDA FSMA compliance costs is forcing sub-scale processors toward acquisition or exit, rewarding operators with certified infrastructure and backward-integrated kernel sourcing.
For Market Incumbents: Deploy stone grinding equipment retrofitting as a texture-quality lever to defend specialty shelf positioning against mid-tier private-label encroachment. Deepen backward integration into Vietnamese or Indian kernel sourcing to secure supply continuity against currency-driven price spikes. FSMA facility mandates threaten smaller competitors with capital-intensive allergen segregation requirements. For New Entrants and Emerging Players: Subscription platform direct-to-consumer routes offer lowest barrier-to-entry for single-origin storytelling and recurring revenue capture. Target food service pouch and squeeze pack segments where portion control demand outpaces established supply. White-space exists in European REACH-aligned export production with limited domestic competition. Launch through Amazon or Thrive Market private-label partnerships to bypass traditional distributor gatekeeping. For Investors and Strategic Acquirers: USDA Organic certification audit backlogs clearing is the leading indicator that supply scarcity premiums will compress, favoring early positioning in transition-stage processors. Long-term viability hinges on cold-chain infrastructure ownership and solar-integrated climate control assets ahead of EU F-Gas phase-down deadlines. Target acquisition archetype: mid-cap organic specialists with certified facilities and incomplete geographic coverage. Watch Vietnamese vertical integration announcements as margin-pool inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kernel Sourcing | Vietnamese or Indian origin control secures supply continuity against currency and weather volatility. |
| Stone Grinding Equipment Deployment | Sub-20-micron particle consistency achieves creamy texture specifications without thermal degradation. |
| Direct-to-Consumer Channel Launch | Subscription platforms bypass distributor markups and enable single-origin premium positioning. |
| EU REACH Alignment Investment | EFSA novel food assessment completion unlocks premium European retail channels with limited competition. |
| Solar-Integrated Climate Control | German and Dutch organic storage mandates drive sustainability credential marketing alongside compliance. |
Methodological Framework
Multi-period observation of cashew kernel import volumes, organic certification issuance rates, and specialty grocer SKU expansion anchored the trend analysis, supplemented by interviews with cashew butter brand managers, category buyers at Whole Foods Market and regional equivalents, co-manufacturer operations directors, Vietnamese kernel export traders, and FDA compliance consultants. Secondary validation drew from USDA National Organic Program audit databases, FDA FSMA facility registration records, customs trade data, and SEC filings of publicly traded CPG parents. Bottom-up segment sizing triangulated against top-down market value estimates.
Segment-weighting across product type, end user, packaging format, and distribution channel dimensions structured the analytical framework. CAGRs were derived from regression analysis of historical volume trajectories applied to projected certification penetration and channel shift assumptions. Industry-specific forecast inputs included organic transition acreage timelines and EU F-Gas Regulation phase-down implementation schedules.
Inputs from USDA audit databases and Vietnamese customs records were available through the study window; gaps in private-label contract pricing introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding certification adoption curves and kernel price volatility. A model refresh is warranted upon material change in FDA allergen threshold regulations or Vietnamese export policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
Australia Fox Nuts Market
Nuts and Seeds
North America Peanut Butter Market
Nuts and Seeds
Pecans Market
Nuts and Seeds
Maca Market
Nuts and Seeds
Europe Cashew Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Carob Extract Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
North America Hazelnut Market
Nuts and Seeds
Almond Market
Nuts and Seeds
Nuts and Nut Products Market
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Nut Ingredients Market
Nuts and Seeds
China Fox Nuts Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market