
 Grass Fed Beef Market | 2026-2036
Grass Fed Beef Market Size, Share, and Industry Trends Forecast 2026-2036
Grass Fed Beef Market Outlook
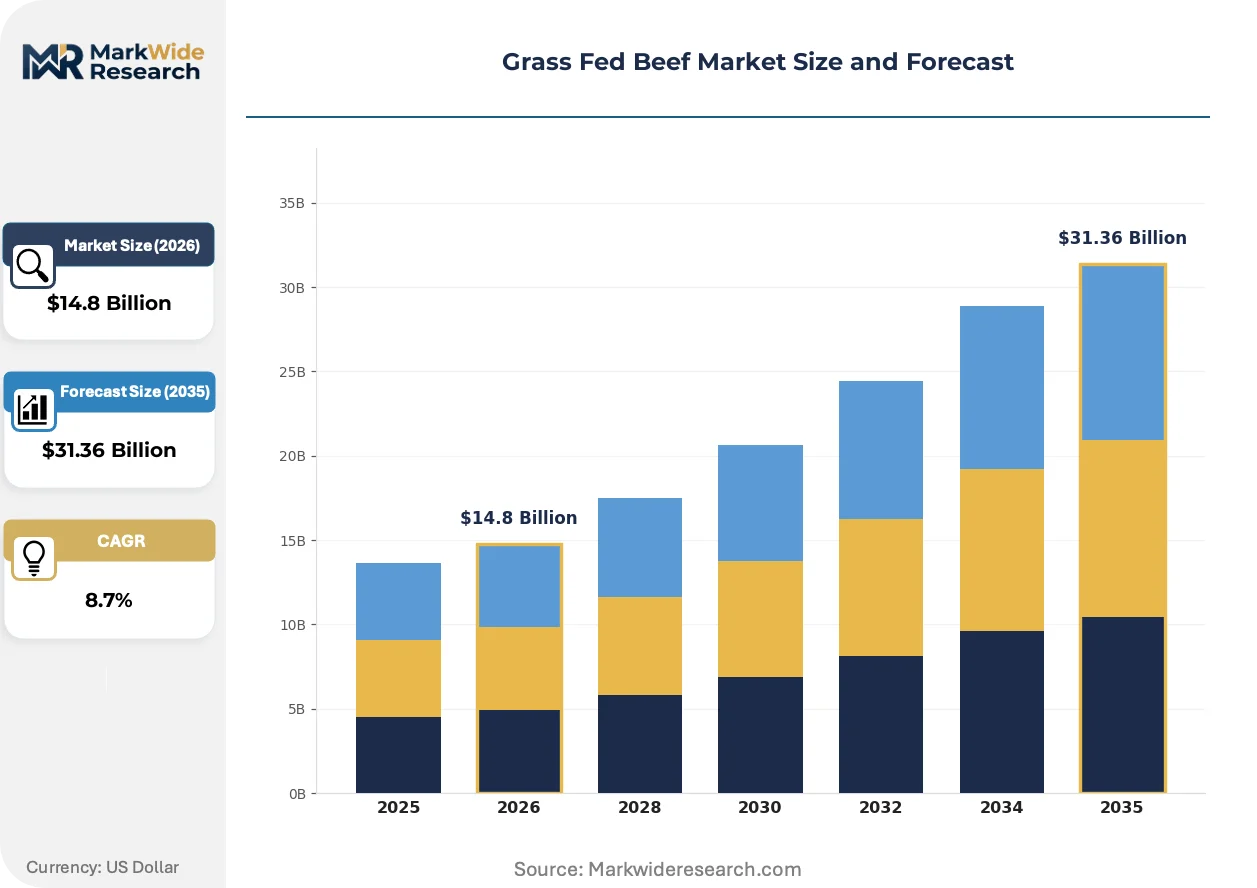
Direct-to-consumer subscription revenue is reconfiguring margin distribution across the grass fed beef value chain. JBS Foods leverages its integrated cattle sourcing networks to secure consistent grass fed volumes at scale. Australian Agricultural Company Limited anchors premium export positioning through dedicated pasture-to-plate traceability systems. Strauss Brands differentiates via specialized Midwest processing capacity dedicated to never-ever antibiotic programs.
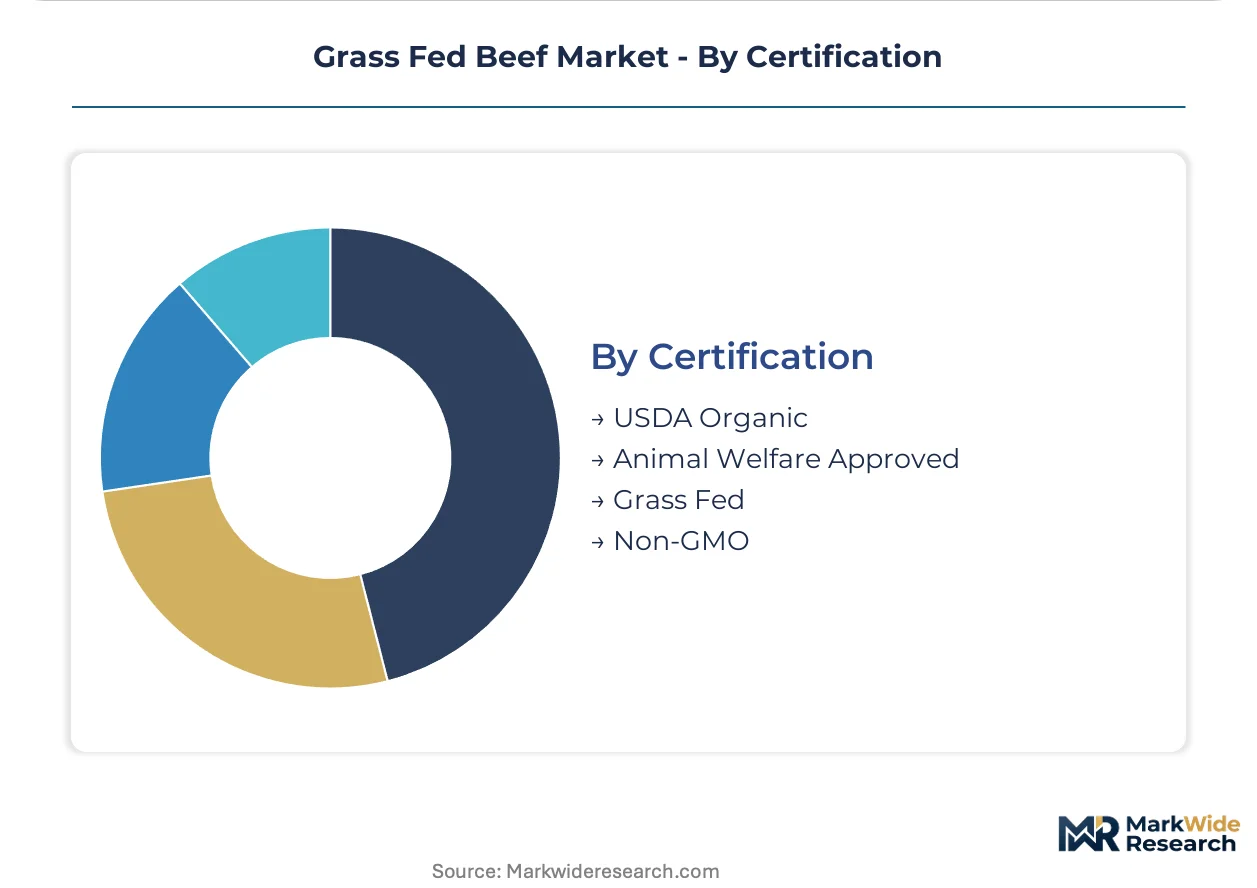
Grass fed beef derives from cattle finished entirely on pasture and forage, with no grain supplementation, and must meet minimum marbling thresholds of Modest or higher under USDA grading to qualify for select premium retail tiers. The product serves commercial buyers seeking differentiated protein with verifiable origin claims and omega-3 fatty acid profiles distinct from conventional grain-finished alternatives. Ground beef commands the largest volume share across product type segments due to price accessibility and versatility in both retail and food service applications. Online retail distribution channels represent the fastest-expanding route to market, though supermarkets still capture the dominant share of household purchases through dedicated natural meat cases. Certification segments show Animal Welfare Approved and Grass Fed designations commanding shelf price premiums, while USDA Organic remains the most widely recognized consumer-facing standard.
The USDA Agricultural Marketing Service governs grass fed label claims through its standard requiring continuous pasture access and 100% forage-based diets, with noncompliance triggering enforcement via the Food Safety and Inspection Service. Australia's Department of Agriculture, Fisheries and Forestry administers export certification protocols that determine market access eligibility for producers like Australian Agricultural Company Limited. Stakeholders must monitor evolving definition standards across jurisdictions, as regulatory divergence between domestic label requirements and import country specifications creates compliance complexity for multinational supply chains.
Market Dynamics
Direct-to-consumer subscription channels are restructuring margin capture across the grass fed beef value chain, compressing traditional wholesale markups while rewarding producers with verifiable pasture-to-plate traceability systems.
Growth Catalysts
- USDA Grass Fed Label Standard:The Agricultural Marketing Service's enforcement through FSIS creates definitional clarity that reduces consumer confusion and enables premium shelf positioning for compliant products.
- Food Service Procurement:Restaurant operators are expanding grass fed beef menus as clean-label protein demand from health-conscious diners accelerates kitchen reformulation cycles.
- Australian Export Certification:The Department of Agriculture, Fisheries and Forestry's protocols grant premium market access to pasture-finished cattle, anchoring supply from Queensland and New South Wales rangelands.
Market Restraints
- Input Cost Volatility:Pasture rental rates and forage seed prices fluctuate with regional drought cycles, compressing margins for producers without integrated land holdings.
- Supply Concentration Risk:Premium grass fed finishing capacity clusters in specific temperate grassland corridors, creating geographic vulnerability to climate disruption.
- Grain-Finished Substitution:Conventional beef's price accessibility and established distribution infrastructure retain volume dominance in price-sensitive retail tiers.
Strategic Opportunities
- Online Retail Expansion:E-commerce platforms enable direct producer-to-consumer relationships that capture full retail margin and build subscription recurring revenue.
- Regenerative Agriculture Incentives:USDA conservation programs and carbon credit markets reward rotational grazing practices that improve soil carbon sequestration on grass fed operations.
- Blockchain Traceability Convergence:Distributed ledger technology integrated with IoT pasture sensors enables real-time verification of continuous grazing claims for export markets.
Industry Challenges
- Veterinary Skill Shortage:Specialized knowledge in preventive herd health for antibiotic-free operations remains scarce in rural veterinary networks.
- Certification Timeline Compression:Animal Welfare Approved and Grass Fed audits require 12-18 month compliance windows that delay market entry for converting operations.
- Cold Chain Reconfiguration:Dedicated processing and distribution infrastructure for never-ever programs demands capital deployment that smaller producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grass Fed Beef Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Beef, Steaks, Roasts, Ribs Distribution Channel: Online Retail, Supermarkets, Farmers' Markets, Butcher Shops End User: Restaurants, Households, Food Service, Meal Kit Companies Certification: USDA Organic, Animal Welfare Approved, Grass Fed, Non-GMO |
| Companies Covered | JBS Foods, Tyson Foods, Hormel Foods Corporation, Australian Agricultural Company Limited, Strauss Brands, Panorama, Verde Farms, Creekstone Farms, Perdue Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grass Fed Beef Market Strategic Shifts
Digital verification systems and evolving procurement architectures are compressing information asymmetries between pasture operations and end buyers while enabling new forms of value capture.
Pasture-based sensor networks combined with satellite imagery analytics are digitizing grazing management decisions. Mid-scale producers in the Midwest and Great Plains are deploying these systems to optimize rotational patterns and document continuous forage access for certification audits. The technology is digitizing compliance documentation workflows that previously required manual record-keeping, reducing audit preparation labor while strengthening claim defensibility against regulatory scrutiny.
The EU Green Deal's Farm to Fork Strategy is tightening import requirements for livestock products entering European markets. This regulatory pressure is forcing export-oriented Australian and South American producers to adopt enhanced traceability systems that document antibiotic-free and hormone-free production histories. Premium chilled beef shipments to Rotterdam and Hamburg now face heightened documentation thresholds that favor integrated supply chains with captive processing capacity.
Subscription-based meat box services are displacing traditional supermarket procurement for affluent household segments. These direct channels capture consumers seeking origin transparency and consistent quality who previously purchased through natural meat cases. The shift concentrates most visibly in coastal metropolitan areas where delivery logistics density supports cold-chain economics at competitive price points.
Grass Fed Beef Market Segmentation
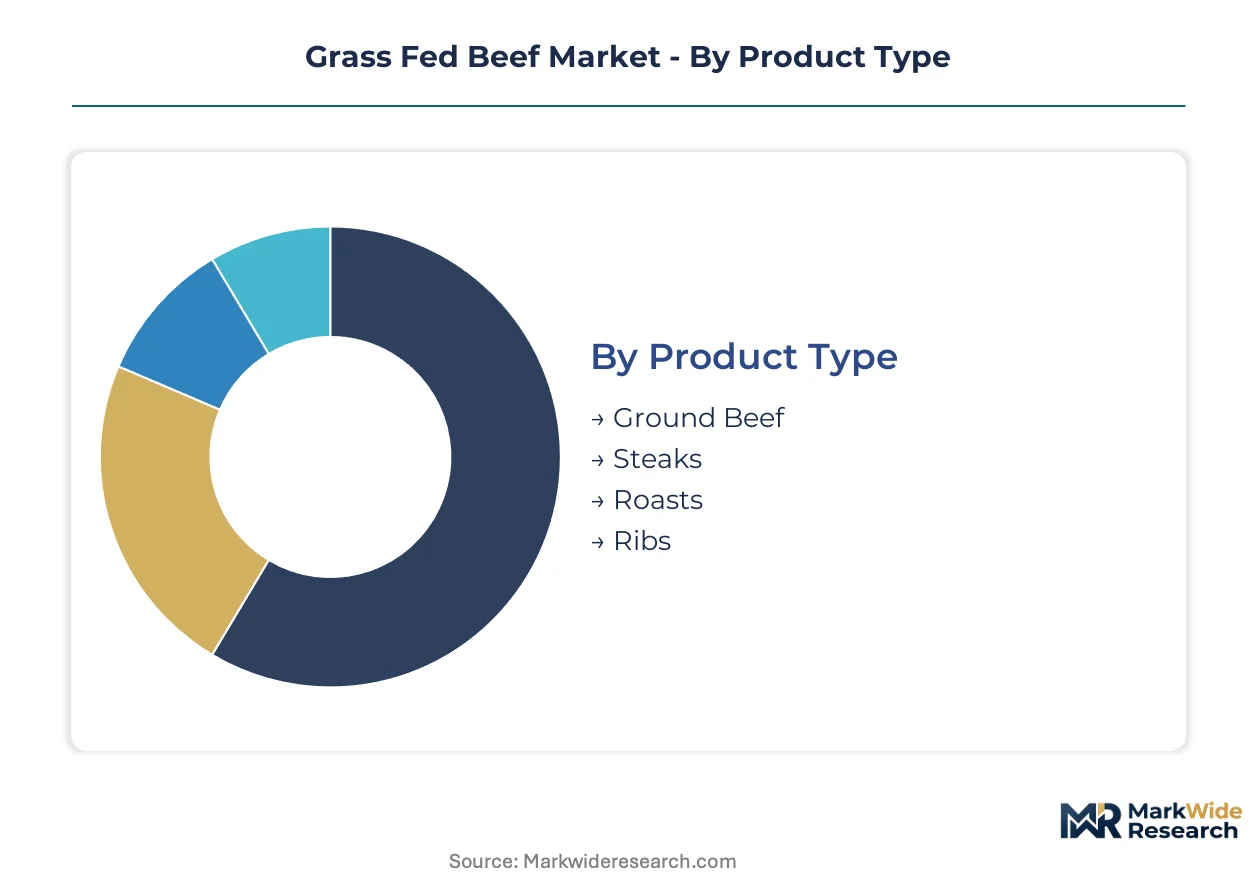
Grass fed beef segmentation reveals divergent margin profiles across product cuts, channel economics, and certification tiers. Understanding these structural differences enables producers to prioritize capacity allocation and pricing architecture.
Product Type:
Ground beef turns inventory fastest through retail and food service channels, while whole-muscle cuts require extended aging and specialized fabrication. Steaks and roasts carry longer production cycles tied to seasonal demand patterns.
- Ground Beef:Comprises trim and whole-muscle grind from chuck, round, and sirloin subprimals with fat content specifications typically ranging 15-20%. Demand concentrates in quick-service restaurant chains and value-oriented retail tiers where price accessibility drives volume. This segment absorbs the majority of carcass utilization, making it the margin anchor for processor economics.
- Steaks:Includes ribeye, strip loin, tenderloin, and sirloin cuts graded Modest or higher under USDA marbling standards. Premium steakhouses and direct-to-consumer subscription services concentrate demand here, with consumers paying shelf price premiums for verifiable grass fed origin claims and omega-3 fatty acid differentiation.
- Roasts:Encompasses chuck, brisket, and round cuts suited for slow-cooking applications. Meal kit companies and seasonal holiday procurement drive concentrated demand periods.
- Ribs:Covers back ribs and short ribs with distinct preparation requirements for barbecue and braising applications. Regional smokehouse chains and specialty retailers capture disproportionate share.
Ground beef dominates installed base. Steaks represent where expansion concentrates as premium retail and food service channels scale procurement.
Distribution Channel:
Channel selection determines margin capture intensity and customer relationship depth. Direct channels reward traceability investments while traditional retail optimizes throughput velocity.
- Online Retail:Subscription platforms and e-commerce marketplaces enable producer-to-consumer relationships that bypass wholesale markups. Cold-chain logistics density in metropolitan corridors supports competitive delivery economics, with recurring revenue models strengthening customer lifetime value for operations with verifiable pasture-to-plate documentation.
- Supermarkets:Natural meat cases in conventional and specialty grocery chains remain the dominant household purchase venue. Dedicated shelf space in retailers like Whole Foods Market and regional cooperatives commands slotting fees that favor scaled suppliers with consistent volume commitments.
- Farmers' Markets:Direct producer sales enable premium pricing through face-to-face origin storytelling. Seasonal throughput limits scale but builds brand equity for farm-direct operations.
- Butcher Shops:Independent meat markets and craft butcher counters provide specialized fabrication and custom cutting services. Urban coastal markets concentrate demand where consumers seek relationship-based purchasing.
Supermarkets anchor volume throughput. Online retail is climbing the fastest as subscription models displace traditional procurement for affluent segments.
End User:
End-user segmentation separates volume-driven food service procurement from relationship-based household purchasing. Each vertical imposes distinct specification and delivery requirements.
- Restaurants:Fine-dining and fast-casual operators reformulate menus around clean-label protein claims. Kitchen specification sheets increasingly require third-party certification documentation and consistent portion-controlled deliveries.
- Households:Affluent consumers in metropolitan coastal markets drive premium retail and subscription channel growth. Origin transparency and health claims outweigh price sensitivity for this segment.
- Food Service:Institutional and contract feeding operations seek volume reliability at competitive unit economics. Distributor relationships through Sysco and US Foods dominate procurement architecture.
- Meal Kit Companies:Blue Apron, HelloFresh, and regional competitors concentrate demand for portion-controlled cuts with recipe-matched specifications. Packaging and labeling requirements differ from conventional retail.
Restaurants dominate commercial procurement volume. Meal kit companies represent the steepest expansion trajectory as convenience-oriented purchasing scales.
Certification:
Certification tiers create price stratification and market access differentiation. Compliance timelines and audit costs vary significantly across standards.
- USDA Organic:Requires third-party verification of organic feed, pasture access, and prohibited substance restrictions. The most widely recognized consumer-facing standard, enabling premium shelf positioning in conventional retail.
- Animal Welfare Approved:Imposes the most stringent pasture-based requirements with 12-18 month compliance windows. Independent retailers and specialty food service operators concentrate demand for this designation.
- Grass Fed:USDA AMS standard mandates continuous pasture access and 100% forage-based diets. Definitional clarity reduces consumer confusion and enables enforcement through FSIS.
- Non-GMO:Verifies absence of genetically modified feed inputs through supply chain documentation. Midwest and Pacific Northwest markets show concentrated consumer preference.
USDA Organic dominates recognized installed base. Animal Welfare Approved is gaining share fastest as welfare-sensitive procurement expands in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grass fed beef consumption patterns diverge sharply by geography. United States households prioritize direct-to-origin transparency through subscription channels, while Australian and South American production systems emphasize export-grade certification compliance for premium chilled beef shipments.
United States
Direct-to-consumer subscription services and premium retail natural meat cases drive demand concentration in coastal metropolitan corridors. The USDA Agricultural Marketing Service enforces grass fed label standards through FSIS, creating definitional clarity for domestic producers. Pasture finishing capacity clusters in the Midwest and Great Plains, where rotational grazing operations supply both ground beef volume and premium steak cuts to food service distributors.
Australia
Export-oriented chilled beef shipments to European and Asian markets anchor production economics for Queensland and New South Wales rangeland operations. The Department of Agriculture, Fisheries and Forestry administers certification protocols determining market access eligibility. Integrated pasture-to-plate traceability systems in these states enable premium positioning for hormone-free and antibiotic-free product lines.
Brazil
Pasture-based cattle finishing dominates production architecture in Mato Grosso and Pará states, supplying both domestic retail and export markets. The country's national agricultural regulator maintains export health certification standards aligned with import country requirements. Southern Brazil's integrated beef processors are deploying enhanced documentation systems to access EU Green Deal-compliant market segments.
Argentina
Traditional grass fed production in Buenos Aires Province and the Pampas region serves domestic consumption and selective export channels. National food safety authorities enforce residue monitoring programs for antibiotic and hormone verification. Premium branded beef programs from these pastoral zones target specialty retailers in Spain and Italy with heritage-breed positioning.
Canada
Western prairie provinces of Alberta and Saskatchewan concentrate certified organic and grass fed finishing operations for cross-border shipment to United States retailers. Health Canada and the Canadian Food Inspection Agency administer dual-country recognition agreements for organic equivalency. Prairie-based producer cooperatives are expanding direct-to-consumer e-commerce capacity to capture margin from American metropolitan demand.
Grass Fed Beef Market Competitive Environment
Capability concentration sits with pasture-to-plate traceability specialists; scale advantage sits with integrated protein conglomerates with multi-protein sourcing networks. The market structures around three tiers: multinational packers with dedicated grass fed product lines, mid-scale regional processors with certification specialization, and farm-direct operations selling through subscription channels. Dominant competitive moves include backward integration into captive cattle sourcing and strategic partnerships with regenerative agriculture certification bodies.
Within the integrated multinational tier, JBS Foods and Tyson Foods exemplify scale-driven positioning through diversified protein platforms that incorporate grass fed beef within broader retail and food service portfolios. Australian Agricultural Company Limited occupies a distinct geography-focused archetype as an integrated cattle producer and exporter with dedicated pasture-finishing infrastructure. Strauss Brands represents the specialized processor archetype, anchoring premium positioning through dedicated Midwest processing capacity aligned with never-ever antibiotic programs.
| Leading Market Players |
|---|
| JBS Foods |
| Tyson Foods |
| Hormel Foods Corporation |
| Australian Agricultural Company Limited |
| Strauss Brands |
| Panorama |
| Verde Farms |
| Creekstone Farms |
| Perdue Farms |
| Others |
Value Chain & Pricing Dynamics
Midwest cold-chain corridors connecting Great Plains finishing operations to East Coast metropolitan markets carry freight premiums that compound with certification audit costs, concentrating margin capture among integrated producers with captive processing while forcing price stratification between commodity ground beef and premium steak tiers.
Pricing Analysis
Long-term offtake contracts with food service distributors anchor volume pricing for ground beef, while spot-market transactions govern premium steak sales through direct-to-consumer channels. Price differentiation rests on USDA certification tier and pasture-to-plate traceability documentation, with Animal Welfare Approved products commanding shelf premiums above standard Grass Fed designations. Cost compression in the commodity tier intensifies as grain-finished alternatives retain price accessibility. Quick-service restaurant chains exhibit highest price sensitivity, while subscription-based household buyers prioritize origin transparency over unit economics.
Supply Chain Analysis
Dedicated Midwest processors including Strauss Brands hold specialized capacity for never-ever antibiotic programs, with geographic concentration in Iowa and Nebraska feeding both domestic retail and export channels. Raw material flows draw from forage seed inputs, pasture rental agreements, and breeding stock genetics, with supply chain vulnerability centering on drought-driven forage cost volatility. Distribution runs through integrated packer networks, regional cold-chain distributors, and direct subscription fulfillment centers serving coastal metropolitan demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and channel architectures creates niche formation opportunities as consumer procurement splits between convenience-oriented subscription buyers and relationship-seeking farm-direct purchasers.
For Market Incumbents: Entrench market position through backward integration into captive cattle sourcing networks that secure consistent grass fed volumes at scale, while investing in blockchain-integrated traceability systems to defend against emerging pasture-to-plate specialists. JBS Foods exemplifies this consolidation logic through multi-protein platform diversification that absorbs channel volatility.
For New Entrants and Emerging Players: Mid-scale rotational grazing operations in the Great Plains without legacy processing commitments represent the most penetrable entry point for certification-focused challengers seeking to bypass incumbent slotting fee barriers. Direct-to-consumer subscription models enable margin capture unachievable through wholesale channels, with regenerative agriculture certification partnerships providing differentiated positioning against commodity competitors.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified protein conglomerates with underoptimized grass fed product lines lacking dedicated pasture-finishing infrastructure. Long-term viability hinges on climate resilience of temperate grassland corridors and evolving EU import documentation requirements. Monitor USDA conservation program enrollment rates as an inflection indicator for regenerative agriculture capital flows.
| Strategic Initiative | Industry Significance |
|---|---|
| Pasture-to-Plate Traceability Investment | Blockchain-IoT integration enables real-time verification for Animal Welfare Approved audits and EU Green Deal compliance. |
| Direct-to-Consumer Channel Expansion | Subscription models bypass supermarket slotting fees and capture full retail margin from affluent coastal households. |
| Regenerative Agriculture Certification | USDA conservation program alignment unlocks carbon credit revenue streams and premium positioning in sustainability-focused procurement. |
| Backward Integration into Cattle Sourcing | Captive breeding and finishing operations reduce exposure to drought-driven forage cost volatility and supply concentration risk. |
| Midwest Processing Capacity Addition | Dedicated never-ever antibiotic infrastructure addresses cold-chain reconfiguration demands and veterinary skill shortages in rural networks. |
Study Parameters
Operator-level perspectives from ranch managers, meat processing plant supervisors, food service procurement directors, and subscription platform operators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews across these stakeholder categories with secondary validation from USDA Agricultural Marketing Service enforcement records, FSIS compliance documentation, Australian Department of Agriculture export certification protocols, and trade flow data from customs records. Bottom-up pasture capacity estimates and top-down retail channel revenue assessments were triangulated to establish market sizing boundaries.
Scenario-bracketing around drought frequency, EU import documentation stringency, and subscription adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product cut tier, distribution channel architecture, certification standard, and regional production cluster. CAGRs were derived from trend extrapolation of pasture finishing capacity expansion, cross-referenced with food service menu reformulation rates and direct-to-consumer subscription growth patterns in coastal metropolitan corridors.
Macroeconomic conditions sit as an overlay; deviation in pasture rental rates, forage seed input costs, or cross-border chilled beef tariff structures would shift the trajectory. Quarterly review of USDA drought monitor indices, EU Green Deal implementation timelines, and food service procurement specification changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Europe Animal Protein Market
Meat Products
India Animal Protein Market
Meat Products
Poultry Processing Meat Market
Meat Products
Middle East Edible Meat Market
Meat Products
Antibiotic Free Meat Market
Meat Products
United States Frozen Meat Market
Meat Products
Meat Paste Market
Meat Products
Pork Meat Market
Meat Products
Nitrate-Free Bacon Market
Meat Products
France Meat Products Market
Meat Products
Beef Fat Market
Meat Products
Organic Meat Market
Meat Products
Lab-Grown Meat Market
Meat Products
Beef Fat Powder Market
Meat Products
GCC Red Meat Market
Meat Products
Beef Bone Broth Market