
 Sour Cream Market | 2026-2036
Sour Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Sour Cream Market Outlook
Dairy processing technician shortages across the Upper Midwest are redrawing where sour cream production can scale efficiently. Daisy Brand LLC leverages its all-natural positioning to command shelf space in conventional retail channels. Danone SA anchors European sour cream demand through its specialized fresh dairy division. Fonterra Co-operative Group Limited dominates Oceania supply through backward integration into grass-fed milk pools.
Sour cream is a fermented dairy product produced by inoculating pasteurized cream with lactic acid bacteria, typically achieving a titratable acidity of 0.5% to 0.9% and a butterfat content ranging from 14% to 18%. The product functions primarily as a condiment, recipe ingredient, and base for dips in both household kitchens and commercial food preparation. Traditional sour cream still occupies the largest volume share across retail channels, though organic variants are capturing margin pools as certification premiums widen. Food service demand concentrates in tub formats for back-of-house efficiency, while squeeze bottles are gaining traction in quick-service restaurant condiment stations.
The FDA oversees sour cream identity standards under 21 CFR 131.160, prescribing minimum milkfat requirements and permissible bacterial cultures, while USDA grading programs influence procurement specifications for institutional buyers. In Europe, EFSA scientific opinions on dairy fermentation cultures shape which starter strains gain regulatory approval for cross-border trade. Stakeholders must monitor how evolving clean-label definitions in multiple jurisdictions will redefine permissible stabilizers and preservatives.
Market Dynamics
Sour cream production capacity is fragmenting across geographies as dairy technician shortages in the Upper Midwest force processors to relocate fermentation operations to regions with trained labor pools.
Growth Catalysts
- Fusion Cuisine Expansion:Quick-service restaurants across the United States are embedding sour cream into Tex-Mex and Korean-Mexican hybrid menus, driving institutional tub-format procurement.
- Clean-Label Mandates:EFSA scientific opinions on permissible dairy fermentation cultures are accelerating approval pathways for novel starter strains with shorter fermentation cycles.
- Grass-Fed Positioning:New Zealand's backward integration into pasture-based milk supply chains enables premium butterfat sourcing for export-grade sour cream.
Market Restraints
- Cream Price Volatility:Butterfat input costs fluctuate with seasonal milk production cycles in Wisconsin and California, compressing processor margins during spring flush periods.
- Regulatory Friction:FDA identity standards under 21 CFR 131.160 restrict minimum milkfat thresholds, blocking light sour cream variants from standard labeling.
- Substitution Threat:Plant-based cashew and oat cremas are capturing shelf space in natural grocery channels among lactose-intolerant households.
Strategic Opportunities
- Underpenetrated Urban Markets:India's tier-two cities lack refrigerated cold-chain infrastructure for fresh dairy distribution, creating first-mover potential for UHT-stabilized sour cream formats.
- Regulatory Tailwind:Mexico's traditional crema consumption patterns support protected designation of origin frameworks that could anchor premium export positioning.
- Squeeze Bottle Innovation:Quick-service restaurant condiment stations are adopting portion-control dispensing formats that reduce waste and labor costs.
Industry Challenges
- Fermentation Technician Scarcity:Dairy science programs in Minnesota and Iowa are graduating insufficient personnel to staff expanded culturing operations.
- Clean-Label Reformulation Complexity:Removing carrageenan and modified food starch while maintaining viscosity requires extended R&D timelines and sensory testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sour Cream Market |
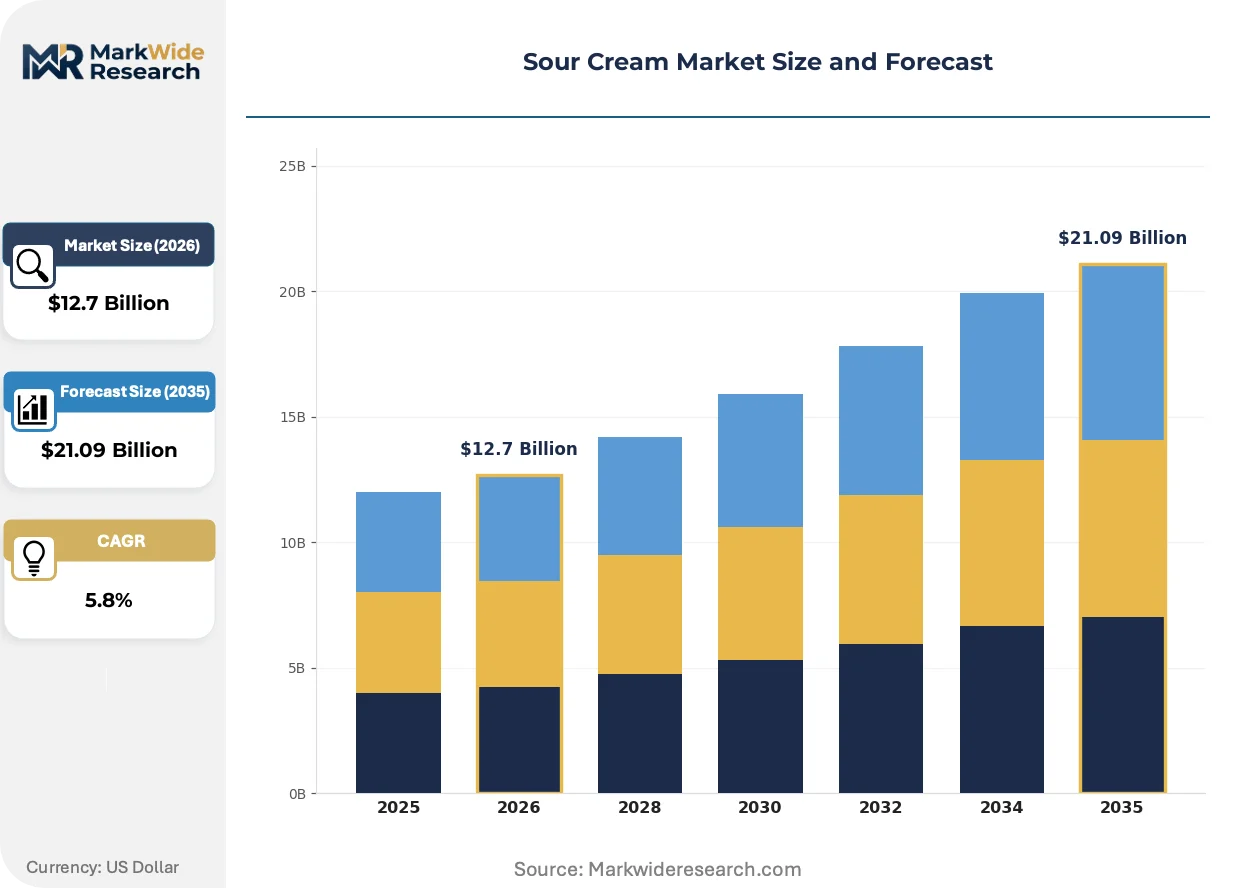
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Organic, Low-Fat, Flavored Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service End User: Households, Restaurants, Cafés, Food Manufacturers Packaging Type: Tubs, Squeeze Bottles, Pouches, Jars |
| Companies Covered | Daisy Brand LLC, The Kraft Heinz Company, Danone SA, Dean Foods Company, HP Hood LLC, LALA U.S. Inc., Fonterra Co-operative Group Limited, Nestle SA, Arla Foods amba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sour Cream Market Strategic Shifts
Starter culture biotechnology and packaging format diversification are reconfiguring how sour cream moves from fermentation vats to end-use applications across retail and food service channels.
Precision fermentation using CRISPR-edited lactic acid bacteria strains is bifurcating the starter culture supply landscape. Large-scale processors in Denmark and the Netherlands are adopting these strains to achieve consistent titratable acidity within tighter bands. This biotechnology is compressing batch-to-batch variation and enabling just-in-time production scheduling that reduces working capital requirements.
EFSA additive disclosure requirements under evolving clean-label frameworks are tightening stabilizer permissibility lists across European Union member states. Industrial sour cream formulations must now substitute locust bean gum and pectin for traditional modified starches to maintain shelf stability. German and French retail buyers are responding by demanding full supply chain documentation from their dairy suppliers.
Food service procurement patterns are consolidating around single-source tub contracts with guaranteed volume commitments. Regional restaurant chains in Texas and California are displacing spot-market purchasing with annual agreements that lock in butterfat specifications. This concentration is most visible among burrito-focused quick-service operators who standardize sour cream as a core ingredient across their menus.
Sour Cream Market Segmentation
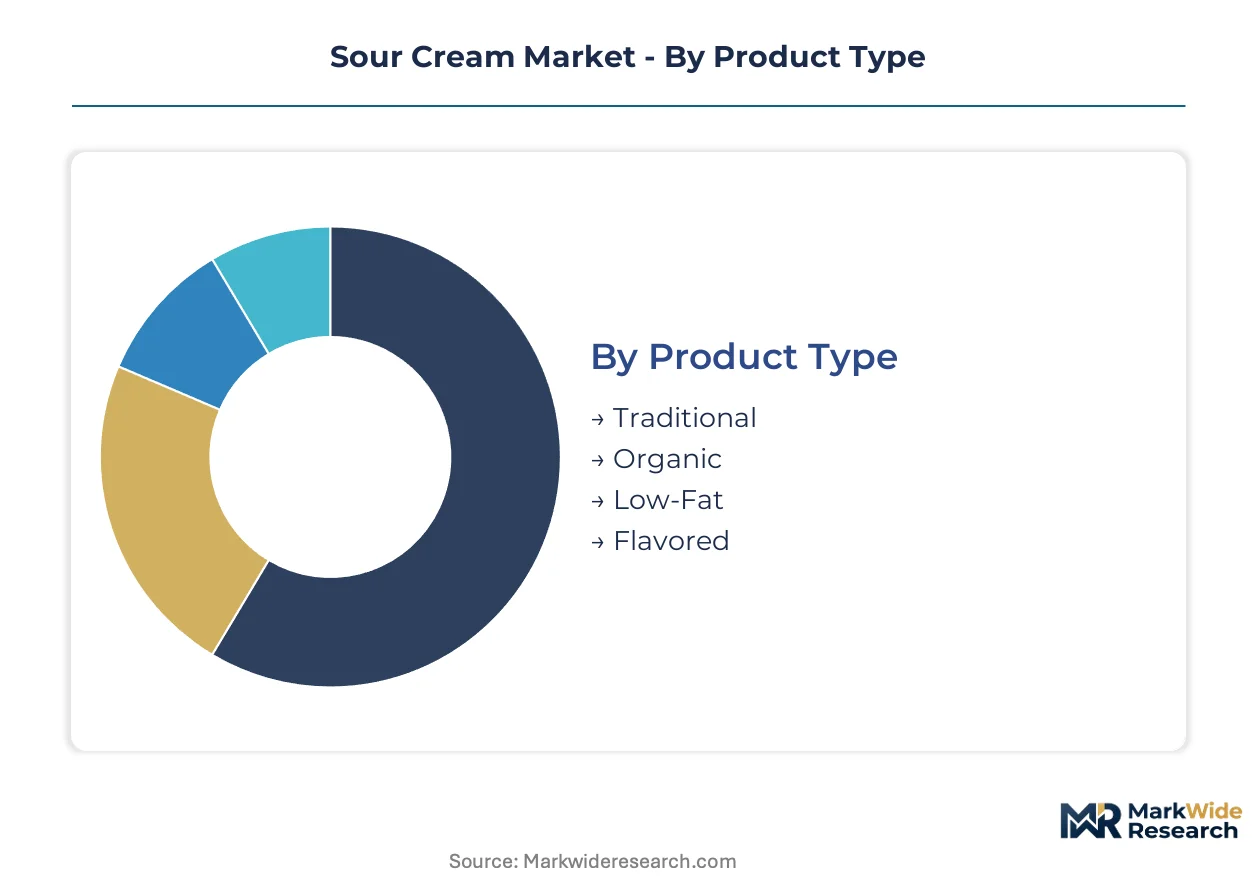
Sour cream manufacturers calibrate formulation, packaging, and channel strategies against distinct buyer requirements across retail and food service environments. Segmentation reveals where butterfat premiums command pricing power versus where operational efficiency drives procurement decisions.
Product Type:
Traditional and organic variants anchor domestic consumption in North America and Europe, while low-fat formulations find traction in export markets with stringent nutritional labeling regimes.
- Traditional:Standard butterfat content of 14% to 18% delivers the viscosity and acidic tang required for baking and hot-food applications. Households in the United States and Mexico generate consistent volume through retail tub purchases, though food service operators are consolidating procurement around single-source annual contracts.
- Organic:Certification requirements restrict starter culture sourcing and prohibit synthetic stabilizers, narrowing the supplier base to processors with dedicated fermentation lines. German and French retail buyers now mandate full supply chain documentation, compressing margins for non-compliant operators.
- Low-Fat:Skim milk solids and modified food starch replace butterfat to achieve texture parity, though FDA identity standards under 21 CFR 131.160 block these variants from standard sour cream labeling.
- Flavored:Onion, ranch, and chipotle infusions target dip and condiment occasions, with quick-service restaurants in Texas and California driving institutional tub demand.
Traditional holds the largest share; momentum sits with organic as certification premiums widen.
Distribution Channel:
Channel selection determines cold-chain investment intensity and margin structure, with direct-store-delivery requirements varying sharply between retail and food service endpoints.
- Supermarkets:Refrigerated dairy cases in conventional retail chains concentrate volume for household-size tubs and squeeze bottles. Slotting fees and promotional calendars compress net revenue per case.
- Online Retail:Temperature-controlled fulfillment centers in urban corridors enable subscription and same-day delivery models for organic and specialty variants, though packaging integrity during last-mile transit remains unresolved.
- Convenience Stores:Single-serve pouches and small-format tubs target immediate consumption occasions, with placement concentrated in travel corridors and college-adjacent locations.
- Food Service:Back-of-house tub procurement dominates institutional volume, with burrito-focused quick-service operators standardizing sour cream across their menus through guaranteed annual volume commitments.
Supermarkets maintain volume dominance; online retail is climbing the fastest as cold-chain logistics mature.
End User:
User type dictates packaging format preference and butterfat specification tolerance, with commercial buyers prioritizing consistency over artisanal variation.
- Households:Retail consumers select across tub sizes and price tiers based on recipe requirements and storage constraints, with organic certification influencing premium willingness in coastal metropolitan areas.
- Restaurants:Quick-service and casual-dining operators specify titratable acidity ranges and viscosity profiles to ensure performance across hot and cold applications, locking in supply through annual procurement agreements.
- Cafés:Limited-menu operators favor squeeze bottles for condiment station efficiency, reducing labor costs and portion variability.
- Food Manufacturers:Industrial buyers source bulk cream and inoculate in-house to control fermentation timelines, displacing finished sour cream purchases in sauce and prepared meal production.
Restaurants command the steepest expansion trajectory; food manufacturers are consolidating backward into captive production.
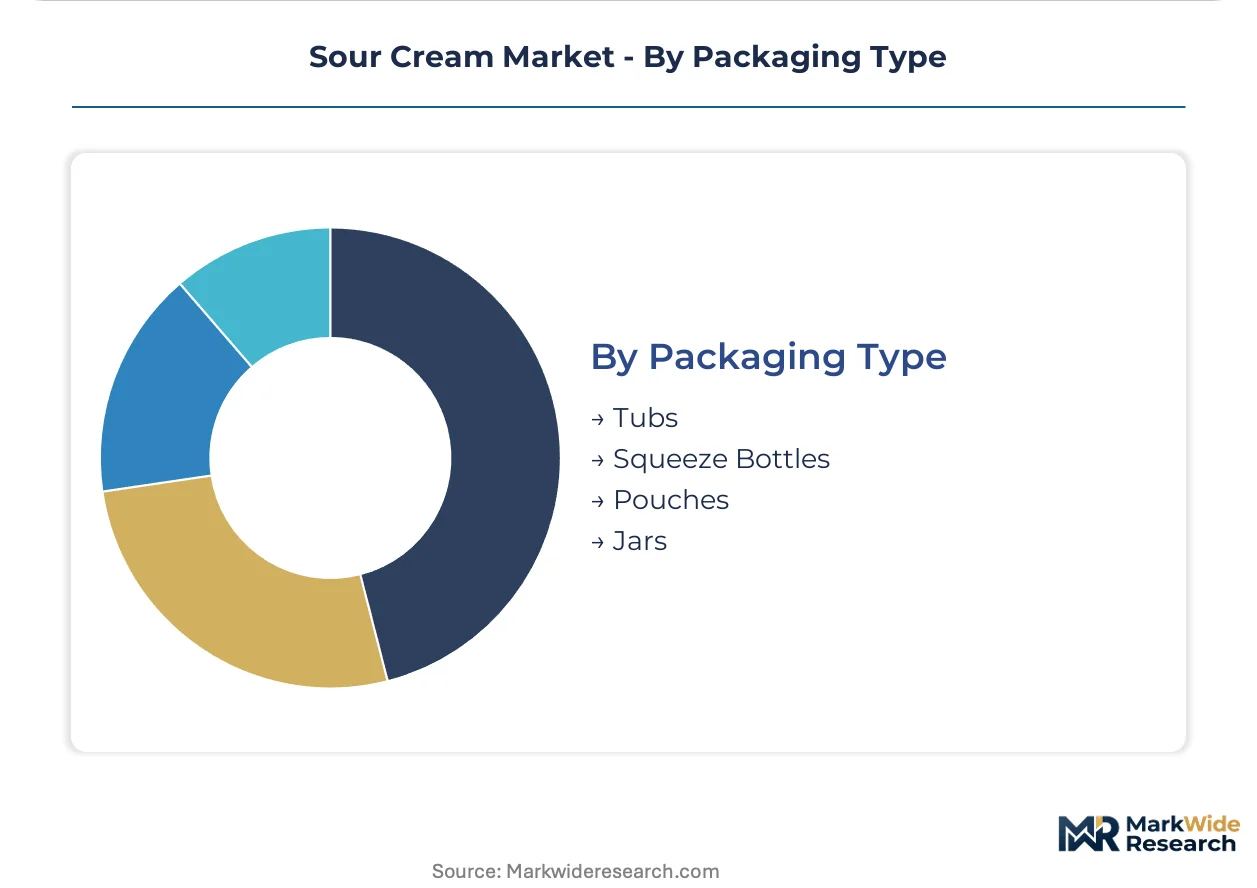
Packaging Type:
Format innovation targets waste reduction and dispensing efficiency, with material selection constrained by dairy fat migration and oxygen permeability requirements.
- Tubs:Polypropylene containers with resealable lids dominate retail and food service bulk procurement, offering stackability and label surface area for clean-label claims.
- Squeeze Bottles:Portion-control dispensing formats reduce back-of-house labor and waste, gaining adoption in quick-service condiment stations across Texas and California.
- Pouches:Flexible film structures target single-serve and travel occasions, though puncture resistance and refrigeration requirements limit distribution reach.
- Jars:Glass and rigid plastic formats serve specialty and gift-market positioning, with higher unit economics supporting artisanal and small-batch production.
Tubs retain volume leadership; squeeze bottles are gaining share fastest as food service operators standardize dispensing infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA identity standards under 21 CFR 131.160 anchor regulatory frameworks in the United States, the world's largest sour cream market by volume. Regional production clusters align with butterfat supply chains and fermentation technician availability.
United States
Quick-service restaurant chains in Texas and California drive institutional tub-format procurement for Tex-Mex fusion menus. The FDA enforces minimum milkfat thresholds that block light sour cream variants from standard labeling. Wisconsin and California dairy processing clusters face technician shortages that force fermentation capacity relocation to Minnesota and Iowa.
Germany
Retail buyers in Berlin and Munich mandate full supply chain documentation for organic certification compliance. EFSA scientific opinions on dairy fermentation cultures shape which starter strains gain regulatory approval for cross-border trade. Bavarian dairy cooperatives specialize in precision fermentation using CRISPR-edited lactic acid bacteria for acidity consistency.
Mexico
Traditional crema consumption patterns in Mexico City and Jalisco anchor protected designation of origin frameworks for premium export positioning. The country's national dairy regulator enforces additive disclosure requirements that tighten clean-label compliance. Northern border states concentrate production facilities serving cross-border food service demand.
France
Parisian retail channels demand locust bean gum and pectin substitutions for modified starches under evolving clean-label frameworks. EFSA additive permissibility lists restrict stabilizer options for industrial formulations. Normandy dairy processors leverage grass-fed milk pools for premium butterfat sourcing in export-grade sour cream.
New Zealand
Pasture-based milk supply chains enable Fonterra's backward integration into grass-fed butterfat for export markets. The country's national food safety authority aligns with EFSA opinions on fermentation culture approvals. Canterbury and Waikato regions dominate production through captive control over milk pool quality specifications.
Sour Cream Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the sour cream market. The upper tier comprises dairy cooperatives with captive milk supply and multinational fresh dairy divisions with dedicated fermentation infrastructure. Specialist tiers include regional processors competing on organic certification and clean-label positioning. Two strategic archetypes dominate: backward-integrated cooperatives controlling grass-fed milk pools, and brand-focused operators commanding retail shelf space through all-natural claims. Competitive moves concentrate on single-source annual procurement contracts with food service chains and reformulation investments to remove carrageenan while maintaining viscosity.
Among North American brand operators, Daisy Brand LLC and The Kraft Heinz Company occupy positions defined by retail channel penetration and conventional grocery shelf space command. Danone SA represents the European multinational archetype through its specialized fresh dairy division structure. Fonterra Co-operative Group Limited anchors the cooperative model with its New Zealand-based captive supply of pasture-derived butterfat. These three entities exemplify how geographic origin and corporate structure shape competitive positioning without overlapping segment focus.
| Leading Market Players |
|---|
| Daisy Brand LLC |
| The Kraft Heinz Company |
| Danone SA |
| Dean Foods Company |
| HP Hood LLC |
| LALA U.S. Inc. |
| Fonterra Co-operative Group Limited |
| Nestle SA |
| Arla Foods amba |
| Others |
Value Chain & Pricing Dynamics
Seventy-two-hour fermentation-to-distribution cycles in the Upper Midwest compress working capital windows while amplifying pricing power for processors with captive technician pools. This lead-time concentration rewards backward-integrated cooperatives and penalizes spot-market buyers during spring flush butterfat volatility.
Pricing Analysis
Geographic price spreads between Wisconsin dairy processing clusters and California Central Valley operations widen during seasonal milk production peaks. Three-tier pricing structure across organic certification, conventional retail, and food service contract tiers anchors the market. Price differentiation rests on butterfat specification tolerance and clean-label certification status. Cost compression in conventional retail channels intensifies because slotting fees and promotional calendars erode net revenue per case. Food service buyers exhibit lowest price sensitivity due to guaranteed annual volume commitments, while household purchasers in coastal metropolitan areas show highest premium willingness for organic variants.
Supply Chain Analysis
New Zealand and the United States anchor grass-fed butterfat production for premium export-grade sour cream, while Germany and France concentrate precision fermentation infrastructure for starter culture biotechnology. Raw material dependencies center on pasture-based milk pools, CRISPR-edited lactic acid bacteria strains, and locust bean gum stabilizers. Single-source vulnerability runs through Upper Midwest technician training pipelines that fail to replenish dairy science program graduates. Distribution runs through direct-store-delivery networks for retail tubs and single-source annual contracts for institutional food service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
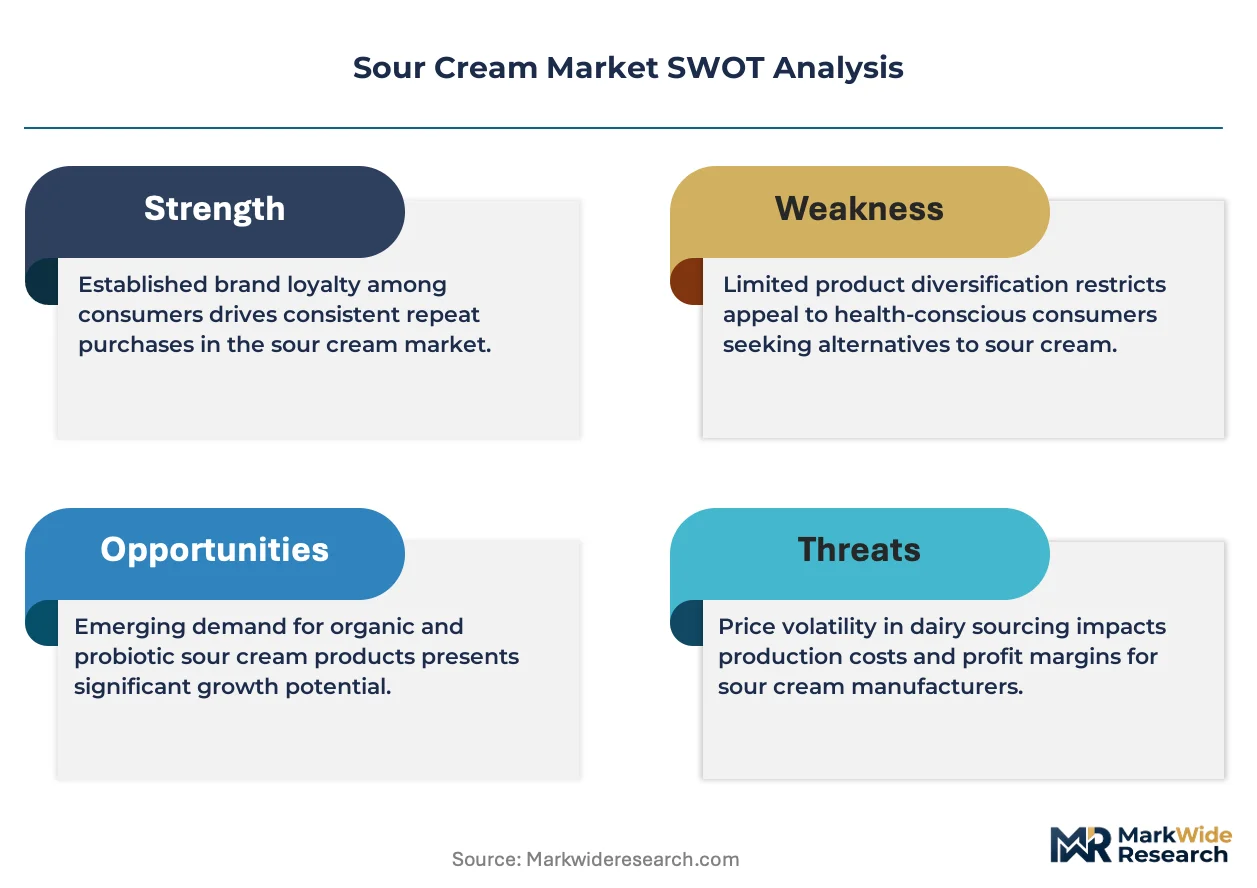
Precision fermentation biotechnology and tightening EFSA clean-label frameworks are disrupting competitive positioning in fresh dairy, creating acceleration windows for first-movers in novel starter strain adoption.
For Market Incumbents: Secure fermentation technician pipelines through partnerships with Minnesota and Iowa dairy science programs before capacity relocations complete. Lock in single-source annual procurement contracts with burrito-focused quick-service chains to defend against plant-based cashew and oat crema substitution threats. Prioritize carrageenan removal R&D to maintain viscosity under evolving clean-label mandates. For New Entrants and Emerging Players: Differentiate on UHT-stabilized formats for India's tier-two cities where refrigerated cold-chain infrastructure remains underdeveloped. Target squeeze bottle dispensing innovation for quick-service restaurant condiment stations in Texas and California. Pursue protected designation of origin frameworks in Mexico's traditional crema regions for premium export positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational fresh dairy divisions seeking to divest non-core fermentation infrastructure. Long-term viability favors processors with captive grass-fed milk pools and dedicated organic certification lines. Watch EFSA scientific opinion timelines on novel starter strain approvals as the inflection signal for biotechnology adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Adoption | CRISPR-edited lactic acid bacteria strains compress batch-to-batch variation for just-in-time scheduling. |
| Clean-Label Reformulation | Locust bean gum and pectin substitutions satisfy German and French retail documentation mandates. |
| Squeeze Bottle Format Expansion | Portion-control dispensing reduces waste and labor costs in quick-service condiment stations. |
| Backward Integration into Milk Pools | Fonterra's pasture-based supply chains enable premium butterfat sourcing for export markets. |
| Protected Designation of Origin Pursuit | Mexico's traditional crema frameworks anchor premium export positioning for regional processors. |
Study Parameters
The analysis maps traditional, organic, low-fat, and flavored product segments, each validated through dairy processing technicians, retail category buyers, food service procurement managers, and fermentation R&D directors. Primary interviews with these stakeholders combined with secondary validation from FDA 21 CFR 131.160 filings, EFSA scientific opinions, USDA grading program documentation, and dairy cooperative annual reports. Bottom-up volume triangulation against top-down value estimates ensures consistency across geographies.
Outputs were validated against external benchmarks including customs trade flows and retail audit data. The projection horizon spans product type, distribution channel, end user, and packaging format dimensions. CAGRs were derived from historical trajectory analysis adjusted for biotechnology adoption curves and regulatory approval timelines. Forecast inputs incorporate butterfat price cycle patterns and clean-label reformulation completion rates.
Forecasts assume regulatory continuity in FDA identity standards and EFSA additive permissibility frameworks; material policy shifts would require re-modeling. Specific risks include dairy technician shortage acceleration, plant-based substitution threshold crossings, and cold-chain infrastructure delays in emerging markets. Recalibration cycles align with material shifts in starter culture biotechnology adoption and clean-label mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Organic Cheese Powder Market
Dairy Products
India Dairy Market
Dairy Products
Malted Milk Powder Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
United States Dairy Market
Dairy Products
Yogurt and Probiotic Drink Market
Dairy Products
US Cheese Market
Dairy Products
Butter and Margarine Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
Dairy Carton Market
Dairy Products
Global Milk Protein Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
A2 Milk Market
Dairy Products
Cheese Concentrate Market