
 Italy Probiotic Drinks Market | 2026-2036
Italy Probiotic Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Probiotic Drinks Market Insights
Fermentation technology is fragmenting across traditional dairy cultures and novel non-dairy substrates, forcing manufacturers to rebuild production lines around strain-specific viability protocols. DANONE Italy leverages its refrigerated distribution network to anchor shelf-stable probiotic yogurt drinks across northern retail corridors. Yakult Italia competes through dedicated home-delivery channels that sustain daily-consumption habits among urban households. Legendary Drink Srl specializes in small-batch kombucha with extended cold-chain requirements that differentiate its portfolio from mass-market alternatives.
Probiotic drinks are functional beverages containing live microbial cultures, typically formulated with minimum colony-forming unit counts between 10^6 and 10^9 CFU per serving, designed to deliver gastrointestinal health benefits through regular consumption. Kefir and yogurt drinks occupy the mature core of the Italian market, where margin pools remain concentrated among established dairy processors with captive fermentation capacity. Kombucha represents the fastest-expanding product type, though its alcohol-content variability near 0.5% ABV creates compliance complexity under Italian beverage classification standards. Distribution through health stores and specialty shops captures premium pricing, while supermarket penetration drives volume scale among family purchasers.
EFSA nutrition and health claims regulation shapes permissible marketing language around digestive benefits, compelling reformulation documentation for any strain-specific assertions. Italy's Ministry of Health enforces beverage alcohol thresholds that classify certain kombucha productions under wine-excise frameworks, constraining channel access for smaller fermenters. The National Institute of Health coordinates with regional food safety authorities to audit cold-chain integrity from production through retail. Stakeholders must monitor pending EU-wide harmonization of probiotic definition standards that could redraw competitive boundaries between dairy and non-dairy format producers.
Market Dynamics
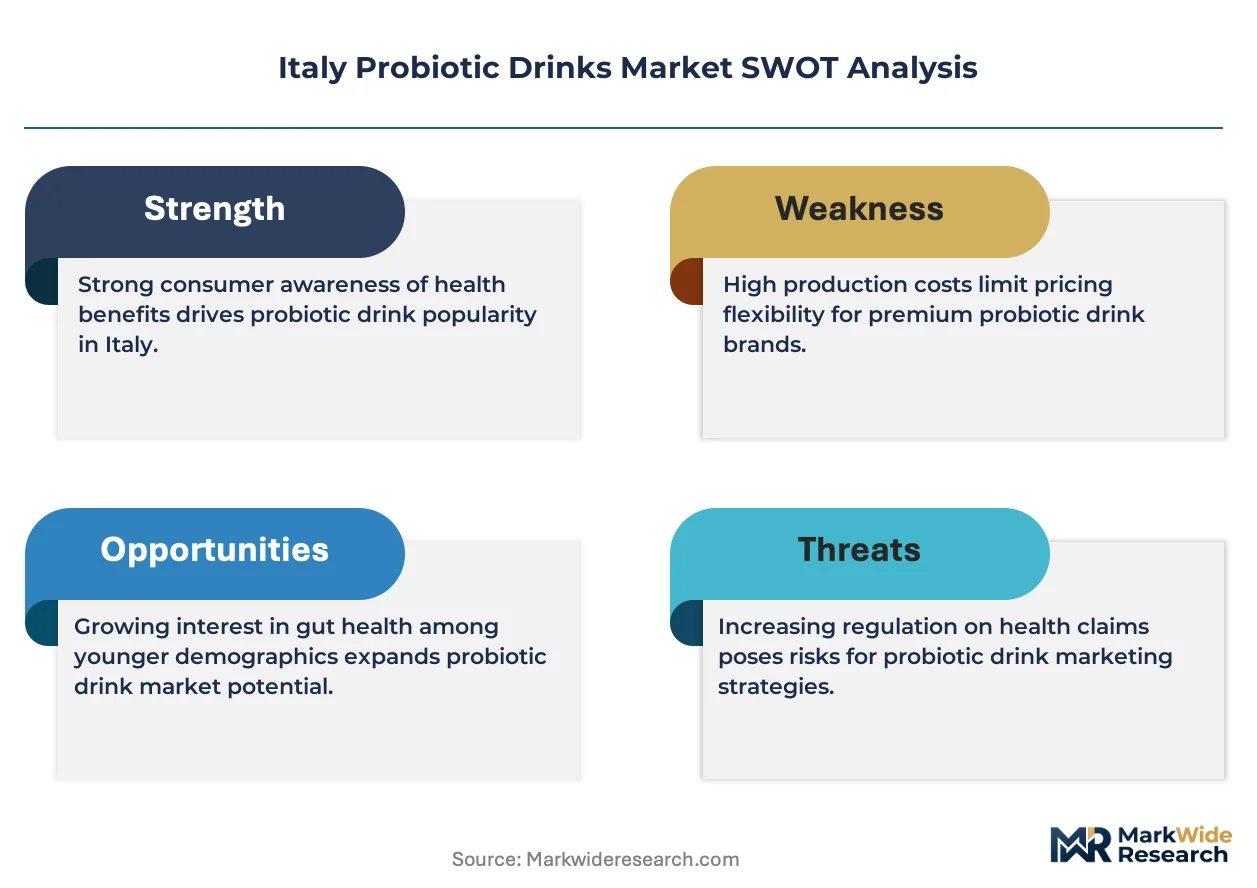
EFSA health claim enforcement is fragmenting formulation strategies across Italian probiotic drink manufacturers, forcing strain-specific clinical documentation and reshaping R&D allocation between dairy and non-dairy fermentation platforms.
Growth Catalysts
- Clean-label fermentation:Consumer rejection of artificial additives in Lombardy and Emilia-Romagna is pulling investment toward minimal-processing technologies that preserve live culture counts without chemical stabilizers.
- EFSA regulatory clarity:Strain-specific digestive health claim pathways provide compliant marketing frameworks that reduce litigation exposure for documented probiotic assertions.
- Urban household density:Milan and Rome apartment living patterns favor single-serve refrigerated formats over bulk purchasing, expanding daily-consumption occasions.
Market Restraints
- Excise classification friction:Italy's Ministry of Health alcohol thresholds near 0.5% ABV force kombucha producers into wine-tax frameworks that constrain mainstream retail channel access.
- Cold-chain infrastructure gaps:Southern Italian regions lack the refrigerated logistics density of northern corridors, limiting viable distribution geography for live-culture products.
- Strain viability degradation:Shelf-stable packaging technologies remain technically constrained, forcing reliance on expensive refrigerated transport and shortening effective product windows.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily present white-space demand with minimal incumbent probiotic drink presence and rising health-conscious middle-class formation.
- Home-delivery channel expansion:Dedicated subscription logistics bypass supermarket slotting fees while capturing recurring revenue from habituated daily consumers.
- EU harmonization tailwind:Pending bloc-wide probiotic definition standards could unlock cross-border formulation portability and reduce country-specific compliance fragmentation.
Industry Challenges
- Microbiome R&D talent scarcity:Strain-specific clinical trial design and gastrointestinal endpoint validation require specialized expertise concentrated in limited academic and contract research institutions.
- Legacy dairy equipment retrofit costs:Traditional yogurt production lines require substantial capital reconfiguration to handle non-dairy substrates and novel fermentation protocols.
- EFSA substantiation timelines:Health claim approval processes extend 18-24 months, compressing effective patent windows for novel strain commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Probiotic Drinks Market |
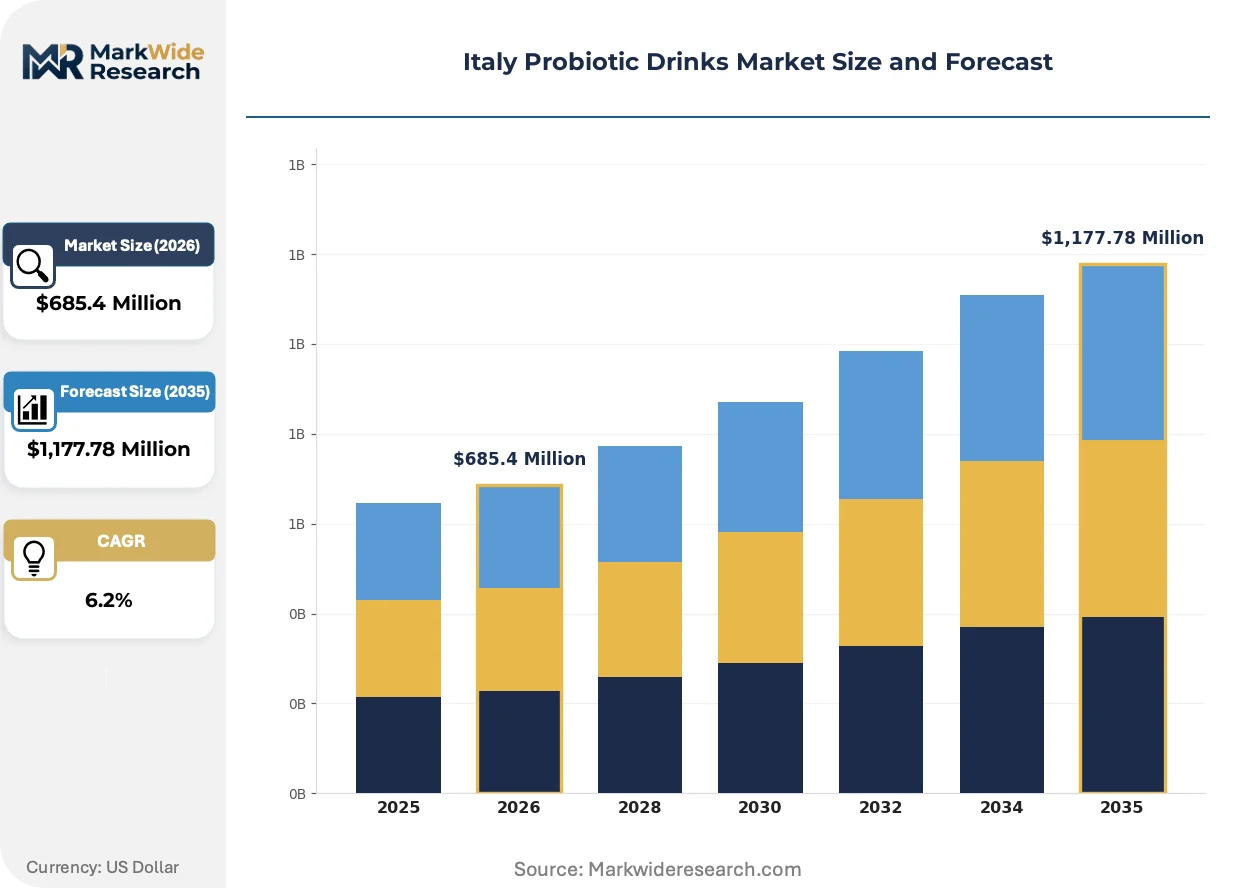
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kefir, Yogurt Drinks, Kombucha, Probiotic Juices Distribution Channel: Supermarkets, Health Stores, Online Retail, Specialty Shops Consumer Age Group: Children, Teenagers, Adults, Seniors Flavor Profile: Fruit Flavors, Herbal, Plain, Spiced |
| Companies Covered | Trevalli Cooperlat, Legendary Drink Srl, DANONE Italy, Fervere, Mia Kombucha, Yakult Italia, Centrale del Latte d'Italia Spa, Activia Italia, Lactalis Group Italy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Probiotic Drinks Market Trends and Innovations
Fermentation control systems and substrate diversification are actively compressing the technical gap between artisanal batch consistency and industrial scale, reshaping competitive boundaries between mass-market and specialty probiotic drink producers.
Smart fermentation monitoring is digitizing production traceability across Italian probiotic facilities. Mid-sized processors in Emilia-Romagna are deploying sensor arrays that track temperature, pH, and colony viability in real time. This infrastructure is digitizing quality assurance documentation that EFSA compliance auditors now expect for strain-specific health claim substantiation.
EFSA nutrition and health claims regulation is tightening permissible marketing language for digestive benefit assertions. Manufacturers must now maintain clinical dossiers for each strain-specific claim, elevating documentation costs. Kombucha and water kefir segments face particular scrutiny as novel formats lack the historical safety data that traditional yogurt drinks accumulated.
Urban Italian households are consolidating beverage purchases through dedicated subscription channels that bypass conventional retail. Health-conscious consumers in Milan and Rome prioritize delivery reliability and cold-chain integrity over supermarket convenience. This behavioral pivot is most visible among dual-income families seeking to automate daily probiotic consumption without inventory management friction.
Italy Probiotic Drinks Market Segmentation
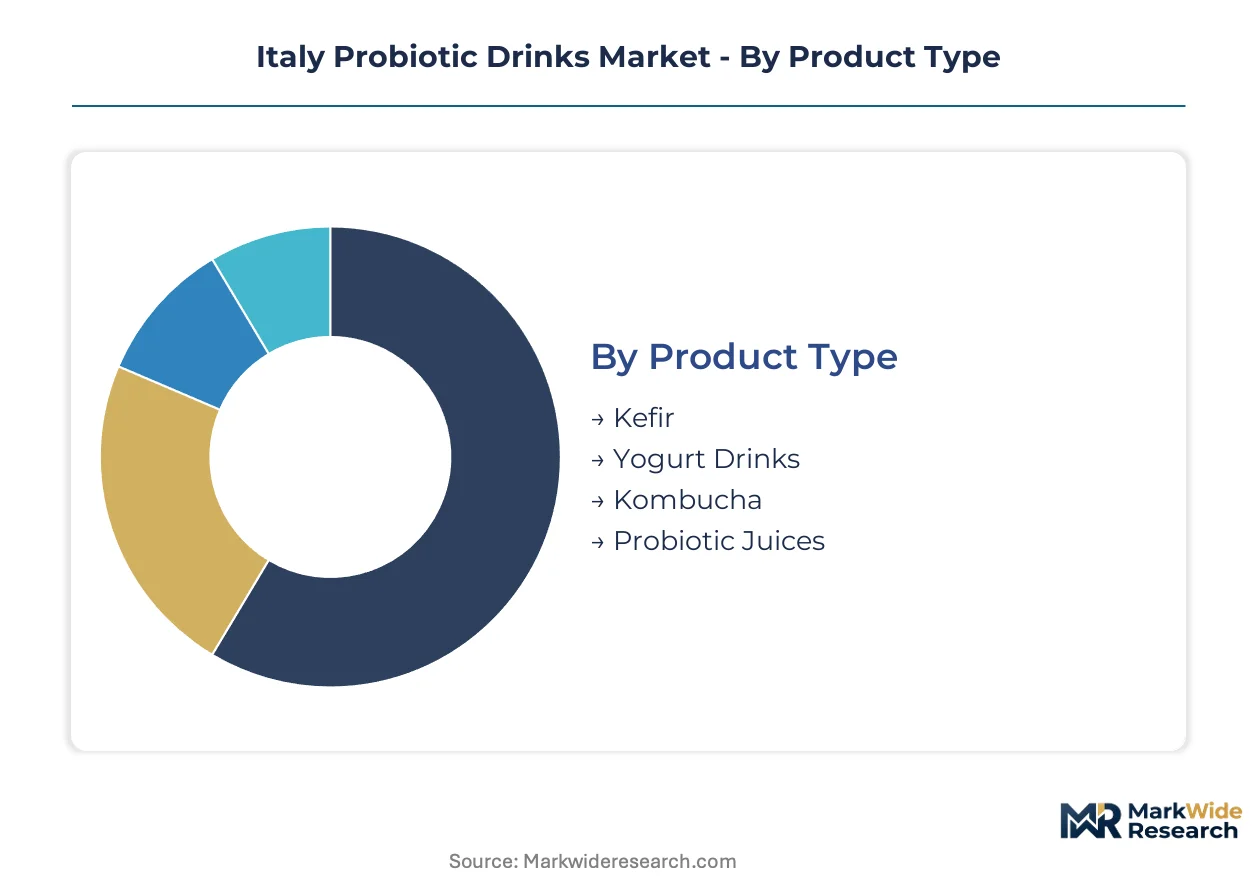
Segmentation in Italy's probiotic drinks market reveals divergent service requirements across cold-chain intensity and purchase frequency. Each category exposes distinct margin architectures and loyalty mechanics that manufacturers must calibrate against regional infrastructure realities.
Product Type:
After-sales service intensity varies sharply across fermentation platforms, with live-culture viability demands driving refrigerated logistics investment and subscription support infrastructure.
- Kefir:Fermented milk beverage containing multiple yeast and bacterial strains, traditionally consumed daily for digestive regularity. Demand concentrates in Lombardy and Emilia-Romagna households with established dairy consumption habits, where cold-chain density supports consistent viability. Margin pools here remain captive to processors with in-house fermentation capacity.
- Yogurt Drinks:Liquid yogurt formats with standardized probiotic strain concentrations between 10^6 and 10^9 CFU per serving. Milan and Rome urban households favor single-serve refrigerated bottles over bulk purchasing, expanding daily-consumption occasions among time-constrained professionals.
- Kombucha:Fermented tea with variable alcohol content near 0.5% ABV, requiring careful compliance navigation under Italy's beverage classification standards. Legendary Drink Srl and artisanal producers target premium positioning through extended cold-chain protocols.
- Probiotic Juices:Fruit-based carriers with added live cultures, positioned at the intersection of functional beverages and traditional juice categories. Shelf-stable variants attempt to bypass refrigeration constraints but face strain viability skepticism from EFSA-conscious consumers.
By volume, Yogurt Drinks leads. By growth pace, Kombucha is expanding most quickly.
Distribution Channel:
Channel selection directly determines cold-chain accountability and consumer education burdens, with each pathway imposing distinct working capital and promotional cost structures.
- Supermarkets:Mass retail penetration driving volume scale among family purchasers across northern Italy's refrigerated retail corridors. DANONE Italy anchors shelf-stable and chilled formats through dominant slotting positions.
- Health Stores:Specialty retail capturing premium pricing through educated staff and curated strain-specific assortments. These outlets absorb higher margin products that require consumer explanation of CFU counts and fermentation benefits.
- Online Retail:Direct-to-consumer subscription logistics bypassing conventional retail friction. Yakult Italia leverages dedicated home-delivery channels to sustain daily-consumption habits with reliable cold-chain integrity.
- Specialty Shops:Independent retailers focusing on artisanal kombucha and small-batch kefir with provenance narratives. Extended cold-chain requirements differentiate this channel from mass-market alternatives.
Supermarkets dominate absolute volume. Online Retail shows the steepest expansion trajectory as subscription models consolidate habituated purchasing.
Consumer Age Group:
Age-based segmentation exposes divergent format preferences and health claim receptivity, with each cohort presenting distinct regulatory sensitivities around pediatric and geriatric marketing.
- Adults:Core consumption base in Milan and Rome urban centers, driving functional beverage expansion through workplace and commute consumption occasions. EFSA digestive health claims resonate most directly with this cohort's self-directed health management.
- Seniors:Growing segment attracted to gastrointestinal regularity and immune support positioning. Northern Italy's aging demographics concentrate demand in Lombardy's established dairy markets.
- Children:Pediatric formulations face strict EFSA substantiation requirements for strain-specific claims, limiting marketing language and flavor innovation.
- Teenagers:Emerging target for flavored kombucha and juice-based formats, though alcohol-content variability creates compliance complexity for producers.
Adults command current volume leadership. Seniors are gaining share fastest as aging demographics and health consciousness converge.
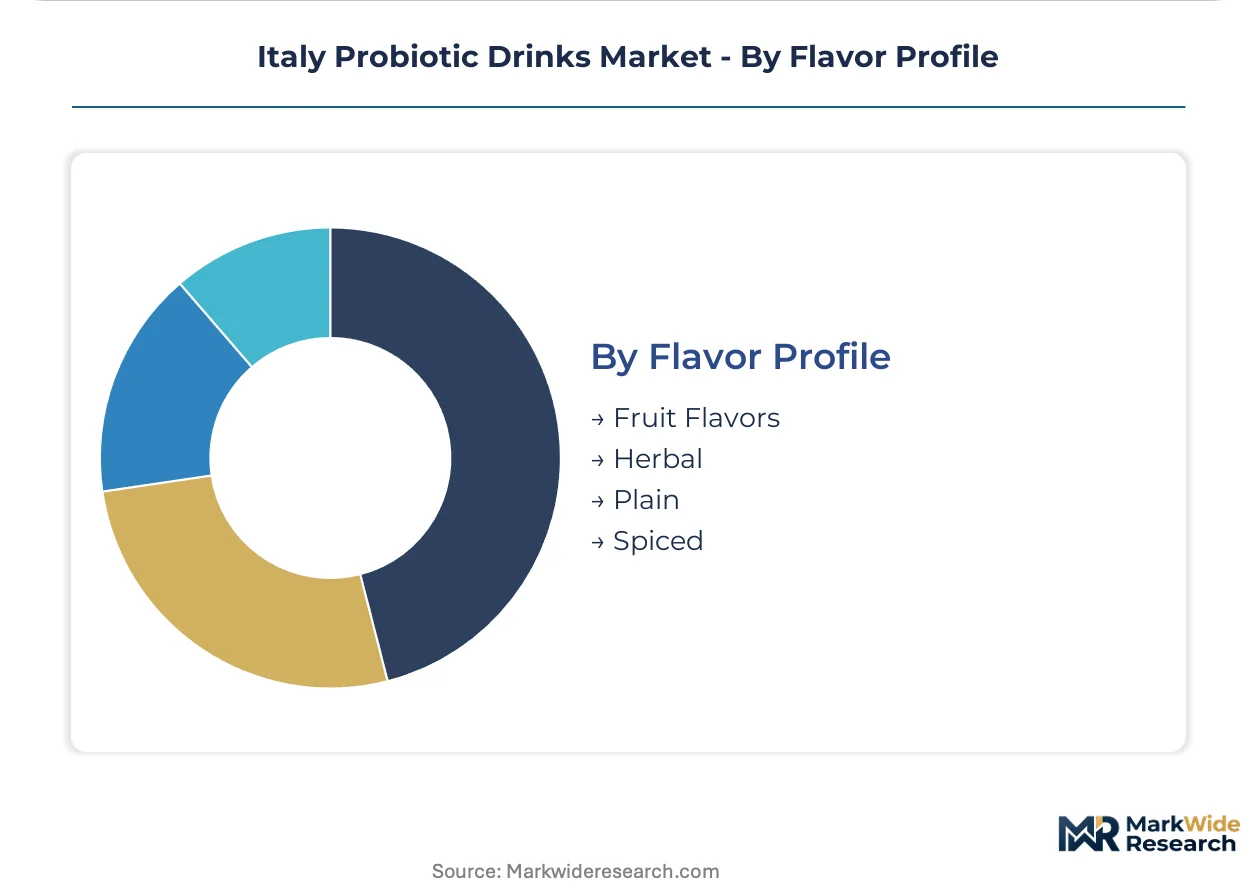
Flavor Profile:
Flavor diversification strategies must balance clean-label fermentation integrity against palatability thresholds, with artificial additive rejection in northern regions constraining formulation options.
- Fruit Flavors:Berry, citrus, and tropical variants masking fermentation tang for mainstream acceptance. These formulations dominate supermarket shelves and family-oriented purchasing.
- Plain:Unflavored formats appealing to purist consumers and culinary applications. Kefir and yogurt drink traditionalists in Emilia-Romagna sustain this segment's relevance.
- Herbal:Botanical infusions targeting wellness-positioned consumers in specialty and health store channels. Ginger, turmeric, and adaptogenic combinations differentiate premium offerings.
- Spiced:Cinnamon, cardamom, and chai-inspired profiles aligning with kombucha's tea heritage. Artisanal producers leverage these variants for seasonal and limited-release positioning.
Fruit Flavors lead by volume. Herbal profiles are climbing the fastest as functional positioning intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Dutch probiotic drink exports flow into Italy through Alpine logistics corridors, supplying northern retailers with refrigerated formats that compete against domestic Lombardy production.
Lombardy
Milan's dense urban workforce sustains daily consumption habits for single-serve yogurt drinks and kefir. EFSA health claim documentation requirements filter out undercapitalized local entrants. Cold-chain infrastructure in the Po Valley supports Centrale del Latte d'Italia Spa's fermentation facilities and DANONE Italy's distribution hubs.
Emilia-Romagna
Bologna's food science research clusters generate strain-specific clinical data for EFSA-compliant marketing. Italy's Ministry of Health beverage classification audits concentrate in this region due to high kombucha production volumes. Artisanal kefir producers in Parma and Modena leverage traditional dairy heritage for premium positioning.
Lazio
Rome's dual-income households drive subscription-channel adoption for home-delivered probiotic formats. Yakult Italia anchors daily-consumption routines through dedicated logistics networks. The region's retail density lags Lombardy, constraining refrigerated format penetration outside urban cores.
Veneto
Verona and Padua health-conscious consumers expand demand for clean-label kombucha and water kefir. Regional food safety authorities coordinate cold-chain audits with the National Institute of Health. Trevalli Cooperlat processes dairy substrates from Alpine supply basins into probiotic yogurt drinks.
Piedmont
Turin's established pharmaceutical and food technology sectors supply fermentation equipment and strain validation services to probiotic drink manufacturers. The proximity to French cross-border trade corridors exposes local producers to EU-wide harmonization pressures on probiotic definition standards. Mia Kombucha and Fervere operate small-batch facilities targeting specialty retail channels.
Italy Probiotic Drinks Market Competitive Landscape
On the supply side, the industry is bifurcated between mass-market dairy processors with captive fermentation capacity and artisanal non-dairy specialists competing through premium positioning. Strategic archetypes include refrigerated logistics integrators, small-batch kombucha fermenters, and multinational brand licensors. Dominant competitive moves center on home-delivery channel construction and EFSA-compliant strain documentation investments.
Within the mass-market dairy tier, DANONE Italy and Lactalis Group Italy exemplify scale-driven refrigerated distribution architectures. Legendary Drink Srl occupies the artisanal kombucha specialization vector. Yakult Italia anchors the dedicated subscription logistics archetype that bypasses conventional retail slotting structures.
| Leading Market Players |
|---|
| Trevalli Cooperlat |
| Legendary Drink Srl |
| DANONE Italy |
| Fervere |
| Mia Kombucha |
| Yakult Italia |
| Centrale del Latte d'Italia Spa |
| Activia Italia |
| Lactalis Group Italy |
| Others |
Pricing and Supply Chain Analysis
Emilia-Romagna's fermentation equipment clusters anchor Italy's probiotic drink production capacity, concentrating margin capture among processors with captive dairy substrate access and cold-chain density that downstream buyers cannot easily replicate.
Pricing Analysis
Refrigerated-format pricing commands substantial premiums over ambient-stable alternatives due to live-culture viability guarantees. Three-tier pricing structure across premium, standard, and economy levels separates small-batch kombucha with extended cold-chain protocols from mass-market yogurt drinks and private-label kefir. Pricing pressure stems from EFSA documentation costs elevating R&D overhead for strain-specific claims. Family purchasers in supermarket channels exhibit highest price sensitivity, while subscription-based urban households prioritize reliability over per-unit cost.
Supply Chain Analysis
Organic milk substrates from Alpine supply basins feed into Lombardy and Emilia-Romagna fermentation facilities. Live culture strains draw from specialized suppliers in France and Germany, while packaging materials rest on Italian and Austrian converters. Single-source vulnerability concentrates around proprietary strain libraries held by limited academic licensors. Distribution runs through refrigerated logistics networks anchored by DANONE Italy and Yakult Italia, with southern regions exhibiting infrastructure gaps that constrain viable geography.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's probiotic drinks sector sits in early-cycle expansion as home-delivery subscription models penetrate dual-income households and EFSA regulatory clarity reduces compliance fragmentation for documented strain claims.
For Market Incumbents: Harden refrigerated logistics density in southern corridors to preempt competitive entry as Campania and Sicily health-consciousness rises. Deepen backward integration into organic dairy substrates to secure margin pools against Alpine supply volatility and input cost pressure from competing bio-industrial applications. For New Entrants and Emerging Players: Pursue white-space positioning in probiotic juices and water kefir formats where incumbent presence remains thin and EFSA substantiation pathways are less crowded than traditional yogurt drinks. Target specialty retail channels in Verona and Padua with clean-label fermentation narratives that justify premium positioning above mass-market alternatives. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors small-batch kombucha specialists with documented cold-chain protocols and artisanal provenance stories that resist commoditization. Long-term viability hinges on EU harmonization of probiotic definition standards unlocking cross-border formulation portability. Monitor EFSA strain approval timelines as inflection indicator for documentation cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerated Distribution Expansion | DANONE Italy's northern corridor density creates defensive moats against southern market entry. |
| Strain-Specific Clinical Documentation | EFSA-compliant dossiers reduce litigation exposure and enable premium pricing for digestive claims. |
| Home-Delivery Channel Construction | Yakult Italia's subscription logistics bypass supermarket slotting fees while capturing recurring revenue. |
| Clean-Label Fermentation Investment | Minimal-processing technologies preserve live culture counts without chemical stabilizers rejected in Lombardy. |
| Non-Dairy Substrate Diversification | Kombucha and water kefir formats expand addressable market beyond traditional dairy consumption households. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation technology directors, refrigerated logistics managers, retail category buyers, and EFSA regulatory consultants and refined through secondary validation against customs trade records, Ministry of Health beverage classification filings, National Institute of Health cold-chain audit reports, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spend estimates.
Demand-supply balance dynamics across the analysis window were calibrated through segmentation by product type, distribution channel, consumer age cohort, and regional infrastructure maturity. CAGRs derived from historical trajectory analysis adjusted for regulatory timeline impacts and technology adoption S-curves. Industry-specific inputs incorporated EFSA strain approval pipeline tracking and refrigerated logistics capacity utilization rates.
Sensitivities concentrate around EU harmonization timing, EFSA documentation cost inflation, and southern infrastructure buildout pace. Forecasts reflect assumptions regarding live-culture viability technology maturation and subscription channel penetration rates. Cross-checking against Alpine dairy substrate price indices and refrigerated transport cost benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
US and Canada Tonic Water Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
Commercial Sparkling Water Dispenser Market
Beverages
Fruit Water Market
Beverages
Europe Juices Market
Beverages
Hot Cocoa Mix Market
Beverages
Packaged Cactus Water Market
Beverages
Nitro-Infused Beverages Market
Beverages
Fruit Beverages Market
Beverages
Reconstituted Juice Market
Beverages
Chocolate Malt Drink Market
Beverages
GCC Juice Market
Beverages
South America Dairy Based Beverages Market
Beverages
North America Dairy Beverages Market
Beverages
Global Electrolyte Drinks Market
Beverages
Recovery Drinks Market