
 US and Europe Nuts and Seeds Cheese Market | 2026-2036
US and Europe Nuts and Seeds Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
US and Europe Nuts and Seeds Cheese Market Outlook
Precision fermentation and enzymatic culturing is reshaping how nut and seed bases achieve texture parity with conventional dairy. Miyoko's Creamery leverages proprietary cashew fermentation to sustain premium positioning across US natural grocery channels. Kite Hill anchors its supply chain through in-house almond sourcing and clean-label formulations. Treeline Treenut Cheese differentiates through small-batch French-style aging techniques that occupy the artisan segment.
Nuts and seeds cheese denotes plant-based dairy alternatives manufactured from blended oilseeds and tree nuts through mechanical pressing, enzymatic coagulation, or lactic acid fermentation, typically achieving protein contents between 2% and 6% and fat profiles mirroring soft dairy equivalents. Creamy cheese variants lead volume due to their spreadable functionality and lower production complexity, while flavored cheese commands margin premiums through herb infusion and smoked preparations. Almond-based formulations dominate ingredient type segmentation owing to neutral flavor compatibility and established supplier infrastructure.
FDA standards for nut allergen labeling and the EU's Nutrition and Health Claims Regulation shape formulation transparency and cross-border market access for producers. The USDA Organic seal and EU Organic certification create tiered compliance pathways that influence pricing architecture and retail placement. Stakeholders must monitor evolving enforcement of the EU Deforestation Regulation as it extends traceability requirements to cashew and almond supply chains originating outside covered regions.
Market Dynamics
Precision fermentation infrastructure is consolidating production economics for nut and seed cheese manufacturers, compressing unit costs while enabling texture parity with conventional dairy that was previously unattainable through mechanical processing alone.
Growth Catalysts
- EU Green Deal implementation:The EU Deforestation Regulation mandates supply chain traceability for cashew and almond imports, accelerating certified ingredient sourcing investments among Dutch and German producers seeking premium retail placement.
- Enzymatic culturing advancement:Proteolytic enzyme blends now achieve protein breakdown patterns matching aged dairy, enabling French-style aging techniques that command shelf space in specialty food retailers across Paris and Lyon.
- California urban demand concentration:Premium natural grocery channels in Los Angeles and San Francisco are expanding refrigerated plant-based sections, creating pull-through for fermented cashew cream cheese variants with clean-label positioning.
Market Restraints
- Almond supply concentration:California's Central Valley dominates raw almond supply, exposing European processors to water scarcity risks and tariff volatility that compress margin predictability.
- FDA allergen labeling friction:The Food Allergen Labeling and Consumer Protection Act mandates prominent tree nut disclosure, limiting cross-merchandising opportunities in conventional dairy aisles and constraining trial among hesitant consumers.
- Protein content ceiling:Current fermentation protocols cap finished product protein at approximately six percent, creating functional limitations for applications requiring structural integrity under heat stress.
Strategic Opportunities
- Netherlands foodservice penetration:Amsterdam and Rotterdam hotel chains are expanding vegan menu requirements, creating white space for bulk cultured cashew formats in hospitality procurement.
- Precision fermentation convergence:Integration of biomass fermentation with traditional nut bases enables hybrid products combining dairy-identical proteins with plant-derived fats, opening reformulation pathways for German industrial bakeries.
- Direct-to-subscription channels:Specialty retailers in Berlin and Munich are piloting curated plant-based cheese boxes, bypassing slotting fee structures that disadvantage emerging brands in conventional retail.
Industry Challenges
- Microbiology talent scarcity:Commercial-scale fermentation operations require specialized lactic acid bacteria cultivation expertise that remains concentrated among European dairy science programs, constraining US facility expansion timelines.
- Organic certification lag:USDA Organic and EU Organic dual certification processes extend product development cycles by eight to fourteen months, delaying market entry for reformulated lines targeting both jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Europe Nuts and Seeds Cheese Market |
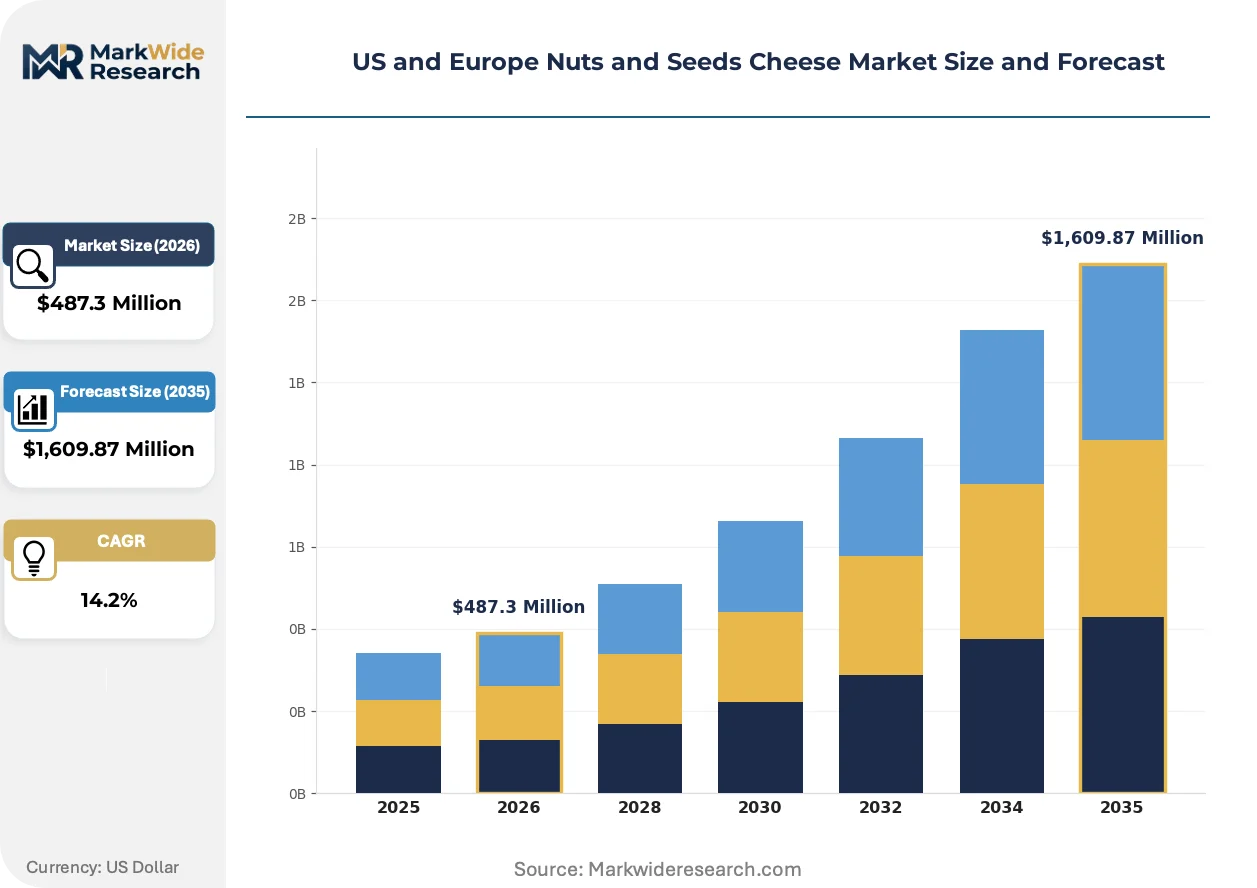
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,609.87 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creamy Cheese, Spreadable Cheese, Crumbly Cheese, Flavored Cheese Ingredient Type: Almonds, Cashews, Walnuts, Peanuts Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farmers Markets Customer Type: Health-Conscious Consumers, Vegetarians, Food Enthusiasts, Culinary Professionals |
| Companies Covered | Miyoko's Creamery, Heidi Ho! Foods, Treeline Treenut Cheese, Tyne Chease Limited, Vtopian Artisan Cheeses, Kite Hill, Parmela Creamery, Nutcrafter Creamery, Dr-Cow Tree Nut Cheese, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Europe Nuts and Seeds Cheese Market Strategic Shifts
Bioprocessing capabilities are advancing faster than formulation science can commercialize them, creating a pipeline of texture and flavor technologies that will filter into retail products over the next production cycle.
High-pressure processing technology is migrating from beverage sterilization applications into nut cheese manufacturing, enabling extended shelf life without thermal degradation of volatile flavor compounds. California-based copackers are retrofitting existing HPP lines for cultured cashew formats, achieving sixty-day refrigerated stability that matches conventional soft cheese distribution requirements. This capability compression is eliminating the geographic radius constraints that previously limited artisan producers to local farmers market circuits.
The EU Nutrition and Health Claims Regulation is tightening enforcement of protein content declarations, forcing reformulators to substantiate nutritional parity claims with analytical data. German retailers are now requiring third-party amino acid profiling for products bearing "high protein" positioning, shifting competitive advantage toward manufacturers with in-house laboratory capabilities. Almond-based spreadable formats face the steepest compliance burden given their naturally lower protein density relative to fermented cashew equivalents.
Foodservice procurement is consolidating around single-source supplier agreements that bundle plant-based cheese with complementary alternatives. Institutional buyers in French hospital and university networks are awarding multi-year contracts to vendors offering comprehensive dairy-free portfolios, displacing the fragmented supplier relationships common in early category development. This buyer concentration is most visible in Île-de-France, where centralized purchasing for the Paris metropolitan area now covers over four hundred individual foodservice outlets.
US and Europe Nuts and Seeds Cheese Market Segmentation
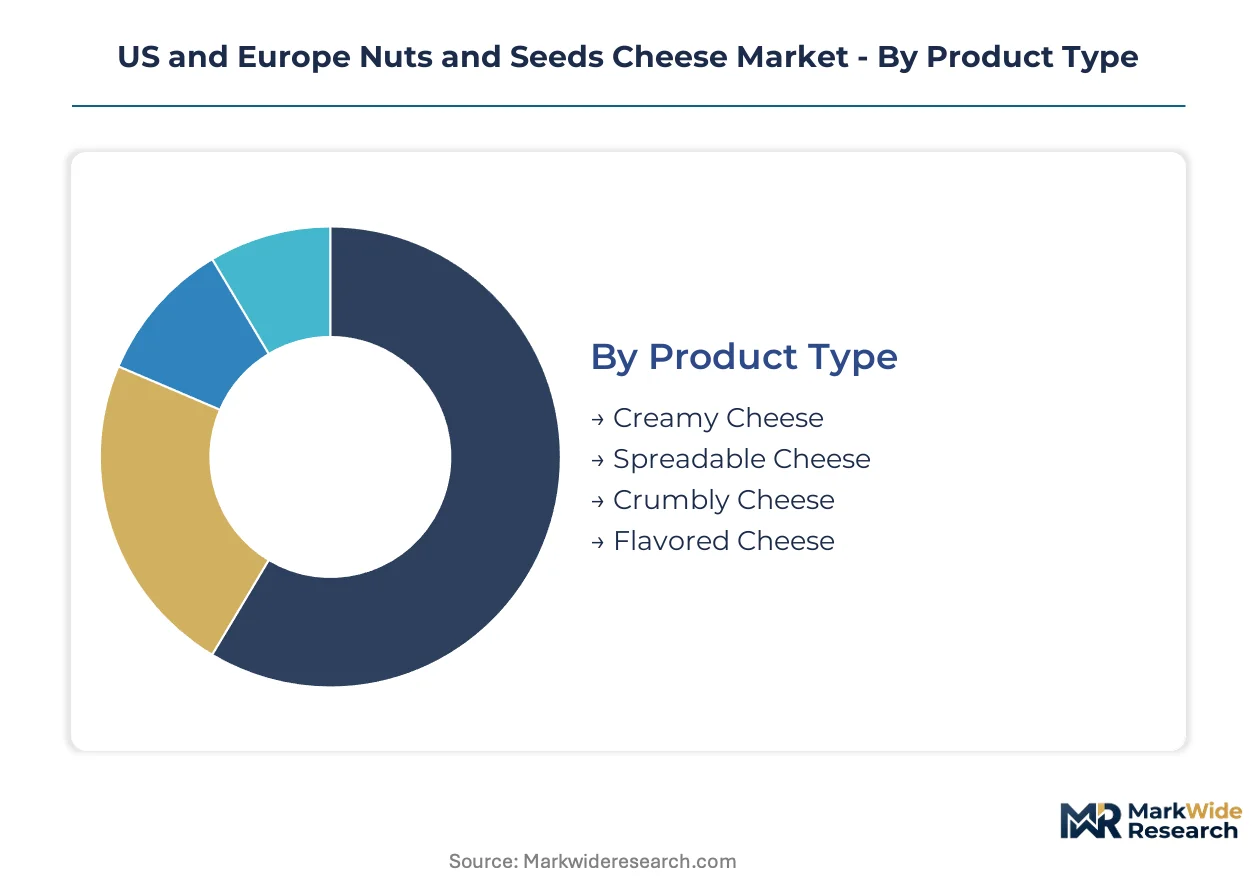
Segmentation in the US and Europe nuts and seeds cheese market reveals how production complexity, ingredient sourcing cycles, and retail channel velocity create divergent competitive arenas. Manufacturers must align fermentation capacity and aging infrastructure with the specific turnover rhythms of each segment to capture margin.
Product Type:
Creamy cheese variants turn inventory fastest due to shorter fermentation cycles, while aged formats tie up working capital through extended cellar time.
- Creamy Cheese:Spreadable formulations achieve protein contents between 2% and 6% through abbreviated lactic acid fermentation. Los Angeles and San Francisco natural grocery channels are expanding refrigerated sections for these formats, driven by clean-label positioning that commands premium placement.
- Flavored Cheese:Herb infusion and smoked preparations layer additional processing steps atop base fermentation. Paris and Lyon specialty food retailers are allocating expanded shelf space to French-style aged variants, capitalizing on enzymatic culturing advancements that achieve dairy-parity texture.
- Spreadable Cheese:Lower production complexity enables rapid SKU proliferation for seasonal and limited-edition releases.
- Crumbly Cheese:Extended pressing and dehydration protocols extend production cycles, constraining output scalability.
Creamy cheese dominates installed base. Flavored cheese is where expansion concentrates.
Ingredient Type:
Cost tier stratification separates commodity oilseeds from tree nuts with certified provenance requirements.
- Almonds:Neutral flavor compatibility and established supplier infrastructure in California's Central Valley anchor volume production. Dutch and German processors face margin compression from water scarcity risks and tariff volatility affecting raw material predictability.
- Cashews:Higher fat content enables superior mouthfeel in fermented cream cheese applications. Amsterdam and Rotterdam hotel chains are expanding vegan menu procurement for bulk cultured cashew formats, creating foodservice white space.
- Walnuts:Tannic bitterness limits application breadth to specific regional taste preferences.
- Peanuts:Lower input costs position this segment for economy-tier pricing, though allergen labeling constraints restrict retail placement.
Almond-based formulations anchor current volume. Cashew-derived products are climbing the fastest as precision fermentation infrastructure matures.
Distribution Channel:
Customer acquisition economics vary sharply between high-touch experiential retail and automated replenishment systems.
- Specialty Stores:Curated plant-based cheese boxes in Berlin and Munich are piloting direct-to-subscription models that bypass conventional slotting fees. These channels enable emerging brands to build trial before scaling to mass retail.
- Supermarkets:Centralized refrigerated section expansion across California and the Netherlands is consolidating category management under fewer buyer relationships.
- Online Retail:Cold-chain logistics investments are extending geographic reach for perishable fermented formats.
- Farmers Markets:High-pressure processing retrofits are eliminating radius constraints that previously limited artisan producers to local circuits.
Specialty stores concentrate margin capture. Supermarkets are gaining share fastest through refrigerated section expansion.
Customer Type:
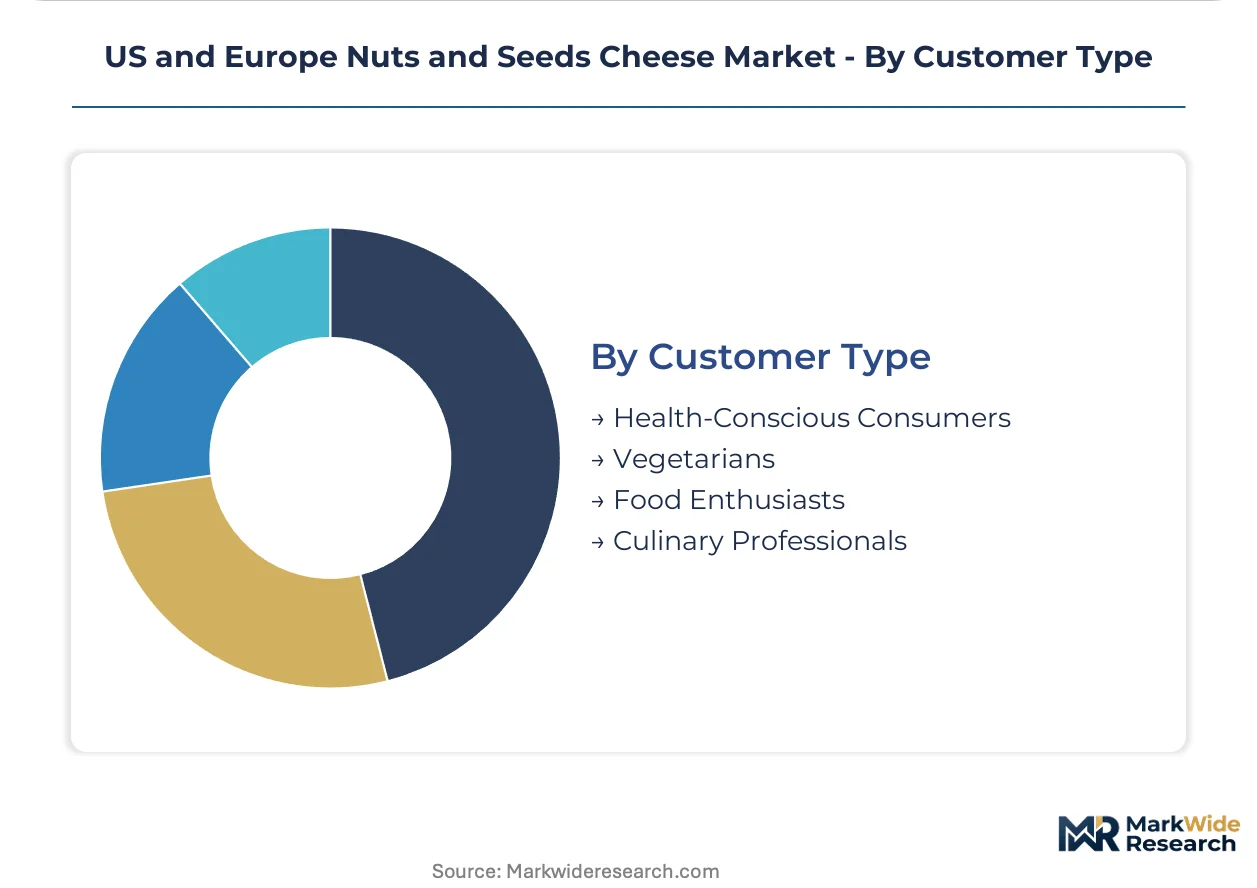
Application intensity separates occasional purchasers from professional users with recurring volume requirements.
- Culinary Professionals:Institutional buyers in French hospital and university networks are awarding multi-year contracts to vendors with comprehensive dairy-free portfolios. Centralized purchasing for the Paris metropolitan area now covers over four hundred individual foodservice outlets.
- Health-Conscious Consumers:Third-party amino acid profiling requirements from German retailers are shifting advantage toward manufacturers with in-house laboratory capabilities for substantiating protein content claims.
- Vegetarians:Dietary adherence creates predictable replenishment patterns with lower price sensitivity.
- Food Enthusiasts:Experimental purchasing behavior drives trial of limited-edition and seasonal formulations.
Culinary professionals anchor contracted volume. Health-conscious consumers are expanding most quickly as labeling transparency requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley exports raw almonds to Dutch and German processors, establishing the dominant transatlantic ingredient corridor for the US and Europe nuts and seeds cheese market. This trade flow concentrates production economics and regulatory compliance burdens on both coasts of the supply chain.
United States
Los Angeles and San Francisco natural grocery channels are expanding refrigerated plant-based sections, creating pull-through for fermented cashew cream cheese variants with clean-label positioning. FDA standards for nut allergen labeling mandate prominent tree nut disclosure, constraining cross-merchandising opportunities in conventional dairy aisles. California's Central Valley dominates raw almond supply, exposing processors to water scarcity risks that compress margin predictability.
Germany
Berlin and Munich specialty retailers are piloting curated plant-based cheese boxes, bypassing slotting fee structures that disadvantage emerging brands in conventional retail. The EU Deforestation Regulation mandates supply chain traceability for cashew and almond imports, accelerating certified ingredient sourcing investments among producers seeking premium retail placement. German retailers now require third-party amino acid profiling for products bearing high protein positioning.
France
Paris and Lyon specialty food retailers are allocating expanded shelf space to French-style aged variants, capitalizing on enzymatic culturing advancements that achieve dairy-parity texture. The EU Nutrition and Health Claims Regulation shapes formulation transparency and cross-border market access for producers. Centralized purchasing for the Paris metropolitan area now covers over four hundred individual foodservice outlets, consolidating procurement around single-source supplier agreements.
Netherlands
Amsterdam and Rotterdam hotel chains are expanding vegan menu requirements, creating white space for bulk cultured cashew formats in hospitality procurement. The EU Green Deal implementation tightens ingredient transparency requirements across Dutch retail channels. Dutch processors face margin compression from California almond supply concentration and tariff volatility affecting raw material predictability.
US and Europe Nuts and Seeds Cheese Market Competitive Environment
On the supply side, the industry is fragmented across artisan producers and emerging scale players, with consolidation pressure building around precision fermentation infrastructure investments. Three strategic archetypes occupy distinct competitive terrain: heritage cashew fermenters with proprietary cultures, almond-based spreadable specialists leveraging California supply proximity, and hybrid biomass innovators integrating dairy-identical proteins. Dominant competitive moves include backward integration into captive almond and cashew sourcing, plus technology licensing agreements that transfer enzymatic culturing protocols across European and North American production facilities.
Within the heritage fermentation tier, Miyoko's Creamery and Treeline Treenut Cheese exemplify archetypes built on proprietary aging techniques and small-batch positioning. Kite Hill anchors a distinct cluster through in-house almond sourcing and clean-label formulations. These three entities represent the competitive spectrum from artisan scale to integrated supply chain control, with each occupying a definable position in the premium channel architecture that specialty retailers and natural grocery buyers navigate.
| Leading Market Players |
|---|
| Miyoko's Creamery |
| Heidi Ho! Foods |
| Treeline Treenut Cheese |
| Tyne Chease Limited |
| Vtopian Artisan Cheeses |
| Kite Hill |
| Parmela Creamery |
| Nutcrafter Creamery |
| Dr-Cow Tree Nut Cheese |
| Others |
Value Chain & Pricing Dynamics
California's Central Valley anchors raw almond supply for Dutch and German processors, concentrating pricing power among handlers who control certified organic and conventional grade segregation. Water scarcity risks and tariff exposure on transatlantic shipments compress margin predictability for European manufacturers dependent on this single-source corridor.
Pricing Analysis
Prior-generation mechanical pressing equipment produces economy-tier spreads at commodity price points, while current-generation precision fermentation infrastructure commands premium positioning through texture parity claims, and next-generation biomass hybrid formats will reset value benchmarks entirely. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified SKUs from conventional clean-label positioning and unbranded private-label alternatives. Pricing pressure stems from California almond supply concentration and EU Deforestation Regulation compliance costs that transfer downstream. Foodservice procurement teams exhibit highest price sensitivity due to contract volume leverage, while direct-to-subscription specialty retail channels absorb premium tiers with minimal elasticity.
Supply Chain Analysis
EU Deforestation Regulation traceability requirements restrict cashew and almond flows from non-certified origins, compelling Dutch and German processors to document supply chain provenance through blockchain-enabled tracking systems. Raw material sourcing draws from California almonds, Vietnamese cashews, and Mediterranean pine nuts as secondary inputs. Single-source vulnerability concentrates in California's Central Valley water-dependent production, exposing European manufacturers to climate-induced harvest volatility. Distribution runs through temperature-controlled logistics networks linking California export terminals to Rotterdam port facilities and inland European cold-chain distribution centers serving natural grocery and foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation infrastructure buildout signals early-cycle expansion with penetration tailwinds from enzymatic culturing advancements achieving dairy-parity texture in premium urban markets.
For Market Incumbents: Build captive fermentation capacity moats through proprietary lactic acid bacteria strain libraries and in-house enzymatic protocol development. Defensive consolidation should prioritize backward integration into certified organic almond and cashew sourcing to secure EU Deforestation Regulation compliance ahead of enforcement tightening. Capacity addition in Netherlands foodservice processing hubs counters emerging biomass hybrid threats from German industrial bakery partnerships. For New Entrants and Emerging Players: Build out direct-to-subscription specialty retail presence in Berlin and Munich curated cheese box pilots, bypassing supermarket slotting fee barriers that entrench established brands. White-space concentration sits in Amsterdam and Rotterdam hotel chain vegan menu procurement for bulk cultured cashew formats. Foodservice penetration offers lowest competitive density with recurring contract structures and technical specification flexibility absent from retail channel gatekeeping. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation infrastructure owners with validated scale-up protocols and European regulatory compliance track records. Long-term viability over the extended investment horizon hinges on defensible microbiology talent retention and dual USDA-EU Organic certification capabilities. Watch enzymatic culturing patent filing velocity as inflection indicator for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Proprietary enzymatic protocols from Miyoko's Creamery compress unit costs while achieving texture parity with conventional dairy soft cheeses. |
| Certified Ingredient Sourcing Investment | EU Deforestation Regulation compliance accelerates traceability infrastructure for cashew and almond supply chains entering Dutch retail channels. |
| Direct-to-Subscription Channel Development | Berlin and Munich specialty retailer pilots bypass conventional slotting fees that disadvantage emerging brands in supermarket refrigerated sections. |
| Foodservice Procurement Consolidation | Paris metropolitan area centralized purchasing covers four hundred individual outlets, creating contract volume concentration for comprehensive dairy-free portfolios. |
| Hybrid Biomass Product Development | Integration of dairy-identical proteins with plant-derived fats opens reformulation pathways for German industrial bakery applications. |
Study Parameters
A spread of perspectives from plant-based dairy R&D directors, natural grocery category buyers, foodservice procurement managers, and fermentation facility operators converged on the working assumptions driving volume and value estimates. Primary interview intelligence combined with secondary validation from FDA labeling guidance documents, EU Nutrition and Health Claims Regulation enforcement notices, USDA Organic certification databases, and refrigerated retail audit data from California and Netherlands markets. Bottom-up SKU-level demand modeling triangulated against top-down ingredient flow analysis from California export statistics.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, ingredient base, distribution channel velocity, and customer application intensity. CAGRs derived from fitted growth curves calibrated to historical adoption patterns in adjacent plant-based dairy categories. Industry-specific forecast inputs included precision fermentation capacity expansion timelines and EU Deforestation Regulation compliance cost pass-through assumptions.
Stress conditions across California water availability, transatlantic tariff regimes, and enzymatic culturing technology diffusion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding clean-label positioning premium persistence and foodservice contract renewal rates. Material shifts in FDA allergen labeling enforcement stringency or EU Green Deal implementation acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Paneer Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
Low-Fat Cheese Nutrition Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Savory Dairy Products Market
Dairy Products
Dairy Spreads Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
Dairy Based Dressings Market
Dairy Products
Reconstituted Milk Market
Dairy Products
Skim Milk Powder Market
Dairy Products
Whole Milk Powder Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
North America Dairy Market
Dairy Products
Global Grass Fed Dairy Product Market