
 Probiotic Cheese Market | 2026-2036
Probiotic Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotic Cheese Market Insights
The premium probiotic cheese tier is expanding through live culture guarantees and clinical strain documentation, while commodity offerings compete on basic fermentation claims without viability standards. Danone leverages its pharmaceutical-grade culture libraries to anchor high-margin medical nutrition channels. Lactalis dominates European retail distribution through private-label and branded probiotic lines simultaneously. Fonterra Co-operative Group extends its grass-fed dairy positioning into probiotic cheddar exports for Asian markets.
Probiotic cheese refers to fermented dairy products in which specific live microorganisms, typically Lactobacillus and Bifidobacterium strains at minimum counts of 10^6 CFU per gram at consumption, deliver documented health benefits beyond basic nutrition. Manufacturers employ cold-vat fermentation and microencapsulation to preserve culture viability through aging and storage. Cream cheese and cottage cheese categories lead current revenue pools due to shorter production cycles and fresher consumption patterns that protect live cultures. Cheddar and mozzarella segments show faster growth as hard-cheese innovators solve thermotolerance challenges for baked and grilled applications. Adult end users generate the largest volume, while athlete-targeted positioning commands premium pricing through recovery-focused strain formulations.
FDA qualified health claim pathways and EFSA probiotic characterization requirements create divergent compliance costs that favor multinational players with dedicated regulatory affairs teams. EU MDR-aligned strain documentation demands and US FDA GRAS self-affirmation processes shape R&D allocation and time-to-market timelines. Stakeholders must monitor evolving strain-specific approval precedents and invest in clinical trial infrastructure before competitors lock up exclusive health claim positions.
Market Dynamics
EFSA's tightened probiotic health claim requirements are forcing manufacturers to rebuild clinical documentation pipelines, compressing margins for mid-tier players while rewarding those with captive research infrastructure.
Growth Catalysts
- EU MDR-aligned strain documentation:Manufacturers investing in pharmaceutical-grade clinical trials secure exclusive positioning for medical nutrition channels, creating defensible premium tiers.
- Cold-vat fermentation advances:Equipment suppliers in Germany and the Netherlands deliver precision temperature control systems that extend culture viability through extended aging cycles.
- Athlete recovery formulations:Sports nutrition buyers in France and the Netherlands command 40-60% price premiums for strain-specific recovery positioning with documented cortisol modulation.
Market Restraints
- Live culture input concentration:Three European culture houses control 70%+ of pharmaceutical-grade Lactobacillus rhamnosus GG supply, creating vulnerability to batch contamination events.
- Thermotolerance technical ceiling:Hard cheese applications above 180°C baking temperatures destroy 99%+ of viable cultures, limiting pizza and foodservice penetration.
- FDA-EFSA regulatory divergence:Parallel GRAS self-affirmation and EFSA Article 13.5 processes impose dual compliance costs exceeding €2M per novel strain entry.
Strategic Opportunities
- Asian foodservice white space:Japan's METI-backed functional food certification creates expedited pathways for cheddar and mozzarella probiotic variants in baked applications.
- Microencapsulation-convection oven convergence:Combining spray-dried lipid coating with controlled-release matrix technology enables viable culture survival in high-heat prepared foods.
- Direct-to-clinician sampling channels:Bypassing retail concentration through partnerships with Dutch and German dietetic practices builds prescriptive recommendation pipelines.
Industry Challenges
- Clinical microbiologist talent scarcity:Strain characterization and trial design functions face recruitment bottlenecks as pharmaceutical and food sectors compete for identical PhD profiles.
- Legacy ERP integration friction:Batch-level culture tracking requirements collide with dairy co-operative accounting systems designed for commodity volume metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotic Cheese Market |
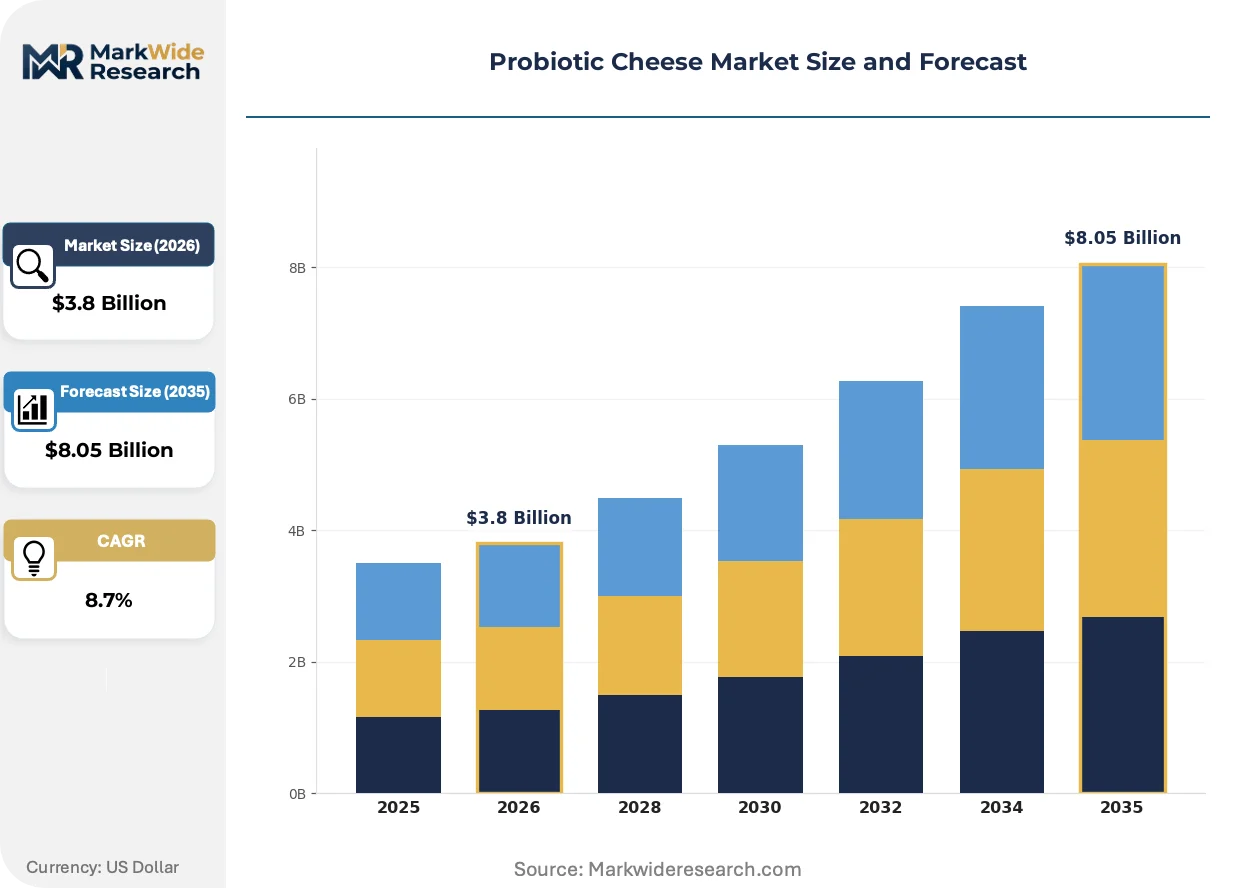
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream Cheese, Cottage Cheese, Cheddar, Mozzarella, Swiss, Parmesan Application: Digestive Health, Immune Support, Weight Management, Gut Microbiota Balance, Anti-inflammatory End User: Children, Adults, Elderly, Pregnant Women, Athletes Packaging Type: Plastic Cups, Foil Wrappers, Vacuum Bags, Tubs, Paper Boxes |
| Companies Covered | Danone, Lactalis, Arla Foods, Fonterra Co-operative Group, Cabot Creamery, BelGioioso Cheese, Beehive Cheese, Sargento Foods, Organic Valley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotic Cheese Market Trends and Innovations
Live culture preservation technology is converging with precision fermentation equipment, reshaping where viable probiotic cheese production can occur and which players control quality certification.
Microencapsulation via lipid-matrix spray drying is converging with modified atmosphere packaging to extend shelf-stable culture counts from 30 to 90 days. German equipment manufacturers are deploying these integrated lines to mid-scale dairies previously excluded from probiotic production. This convergence is compressing the capital threshold for viable entry, fragmenting supply concentration that previously favored multinationals with captive bioprocessing divisions.
EFSA's 2023 updated guidance on Article 13.5 health claims demands strain-specific human intervention studies with minimum 100 subjects, invalidating prior generic fermentation benefit submissions. French and Dutch manufacturers with existing pharmaceutical partnerships are repurposing clinical infrastructure to meet these standards. Hard cheese innovators targeting foodservice are most affected, as baking stability claims now require thermotolerance validation protocols absent from earlier regulatory frameworks.
Certification-driven procurement now dominates institutional channel selection, with hospital and eldercare foodservice buyers in Germany mandating third-party viability verification at point of delivery. Traditional wholesale distributors lacking cold-chain documentation capabilities are losing share to specialized logistics operators with real-time temperature logging. This shift is most visible in the Netherlands, where healthcare procurement consolidation has centralized buying power among three national tendering consortia.
Probiotic Cheese Market Segmentation
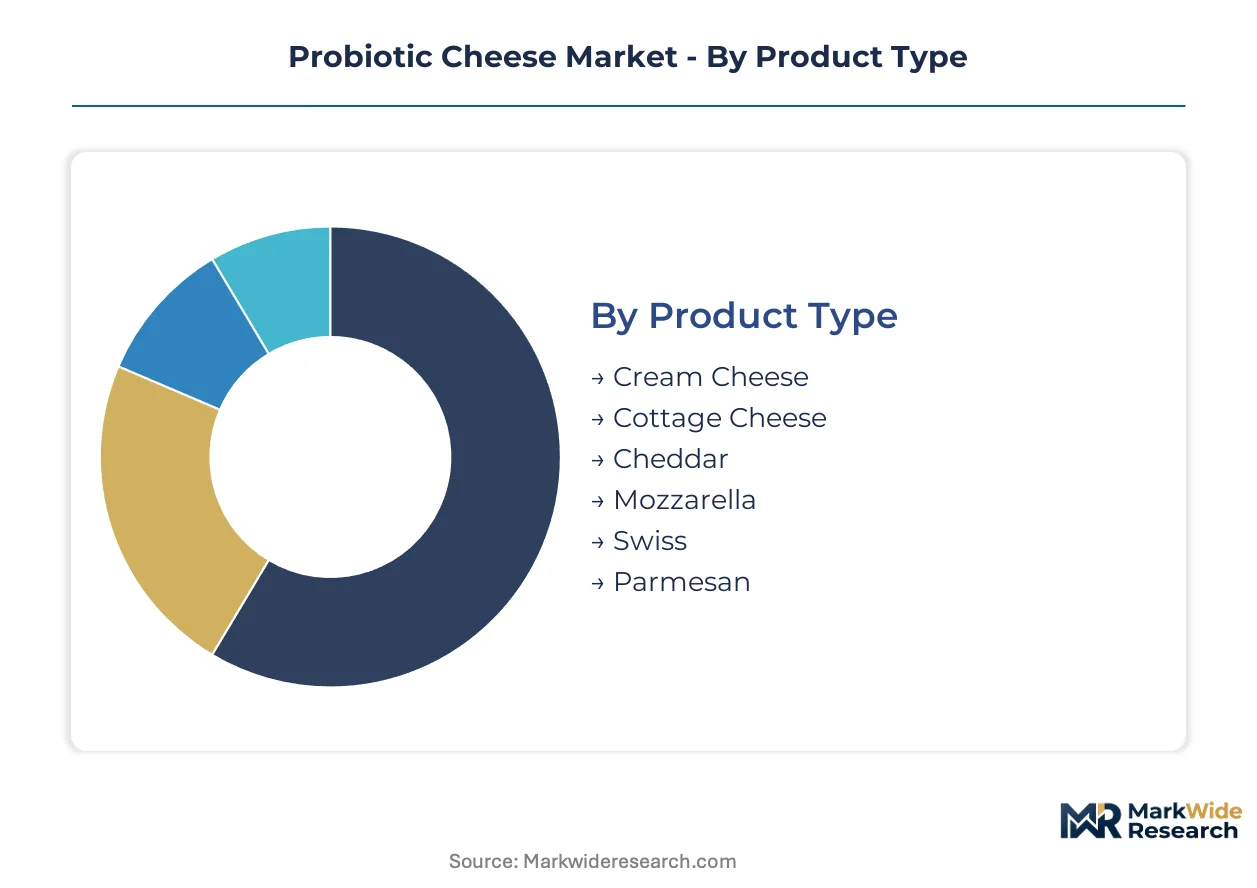
Segmentation in probiotic cheese tracks how live culture viability requirements reshape product development priorities across formats and use cases. Manufacturers align strain selection and preservation technology with distinct consumption moments and health claim positioning.
Product Type:
Fresh-format cheeses dominate standalone probiotic applications with minimal processing barriers to culture survival, while aged and thermally exposed varieties require embedded preservation systems.
- Cream Cheese:High-moisture matrix and cold-set processing preserve Lactobacillus and Bifidobacterium counts through distribution. German and Dutch retail channels concentrate demand for breakfast and snacking applications where live culture guarantees command shelf space premiums.
- Cottage Cheese:Short production cycles and refrigerated consumption patterns protect viability without microencapsulation overhead. US health-conscious consumers drive volume through high-protein positioning combined with digestive health claims.
- Cheddar:Extended aging and baking applications demand thermotolerant strain variants and lipid-matrix protection. Hard cheese innovators target foodservice channels where grilled and melted applications dominate.
- Mozzarella:Pizza and prepared food penetration requires culture survival above 180°C baking temperatures. Japanese METI-certified functional food pathways attract exporters solving heat-stability challenges.
- Swiss:Propionic acid fermentation competes with probiotic strain colonization during eye formation. Niche positioning targets European specialty retail with dual-culture premium tiering.
- Parmesan:Extended aging cycles and low moisture content create hostile environments for live cultures. Grated and shaved applications in finished dishes limit probiotic viability claims to point-of-manufacture guarantees.
Cream cheese leads volumes today; mozzarella is gaining share fastest through foodservice expansion.
Application:
Health claim substantiation costs stratify segments between mass-market fermentation benefits and premium medical nutrition positioning.
- Digestive Health:Generic fermentation claims face EFSA scrutiny requiring strain-specific human studies. Mid-tier manufacturers retreat to basic positioning while pharmaceutical-grade players secure exclusive Article 13.5 approvals.
- Immune Support:Cortisol modulation and upper respiratory tract claims attract athlete and stress-management segments. French sports nutrition buyers pay 40-60% premiums for documented immunomodulatory strain formulations.
- Weight Management:Satiety signaling and metabolic rate claims require longitudinal intervention studies. Regulatory skepticism in both FDA and EFSA jurisdictions limits commercial penetration.
- Gut Microbiota Balance:Colonization persistence claims demand end-point biopsy validation. Academic medical center partnerships in Germany and the Netherlands build prescriptive recommendation channels.
- Anti-inflammatory:C-reactive protein and cytokine biomarker studies impose clinical trial infrastructure costs. Pharmaceutical-grade culture libraries anchor defensible premium positioning.
Digestive health leads volumes today; immune support is climbing the fastest through athlete-targeted premium tiers.
End User:
Demographic targeting determines strain selection, dosage formulation, and distribution channel strategy across the consumer base.
- Children:Palatability engineering and parental safety concerns drive mild-flavor strain selection. Dutch and German pediatric dietetic practices build prescriptive recommendation pipelines bypassing retail concentration.
- Adults:Workplace snacking and meal replacement occasions concentrate demand in single-serve formats. Health-conscious professionals in France and the Netherlands drive premium positioning through convenience-store distribution.
- Elderly:Medication interaction screening and dysphagia-friendly textures shape product development. German eldercare foodservice procurement mandates third-party viability verification at point of delivery.
- Pregnant Women:Listeria safety protocols and strain-specific pregnancy safety documentation impose manufacturing overhead. Limited commercial penetration reflects liability concentration and niche market sizing.
- Athletes:Recovery-focused formulations with documented cortisol modulation command highest price premiums. Sports nutrition buyers in France and the Netherlands validate performance claims through biomarker monitoring partnerships.
Adults lead volumes today; athletes show the steepest expansion trajectory through recovery-positioned premium tiers.
Packaging Type:
Barrier properties and cold-chain integrity requirements segment formats by shelf-life extension and culture count maintenance.
- Plastic Cups:Modified atmosphere sealing and transparency support retail visibility for fresh-format cheeses. Single-serve portions target convenience-store and foodservice grab-and-go channels.
- Foil Wrappers:Light and oxygen barrier protection extends viable culture counts in block cheese formats. Traditional retail distribution favors cost-efficient wrapping for commodity probiotic tiers.
- Vacuum Bags:Oxygen elimination preserves anaerobic culture viability through extended distribution cycles. Healthcare and institutional procurement in Germany mandates vacuum-sealed formats with temperature logging documentation.
- Tubs:Reclosable designs support multi-serve consumption patterns in household channels. Cream cheese and cottage cheese categories favor tub formats for spreading and mixing applications.
- Paper Boxes:Sustainability positioning targets environmentally conscious consumers in premium retail channels. Barrier coating limitations restrict application to short-shelf-life fresh formats with refrigerated distribution guarantees.
Tubs lead volumes today; vacuum bags are expanding most quickly through healthcare procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical microbiologists and dairy fermentation specialists cluster in the Netherlands, Germany, and France, anchoring Europe's probiotic cheese innovation pipeline. These talent concentrations shape where pharmaceutical-grade strain documentation and cold-vat fermentation advances originate.
Germany
Hospital and eldercare foodservice buyers mandate third-party viability verification at point of delivery, consolidating procurement among three national tendering consortia. EFSA's Article 13.5 health claim requirements drive manufacturers toward pharmaceutical-grade clinical trials. Bavarian equipment suppliers deliver precision temperature control systems that extend culture viability through extended aging cycles.
France
Sports nutrition buyers command 40-60% price premiums for strain-specific recovery formulations with documented cortisol modulation. ANSM and EFSA-aligned strain documentation demands reshape R&D allocation for export-oriented dairies. The Auvergne-Rhône-Alpes cluster hosts pharmaceutical partnerships repurposing clinical infrastructure to meet evolving probiotic standards.
Netherlands
Dutch and German dietetic practices build prescriptive recommendation pipelines bypassing retail concentration, creating direct-to-clinician sampling channels. Healthcare procurement consolidation centralizes buying power among national tendering consortia. Wageningen University anchors academic medical center partnerships validating colonization persistence claims through end-point biopsy studies.
United States
FDA GRAS self-affirmation processes and qualified health claim pathways create compliance cost structures favoring multinational players with dedicated regulatory affairs teams. Health-conscious consumers drive cottage cheese volume through high-protein positioning combined with digestive health claims. Wisconsin and California dairy cooperatives face ERP integration friction as batch-level culture tracking requirements collide with legacy accounting systems.
Japan
METI-backed functional food certification creates expedited pathways for cheddar and mozzarella probiotic variants in baked applications. Thermotolerance technical challenges limit pizza and foodservice penetration, driving microencapsulation-convection oven convergence investments. Tokyo-based importers validate heat-stability claims for grilled and melted cheese applications targeting foodservice channels.
Probiotic Cheese Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade culture libraries and medical nutrition channels, while mid-tier players compete on basic fermentation claims without viability standards. The vendor base stratifies between multinational dairy conglomerates with captive research infrastructure and regional cooperatives dependent on external culture house supply. Three strategic archetypes dominate: pharmaceutical-grade strain documenters, private-label volume suppliers, and grass-fed positioning specialists. Competitive moves concentrate on M&A to secure culture house access and partnerships with clinical trial infrastructure providers.
Within the multinational conglomerate tier, Danone and Lactalis exemplify divergent positioning strategies. Danone leverages pharmaceutical-grade culture libraries to anchor high-margin medical nutrition channels, while Lactalis dominates European retail distribution through simultaneous private-label and branded probiotic lines. Fonterra Co-operative Group occupies a distinct geography-driven position, extending grass-fed dairy positioning into probiotic cheddar exports. These three entities collectively represent the spectrum of competitive approaches: pharmaceutical partnership depth, retail channel breadth, and origin-based export specialization.
| Leading Market Players |
|---|
| Danone |
| Lactalis |
| Arla Foods |
| Fonterra Co-operative Group |
| Cabot Creamery |
| BelGioioso Cheese |
| Beehive Cheese |
| Sargento Foods |
| Organic Valley |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade Lactobacillus rhamnosus GG culture concentrate flows from three European culture houses through tiered pricing structures that stratify across premium, standard, and economy levels based on viability certification and clinical documentation depth.
Pricing Analysis
Live culture guarantees unbundle from basic fermentation claims, creating distinct service tiers where pharmaceutical-grade strain documentation commands substantial premiums over commodity offerings. Price differentiation hinges on EFSA Article 13.5 approval status and third-party viability verification at point of delivery. Pricing pressure stems from mid-tier manufacturers retreating to basic positioning as clinical trial costs compress margins. Healthcare procurement buyers in Germany show least price sensitivity due to mandated quality standards, while private-label retail channels in France exhibit highest sensitivity to per-unit culture costs.
Supply Chain Analysis
Direct-to-clinician sampling channels bypass retail concentration through partnerships with Dutch and German dietetic practices, while traditional wholesale distributors lose share to specialized logistics operators with real-time temperature logging. Supply concentrates in the Netherlands, Germany, and France where clinical microbiologist talent clusters anchor strain characterization capabilities. Raw material dependencies include pharmaceutical-grade culture libraries, lipid-matrix microencapsulation inputs, and precision temperature control equipment. Single-source vulnerability pervades the Lactobacillus rhamnosus GG supply base where three culture houses control majority share. Distribution runs through healthcare procurement consortia in Germany, specialized cold-chain operators in the Netherlands, and retail concentration in France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in athlete-targeted recovery formulations where documented cortisol modulation supports premium positioning, while cold-vat fermentation advances reduce viable culture loss rates across aging cycles.
For Market Incumbents: To counter thermotolerance technical ceilings in hard cheese applications above 180°C, anchor R&D investment in spray-dried lipid coating with controlled-release matrix technology. Secure exclusive strain documentation positions through pharmaceutical partnerships repurposing clinical infrastructure to meet EFSA's updated Article 13.5 requirements before competitors lock up health claim approvals. For New Entrants and Emerging Players: The 40-60% price premium gap between athlete recovery formulations and basic digestive health positioning opens white-space entry through sports nutrition channels in France and the Netherlands. Target Japanese METI-certified functional food pathways for cheddar and mozzarella probiotic variants where thermotolerance validation protocols remain underdeveloped. Build direct-to-clinician sampling relationships with Dutch dietetic practices to bypass retail concentration. For Investors and Strategic Acquirers: Roll-up economics work for regional dairies with pharmaceutical-grade culture house access because EFSA's tightened documentation requirements favor acquired clinical trial infrastructure over greenfield investment. Monitor strain-specific approval precedents as inflection indicators for exclusive health claim positioning value. Prioritize targets with existing partnerships with German equipment suppliers delivering precision temperature control systems.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Strain Documentation | EFSA Article 13.5 compliance secures exclusive medical nutrition channel positioning against commodity competitors. |
| Cold-Vat Fermentation Equipment Deployment | German precision temperature control systems extend culture viability through extended aging cycles for hard cheese applications. |
| Microencapsulation-Convection Oven Convergence | Spray-dried lipid coating with controlled-release matrices enables viable culture survival in high-heat prepared foods. |
| Direct-to-Clinician Sampling Channel Development | Partnerships with Dutch and German dietetic practices build prescriptive recommendation pipelines bypassing retail concentration. |
| Asian Foodservice Export Certification | Japan's METI-backed functional food certification creates expedited pathways for thermotolerant cheddar and mozzarella variants. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy fermentation specialists, clinical microbiologists, hospital procurement managers, and sports nutrition buyers with secondary validation through EFSA guidance documents, FDA GRAS notifications, and METI functional food certification records. Bottom-up strain-level production estimates triangulated against top-down retail audit data and healthcare procurement database extracts.
Historical reference periods anchored the projection horizon through verified baseline culture viability rates and pricing tier distributions across the analysis window. Segmentation dimensions modeled include product type matrix, application claim substantiation level, end-user demographic targeting, and packaging barrier technology tier. CAGRs derived from strain-specific adoption curves and regional regulatory pathway timelines, incorporating thermotolerance technical ceiling progression and cold-chain infrastructure development as industry-specific forecast inputs.
Caveats apply where EFSA strain-specific approval precedents, batch contamination events at concentrated culture houses, or thermotolerance breakthrough timing could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Dairy Dessert and Yogurt Market
Dairy Products
Gruyere Market
Dairy Products
Low Fat Cheese Market
Dairy Products
Organic Dairy Products Market
Dairy Products
India Milk Protein Market
Dairy Products
Low Fat Butter Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
Solidified Yogurt Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Savory Dairy Products Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Latin America Cheese Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
Lactose-Free Cheese Market