
 Kefir Market | 2026-2036
Kefir Market Size, Share, and Industry Trends Forecast 2026-2036
Kefir Market Analysis
Specialty retail and direct-to-consumer channels are reshaping how kefir reaches end users, bypassing traditional grocery intermediaries. Lifeway Foods controls the branded probiotic positioning in North American health food stores. Groupe Lactalis leverages its dairy processing infrastructure to anchor European kefir supply. Danone S.A. competes through diversified fermented dairy portfolios spanning multiple continents.
Kefir is a fermented milk or water-based beverage produced through the action of kefir grains containing lactic acid bacteria, acetic acid bacteria, and yeast in a symbiotic culture; the fermentation typically occurs at 20-25°C over 12-48 hours, yielding a tart, effervescent drink with live probiotic content valued for gut health applications. Milk kefir dominates current revenue pools due to established dairy supply chains and consumer familiarity, while dairy-free kefir alternatives from coconut, oat, and almond bases represent the fastest-expanding segment as lactose-intolerant and vegan populations expand. Powdered kefir concentrates occupy a niche but growing position in travel and emergency food kits where refrigeration access is limited.
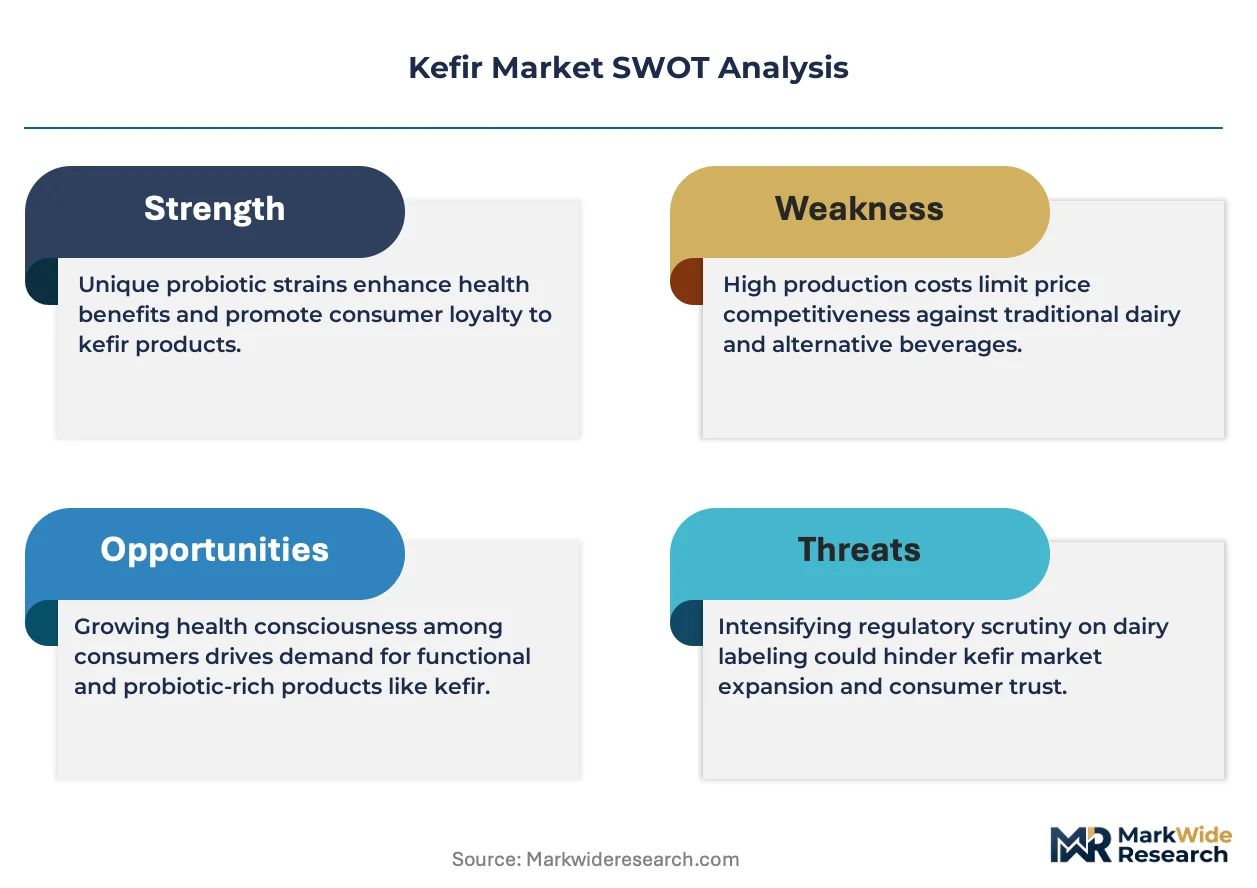
EU EFSA health claim regulations constrain how kefir brands communicate probiotic benefits, forcing reformulation toward documented strains. FDA GRAS notifications and FSMA preventive controls govern U.S. import and domestic production standards for live-culture beverages. Stakeholders must monitor evolving strain-specific clinical evidence requirements that will determine which products retain premium positioning versus commodity dairy alternatives.
Market Dynamics
Fermentation technology maturation and clean-label regulatory pressure are compressing production timelines while expanding strain-specific probiotic positioning. EFSA documentation requirements and FDA preventive controls are forcing manufacturers to invest in clinical validation infrastructure ahead of competitors.
Growth Catalysts
- EU Green Deal agricultural standards:Subsidies for sustainable dairy processing incentivize kefir producers to adopt renewable energy in fermentation facilities.
- Fitness center channel expansion:Wellness-oriented gyms in Germany and the United States now stock refrigerated kefir as post-workout recovery beverages.
- Precision fermentation:Controlled bioreactor systems enable consistent kefir grain culture propagation at industrial scale.
Market Restraints
- Raw milk input volatility:Dairy commodity price swings compress margins for traditional milk kefir producers dependent on spot purchasing.
- EFSA health claim substantiation:Strain-specific clinical trial requirements block probiotic messaging for products lacking documented efficacy data.
- Plant-based substitution threat:Oat and coconut milk alternatives attract lactose-intolerant consumers away from dairy-derived kefir.
Strategic Opportunities
- Russia's underpenetrated retail modern trade:Convenience store chains in Moscow and Saint Petersburg lack dedicated fermented dairy sections.
- Direct-to-subscription channel innovation:Cold-chain home delivery services bypass traditional grocery markups for recurring revenue.
- FSMA preventive control harmonization:Standardized U.S. safety protocols reduce compliance fragmentation for multi-state distribution.
Industry Challenges
- Microbiologist talent scarcity:Symbiotic culture maintenance requires specialized fermentation science expertise rarely taught in standard food technology programs.
- Clean-label certification timelines:Organic and non-GMO verification processes delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kefir Market |
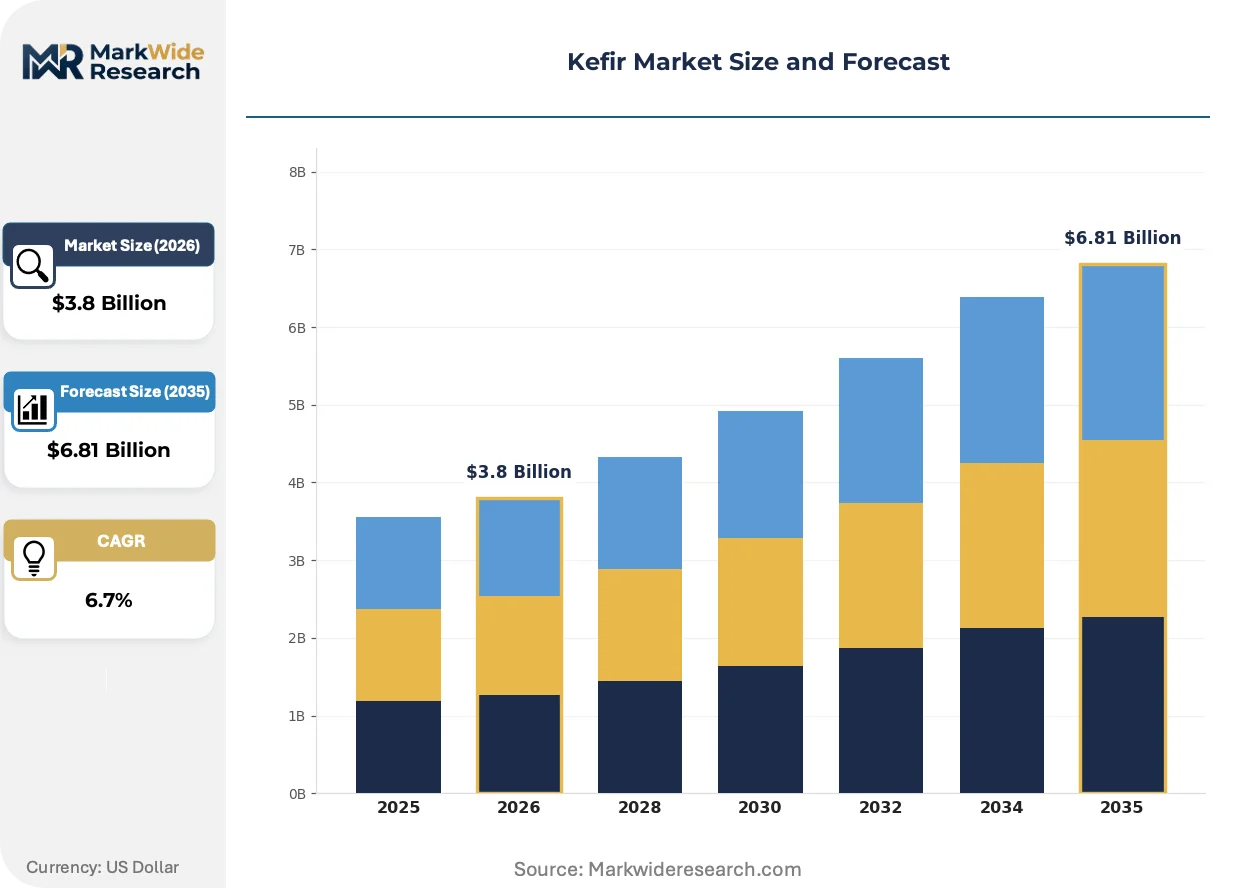
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Kefir, Water Kefir, Flavored Kefir, Dairy-Free Kefir Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Shops End User: Households, Cafés, Restaurants, Fitness Centers Form: Liquid, Powder, Granules, Concentrate |
| Companies Covered | Groupe Lactalis S.A., Nestlé S.A., Danone S.A., The Hain Celestial Group, Valio Ltd, Lifeway Foods, Inc., FrieslandCampina N.V., Chobani, LLC, Arla Foods amba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kefir Market Emerging Trajectories
Digital monitoring systems and strain banking protocols are virtualizing quality assurance in kefir production. Regulatory documentation automation and consumer traceability demands are accelerating investment in production transparency infrastructure.
Continuous pH and temperature monitoring via IoT sensors is virtualizing batch consistency control. Mid-sized producers in Germany and the United States deploy these systems to reduce manual sampling labor. Real-time data streams enable predictive intervention before culture stress degrades probiotic counts.
EFSA's evolving strain-specific health claim framework forces reformulation toward documented bacterial strains. Manufacturers must commission human intervention studies to retain premium positioning against commodity yogurt. German and French producers lead investment in clinical validation partnerships.
Wellness-oriented households now prioritize subscription-based kefir delivery over supermarket purchasing. Direct-to-consumer channels in the United States and Russia capture recurring revenue through customized flavor and fat-content preferences. Urban clusters in Berlin, Moscow, and Chicago show highest adoption of auto-replenishment models.
Kefir Market Segmentation
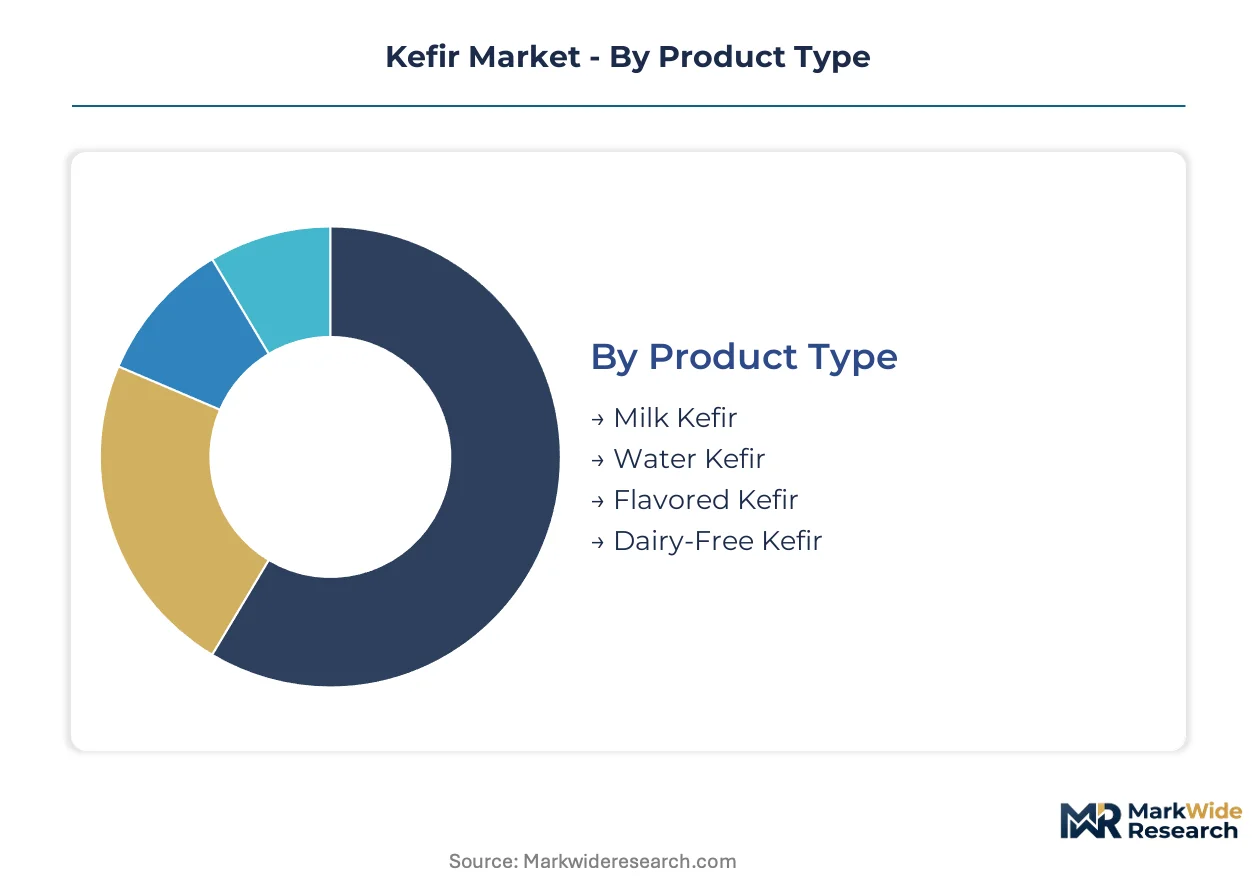
Kefir producers calibrate portfolio depth against refrigeration requirements and culture viability windows. Segmentation strategy determines whether brands compete on probiotic potency, convenience formats, or channel-specific positioning.
Product Type:
After-sales intensity varies sharply across kefir categories, with live-culture products demanding cold-chain maintenance and consumer education on storage protocols.
- Milk Kefir:Fermented dairy beverage produced from cow, goat, or sheep milk using symbiotic kefir grain cultures containing lactic acid bacteria and yeast. Demand concentrates in German and Russian households with established fermented dairy consumption habits, constrained by raw milk price volatility and seasonal supply fluctuations.
- Dairy-Free Kefir:Plant-based alternatives fermented from coconut, oat, or almond bases using adapted starter cultures. German and U.S. wellness-oriented consumers drive adoption fastest, propelled by lactose intolerance prevalence and vegan dietary shifts.
- Water Kefir:Non-dairy fermented beverage using tibicos cultures in sugar-water solution, producing a lighter, effervescent probiotic drink.
- Flavored Kefir:Milk or water kefir with added fruit, vanilla, or herbal infusions to mask tartness and broaden palate appeal.
Milk kefir holds the largest share; momentum sits with dairy-free alternatives.
Distribution Channel:
Cost tier stratification separates premium-positioned kefir from mass-market equivalents, with channel selection directly determining margin structure and brand positioning.
- Supermarkets:Mainstream retail channel carrying both branded and private-label kefir in refrigerated dairy sections. Russian and U.S. urban supermarkets move highest volumes, though slotting fees and promotional spending compress net margins for emerging brands.
- Online Retail:Direct-to-consumer and third-party e-commerce platforms enabling subscription models and flavor customization. Berlin and Chicago households show steepest adoption curves, driven by auto-replenishment convenience and cold-chain logistics maturation.
- Health Food Stores:Specialty retailers emphasizing organic certification, raw milk sourcing, and artisanal production narratives.
- Specialty Shops:Ethnic grocery and farmers market vendors targeting Russian, Eastern European, and Middle Eastern diaspora communities.
Supermarkets dominate volume; online retail gains share fastest.
End User:
Application-specific formulation requirements diverge sharply between household consumption and foodservice operations, dictating packaging formats and probiotic count specifications.
- Households:Individual and family consumers purchasing retail-format kefir for daily probiotic intake and meal accompaniment. German households lead per-capita consumption, supported by EFSA-aligned health literacy and established fermentation traditions.
- Fitness Centers:Wellness facilities stocking kefir as post-workout recovery beverages with protein and electrolyte positioning. U.S. boutique gym chains in metropolitan markets drive channel-specific demand, requiring portable single-serve packaging and sports-focused branding.
- Cafés:Coffee shops and juice bars incorporating kefir into smoothies, breakfast bowls, and functional beverage menus.
- Restaurants:Full-service and fast-casual dining operations using kefir in dressings, marinades, and digestive health-focused menu items.
Households anchor consumption volume; fitness centers show the steepest expansion trajectory.
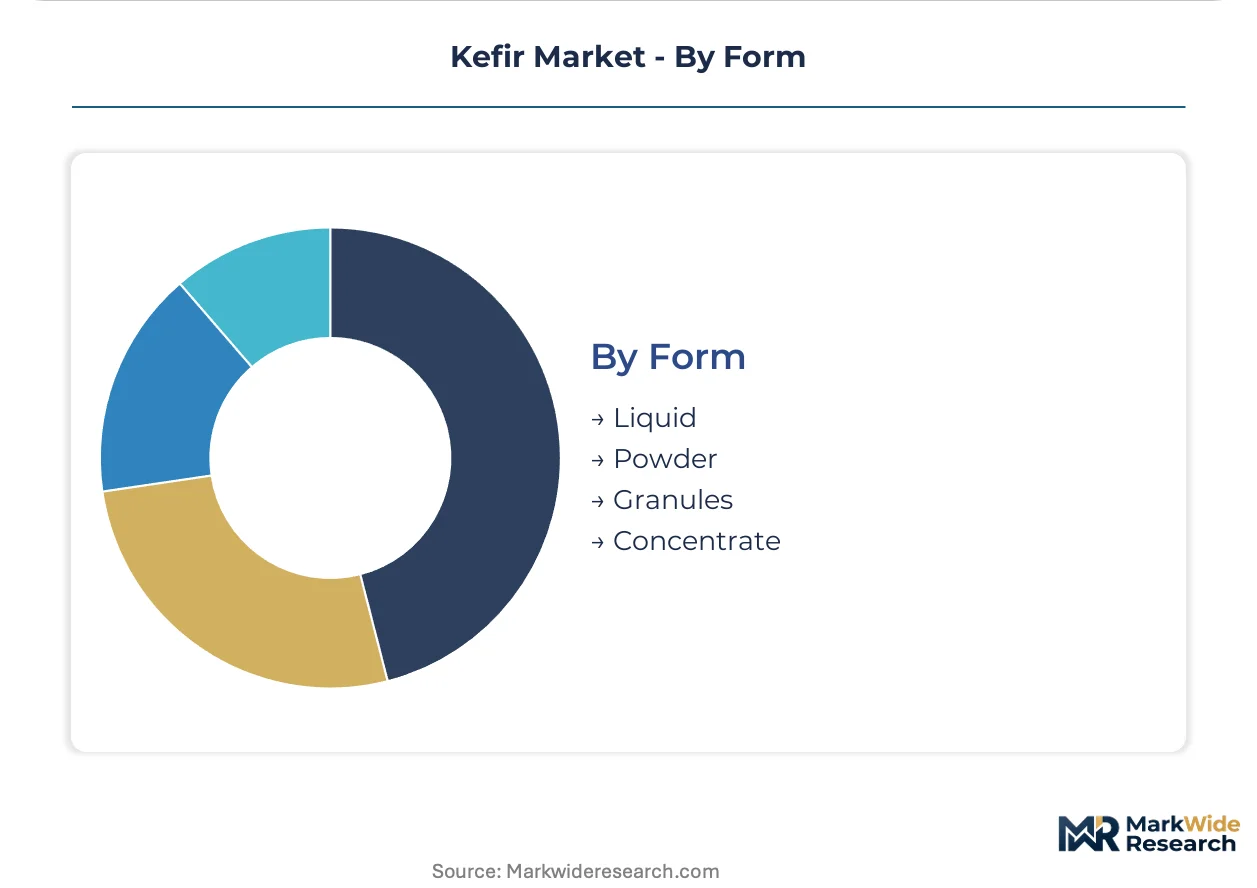
Form:
Supply concentration in liquid kefir production reflects dairy processing infrastructure dominance, while alternative formats address distribution gaps and usage occasion fragmentation.
- Liquid:Standard refrigerated kefir in bottles or cartons requiring continuous cold-chain maintenance. Production clusters in Germany, Russia, and the United States leverage existing dairy plant fermentation capacity and established distribution networks.
- Powder:Dehydrated kefir concentrate with extended shelf stability for travel, emergency kits, and military rations. Niche demand concentrates in outdoor recreation and preparedness segments where refrigeration access is unreliable.
- Granules:Freeze-dried kefir grains for home fermentation enthusiasts seeking culture reusability and cost reduction.
- Concentrate:Reduced-water formulations for dilution prior to consumption, optimizing transport efficiency and storage footprint.
Liquid commands the revenue base; powder formats climb fastest among alternative segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal agricultural standards subsidize renewable energy adoption in fermentation facilities, reshaping production economics across major kefir-producing nations. Germany, Russia, and the United States concentrate demand, with regulatory frameworks from EFSA and FDA governing probiotic health claims and safety protocols respectively.
Germany
Wellness-oriented households in Berlin and Munich drive per-capita consumption leadership, supported by established fermentation traditions and EFSA-aligned health literacy. The EU Green Deal provides direct subsidies for sustainable dairy processing infrastructure. Bavarian dairy cooperatives leverage precision fermentation technology to scale kefir grain culture propagation.
Russia
Moscow and Saint Petersburg consumers maintain deep-rooted fermented dairy consumption habits, though modern trade retail penetration remains incomplete. Domestic regulators emphasize traditional food safety standards alongside emerging probiotic labeling requirements. Convenience store chains in the capital region lack dedicated fermented dairy sections, creating whitespace for branded entry.
United States
Fitness centers in metropolitan markets stock refrigerated kefir as post-workout recovery beverages, while Chicago and coastal urban clusters adopt subscription-based home delivery models. FDA GRAS notifications and FSMA preventive controls govern live-culture beverage production standards. Cold-chain logistics maturation enables direct-to-consumer channels to bypass traditional grocery markups.
France
Consumers in Paris and Lyon demonstrate sophisticated demand for strain-specific probiotic positioning, driving clinical validation investment among domestic producers. EFSA health claim substantiation requirements force reformulation toward documented bacterial strains. Producers in the Île-de-France region lead European investment in human intervention studies for premium positioning.
United Kingdom
London health food stores and specialty retailers emphasize organic certification and artisanal production narratives for differentiated positioning. Post-Brexit regulatory divergence from EU EFSA frameworks creates compliance complexity for cross-border suppliers. Urban clusters in Greater London show highest adoption of flavored kefir variants targeting palate expansion beyond traditional tartness.
Kefir Market Vendor Landscape
On the supply side, the industry is moderately consolidated around diversified dairy multinationals and specialized fermented beverage specialists. Tiered competitive positioning separates premium strain-documented offerings from commodity dairy alternatives. Three archetypes dominate: legacy dairy processors leveraging existing fermentation infrastructure, dedicated probiotic beverage specialists, and plant-based challengers attacking lactose-intolerant segments. Dominant competitive moves include clinical validation partnerships for EFSA compliance and direct-to-consumer channel buildout to capture recurring revenue.
Within the legacy dairy processor tier, Groupe Lactalis S.A. and Danone S.A. exemplify scale-driven positioning through diversified fermented dairy portfolios spanning multiple continents. Lifeway Foods, Inc. occupies a specialist position representing North American probiotic-focused branding in health food retail channels. These three entities collectively illustrate the strategic divergence between infrastructure-heavy multinational approaches and niche health-positioned specialist models.
| Leading Market Players |
|---|
| Groupe Lactalis S.A. |
| Nestlé S.A. |
| Danone S.A. |
| The Hain Celestial Group |
| Valio Ltd |
| Lifeway Foods, Inc. |
| FrieslandCampina N.V. |
| Chobani, LLC |
| Arla Foods amba |
| Others |
Supply Flow & Price Mechanics
Overcapacity in German dairy fermentation facilities is compressing spot milk procurement leverage while simultaneously eroding pricing power for commodity-grade kefir, forcing producers to differentiate through strain-documented premium positioning or absorb margin erosion.
Pricing Analysis
Volume-discount tiering structures separate subscription-based direct-to-consumer kefir from mass-market supermarket placements, with German and U.S. wellness households absorbing premium markups for EFSA-aligned strain documentation while Russian convenience channels remain acutely price-sensitive to raw milk commodity swings. Price differentiation hinges on certification grade and cold-chain reliability, with organic and non-GMO verification commanding measurable premiums. Pricing pressure stems from oat and coconut milk alternatives displacing lactose-intolerant demand. Fitness centers and health food stores exhibit lowest price sensitivity; Russian mass retail shows highest.
Supply Chain Analysis
Upstream feedstock dependence on cow milk from Germany, Russia, and the United States anchors production geography, with kefir grain culture propagation requiring specialized microbiologist labor concentrated in Bavarian and Île-de-France fermentation science programs. Raw material inputs encompass dairy commodities, adapted plant-based bases, and tibicos cultures for water kefir variants. Supply chain risk centers on single-source vulnerability for kefir grain cultures, where contamination events propagate batch failures. Distribution runs through refrigerated trucking networks into supermarket dairy cases, with direct-to-consumer cold-chain logistics emerging as an alternative downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against plant-based fermented beverages, as oat and coconut milk alternatives capture lactose-intolerant and vegan consumers previously tethered to dairy-derived kefir.
For Market Incumbents: Harden strain-specific clinical validation infrastructure to meet EFSA substantiation thresholds before competitors commoditize probiotic messaging. Deepen backward integration into kefir grain culture banking to reduce single-source contamination exposure. Anchor premium positioning through documented efficacy data that plant-based substitutes cannot replicate.
For New Entrants and Emerging Players: Pursue Russia's underpenetrated convenience store channel in Moscow and Saint Petersburg, where dedicated fermented dairy sections remain absent. Target U.S. fitness center white space with portable single-serve formats and sports-focused branding. Launch through direct-to-subscription models to bypass supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer kefir specialists with established cold-chain logistics and auto-replenishment algorithms. Long-term viability favors acquisition targets combining precision fermentation capabilities with EFSA-compliant strain documentation. Watch for inflection in EFSA health claim rulings that would elevate documented strains above commodity competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Documentation Investment | Human intervention studies satisfy EFSA requirements for premium probiotic positioning against yogurt substitutes. |
| Direct-to-Consumer Channel Buildout | Subscription models in Berlin and Chicago capture recurring revenue while bypassing supermarket promotional spending. |
| Precision Fermentation Scale-Up | Controlled bioreactor systems reduce manual culture maintenance labor and improve batch consistency. |
| Plant-Based Line Extension | Oat and coconut kefir alternatives defend against lactose-intolerant consumer migration to non-fermented substitutes. |
| Russia Retail Modern Trade Entry | Convenience store chain partnerships in Moscow address whitespace in dedicated fermented dairy sections. |
Methodological Framework
Operator-level perspectives from kefir production microbiologists, dairy procurement managers at German cooperatives, U.S. health food store category buyers, and Russian convenience chain executives anchored the qualitative base. Secondary validation drew from EFSA health claim registers, FDA GRAS notification databases, EU Green Deal agricultural subsidy disclosures, and German dairy federation processing statistics. Bottom-up volume modeling triangulated against top-down category spend analysis.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product type, distribution channel, end user, and form. CAGRs derived from exponential smoothing of historical volume trajectories adjusted for regulatory inflection points and channel shift elasticity. Forecast inputs incorporated EFSA strain documentation timelines and cold-chain logistics maturation curves.
Sensitivities concentrate around EFSA health claim rulings, raw milk commodity volatility, and plant-based substitution acceleration. Cross-checking against German dairy federation production statistics and U.S. refrigerated beverage import volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Africa Yogurt Market
Dairy Products
North America Cheese Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
United States Milk Protein Market
Dairy Products
Skim Milk Powder Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Table Butter Market
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market
Dairy Products
Japan Casein Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Canada Dairy Market
Dairy Products
High Protein Yogurt Market