
 Organic Dairy Market | 2026-2036
Organic Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Dairy Market Intelligence
Subscription-based milk delivery and farm-share programs is consolidating recurring revenue into producer balance sheets. Organic Valley leverages cooperative ownership to sustain price premiums across member farms. Arla Foods amba anchors European supply through its farmer-owned structure. Danone SA competes in fermented organic segments with specialized yogurt cultures.
Organic dairy denotes milk and derivative products sourced from livestock raised on certified organic feed without synthetic hormones or antibiotics, with pasteurization temperatures and bacterial counts governed by food safety protocols. The primary commercial purpose centers on delivering verified clean-label nutrition to health-conscious buyers. Milk retains the largest volume position among product types, while yogurt captures expanding margin pools through probiotic positioning. Supermarkets dominate distribution channel flows, though online retail is accelerating fastest in urban delivery zones.
USDA organic certification, EU Organic Regulation, and FDA dairy safety standards collectively define input compliance, processing transparency, and cross-border market access for participants. EFSA guidelines on residue limits further constrain antibiotic traceability thresholds in exported finished goods. Stakeholders must monitor evolving national organic equivalence agreements that determine which certifying bodies gain mutual recognition.
Market Dynamics
EU Green Deal emissions mandates are compressing cold-chain logistics margins while simultaneously accelerating processing capacity consolidation in Germany and Denmark. Organic feed certification bottlenecks now constrain herd expansion timelines more than capital availability.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates are forcing cold-chain operators to retrofit fleets with CO2-based systems, creating captive demand for certified organic logistics providers with compliant infrastructure.
- Clean-label procurement:German retail chains now require third-party organic certification for private-label dairy SKUs, converting conventional shelf space into verified organic placement.
- Pasteurization monitoring:IoT-enabled bacterial count sensors are reducing batch rejection rates at organic processing plants, tightening yield recovery and margin capture.
Market Restraints
- Organic feed cost volatility:Non-GMO soybean and alfalfa price swings in Ukraine and Argentina transmit directly into farm-gate milk production costs, compressing processor margins.
- Herd conversion timelines:USDA organic certification requires 12 months of organic feed transition before milk qualifies, creating supply inelasticity during demand spikes.
- Antibiotic residue thresholds:EFSA maximum residue limits for exported finished goods are stricter than domestic standards, blocking market access for non-compliant batches.
Strategic Opportunities
- Urban subscription channels:Direct-to-consumer delivery platforms in London and Paris are capturing recurring revenue streams previously held by supermarket intermediaries.
- Probiotic strain differentiation:Specialized yogurt cultures with documented gut-health claims command shelf-space premiums in pharmacy and wellness retail formats.
- Carbon credit stacking:Methane capture installations at anaerobic digesters in the Netherlands generate tradable offsets alongside biogas revenue, diversifying farm income.
Industry Challenges
- Veterinary compliance documentation:Organic herds require individual animal health records spanning 24 months, overwhelming farm administrative capacity and delaying certification renewals.
- Multi-standard equivalence mapping:Divergent USDA, EU Organic Regulation, and Swiss BIO SUISSE requirements force exporters to maintain parallel certification tracks, inflating audit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Dairy Market |
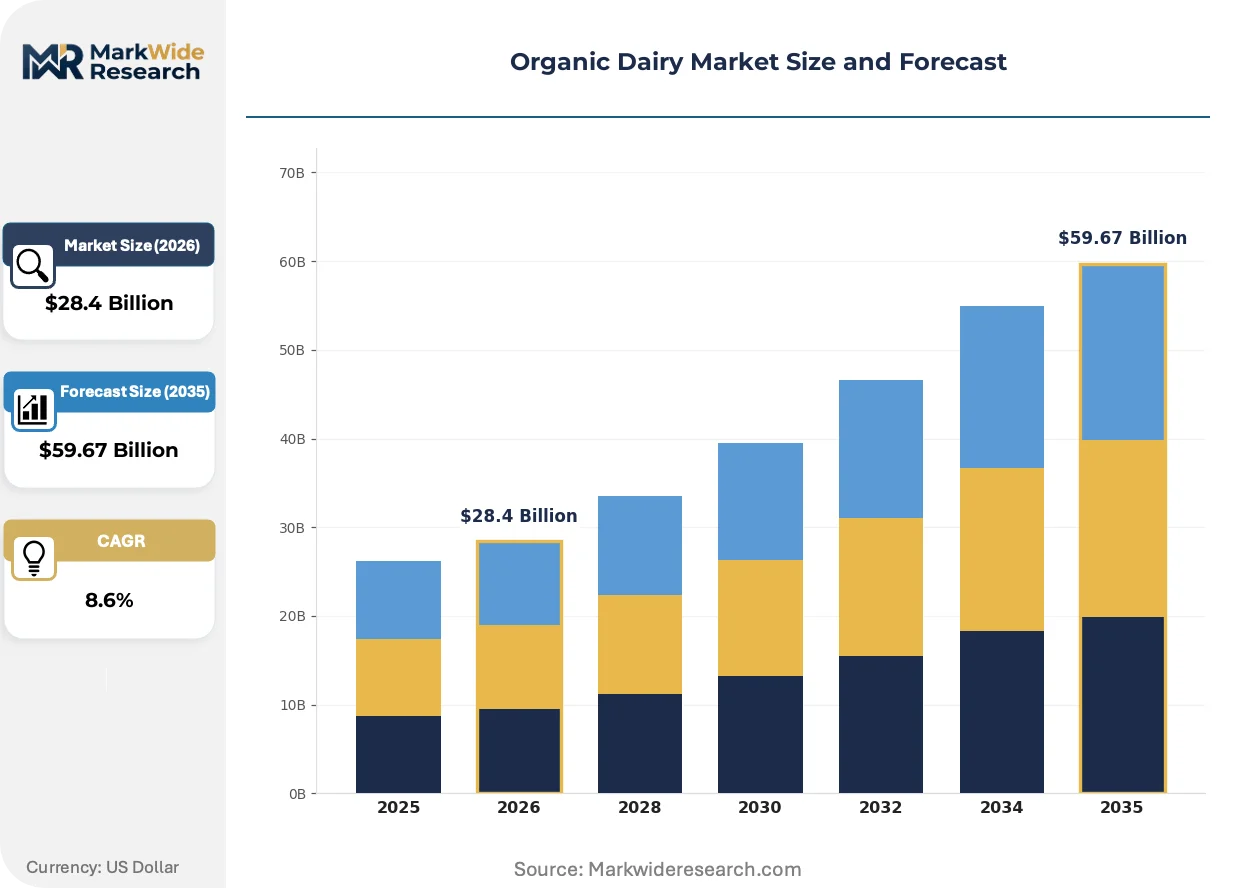
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $59.67 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter End User: Retail Consumers, Food Service, Institutional Buyers, Exporters Packaging Type: Bottles, Tetra Packs, Cartons, Pouches Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Farmers Markets |
| Companies Covered | Aurora Organic Dairy, Groupe Lactalis, Arla Foods amba, Nestlé S.A., Horizon Organic Dairy LLC, Organic Valley, Fonterra Co-operative Group Ltd., Straus Family Creamery Inc., Danone SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Dairy Market Strategic Shifts & Innovations
Processing transparency and feed traceability are converging into unified digital verification platforms that replace paper-based audit trails. Cold-chain emissions monitoring now sits alongside bacterial safety protocols as a core operational discipline.
Blockchain-enabled supply chain verification is unifying feed origin documentation, veterinary records, and processing logs into single-source-of-truth databases accessible to retailers and regulators. Danish cooperatives are deploying these systems fastest, with full-herd traceability now standard for export-bound milk. The technology is compressing certification audit cycles from quarterly to real-time, reducing compliance labor while tightening fraud detection.
EU Green Deal Farm to Fork Strategy mandates 25% organic farmland share by 2030, redirecting CAP subsidies toward conversion cost coverage and technical assistance. Dairy processors in France and Ireland are securing multi-year feed contracts to lock in supply from converting conventional farms. The policy is accelerating herd expansion in member states with existing organic infrastructure, particularly the Netherlands and Austria.
Direct farm-share subscriptions are displacing supermarket intermediaries in metropolitan delivery zones, with consumers accepting longer fulfillment windows for verified single-source provenance. Berlin and Copenhagen show the highest penetration of these models, where weekly delivery slots sell out months in advance. The channel shift is compressing price discovery transparency, as farm-gate pricing now varies by membership tier rather than commodity exchange benchmarks.
Organic Dairy Market Segmentation
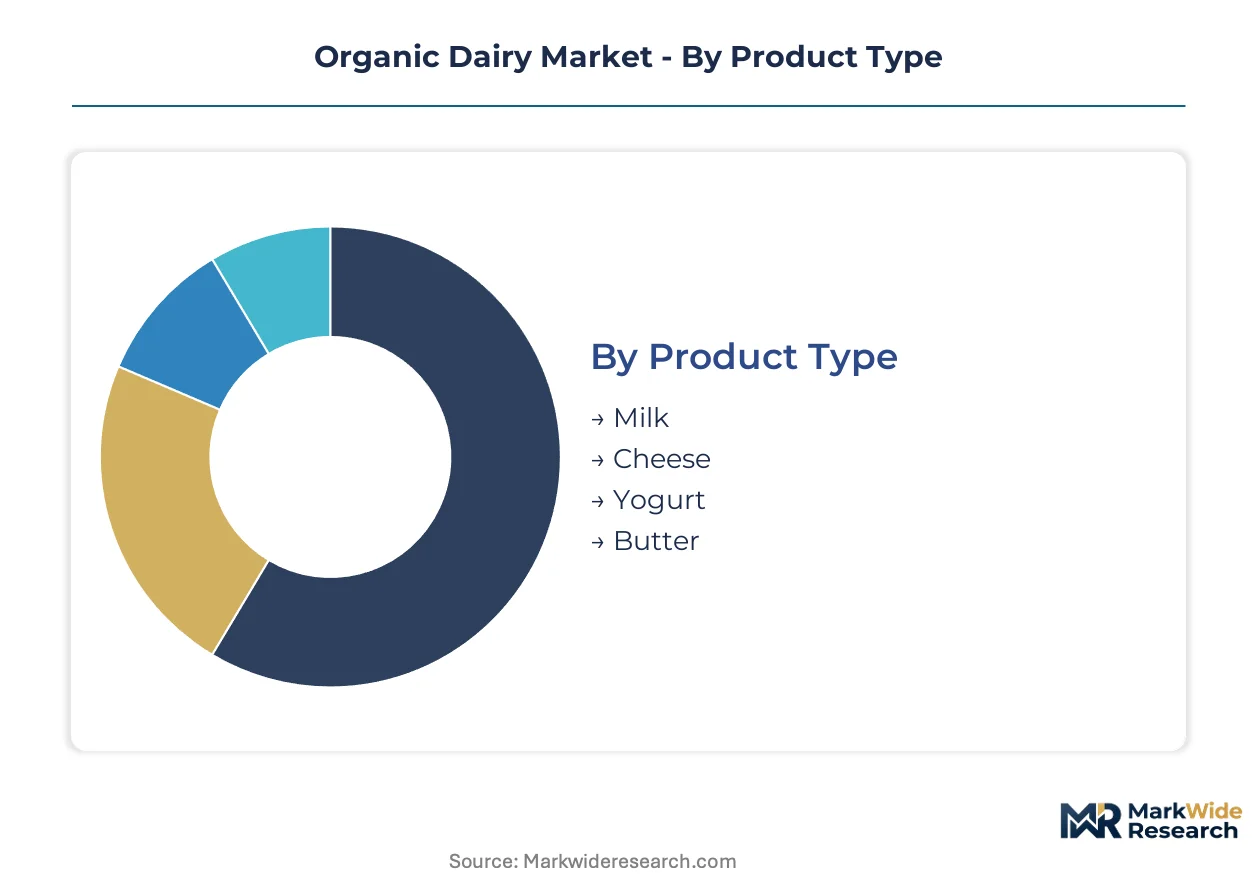
Organic dairy segmentation separates commodity milk flows from value-added derivatives, with each tier commanding distinct margin structures and certification requirements. Channel and packaging choices increasingly determine cold-chain compliance costs and consumer price acceptance.
Product Type:
Volume concentration versus premium capture splits sharply across this category, with fluid milk dominating tonnage while fermented products extract higher unit economics.
- Milk:Standardized at 3.25% fat content for whole milk variants, with homogenization and HTST pasteurization protocols governed by FDA dairy safety standards. German retail chains now mandate third-party organic certification for private-label fluid milk SKUs, converting conventional shelf space into verified placement under EU Organic Regulation compliance.
- Yogurt:Fermented with specialized probiotic cultures including Lactobacillus acidophilus and Bifidobacterium strains, delivering documented gut-health claims. Pharmacy and wellness retail formats in France and Switzerland command shelf-space premiums for certified organic yogurt with live culture counts exceeding 10^8 CFU per gram.
- Cheese:Aged varieties require extended organic certification documentation for milk inputs spanning 24 months.
- Butter:Churned from certified organic cream with butterfat minimums of 80% under USDA organic standards.
Mature deployment sits with Milk. Newer deployment is concentrated in Yogurt.
End User:
Procurement patterns diverge between recurring household subscriptions and institutional tender processes with multi-year contract horizons.
- Retail Consumers:Direct-to-consumer delivery platforms in London and Paris capture recurring revenue streams previously held by supermarket intermediaries, with weekly delivery slots selling out months in advance.
- Food Service:Restaurant and café operators require consistent fat content specifications for menu standardization across multi-location chains.
- Institutional Buyers:School districts and hospital systems mandate EFSA-compliant residue documentation for antibiotic traceability thresholds stricter than domestic standards.
- Exporters:Divergent USDA, EU Organic Regulation, and Swiss BIO SUISSE requirements force parallel certification tracks, inflating audit costs for cross-border shipments.
Volume concentration centers on Retail Consumers. Margin expansion is climbing the fastest in Food Service.
Packaging Type:
Cold-chain emissions compliance and shelf-life extension drive material selection, with F-Gas Regulation refrigerant phase-down mandates favoring certain formats.
- Bottles:HDPE and glass formats dominate home delivery channels where returnable systems reduce per-unit packaging costs.
- Tetra Packs:Aseptic carton technology enables ambient distribution with six-month shelf stability, reducing refrigerated logistics intensity.
- Cartons:Gable-top paperboard with polyethylene liners balances recyclability claims with moisture barrier performance.
- Pouches:Flexible film formats reduce shipping cube and material weight for e-commerce fulfillment operations.
Established infrastructure supports Bottles. Emerging adoption concentrates in Tetra Packs.
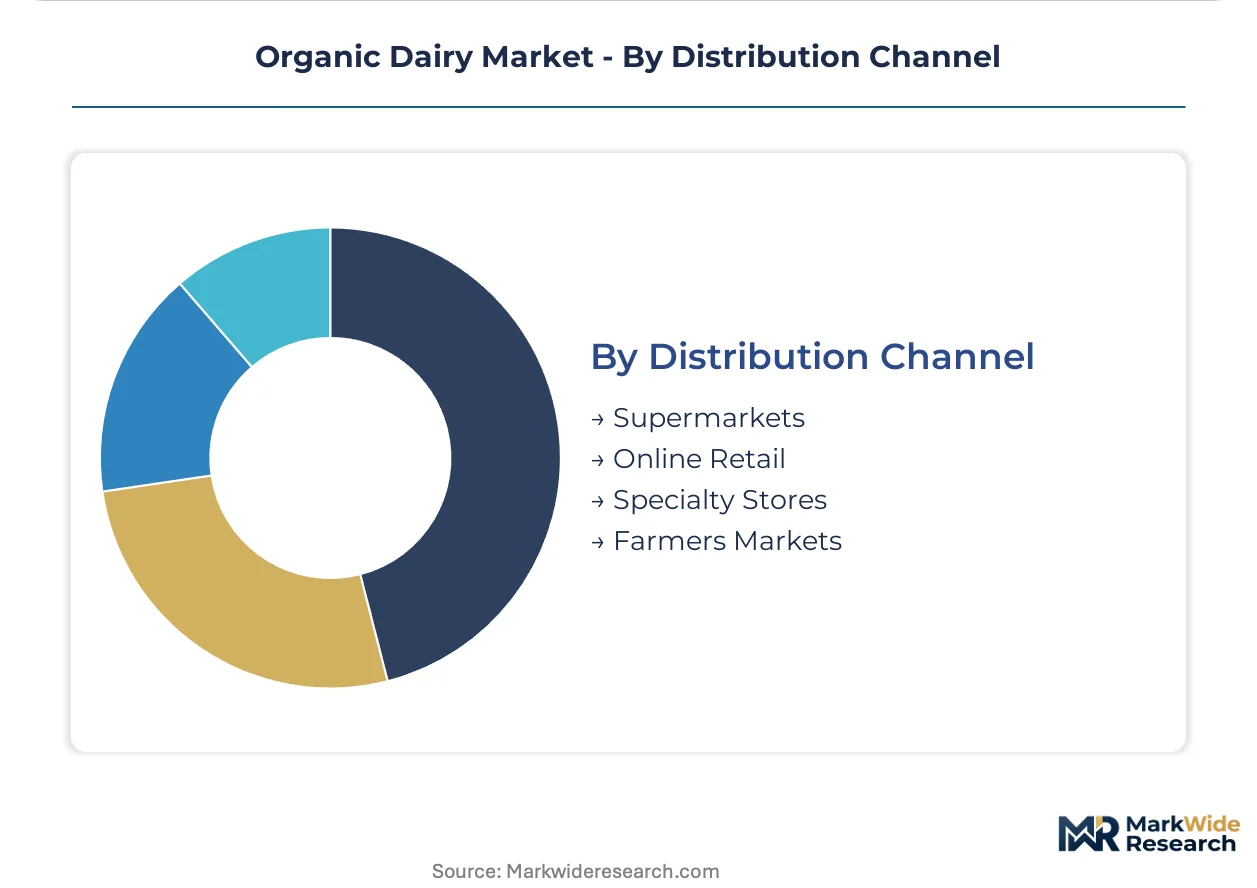
Distribution Channel:
Channel selection determines price discovery transparency and certification audit frequency, with direct models compressing intermediary margins.
- Supermarkets:Dominant flow channel with established slotting fee structures and quarterly certification audits for private-label placement.
- Online Retail:Urban delivery zones in Berlin and Copenhagen show highest penetration, with consumers accepting longer fulfillment windows for verified single-source provenance.
- Specialty Stores:Natural food retailers emphasize probiotic strain differentiation and extended shelf-life organic butter varieties.
- Farmers Markets:Direct farm-share subscriptions displace price benchmarks with membership-tier pricing varying by commitment duration.
Current revenue concentration rests with Supermarkets. Steepest expansion trajectory appears in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copenhagen anchors organic dairy innovation through farm-share subscription density and cold-chain emissions compliance infrastructure that exceeds EU Green Deal mandates.
Germany
Berlin and Hamburg drive subscription-based milk delivery penetration, with weekly delivery slots selling out months in advance. The EU Organic Regulation governs private-label certification requirements for retail chains. Bavaria concentrates processing capacity expansion, where anaerobic digester installations now generate biogas alongside carbon credit revenue streams.
United States
Wisconsin and California dairy corridors sustain cooperative ownership structures that stabilize farm-gate pricing across member networks. USDA organic certification mandates 12-month feed transition timelines that constrain supply elasticity. The Pacific Northwest clusters IoT-enabled pasteurization monitoring deployments that reduce batch rejection rates at processing plants.
France
Paris and Lyon metropolitan zones capture direct-to-consumer delivery platform growth previously held by supermarket intermediaries. The EU Farm to Fork Strategy redirects CAP subsidies toward organic farmland conversion cost coverage. Normandy and Brittany secure multi-year feed contracts to lock in supply from converting conventional farms.
Denmark
Copenhagen's urban delivery zones show highest farm-share subscription penetration, with consumers accepting longer fulfillment windows for verified single-source provenance. Danish cooperatives deploy blockchain-enabled supply chain verification fastest, with full-herd traceability now standard for export-bound milk. Jutland processing facilities consolidate capacity under F-Gas Regulation refrigerant phase-down compliance mandates.
Netherlands
Randstad urban corridors accelerate online retail channel expansion for organic dairy fulfillment. EFSA maximum residue limits for exported finished goods enforce stricter antibiotic traceability thresholds than domestic standards. Friesland and Gelderland concentrate methane capture infrastructure at anaerobic digesters, generating tradable carbon offsets alongside biogas revenue.
Organic Dairy Market Key Industry Players
Capital-heavy producers compete with asset-light designers across cooperative, publicly traded, and privately held ownership structures. The market consolidates around farmer-owned cooperatives that sustain price premiums through member governance, publicly traded multinationals with diversified fermented product portfolios, and regional specialists with single-source provenance claims. Strategic moves center on cold-chain infrastructure retrofitting for F-Gas Regulation compliance and blockchain-enabled traceability platform deployment.
Within the cooperative archetype, Organic Valley and Arla Foods amba exemplify farmer-owned structures that stabilize farm-gate pricing across member networks. Among publicly traded processors, Danone SA occupies a position in fermented organic segments with specialized yogurt cultures. These three entities represent distinct competitive vectors: cooperative ownership sustaining premiums, multinational scale capturing margin pools, and culture specialization commanding pharmacy and wellness retail placement.
| Leading Market Players |
|---|
| Aurora Organic Dairy |
| Groupe Lactalis |
| Arla Foods amba |
| Nestlé S.A. |
| Horizon Organic Dairy LLC |
| Organic Valley |
| Fonterra Co-operative Group Ltd. |
| Straus Family Creamery Inc. |
| Danone SA |
| Others |
Cost & Logistics Intelligence
Farmer-owned cooperatives anchor supply discipline across member networks, converting feed cost volatility into collective bargaining power that stabilizes farm-gate milk premiums. This ownership pattern compresses price discovery transparency while extending payment terms that reward long-term conversion commitments over spot-market participation.
Pricing Analysis
Value-based pricing anchored to certified organic throughput governs farm-gate negotiations, with USDA and EU Organic Regulation tiers commanding premiums over transitional milk grades. Price differentiation rests on certification vintage and live-culture density for fermented derivatives. Cost compression in private-label fluid milk intensifies as German retail chains consolidate shelf-space tenders. Food service operators exhibit lowest price sensitivity due to menu standardization requirements, while subscription households prioritize provenance verification over per-unit cost.
Supply Chain Analysis
EU Green Deal domestic-content mandates for organic feed certification are reshaping sourcing patterns across member-state procurement offices. Supply concentration centers on Germany, Denmark, and the Netherlands for processing infrastructure, with Argentina and Ukraine for non-GMO soybean inputs. Single-source vulnerability persists in alfalfa hay logistics from Black Sea corridors. Distribution runs through cooperative-owned cold-chain networks retrofitted for F-Gas Regulation CO2 refrigerant compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into certified organic feed production represents the decisive vertical lever, with processors securing multi-year cultivation contracts to preempt herd expansion bottlenecks.
For Market Incumbents: Cement cooperative governance structures that lock in member farm exclusivity against private-equity rollup pressure. Expand anaerobic digester capacity in Bavaria and Jutland to capture carbon credit revenue alongside biogas output. Prioritize blockchain-enabled traceability deployment to compress audit cycles and defend shelf-space premiums against multinational entrants. For New Entrants and Emerging Players: Enter via urban subscription channels in Paris and London where delivery slot scarcity outpaces supply. Target pharmacy and wellness retail formats for probiotic yogurt placement with documented CFU claims. Deploy direct-to-consumer platforms with membership-tier pricing that bypasses supermarket slotting fees. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale processors in the Netherlands with stranded methane capture assets and pending EU organic equivalence renewals. Five-to-ten-year viability hinges on feed traceability infrastructure rather than commodity milk volume. Watch EFSA residue limit enforcement patterns as the inflection signal for export-bound capacity valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feed | Multi-year alfalfa contracts in France lock in supply from converting conventional farms under CAP subsidy coverage. |
| Cold-Chain Refrigerant Retrofit | CO2 system deployment satisfies F-Gas Regulation mandates while creating captive demand from compliant logistics providers. |
| Blockchain Traceability Platform | Danish cooperative deployment compresses certification audit cycles from quarterly to real-time with full-herd documentation. |
| Urban Subscription Channel Launch | Berlin and Copenhagen weekly delivery slots sell out months in advance, displacing supermarket intermediaries. |
| Probiotic Strain Differentiation | Specialized Lactobacillus cultures with gut-health claims command pharmacy shelf-space premiums in Switzerland. |
Research Approach
USDA organic certification databases, EU Farm to Fork Strategy implementation reports, and EFSA residue limit guidelines formed the secondary backbone for supply-side validation. Primary interviews with cooperative board members, cold-chain logistics operators, and retail category buyers triangulated against customs data for organic dairy trade flows. Bottom-up herd expansion timelines and top-down CAP subsidy allocation models converged on volume estimates.
Historical trendline analysis of farm-gate milk premiums and processing capacity utilization informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user procurement pattern, packaging cold-chain compliance tier, and distribution channel control level. CAGRs derived from organic farmland conversion rates under EU Green Deal targets and IoT-enabled pasteurization yield recovery curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under organic feed price spikes and veterinary compliance documentation backlogs. Forecasts reflect assumptions on equivalence agreement continuity between USDA and EU Organic Regulation regimes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Colombia Dairy Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Skimmed Milk Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
Nigeria Yogurt Drinks Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
A2 Milk Market
Dairy Products
North America Condensed Milk Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Cream Powder Market
Dairy Products
North America Yogurt Market
Dairy Products
UAE Camel Dairy Market
Dairy Products
Probiotic Cheese Market
Dairy Products
Reduced Fat Dairy Market