
 Global Yogurt Powder Market | 2026-2036
Global Yogurt Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Yogurt Powder Market Foresight
Buyer concentration in the yogurt powder market is broadening from traditional dairy processors toward health and nutrition companies and foodservice providers seeking cultured ingredient solutions. Glanbia PLC leverages its nutritional ingredient platform to anchor supply relationships with sports nutrition formulators. Kerry Group PLC sustains competitive positioning through flavor-culture integration capabilities that span beverage and confectionery applications. EPI Ingredients differentiates via specialized yogurt powder fractions tailored to bakery texture requirements.
Yogurt powder consists of spray-dried or freeze-dried fermented milk solids retaining live or thermally inactivated cultures, typically manufactured at moisture levels below 5% to ensure shelf stability in ambient distribution. The powder serves industrial buyers requiring consistent acidification profiles without cold-chain dependency across beverage, bakery, and dietary supplement production. Greek yogurt powder commands margin premiums due to protein concentration requirements and straining-process complexity in manufacturing. Non-dairy yogurt powder represents the fastest-expanding product type as oat, coconut, and almond base formulations displace dairy-derived alternatives in clean-label portfolios. Application demand in dietary supplements concentrates value pools where probiotic stability during tablet compression drives powder specification premiums.
EFSA Novel Food regulations govern culture strain approvals for yogurt powder marketed across European Union member states, while FDA GRAS self-affirmation pathways shape U.S. market entry timelines for new culture combinations. BIS certification requirements in India mandate microbiological safety testing that influences import sourcing decisions for international suppliers. Stakeholders must monitor evolving strain-specific health claim substantiation standards as regulatory divergence between major markets reshapes formulation and labeling investment priorities.
Market Dynamics
Clean-label reformulation mandates under EFSA and FDA frameworks are compressing cold-chain dependency across dairy ingredient supply chains, forcing manufacturers toward shelf-stable culture delivery systems.
Growth Catalysts
- Functional beverage expansion:Sports nutrition formulators in North America and Europe are procuring yogurt powder as a stable probiotic vehicle for ready-to-drink protein formulations.
- PLI scheme acceleration:India's production-linked incentive program for food processing infrastructure is scaling domestic spray-dry capacity for dairy culture ingredients.
- Freeze-drying technology maturation:Advanced lyophilization protocols are preserving higher viable culture counts through ambient distribution channels.
Market Restraints
- Skim milk powder price volatility:Input cost swings in dairy commodities compress margin stability for yogurt powder manufacturers.
- Strain approval bottlenecks:EFSA Novel Food timelines for new culture combinations extend commercialization cycles by 18-36 months.
- Fresh yogurt substitution:Cold-chain improvements in emerging markets enable liquid cultured dairy to reclaim industrial formulation share.
Strategic Opportunities
- Bakery texture innovation:Specialized yogurt powder fractions enable clean-label moisture retention in artisan bread without chemical conditioners.
- Non-dairy base expansion:Oat and coconut yogurt powders capture formulation share in plant-based confectionery and frozen dessert applications.
- Dietary supplement channel development:Direct-to-consumer probiotic tablets and capsules create pull-through for high-stability culture powders.
Industry Challenges
- Culture viability certification:CFU count standardization across spray-dried and freeze-dried formats lacks harmonized ISO protocols.
- Toll manufacturing dependency:Limited captive spray-dry capacity forces ingredient suppliers into third-party processing arrangements with queue constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Yogurt Powder Market |
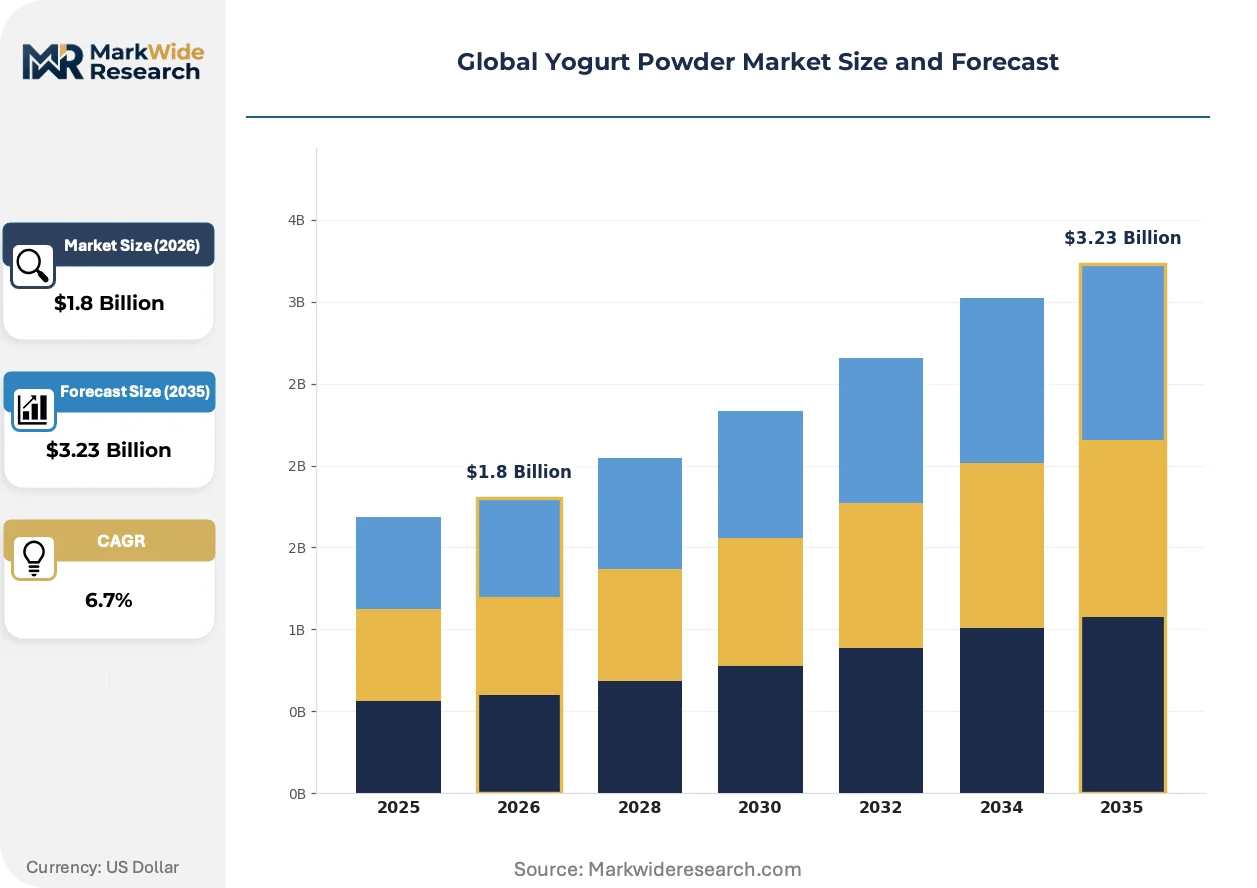
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain Yogurt Powder, Greek Yogurt Powder, Flavored Yogurt Powder, Organic Yogurt Powder, Non-Dairy Yogurt Powder Application: Beverages, Bakery, Confectionery, Dietary Supplements, Culinary End User: Food Manufacturers, Health & Nutrition Companies, Restaurants, Foodservice Providers Packaging Type: Stand-Up Pouches, Sachets, Bulk Bags, Plastic Jars, Tins |
| Companies Covered | Glanbia PLC, EPI Ingredients, PreGel America, Inc., ACE International LLP, Bluegrass Ingredients, Inc., CP Ingredients Ltd, Kerry Group PLC, Bempresa Ltd, Prolactal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Yogurt Powder Market Shifts & Advancements
Manufacturing technology convergence and regulatory strain-specificity are compressing product development cycles while fragmenting specification requirements across end-use verticals.
Microencapsulation technology using lipid or polysaccharide matrices is unifying probiotic protection with processing tolerance. Bakery and confectionery manufacturers in Germany and Switzerland are adopting these systems at pilot scale. This unifying architecture enables culture survival through high-shear mixing and oven temperatures that previously demanded thermal inactivation.
EFSA's evolving health claim substantiation requirements for specific Lactobacillus and Bifidobacterium strains are forcing reformulation documentation investments. Strain-level clinical trial requirements now precede powder product registrations. European dietary supplement brands are consolidating supplier relationships to share toxicological study costs.
Ingredient specification sheets now carry culture strain pedigrees rather than generic "yogurt culture" designations. Sports nutrition contract manufacturers in the United States are rejecting non-strain-specific powders to reduce labeling liability. This documentation burden favors suppliers with internal culture banking capabilities over toll-dependent competitors.
Global Yogurt Powder Market Segmentation
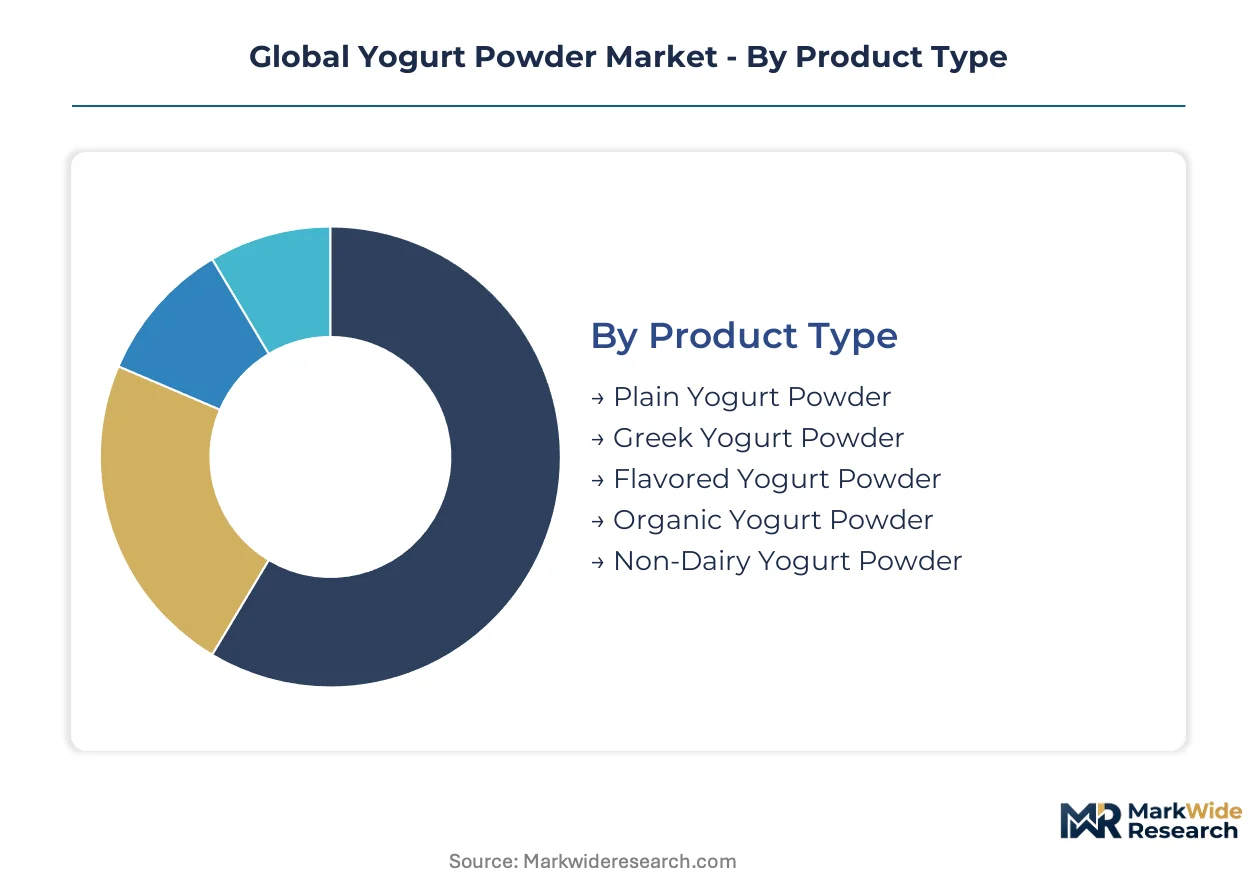
Segmentation in yogurt powder markets exposes divergent capital requirements across manufacturing technologies and distribution channels. Powder specifications vary dramatically by protein concentration, culture viability thresholds, and moisture content tolerances. These technical boundaries determine which suppliers can serve which buyer tiers.
Product Type:
Freeze-drying infrastructure demands substantially higher upfront investment than spray-drying lines, concentrating production among capitalized players.
- Greek Yogurt Powder:Strained milk solids with elevated protein content (typically 10-12% versus 6-8% standard) require specialized ultrafiltration equipment and extended processing cycles. German and Swiss dairy processors dominate this specification tier due to their installed membrane filtration capacity. Straining complexity limits toll manufacturing options and protects margin structures for integrated producers.
- Non-Dairy Yogurt Powder:Oat, coconut, and almond base formulations rely on enzymatic hydrolysis and alternative protein stabilization systems distinct from dairy processing lines. US and Nordic ingredient startups are building dedicated spray-dry capacity for plant-based cultured powders. Base material variability creates formulation standardization challenges that favor suppliers with internal R&D laboratories.
- Plain Yogurt Powder:Standard fermented milk solids without additive or flavor systems serve as the commodity reference point for industrial procurement.
- Flavored Yogurt Powder:Pre-blended fruit, vanilla, or savory inclusions require co-drying or post-blending infrastructure.
- Organic Yogurt Powder:Certified organic milk sourcing and segregation protocols add traceability costs without fundamental process differentiation.
Greek yogurt powder absorbs the bulk of installed capacity; non-dairy yogurt powder is expanding most quickly.
Application:
End-use specifications fragment by thermal tolerance requirements and culture viability demands.
- Dietary Supplements:Tablet and capsule formulations demand high CFU retention through compression forces and gastric acid exposure. Microencapsulation technology using lipid matrices protects cultures during processing and shelf life. European contract manufacturers specify strain-level documentation to satisfy EFSA health claim substantiation requirements.
- Beverages:Ready-to-drink protein formulations incorporate yogurt powder as a stable acidification source without cold-chain dependency. North American sports nutrition brands are specifying thermally inactivated cultures for flavor consistency alongside live probiotic additions.
- Bakery:Moisture retention and crumb texture modification drive specification priorities without culture viability requirements.
- Confectionery:Chocolate and yogurt coating applications prioritize fat compatibility and water activity control.
- Culinary:Sauce and dressing manufacturers value acidification consistency for flavor profiling.
Dietary supplements command specification premiums; beverage applications are climbing the fastest.
End User:
Procurement sophistication varies by scale and technical capability.
- Health & Nutrition Companies:Sports nutrition and direct-to-consumer wellness brands specify strain-specific cultures with clinical trial backing. These buyers reject generic culture designations to reduce labeling liability under FDA and EFSA frameworks. Supplier relationships consolidate around partners with internal culture banking and toxicological documentation capabilities.
- Food Manufacturers:Large-scale bakery and beverage producers prioritize volume consistency and backward integration into spray-dry capacity. Indian food processors are expanding under PLI scheme incentives for domestic dairy ingredient production.
- Foodservice Providers:Restaurant chains and institutional catering seek portion-controlled formats for operational simplicity.
- Restaurants:Independent operators represent fragmented, price-sensitive demand with limited technical specification input.
Food manufacturers anchor volume procurement; health and nutrition companies are gaining share fastest.
Packaging Type:
Packaging investment scales with automation and barrier property requirements.
- Bulk Bags:Industrial totes for food manufacturers require minimal unit packaging investment but demand warehouse automation for handling efficiency.
- Stand-Up Pouches:Retail and foodservice formats balance shelf presence with moisture barrier performance.
- Sachets:Single-serve portions for foodservice and sampling applications.
- Plastic Jars:Club store and direct-to-consumer channels with resealability requirements.
- Tins:Premium positioning and extended shelf life applications.
Bulk bags dominate industrial throughput; stand-up pouches are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates procurement expansion for yogurt powder ingredients through domestic processing scale-up incentives. German membrane filtration specialists supply strained yogurt powder specifications to European health brands. US sports nutrition formulators drive freeze-dried culture demand for ambient-stable probiotic delivery.
United States
Sports nutrition contract manufacturers in California and Utah specify thermally inactivated yogurt powders for ready-to-drink protein formulations. FDA GRAS self-affirmation pathways govern new culture strain introductions. Chicago-area ingredient distributors consolidate supplier relationships to share toxicological documentation costs.
Germany
Bavarian dairy processors dominate Greek yogurt powder production through installed ultrafiltration capacity. EFSA Novel Food regulations mandate strain-level health claim substantiation for probiotic powders. Stuttgart-region engineering firms supply lyophilization equipment for high-CFU preservation systems.
India
Maharashtra and Gujarat food processors expand spray-dry capacity under PLI scheme incentives for dairy ingredient infrastructure. BIS certification requirements mandate microbiological safety testing protocols. Anand district cooperative networks anchor domestic culture sourcing for powder manufacturing.
Switzerland
Zurich and Geneva-based confectionery manufacturers procure specialized yogurt powder fractions for chocolate coating applications. Swissmedic oversight shapes strain documentation standards for cross-border EU distribution. Basel-region ingredient traders coordinate toll manufacturing arrangements for third-party powder processing.
China
Shanghai and Guangzhou beverage formulators trial oat-based yogurt powders for plant-based functional drink lines. SAMR registration requirements extend commercialization timelines for imported culture strains. Yangtze River Delta dairy processors invest in enzymatic hydrolysis capacity for non-dairy base stabilization.
Global Yogurt Powder Market Competitive Landscape
European producers anchor the premium specification tier; North American specialists hold contract manufacturing relationships with sports nutrition brands. The vendor base splits between integrated dairy processors with captive spray-dry capacity and toll-dependent ingredient suppliers facing queue constraints. Three archetypes dominate: membrane filtration specialists commanding Greek yogurt powder margins, plant-based innovators building dedicated non-dairy lines, and nutritional ingredient platforms bundling culture banking with toxicological documentation. Capacity expansion and strain-specific certification investments represent the dominant competitive moves.
Among Irish-domiciled nutritional platforms, Glanbia PLC and Kerry Group PLC exemplify the integrated ingredient archetype. EPI Ingredients occupies a position within the European dairy specialization tier. These named entities represent the competitive positioning patterns visible across the supplier base rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Glanbia PLC |
| EPI Ingredients |
| PreGel America, Inc. |
| ACE International LLP |
| Bluegrass Ingredients, Inc. |
| CP Ingredients Ltd |
| Kerry Group PLC |
| Bempresa Ltd |
| Prolactal |
| Others |
Supply & Pricing Matrix
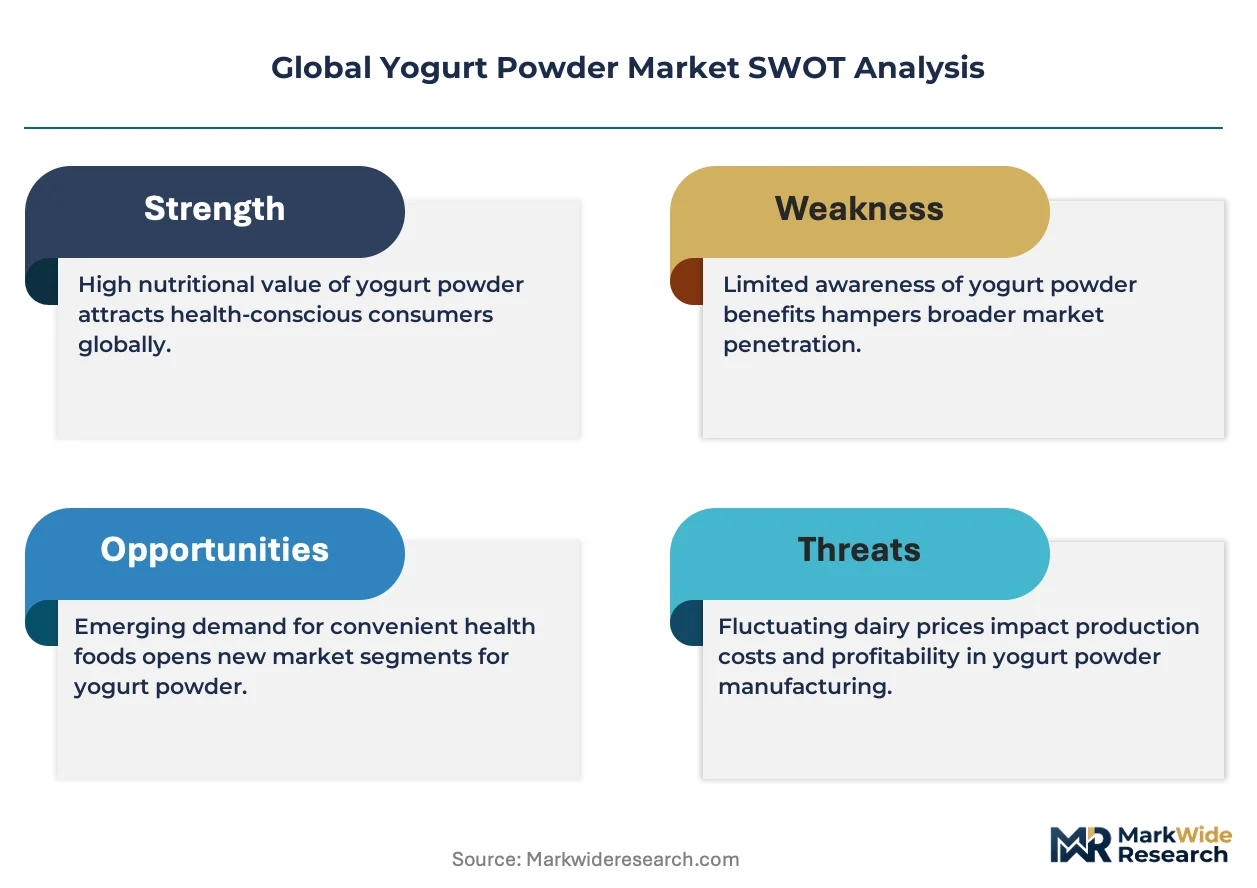
Strain-specific certification requirements from EFSA and FDA are forcing ingredient suppliers to absorb toxicological documentation costs, compressing margins for toll-dependent operators while rewarding integrated culture banking capabilities with pricing power.
Pricing Analysis
Volume procurement by food manufacturers anchors commodity-grade plain yogurt powder at thin margins, while health and nutrition companies pay premiums for strain-documented, microencapsulated grades. Three-tier pricing structure across premium, standard, and economy levels separates Greek yogurt powder with ultrafiltration investment from commodity spray-dried grades and non-dairy alternatives with enzymatic processing overhead. Pricing pressure stems from skim milk powder commodity volatility feeding into dairy-based production. Food manufacturers exhibit highest price sensitivity due to backward integration options; dietary supplement brands show lowest sensitivity given liability-driven specification rigidity.
Supply Chain Analysis
EFSA Novel Food and FDA GRAS certifications gate supplier eligibility for strain-specific formulations, concentrating viable supply among culture banking specialists in Germany, Switzerland, and the United States. Manufacturing draws from skim milk powder, live culture banks, and lipid matrix encapsulation materials. Single-source vulnerability runs through limited captive spray-dry capacity forcing queue-dependent toll arrangements. Distribution runs through ingredient distributors in Chicago and Basel coordinating bulk bag shipments to food manufacturers and stand-up pouch formats for retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated culture banking capabilities as EFSA strain-level documentation requirements eliminate toll-dependent competitors unable to absorb toxicological study investments.
For Market Incumbents: Hedge against fresh yogurt substitution by deepening captive spray-dry capacity in India under PLI scheme incentives. Secure exclusive supply relationships with sports nutrition contract manufacturers in California and Utah by bundling thermally inactivated base powders with live probiotic microencapsulation services. For New Entrants and Emerging Players: Artisan bakery chains in Germany and Switzerland represent an underserved buyer archetype seeking clean-label moisture retention without chemical conditioners. Build dedicated non-dairy spray-dry lines for oat and coconut bases to capture plant-based confectionery formulation share. Lead with texture-specific fraction samples rather than commodity culture specifications. For Investors and Strategic Acquirers: The window for entry favors membrane filtration specialists with installed Greek yogurt powder capacity and internal culture banking capabilities. Long-term viability hinges on regulatory divergence between EFSA and FDA creating sustained documentation service demand. Watch EFSA health claim substantiation rulings on specific Lactobacillus strains as the inflection signal for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Culture Banking Investment | Internal strain repositories eliminate toxicological documentation cost sharing with competitors under EFSA frameworks. |
| Freeze-Drying Capacity Expansion | Advanced lyophilization protocols preserve viable CFU counts for dietary supplement compression requirements. |
| Non-Dairy Base Diversification | Oat and coconut spray-dry lines capture formulation share in plant-based frozen dessert applications. |
| Microencapsulation Technology Licensing | Lipid matrix protection enables culture survival through high-shear bakery mixing and oven temperatures. |
| PLI Scheme Capacity Buildout | Domestic spray-dry infrastructure in Maharashtra and Gujarat reduces import dependency for Indian food processors. |
Research Methodology
Document review covered FDA GRAS notifications, EFSA Novel Food approvals, BIS certification protocols, and customs trade data, complemented by interviews with spray-dry plant managers, sports nutrition procurement leads, bakery R&D directors, and ingredient distribution channel partners. Secondary validation drew from SEC filings of nutritional ingredient platforms, dairy cooperative annual reports, and PLI scheme disbursement records. Bottom-up volume modeling triangulated against top-down category spend estimates across the analysis window.
Cross-referencing historical capacity expansion patterns against expert panel input on strain approval timelines shaped the projection framework. Segmentation dimensions modeled include product type differentiation by protein concentration and culture viability, application-specific thermal tolerance requirements, end-user procurement sophistication tiers, and regional regulatory cluster divergence. CAGRs derived from slope analysis of documented capacity investments and buyer procurement trend trajectories. Forecast inputs incorporated PLI scheme incentive disbursement velocity and EFSA health claim substantiation pipeline status.
Revisions become necessary when EFSA strain approval timelines extend beyond historical 18-36 month baselines or when skim milk powder commodity volatility exceeds banded assumptions. Forecasts reflect documented capacity expansion commitments and regulatory filing status as of the analysis cutoff. A model refresh is warranted upon material change in EFSA-FDA regulatory divergence intensity or PLI scheme incentive restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Sheep Milk Cheese Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
Ultra High Temperature Milk Market
Dairy Products
Buttermilk Powder Market
Dairy Products
GCC UHT Milk Market
Dairy Products
Dry Buttermilk Market
Dairy Products
South America Yogurt Market
Dairy Products
Probiotic Yogurt Market
Dairy Products
Milk Protein Hydrolysate Market
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
Dairy Carton Market
Dairy Products
Dairy Products Market
Dairy Products
Sweet Whey Market