
 Probiotic Dairy Products Market | 2026-2036
Probiotic Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotic Dairy Products Market Analytics
The EU Green Deal is consolidating sustainability mandates across European dairy supply chains, compelling processors to reformulate for lower carbon footprints and cleaner labels. Danone SA leverages its specialized fermentation infrastructure to deliver strain-specific probiotic yogurts with verified CFU counts at scale. Nestlé SA anchors its position through backward integration into dairy farming cooperatives, securing raw milk traceability from farm to finished cup. Yakult Honsha Co. Ltd dominates the single-shot probiotic drink format, sustaining decades of consumer trust through dedicated Lactobacillus casei Shirota research.
Probiotic dairy products are fermented milk-based foods containing live, defined microbial cultures that confer documented gastrointestinal or immunological benefits, typically requiring refrigeration below 8°C to maintain colony viability above 10^6 CFU per gram through stated shelf life. Their primary commercial purpose centers on delivering measurable wellness outcomes in convenient, familiar food matrices that integrate into daily consumption rituals. Yogurt commands the largest value pool due to entrenched breakfast and snacking habits across mature markets, while kefir represents the fastest-expanding category as consumers seek lower-sugar, higher-diversity fermentation profiles. The distribution channel structure tilts toward supermarkets for volume, though health stores capture disproportionate margin through curated, premium-positioned SKUs with third-party strain verification.
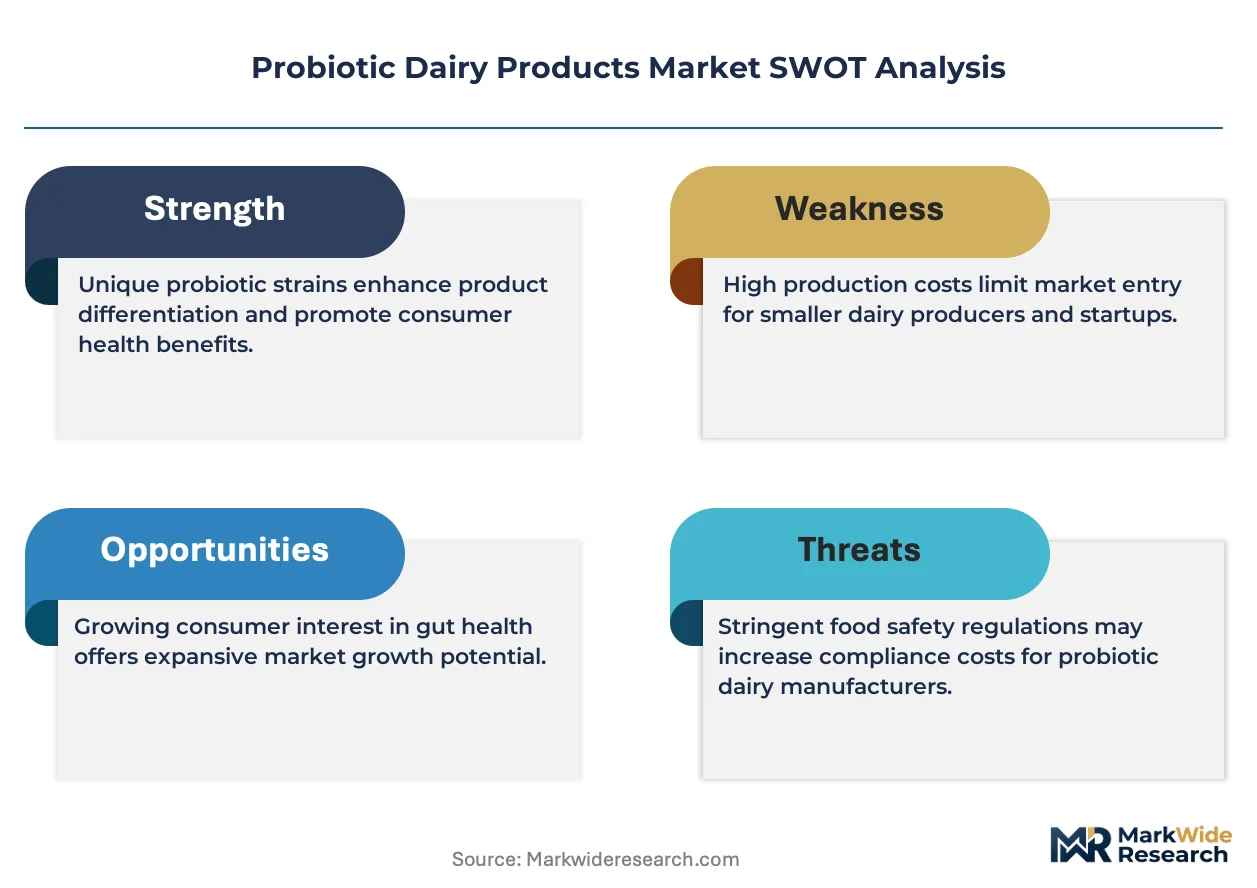
FDA regulations on structure-function claims in the United States, EFSA health claim authorization requirements in Europe, and FSSAI standards for minimum probiotic counts in India collectively shape formulation decisions, labeling precision, and cross-border market access for multinational suppliers. These frameworks elevate compliance costs for entrants but simultaneously protect established players with dedicated regulatory affairs capabilities and substantiated clinical dossiers. Stakeholders must monitor evolving strain-specific approval pathways and emerging microbiome research that could expand or restrict permissible health claims without warning.
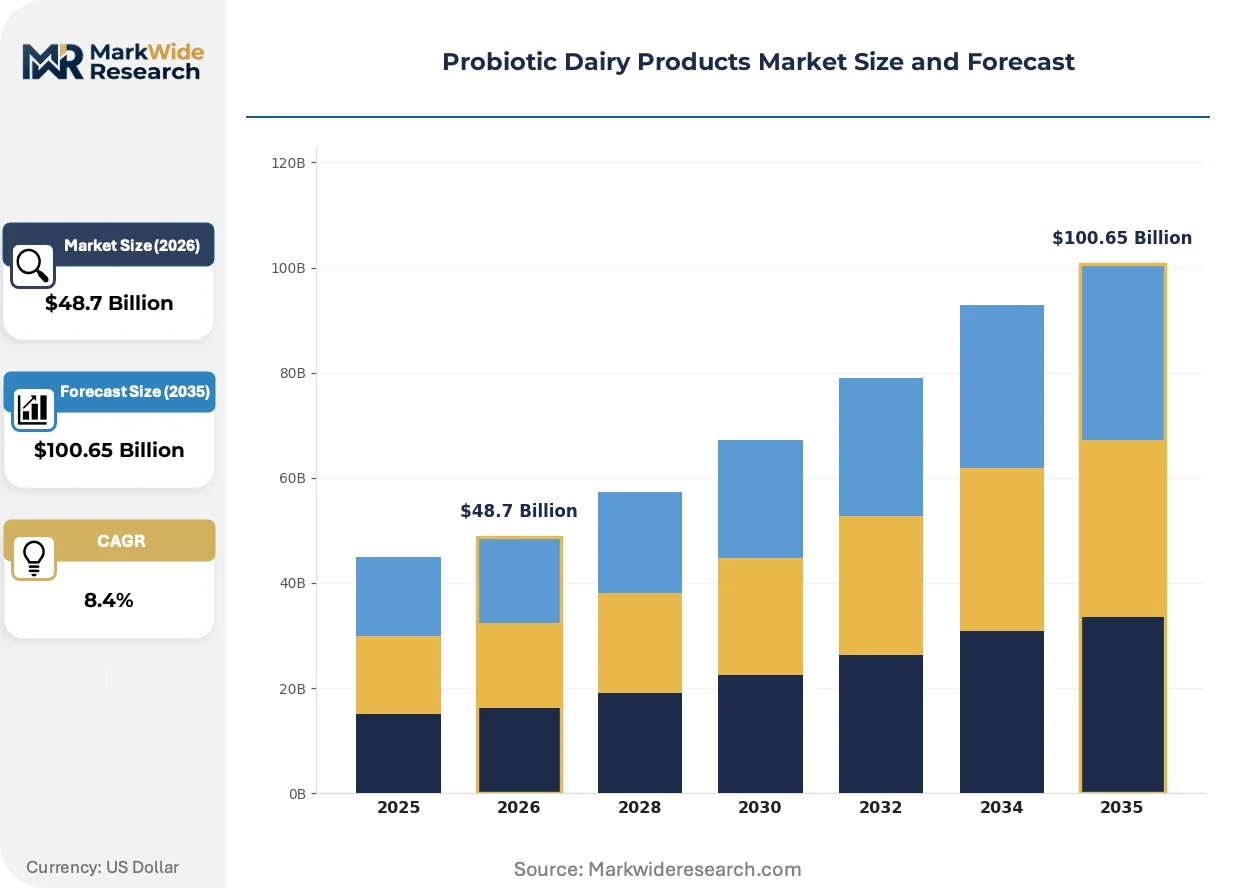
Market Dynamics
The EU F-Gas Regulation is forcing cold-chain infrastructure upgrades across European probiotic dairy processing, compressing margins for operators dependent on legacy refrigeration while advantaging facilities with integrated fermentation-cooling systems.
Growth Catalysts
- EFSA health claim authorization:Validated strain-specific dossiers unlock premium positioning in EU retail channels, creating defensible SKU differentiation.
- Fermentation research clusters:German dairy cooperatives concentrate R&D talent and pilot-scale infrastructure, accelerating strain development cycles.
- Functional snacking:Health-conscious consumers in European supermarkets expand purchases of single-serve probiotic formats beyond traditional breakfast occasions.
Market Restraints
- Refrigerant compliance costs:The EU F-Gas phase-down mandates capital-intensive cooling system retrofits for small and mid-scale processors.
- Live culture supply concentration:Specialized starter culture production clusters in Denmark and the Netherlands create single-source vulnerability for new entrants.
- Strain stability limitations:Temperature excursions above 8°C degrade viable CFU counts, constraining distribution reach in underdeveloped cold-chain geographies.
Strategic Opportunities
- Polish retail expansion:Underpenetrated modern trade channels in Central Europe present whitespace for ambient-stable spore-forming probiotic formats.
- EU Green Deal incentives:Carbon footprint reduction mandates favor processors with on-farm biogas capture and renewable-powered fermentation.
- Direct-to-subscription models:Refrigerated last-mile delivery partnerships with urban logistics platforms bypass traditional supermarket slotting fees.
Industry Challenges
- Microbiome assay talent scarcity:Strain characterization and clinical substantiation require specialized bioinformatics capabilities concentrated in academic institutions.
- Dual certification timelines:Parallel EFSA health claim and organic label approvals extend product development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotic Dairy Products Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt, Kefir, Cheese, Dessert End User: Hospitals, Fitness Centers, Retail, Food Service Distribution Channel: Supermarkets, Online Stores, Health Stores, Wholesale Packaging Type: Plastics, Glass, Tetra Pak, Pouches |
| Companies Covered | Danone SA, Nestlé SA, Yakult Honsha Co. Ltd, Lifeway Foods Inc., Arla Foods, General Mills Inc., Gujarat Cooperative Milk Marketing Federation Limited, Fonterra Co-op Group Ltd, Bright Dairy & Food Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotic Dairy Products Market Evolving Landscape
Precision fermentation infrastructure is absorbing capital flows previously directed toward commodity dairy expansion, redirecting processor investment toward strain-specific production lines with integrated quality verification systems.
Continuous-flow fermentation bioreactors are absorbing process development attention from European equipment suppliers, enabling real-time pH and temperature modulation that stabilizes Lactobacillus viability across extended production runs. Mid-scale German and French yogurt processors are retrofitting batch facilities with modular continuous systems, compressing unit economics for niche strain portfolios. This technology diffusion is absorbing smaller players into contract manufacturing networks as standalone capex requirements exceed balance sheet capacity.
The EU Green Deal's Farm to Fork Strategy is tightening methane emission disclosure requirements for dairy raw material sourcing, compelling processors to document enteric fermentation offsets through cooperative feed additive programs. EFSA-aligned carbon footprint calculators are becoming standard tender prerequisites for retail private-label contracts. Organic and regenerative-certified milk pools command sourcing priority as supermarket sustainability scorecards mature.
Health store buyers are consolidating supplier relationships around third-party strain verification protocols, displacing fragmented procurement across multiple regional brands. German and Dutch pharmacy chains are integrating probiotic dairy SKUs into preventive health consultations, capturing margin through advisory bundling rather than product turnover alone. This channel specialization concentrates volume with processors maintaining dedicated regulatory affairs and clinical dossier capabilities.
Probiotic Dairy Products Market Segmentation
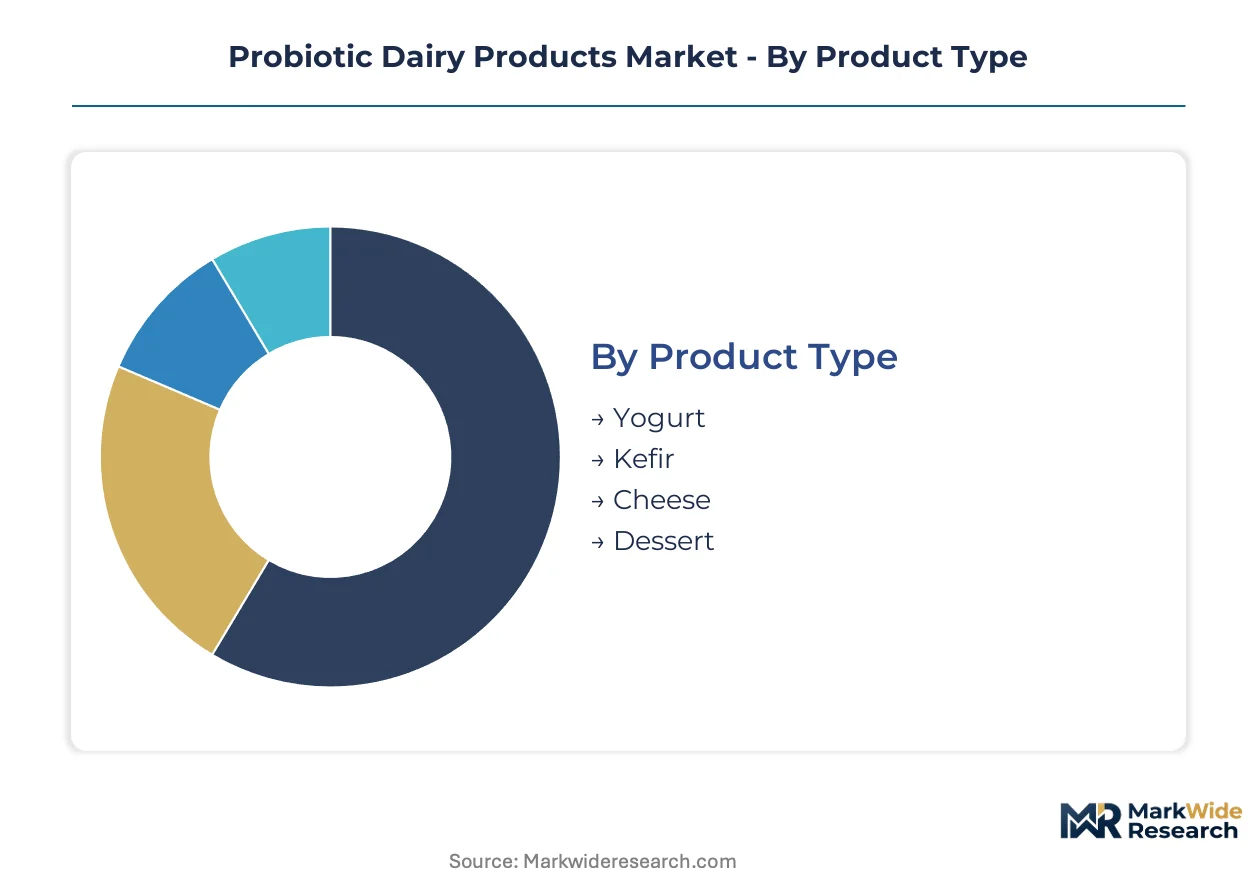
Strain viability requirements and cold-chain dependencies create distinct technical specifications across probiotic dairy formats. Each segment carries unique formulation constraints that determine manufacturing investment, shelf-life engineering, and distribution reach.
Product Type:
Fermentation protocols and live culture density specifications differentiate manufacturing infrastructure requirements across formats.
- Yogurt:Standardized Lactobacillus bulgaricus and Streptococcus thermophilus fermentation at 10^6 CFU/gram minimum delivers the most established production economics. German dairy cooperatives anchor capacity expansion as breakfast and snacking rituals sustain volume concentration in European retail.
- Kefir:Multi-strain symbiotic cultures including Lactobacillus kefiri and Saccharomyces kefir generate higher microbial diversity profiles with pronounced tartness. Health-conscious consumers in Poland and Czech Republic supermarkets are expanding purchases of lower-sugar fermented beverages beyond traditional meal occasions.
- Cheese:Surface-ripened and fresh varieties with adjunct probiotic cultures require extended aging controls or immediate cold-chain distribution.
- Dessert:Pudding and mousse formats with post-fermentation probiotic incorporation face stability challenges in high-sugar matrices.
Mature deployment sits with Yogurt. Newer deployment is concentrated in Kefir.
End User:
Consumption context determines strain selection, portion sizing, and health claim substantiation requirements.
- Retail:Single-serve and family-format SKUs with verified CFU counts dominate household purchase patterns through supermarket and online channels.
- Hospitals:Clinical nutrition protocols specify strain-documented products for post-antibiotic and immunocompromised patient populations. EFSA health claim authorization unlocks procurement contracts in French and Italian healthcare systems where dietetic departments require substantiated gastrointestinal benefit documentation.
- Fitness Centers:High-protein, low-fat formulations with added probiotic strains target recovery and gut health positioning in premium positioning.
- Food Service:Bulk yogurt and kefir for ingredient applications in smoothies and bowls concentrate demand in urban café clusters.
Volume concentrates in Retail. Margin expansion is accelerating in Hospitals.
Distribution Channel:
Cold-chain reliability and slotting fee structures shape channel economics and brand accessibility.
- Supermarkets:Refrigerated dairy cases with temperature monitoring compliance dominate volume throughput in established markets. ESG scorecard requirements from German and Dutch retail chains now mandate carbon footprint disclosure for private-label probiotic SKUs.
- Health Stores:Curated strain-verified portfolios with pharmacy-adjacent positioning command premium pricing through advisory relationships. Third-party certification from specialized microbiome testing laboratories is displacing fragmented procurement across multiple regional suppliers.
- Online Stores:Refrigerated last-mile partnerships with urban logistics platforms enable subscription models that bypass traditional slotting fees.
- Wholesale:Food service and institutional bulk purchasing concentrates in cooperative buying groups serving hospital and education sectors.
Supermarkets capture volume concentration. Health Stores are expanding most quickly.
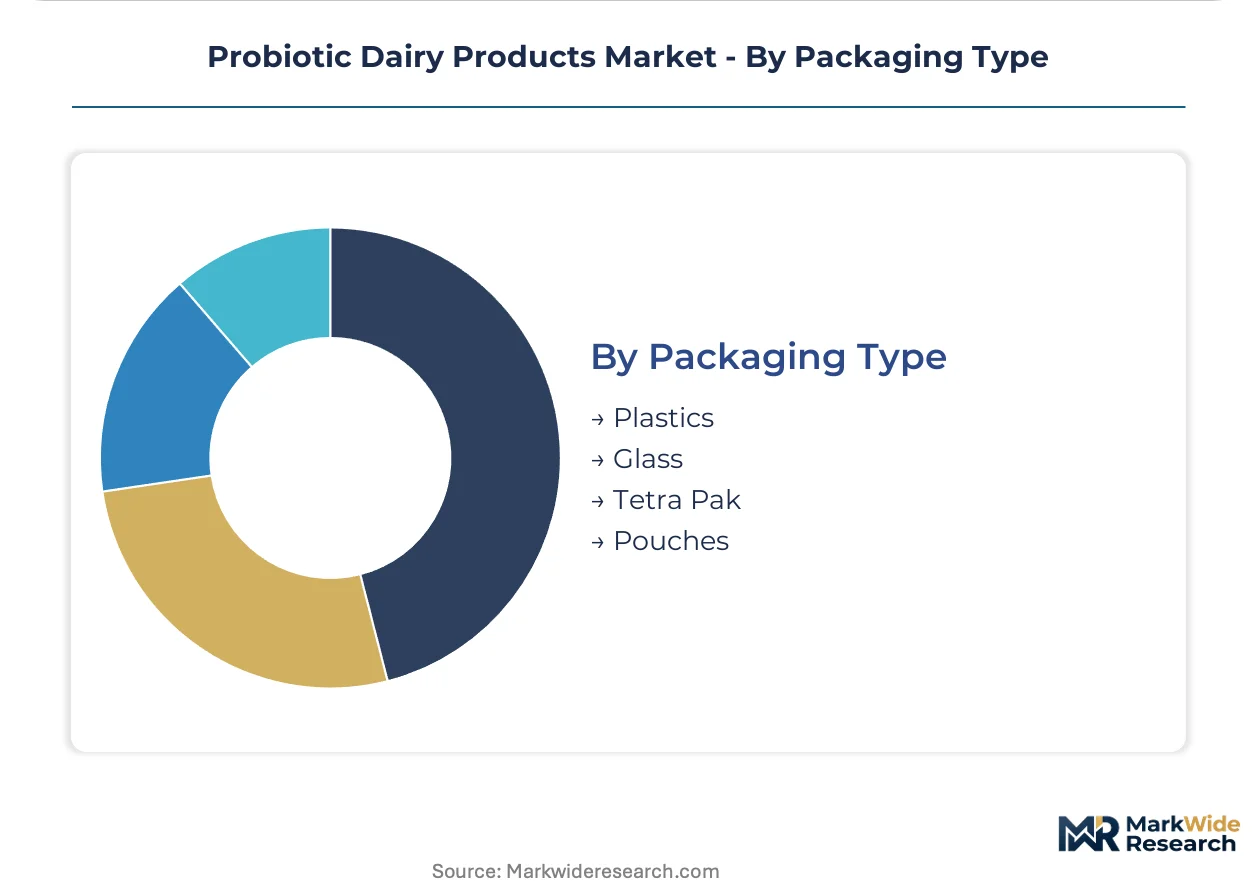
Packaging Type:
Barrier properties and temperature stability determine viable distribution radius and shelf-life extension.
- Plastics:HDPE and PET containers with oxygen scavenging layers dominate single-serve yogurt and kefir formats. EU Green Deal packaging waste directives are accelerating rPET adoption and lightweighting investments among German processors.
- Tetra Pak:Aseptic carton technology with aluminum barrier layers enables ambient-stable probiotic formats through spore-forming strain selection. Polish retail channels are absorbing these products where cold-chain infrastructure remains underdeveloped.
- Glass:Premium positioning in health store and pharmacy channels leverages perceived purity and reusability programs.
- Pouches:Flexible format for children's probiotic dairy and on-the-go consumption with reduced material intensity.
Plastics dominate current deployment. Tetra Pak is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European probiotic dairy innovation through its fermentation research corridor, where Bavarian dairy cooperatives concentrate pilot-scale infrastructure and strain development capabilities.
Germany
Health-conscious consumers in Bavarian and North Rhine-Westphalian supermarkets expand purchases of functional snacking formats beyond traditional breakfast occasions. The EU F-Gas Regulation mandates capital-intensive cooling system retrofits for mid-scale processors. The Munich-Stuttgart fermentation research cluster accelerates strain development cycles through concentrated R&D talent and shared pilot facilities.
France
EFSA health claim authorization unlocks procurement contracts in Parisian and Lyonnais hospital systems where dietetic departments require substantiated gastrointestinal benefit documentation. The EU Green Deal's Farm to Fork Strategy tightens methane emission disclosure requirements for dairy raw material sourcing. The Brittany dairy cooperative network documents enteric fermentation offsets through feed additive programs.
Netherlands
Specialized starter culture production concentrates in Utrecht and Wageningen, creating single-source vulnerability for new entrants dependent on live culture supply. REACH compliance elevates formulation costs for processors using novel stabilizer systems. The Wageningen University & Research microbiome assay capabilities anchor strain characterization services for regional dairy processors.
Poland
Underpenetrated modern trade channels in Warsaw and Kraków present whitespace for ambient-stable spore-forming probiotic formats distributed through Tetra Pak aseptic cartons. F-Gas phase-down timelines compress margins for operators dependent on legacy refrigeration infrastructure. The Masovian retail expansion absorbs these products where cold-chain infrastructure remains underdeveloped relative to Western European benchmarks.
United States
FDA structure-function claim regulations shape formulation decisions and labeling precision for processors targeting health-conscious consumers in California and New York Metro retail channels. Hospital nutrition protocols in the Boston and Pacific Northwest healthcare systems specify strain-documented products for post-antibiotic patient populations. The California dairy processing corridor concentrates precision fermentation infrastructure investment previously directed toward commodity expansion.
Probiotic Dairy Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across strain verification and clinical dossier capabilities, with EFSA-aligned processors commanding retail private-label contracts through carbon footprint transparency. The vendor base organizes around three strategic archetypes: multinational dairy conglomerates with backward integration into farming cooperatives, specialized fermentation houses with dedicated culture collections, and regional cooperatives leveraging proximity to research clusters. Dominant competitive moves include M&A to secure starter culture supply security and capacity expansion of continuous-flow fermentation bioreactors.
Within the multinational tier, Danone SA and Nestlé SA occupy positions defined by scale-advantaged fermentation infrastructure and regulatory affairs capabilities. Yakult Honsha Co. Ltd exemplifies the single-format specialist archetype through decades of dedicated strain research. Among cooperative structures, Arla Foods and Fonterra Co-op Group Ltd represent member-owned models with integrated farm-to-finished-product traceability systems.
| Leading Market Players |
|---|
| Danone SA |
| Nestlé SA |
| Yakult Honsha Co. Ltd |
| Lifeway Foods Inc. |
| Arla Foods |
| General Mills Inc. |
| Gujarat Cooperative Milk Marketing Federation Limited |
| Fonterra Co-op Group Ltd |
| Bright Dairy & Food Co. Ltd |
| Others |
Value Network & Pricing Analysis
Fermentation microbiologists concentrated in the Munich-Stuttgart research corridor command wage premiums that compress margins for processors outside this talent cluster, widening spreads between premium strain-verified SKUs and commodity yogurt tiers.
Pricing Analysis
Outcome-based pricing anchored to verified CFU counts at consumption determines tier placement across the probiotic dairy market. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-authorized clinical strains from conventional fermentation cultures from private-label basics. Cost compression in the economy tier is intensifying because F-Gas retrofit mandates hit small processors hardest. Hospital procurement departments show least price sensitivity due to dietetic protocol requirements, while Polish supermarket buyers in underpenetrated modern trade channels drive hardest bargain negotiations.
Supply Chain Analysis
EU Green Deal domestic-content mandates for renewable energy in processing facilities are reshaping sourcing toward biogas-capture cooperative networks within member states. Live culture supply concentrates in Denmark, the Netherlands, and Germany, drawing from specialized starter culture banks and cryogenic preservation infrastructure. Raw milk procurement rests on regenerative-certified cooperative pools, rPET packaging substrates, and cold-chain logistics partnerships. Single-source vulnerability in Utrecht-Wageningen culture production clusters exposes processors to supply interruption. Distribution runs through German and Dutch supermarket refrigerated dairy cases with temperature monitoring compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fermentation infrastructure capacity constraints prop pricing power for incumbent processors with integrated culture collections, as retrofit timelines under F-Gas Regulation outpace demand expansion.
For Market Incumbents: Hedge against starter culture supply concentration by securing dual-source fermentation partnerships outside the Utrecht-Wageningen corridor. Expand continuous-flow bioreactor capacity in Bavarian research clusters to capture contract manufacturing overflow from smaller players lacking balance sheet depth for standalone capex. F-Gas compliance timelines threaten margin compression for facilities without integrated cooling systems. For New Entrants and Emerging Players: EU Green Deal carbon footprint incentives in Poland open a window for ambient-stable spore-forming probiotic formats distributed through Tetra Pak aseptic cartons. Target Warsaw and Kraków modern trade channels where cold-chain infrastructure lags Western European benchmarks. Pursue direct-to-subscription partnerships with urban logistics platforms to bypass supermarket slotting fees that favor established dairy conglomerates. For Investors and Strategic Acquirers: The window for entry favors specialized fermentation houses with dedicated strain collections and EFSA-aligned clinical dossiers. Long-term viability centers on acquisition targets possessing regulatory affairs capabilities that compress dual certification timelines for organic and health claim approvals. Watch for EFSA strain-specific authorization expansions as inflection signal for premium SKU proliferation.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Bioreactor Retrofit | Bavarian processors compress unit economics for niche strain portfolios through real-time pH modulation. |
| EFSA Health Claim Authorization | French hospital systems unlock procurement contracts requiring substantiated gastrointestinal benefit documentation. |
| Backward Integration into Farming Cooperatives | Danish and Dutch processors secure raw milk traceability from farm to finished cup under Farm to Fork mandates. |
| Direct-to-Subscription Model Launch | German urban logistics partnerships bypass refrigerated dairy case slotting fees dominating supermarket channels. |
| Spore-Forming Strain Development | Polish retail channels absorb ambient-stable formats where cold-chain infrastructure remains underdeveloped. |
Research Methodology
Multi-period observation of strain authorization timelines, cold-chain infrastructure investments, and cooperative feed additive program adoption anchored the trend analysis, supplemented by interviews with fermentation R&D directors, dairy cooperative procurement leads, supermarket category buyers, hospital dietetic department heads, and regulatory affairs specialists at EFSA-aligned processors. Secondary validation drew from EFSA health claim register filings, EU F-Gas Regulation implementation reports, Farm to Fork Strategy methane disclosure databases, and refrigerated logistics capacity surveys. Bottom-up volume modeling triangulated against top-down value estimates across product type, end user, distribution channel, and packaging format segmentation.
Segment-weighting approaches applied differential growth assumptions across yogurt, kefir, cheese, and dessert formats based on fermentation protocol complexity and strain stability requirements. End-user splits between retail, hospital, fitness center, and food service channels incorporated consumption context and health claim substantiation intensity. Distribution channel modeling captured cold-chain reliability variance between supermarket, health store, online, and wholesale structures. CAGRs derived from logistic curve fitting to historical probiotic SKU penetration patterns, adjusted for EFSA authorization velocity and F-Gas compliance investment cycles.
Caveats apply where EFSA strain-specific approval pathway revisions, F-Gas phase-down timeline accelerations, or microbiome assay talent scarcity disruptions could materially shift the outlook for clinical substantiation costs and premium SKU viability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Dairy Protein Market
Dairy Products
Malted Milk Powder Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Evaporated Milk Market
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
Cheese Crumbles Market
Dairy Products
Global Butter Market
Dairy Products
Germany Dairy Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Dairy Blends Market
Dairy Products
Dairy Concentrates Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Donkey Milk Market
Dairy Products
North America Yogurt Market
Dairy Products
United States Milk Protein Market
Dairy Products
Reduced Lactose Whey Market