
 Lactoferrin Supplements Market | 2026-2036
Lactoferrin Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Lactoferrin Supplements Market Analytics
Pharmaceutical-grade lactoferrin purity thresholds is collapsing the gap between commodity whey derivatives and clinical nutrition inputs. Royal FrieslandCampina leverages its dairy cooperative scale to secure raw milk supply chains across Northern Europe. Fonterra anchors Oceania production with integrated spray-drying facilities in New Zealand. Jarrow Formulas differentiates through capsule formulations targeting practitioner channels in North America.
Lactoferrin supplements deliver an iron-binding glycoprotein derived from bovine milk, typically standardized to 95% protein content with low endotoxin levels for oral bioavailability. Manufacturers employ cation exchange chromatography to isolate the protein from whey permeate before lyophilization or spray-drying into finished doses. Capsule formats command premium shelf positioning in pharmacies due to dosing precision and stability, while powder segments compete on bulk value in direct-to-consumer online retail. The athlete end-user category shows structural momentum as sports nutrition brands reformulate around immune-modulating claims beyond basic protein delivery.
The FDA oversees lactoferrin as a dietary ingredient under DSHEA, requiring New Dietary Ingredient notifications for novel extraction methods or synthetic analogs. Japan's Ministry of Health, Labour and Welfare classifies specific lactoferrin concentrates as Foods for Specified Health Uses, creating a regulated claims pathway distinct from standard supplements. EFSA novel food evaluations shape EU market entry timelines for non-bovine sources or recombinant production. Stakeholders must track evolving substantiation requirements for immune health claims as regulators tighten evidentiary standards for bioactive protein ingredients.
Market Dynamics
Pharmaceutical-grade purity thresholds are collapsing the gap between commodity whey derivatives and clinical nutrition inputs, forcing manufacturers to choose between mass-market positioning and premium therapeutic credibility.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined approvals for bovine-derived lactoferrin concentrates have reduced EU market entry timelines from years to months, accelerating product launches across member states.
- Athlete Immune Positioning:Sports nutrition brands now reformulate recovery formulations around lactoferrin's iron-binding properties, creating structural demand pull beyond basic protein supplementation.
- Japan's FOSHU Framework:Specific lactoferrin concentrates qualify for regulated health claims under Foods for Specified Health Uses, giving compliant products premium shelf access in aging consumer markets.
Market Restraints
- Raw Milk Supply Concentration:Northern European dairy cooperatives control the majority of high-grade whey permeate feedstock, creating geographic dependency for manufacturers outside the region.
- Cation Exchange Chromatography Costs:The protein isolation process requires specialized resin systems and buffer chemicals whose prices fluctuate with petrochemical feedstock volatility.
- Endotoxin Specification Limits:Pharmaceutical-grade oral bioavailability demands sub-threshold pyrogen levels that commodity processors cannot achieve without capital-intensive facility upgrades.
Strategic Opportunities
- Recombinant Production Methods:Microbial and cell-culture synthesis routes bypass bovine supply chains entirely, opening regulatory pathways in markets with strict animal-source restrictions.
- Practitioner Channel Expansion:Capsule formulations targeting functional medicine clinicians command price multiples over mass-market powders while building clinical evidence libraries.
- Pediatric Nutrition Integration:Infant formula manufacturers seek iron-modulating ingredients with documented safety profiles, creating formulation partnership potential for certified suppliers.
Industry Challenges
- Lyophilization Scale-Up Expertise:The transition from pilot-batch freeze-drying to commercial spray-drying while preserving protein tertiary structure requires specialized biochemical engineering talent that remains scarce.
- DSHEA Notification Burden:FDA New Dietary Ingredient requirements for novel extraction methods or synthetic analogs impose documentation timelines that delay revenue recognition by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactoferrin Supplements Market |
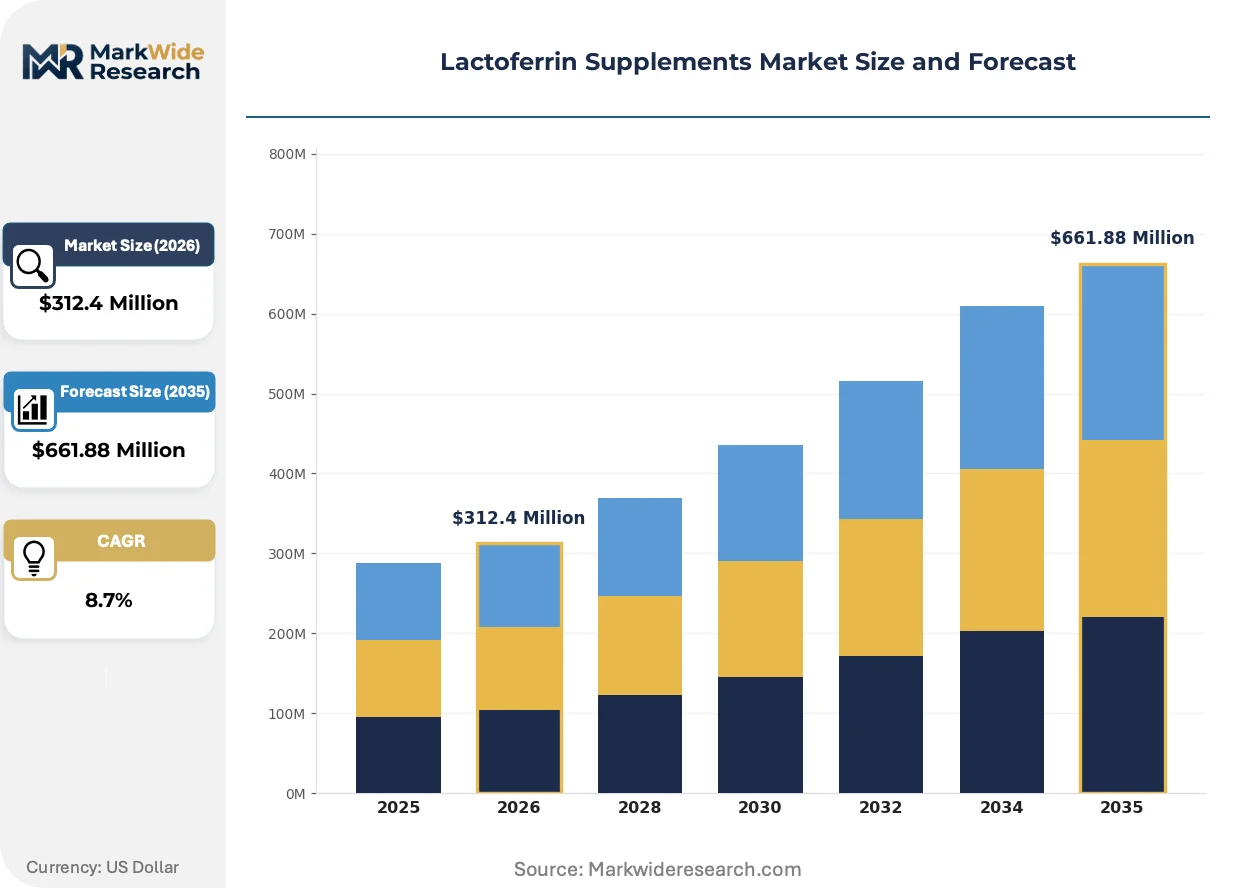
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Liquid, Softgels End User: Adults, Infants, Athletes, Seniors Distribution Channel: Online Retail, Pharmacies, Health Stores, Supermarkets Formulation: Organic, Non-GMO, Gluten-Free, Others |
| Companies Covered | Royal FrieslandCampina, Armor Protéines, Fonterra, Jarrow Formulas, NOW Foods, Morinaga Milk Industry, Glanbia Plc, Ingredia, Arla Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactoferrin Supplements Market Evolving Landscape
Manufacturing technology and regulatory positioning are diverging the market into two distinct value tiers, with premium players investing in clinical substantiation while commodity suppliers compete on bulk whey derivative pricing.
Recombinant microbial production systems are displacing traditional bovine extraction for non-dairy lactoferrin supply. Precision fermentation startups in the Netherlands and California are scaling 10,000-liter bioreactors to match dairy-derived purity specifications. This biotechnology shift is displacing geographic supply constraints that have historically tied production to Northern European dairy cooperatives.
EFSA's tightening evidentiary standards for immune health claims are reshaping substantiation investment patterns. Bioactive protein suppliers must now fund randomized controlled trials rather than relying on compositional data alone. Sports nutrition brands targeting EU markets are reformulating away from general wellness positioning toward specific, approved claim structures.
Athlete procurement patterns now favor immune-modulating ingredients with batch-level certificate of analysis transparency. Direct-to-consumer subscription models are replacing traditional retail replenishment for serious recreational athletes. This channel shift is most pronounced in North American markets where practitioner-influenced purchasing drives premium capsule adoption over bulk powders.
Lactoferrin Supplements Market Segmentation
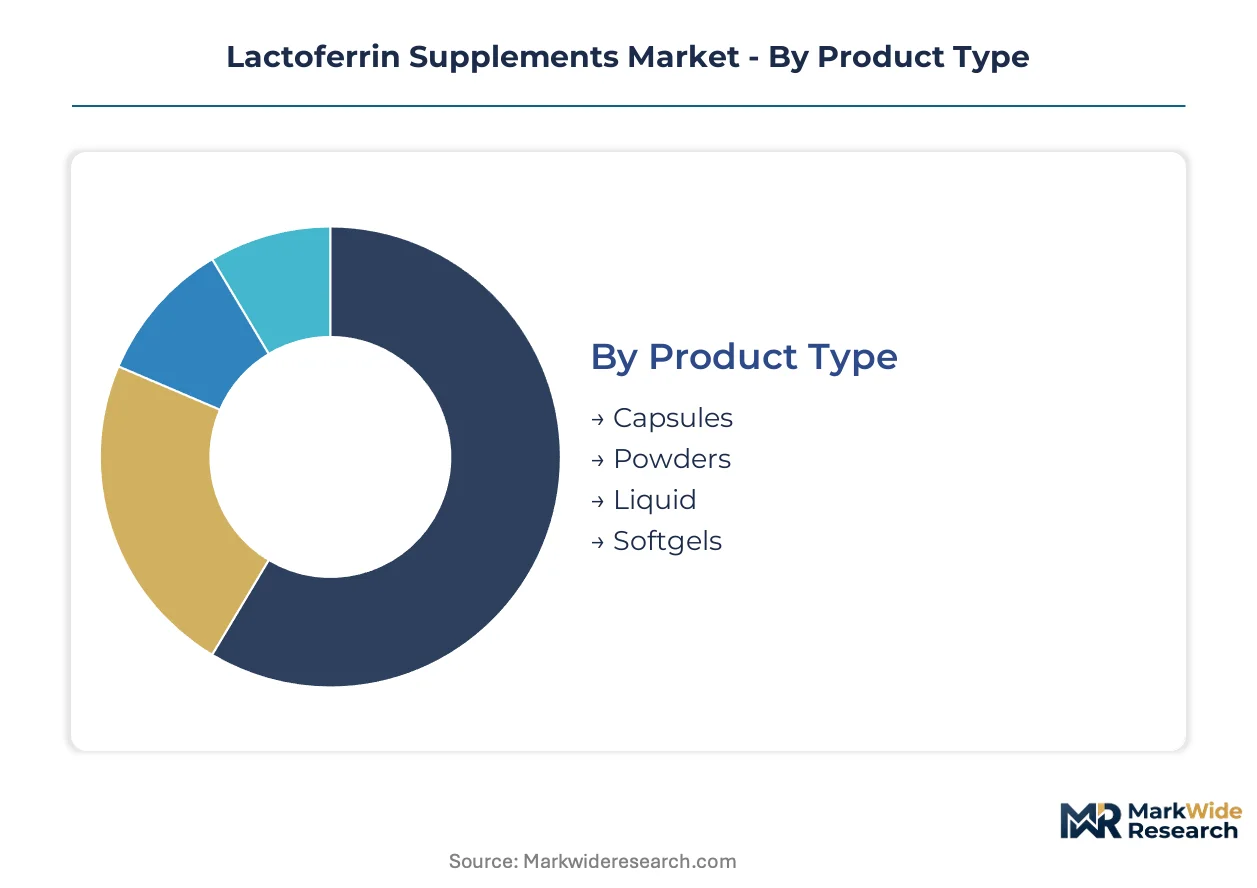
Lactoferrin supplement manufacturers navigate divergent regulatory pathways across delivery formats, with capsule stability requirements differing substantially from liquid bioavailability standards. Segmentation strategies must align purity specifications with end-user compliance expectations and channel-specific documentation demands.
Product Type:
EFSA novel food approvals for bovine-derived concentrates apply uniformly across formats, yet FDA DSHEA notification triggers vary by delivery mechanism and extraction method novelty.
- Capsules:Hard-shell gelatin or vegetable-based encapsulation protects lactoferrin from gastric degradation, enabling enteric release for intestinal absorption. Demand concentrates in North American practitioner channels where functional medicine clinicians prescribe precise 250mg doses for immune modulation protocols.
- Powders:Bulk spray-dried formulations offer dosing flexibility and cost efficiency for direct-to-consumer online retail. Japan's aging consumers favor powder sachets for FOSHU-compliant functional food integration, though moisture sensitivity requires specialized packaging investments.
- Liquid:Aqueous suspensions with preserved protein tertiary structure target pediatric and senior populations with swallowing difficulties. Stability challenges limit shelf life without refrigerated distribution.
- Softgels:Oil-based matrix encapsulation remains niche due to lactoferrin's hydrophilic nature and lipophilic formulation incompatibility. Limited commercial penetration outside experimental delivery research.
Established volume favors capsules; emerging adoption favors powders.
End User:
Application-specific purity tiers separate pharmaceutical-grade clinical nutrition from commodity wellness positioning, with endotoxin thresholds and certificate-of-analysis transparency driving procurement decisions.
- Adults:General wellness consumers seek iron-binding glycoprotein supplementation for routine immune support. Online subscription models in North America and direct-to-consumer platforms in Western Europe dominate procurement.
- Infants:Pediatric nutrition demands the most stringent safety documentation, with infant formula manufacturers requiring supplier certification to ISO 22000 and specific allergen management protocols. Regulatory scrutiny from FDA and EFSA exceeds all other categories.
- Athletes:Sports nutrition brands reformulate recovery products around lactoferrin's iron-modulating properties, with batch-level transparency and banned-substance testing now standard procurement requirements. This segment climbs the fastest as immune positioning displaces basic protein claims.
- Seniors:Aging populations in Japan and Southern Europe prioritize bioactive ingredients with documented absorption profiles. FOSHU framework compliance unlocks premium retail placement for compliant suppliers.
Volume concentrates in adults; margin expansion concentrates in athletes.
Distribution Channel:
Channel selection determines documentation burden, with pharmacies requiring pharmacovigilance reporting capabilities that online pure-plays circumvent.
- Online Retail:Direct-to-consumer platforms enable subscription replenishment and batch-level certificate of analysis transparency. Athlete procurement patterns favor this channel for serious recreational users seeking immune-modulating formulations.
- Pharmacies:Brick-and-mortar dispensaries demand cold-chain integrity documentation and stability data that commodity suppliers cannot provide. Premium capsule positioning commands shelf access where practitioner influence drives purchasing.
- Health Stores:Specialty retailers bridge mass-market and clinical positioning, requiring GMP certification without pharmaceutical-grade purity thresholds. Staff training on iron-binding mechanisms differentiates lactoferrin from generic protein supplements.
- Supermarkets:Mass-market penetration remains limited due to price positioning against commodity whey derivatives and consumer education requirements for bioactive protein differentiation.
Scale advantages favor online retail; credibility advantages favor pharmacies.
Formulation:
Certification stacking creates tiered price positioning, with multiple designations commanding manufacturing complexity premiums that filter through to end-user pricing.
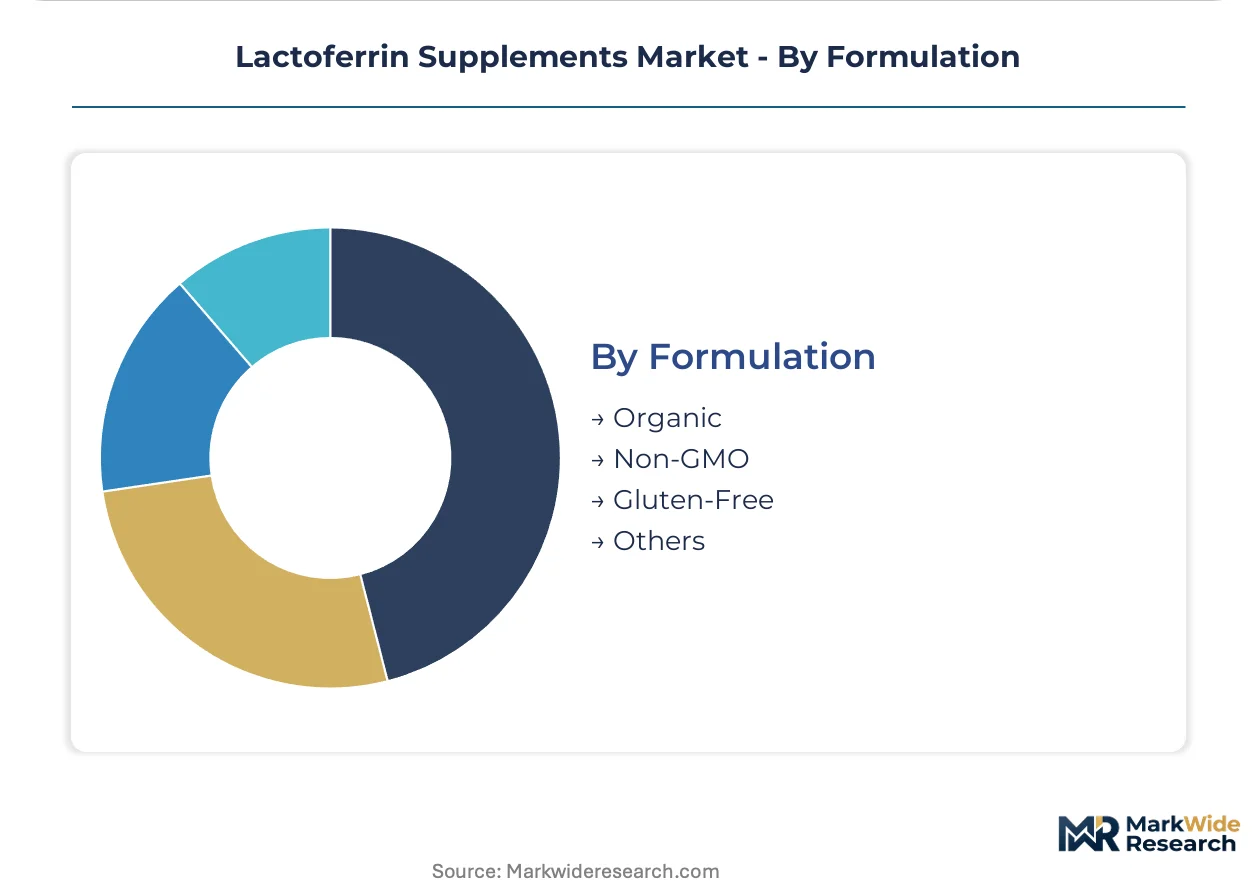
- Organic:USDA Organic or EU Organic certification requires bovine sourcing from hormone-free, pasture-raised dairy operations. Supply constraints limit volume scalability for major brands.
- Non-GMO:Non-GMO Project verification or equivalent European standards address consumer skepticism toward recombinant production methods. Critical differentiator as precision fermentation alternatives enter market.
- Gluten-Free:Celiac-safe certification expands addressable market for autoimmune-sensitive consumers, though lactoferrin's dairy origin makes this designation primarily a cross-contamination assurance.
- Others:Kosher, halal, and allergen-free designations serve specific demographic and religious compliance requirements, with halal certification particularly relevant for Southeast Asian market entry.
Market penetration favors non-GMO; premium pricing favors organic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand exports the majority of pharmaceutical-grade lactoferrin to Japanese infant formula manufacturers and North American sports nutrition brands, creating a trade-flow corridor that shapes global pricing benchmarks.
Japan
Aging consumers drive demand for FOSHU-certified functional foods with documented bioactive properties. The Ministry of Health, Labour and Welfare maintains strict approval pathways for lactoferrin concentrates seeking regulated health claims. Tokyo and Osaka house the headquarters of major infant formula manufacturers sourcing premium ingredients.
United States
Sports nutrition brands reformulate recovery products around immune-modulating ingredients for recreational athletes. The FDA requires New Dietary Ingredient notifications for novel extraction methods or recombinant production approaches. California precision fermentation startups are scaling microbial synthesis alternatives to bypass traditional dairy supply chains.
Netherlands
Dairy cooperatives control high-grade whey permeate feedstock for European pharmaceutical and clinical nutrition markets. EFSA novel food approvals have streamlined market entry timelines for bovine-derived concentrates. Royal FrieslandCampina anchors production capacity across Northern European processing facilities.
China
Infant formula manufacturers seek iron-modulating ingredients with documented safety profiles for domestic premium product lines. The National Medical Products Administration oversees novel food ingredient registrations with evolving standards for bioactive proteins. Yangtze River Delta biotech clusters are developing precision fermentation capabilities for non-dairy lactoferrin supply.
Germany
Functional medicine practitioners prescribe precise-dose capsule formulations for immune modulation protocols. The Federal Institute for Drugs and Medical Devices maintains pharmacovigilance requirements for pharmacy-dispensed supplements. Bavaria hosts specialized biochemical engineering talent for lyophilization scale-up operations.
Lactoferrin Supplements Market Competitive Landscape
Listed leaders compete with private specialists across supply chain integration depth, with publicly traded dairy cooperatives facing off against venture-backed precision fermentation startups. The market structure concentrates around three to five major whey processors controlling raw material access, while mid-tier brands compete on formulation differentiation and channel positioning. Two strategic archetypes dominate: integrated dairy processors with captive milk supply and biotechnology specialists pursuing recombinant production routes. Capacity expansion in spray-drying facilities and strategic partnerships with infant formula manufacturers represent the primary competitive moves.
Among integrated dairy processors, Royal FrieslandCampina and Fonterra exemplify the cooperative-owned archetype with upstream control over milk collection networks. Jarrow Formulas occupies a position within the North American practitioner-channel specialist tier. These three entities represent the spectrum from commodity-scale whey processing to premium capsule formulation, illustrating how market participants navigate divergent purity requirements and regulatory pathways across end-use segments.
| Leading Market Players |
|---|
| Royal FrieslandCampina |
| Armor Protéines |
| Fonterra |
| Jarrow Formulas |
| NOW Foods |
| Morinaga Milk Industry |
| Glanbia Plc |
| Ingredia |
| Arla Foods |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Northern European dairy cooperatives and Japanese infant formula manufacturers lock in multi-year supply access while anchoring price visibility against spot whey permeate volatility. These arrangements insulate premium-grade lactoferrin purchasers from cation exchange resin cost fluctuations and seasonal milk supply swings.
Pricing Analysis
Extraction-technology pricing gaps separate cation exchange chromatography products from emerging precision fermentation alternatives, with recombinant microbial production commanding development premiums against established bovine-derived supply. Pharmaceutical-grade certification tiers create three-tier pricing structure across premium, standard, and economy levels based on endotoxin thresholds and batch documentation depth. Cost compression in commodity whey derivatives is intensifying because spray-dried bulk powders face substitution pressure from generic protein concentrates. Sports nutrition brands show least price sensitivity for immune-modulating capsule formulations with banned-substance testing, while direct-to-consumer powder buyers prioritize per-gram economy.
Supply Chain Analysis
The Netherlands and New Zealand anchor pharmaceutical-grade lactoferrin production, with Dutch dairy cooperatives controlling high-grade whey permeate feedstock and Fonterra operating integrated spray-drying facilities across Oceania. Cation exchange resins, buffer chemicals, and pharmaceutical-grade packaging materials feed from petrochemical and specialty chemical suppliers concentrated in Germany and Belgium. Single-source vulnerability concentrates in Northern European whey permeate supply, where cooperative-owned processing infrastructure lacks geographic redundancy. Distribution runs through temperature-controlled logistics networks serving infant formula manufacturers in Japan and practitioner channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward infant formula manufacturers and sports nutrition brands as procurement consolidation concentrates volume among fewer large-scale formulators seeking documented supply security.
For Market Incumbents: Shield market position through backward integration into captive whey permeate supply and pharmaceutical-grade lyophilization capacity additions in Germany or the Netherlands. Precision fermentation startups threaten bovine-derived supply dominance; certification investment in FOSHU and EFSA novel food pathways reinforces regulatory moats against recombinant alternatives. For New Entrants and Emerging Players: Differentiate on recombinant production purity parity with dairy-derived standards to access markets with strict animal-source restrictions. Pediatric nutrition integration offers the most penetrable white-space target given stringent safety documentation requirements that commodity suppliers cannot meet. Practitioner channel partnerships with functional medicine clinicians provide a go-to-market angle commanding price multiples over mass-market positioning. For Investors and Strategic Acquirers: Capital is best deployed toward biotechnology specialists with scaled precision fermentation capabilities and established regulatory submission track records. Long-term viability hinges on demonstrating cost parity with dairy extraction across the next decade while bypassing geographic supply constraints. Watch EFSA tightening of immune health claim substantiation standards as the inflection indicator for clinical evidence investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial synthesis routes bypass Northern European dairy cooperative supply concentration entirely. |
| FOSHU Certification Investment | Japan's Ministry of Health, Labour and Welfare approval unlocks premium retail placement for aging consumers. |
| Practitioner Channel Partnership | Functional medicine clinician relationships build clinical evidence libraries supporting immune modulation claims. |
| Pharmaceutical-Grade Facility Upgrade | Sub-threshold endotoxin specifications enable infant formula manufacturer supplier qualification. |
| Recombinant Production Regulatory Submission | EFSA novel food evaluations for non-bovine sources open EU market entry pathways. |
Research Methodology
A standing panel of infant formula procurement directors, sports nutrition brand formulators, dairy cooperative supply chain managers, and precision fermentation R&D leads provided ongoing calibration against secondary validation. Primary interviews with functional medicine practitioners and pharmacy category buyers supplemented regulatory affairs consultations regarding EFSA and FDA submission pathways. Secondary sources included EFSA novel food opinions, FDA New Dietary Ingredient notifications, Japanese FOSHU approval registers, and dairy industry trade statistics. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, and distribution channel dimensions.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for pharmaceutical-grade protein exports and capacity disclosures from major spray-drying facilities. The analytical framework modeled segmentation across delivery format, purity tier, end-use application, and geographic regulatory cluster throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macro protein supplement demand indicators and bioactive ingredient adoption curves. Forecast inputs incorporated EFSA evidentiary standard evolution timelines and precision fermentation scale-up announcements.
Material uncertainties — regulatory claim substantiation requirement shifts, recombinant production cost parity achievement, and dairy cooperative supply consolidation — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding technology adoption rates and regional regulatory pathway stability. Recalibration cycles align with material shifts in EFSA immune health claim standards and precision fermentation commercial scale achievements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Complete Nutrition Products Market
Nutritional Supplements
South America Nutricosmetics Market
Nutritional Supplements
Ketogenic Diet Market
Nutritional Supplements
Green Food Supplements Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
Bypass Fat Supplement Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Tongkat Ali Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Lactoferrin Products Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
Tryptophan Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Algae Omega 3 Market
Nutritional Supplements
Organic Protein Powder Market