
 Global Friction Products and Materials Market | 2026-2036
Global Friction Products and Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Friction Products and Materials Market Intelligence
Consolidation among large automotive OEMs is hardening procurement requirements for friction material suppliers. Brembo S.p.A specializes in high-performance braking systems for premium vehicle segments. BorgWarner Inc. leverages its extensive powertrain and driveline portfolio to offer integrated solutions. Meanwhile, Akebono Brake Industry Co., Ltd. sustains its market position through deep OEM relationships, particularly within Japan and Southeast Asia.
Friction products and materials are engineered composites designed to manage motion by converting kinetic energy into thermal energy. These materials must maintain a stable coefficient of friction across wide temperature ranges while minimizing wear. Their function is essential in braking and transmission systems. Brake pads made from advanced ceramic materials are gaining share in the passenger car segment, while carbon composite friction plates serve niche, high-performance industrial and aerospace applications.
Market access and product design are shaped by stringent environmental regulations. The US EPA's copper-free brake pad standards and Europe's REACH framework restrict the use of hazardous substances. These mandates compel manufacturers to reformulate products away from traditional materials. Consequently, navigating the dual demands of performance and compliance is the central strategic challenge for material suppliers and parts manufacturers.
Market Dynamics
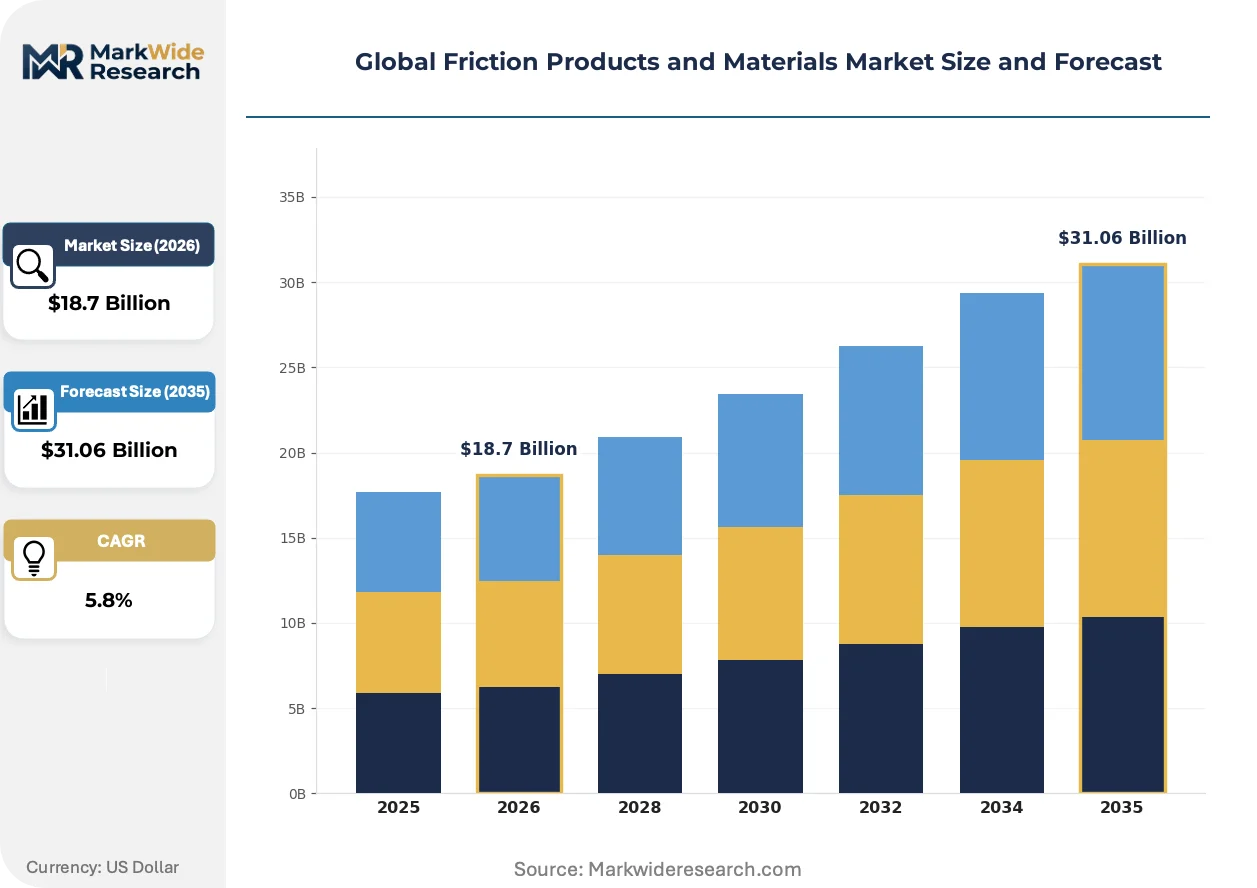
The market's trajectory is defined by the dual pressures of environmental regulation and supply chain consolidation. Stringent mandates phasing out copper and other hazardous materials, combined with hardening procurement requirements from major automotive OEMs, compel simultaneous innovation in material science and business strategy.
Growth Catalysts
- Regulatory Mandates:Stricter standards, including the US EPA's copper-free brake initiative and Europe's REACH framework, directly stimulate R&D and commercialization of alternative materials like advanced ceramics and novel organic formulations.
- Heavy Vehicle Output:Expansion in the production of commercial trucks and buses, particularly in industrializing economies, drives volume demand for durable, high-performance brake linings and pads engineered for severe-duty cycles.
- Aftermarket Upgrades:A growing vehicle parc in China and Southeast Asia fuels demand in the automotive aftermarket for higher-performance, non-asbestos organic (NAO) and ceramic brake pads as consumers seek improved safety and driving experience.
Market Restraints
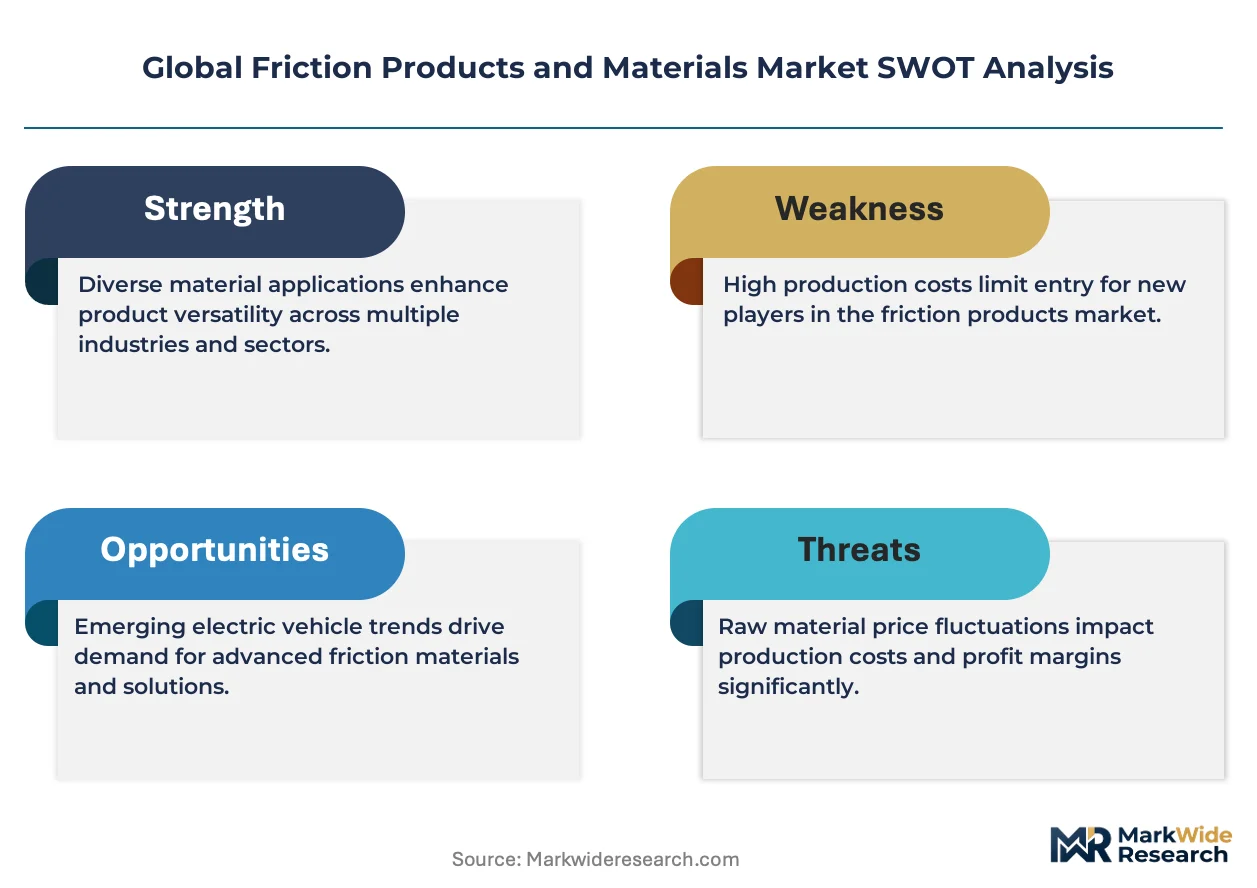
- Raw Material Volatility:Fluctuating prices for critical inputs such as phenolic resins, specialized fibers, and metallic powders directly impact production costs and compress profit margins for friction material manufacturers.
- Regenerative Braking Systems:The increasing prevalence of electric and hybrid vehicles with regenerative braking reduces the wear on conventional friction brake components, extending replacement intervals and dampening long-term aftermarket demand.
- Performance Trade-Offs:A persistent engineering trade-off exists between minimizing noise, vibration, and harshness (NVH) and maximizing durability and stopping power, constraining the development of a single "one-size-fits-all" material solution.
Strategic Opportunities
- Industrial Applications:An emerging opportunity exists in specialized friction materials for industrial machinery, including braking systems for wind turbine yaw controls and clutches for heavy-duty automated manufacturing equipment.
- Bio-Based Materials:Development of environmentally friendly binders and friction modifiers derived from renewable, bio-based sources presents a key opportunity for differentiation, aligning with sustainability goals and stricter regulations.
- Emerging Market Aftermarket:The aftermarket in Latin American and Southeast Asian countries offers significant growth potential for branded, high-quality friction products as vehicle ownership rises and consumers prioritize safety and reliability.
Industry Challenges
- OEM Validation Cycles:Meeting unique performance, durability, and NVH specifications for each automotive OEM requires long and expensive testing and validation processes, creating high barriers to entry for new suppliers.
- Capital-Intensive Testing:Investment in advanced dynamometers and analytical equipment is essential to develop and certify next-generation copper-free and low-steel formulations, requiring significant upfront capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Friction Products and Materials Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brake Linings, Clutch Facings, Brake Pads, Brake Shoes, Friction Plates Material: Sintered Metal, Organic, Ceramic, Semi-Metallic, Carbon Composite Application: Railways, Industrial Machinery, Construction Equipment, Two-Wheelers, Heavy Vehicles End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Parts Distributors |
| Companies Covered | BorgWarner Inc., Tenneco Inc., Brembo S.p.A, ZF Friedrichshafen AG, Aisin Corporation, Nisshinbo Holdings Inc., Miba AG, BASF SE, Akebono Brake Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Friction Products and Materials Market Strategic Shifts & Innovations
Material science is pivoting from a singular focus on performance to a balanced equation of regulatory compliance, system-level efficiency, and environmental impact. This shift is redefining product development priorities and creating new competitive benchmarks for friction material suppliers globally.
Advanced Ceramic Formulations Advanced ceramic-based brake pads provide a stable coefficient of friction and superior fade resistance at high operating temperatures. Adoption is accelerating beyond niche supercars into the premium and luxury passenger vehicle segments. This material evolution is absorbing market share previously dominated by traditional semi-metallic pads, especially in markets with strict standards for brake dust and noise.
REACH Compliance and Reformulation Europe's REACH framework continues to scrutinize and restrict substances used in friction materials, such as certain binders and metal sulfides. This regulatory pressure forces manufacturers to engage in continuous product reformulation to ensure market access across the European Union. The brake pad and lining segments are most affected, with suppliers investing heavily in R&D to identify and validate compliant, high-performance alternative materials.
Life-Cycle Cost Procurement A preference for total cost of ownership (TCO) analysis is gaining traction among large commercial fleet operators and automotive service chains. This procurement model values demonstrated longevity and reduced rotor wear over low upfront unit prices, disrupting channels focused on commodity replacement parts. The shift is most pronounced in the North American heavy-duty trucking sector and European municipal fleet management.
Global Friction Products and Materials Market Segmentation
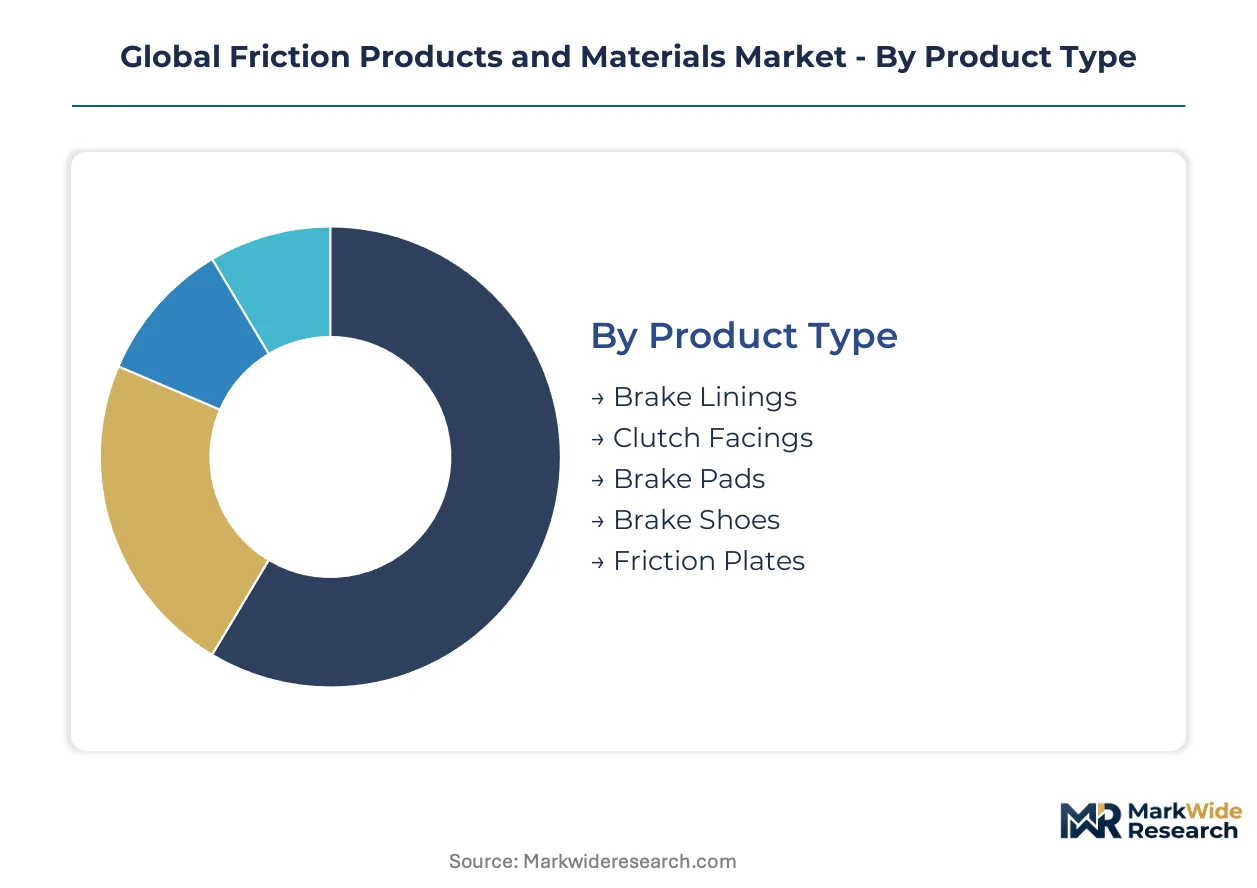
The Global Friction Products and Materials Market is meticulously segmented to reflect the diverse applications and material compositions that define its operational landscape. Understanding these distinctions is crucial for identifying specific market drivers, technological advancements, and regulatory impacts across various industrial and automotive sectors.
Product Type:
Segmentation by product type highlights the varying manufacturing complexities and capital requirements for producing different friction components.
- Brake Pads:These components are engineered for disc braking systems in vehicles, converting kinetic energy into thermal energy through friction. Demand for advanced ceramic and low-metallic brake pads is concentrating in the global passenger car and light commercial vehicle markets, driven by performance and environmental regulations.
- Brake Linings:Designed for drum brake systems and heavy-duty applications, brake linings provide stopping power through friction against a rotating drum. Their robust construction makes them critical in commercial trucking and industrial machinery, where durability and heat dissipation are paramount.
- Clutch Facings:These materials transmit power in manual transmission systems by engaging and disengaging the engine from the gearbox. Demand is significant in agricultural equipment and older vehicle models, particularly in emerging economies.
- Brake Shoes:Integral to drum brake assemblies, brake shoes press the brake lining against the drum. They are widely used in cost-sensitive vehicle segments and certain industrial applications.
- Friction Plates:These specialized plates are found in clutches and braking systems for heavy machinery, aerospace, and high-performance industrial equipment.
Most installed capacity flows through Brake Pads. Expansion is steepest in Brake Linings.
Material:
The material composition segment reveals the technological evolution and performance characteristics of friction products, influencing their suitability for specific applications and regulatory compliance.
- Ceramic:Ceramic friction materials offer superior noise reduction, minimal dust generation, and excellent thermal stability, making them preferred in premium passenger cars. The demand for ceramic formulations is expanding rapidly in the North American and European aftermarket, driven by consumer preference for cleaner wheels and quieter braking.
- Semi-Metallic:Comprising metallic fibers, fillers, and binders, semi-metallic pads provide strong braking performance and high heat resistance, commonly used in heavy-duty and performance vehicles. Their cost-effectiveness and durability ensure consistent demand in commercial vehicle fleets globally.
- Organic:Organic friction materials, often non-asbestos organic (NAO) compounds, are known for their quiet operation and gentle rotor wear. This material type is gaining market share in Asian passenger car segments, particularly in China, where comfort and cost are key considerations.
- Sintered Metal:Produced by compacting metal powders under high heat and pressure, sintered metals provide extreme durability and high friction coefficients for severe-duty applications.
- Carbon Composite:These high-performance materials are used in aerospace, motorsports, and specialized industrial brakes due to their exceptional heat resistance and lightweight properties.
The market's material development focuses on Ceramic compounds. The fastest-growing material segment is Organic formulations.
Application:
This segmentation highlights the diverse end-use sectors for friction products, each with unique performance requirements and operational environments.
- Heavy Vehicles:Friction products for heavy vehicles, including commercial trucks and buses, demand exceptional durability and fade resistance due to high loads and severe duty cycles. Demand is particularly strong in industrializing economies like India and Southeast Asia, where logistics infrastructure is expanding.
- Industrial Machinery:This segment includes friction components for cranes, wind turbines, and manufacturing equipment, requiring robust materials for precise motion control and safety. Specialized friction plates are critical for heavy-duty automated systems in Europe.
- Construction Equipment:Friction materials in excavators, bulldozers, and loaders must withstand extreme conditions and heavy use. The global infrastructure development boom drives consistent demand for these durable components.
- Two-Wheelers:Brake pads and linings for motorcycles and scooters focus on responsiveness and compact design. The Asia-Pacific region, with its high two-wheeler penetration, represents a substantial volume market.
- Railways:Friction materials in railway braking systems require high reliability and consistent performance over long operational periods.
The largest volume application remains Heavy Vehicles. The application segment expanding most quickly is Industrial Machinery.
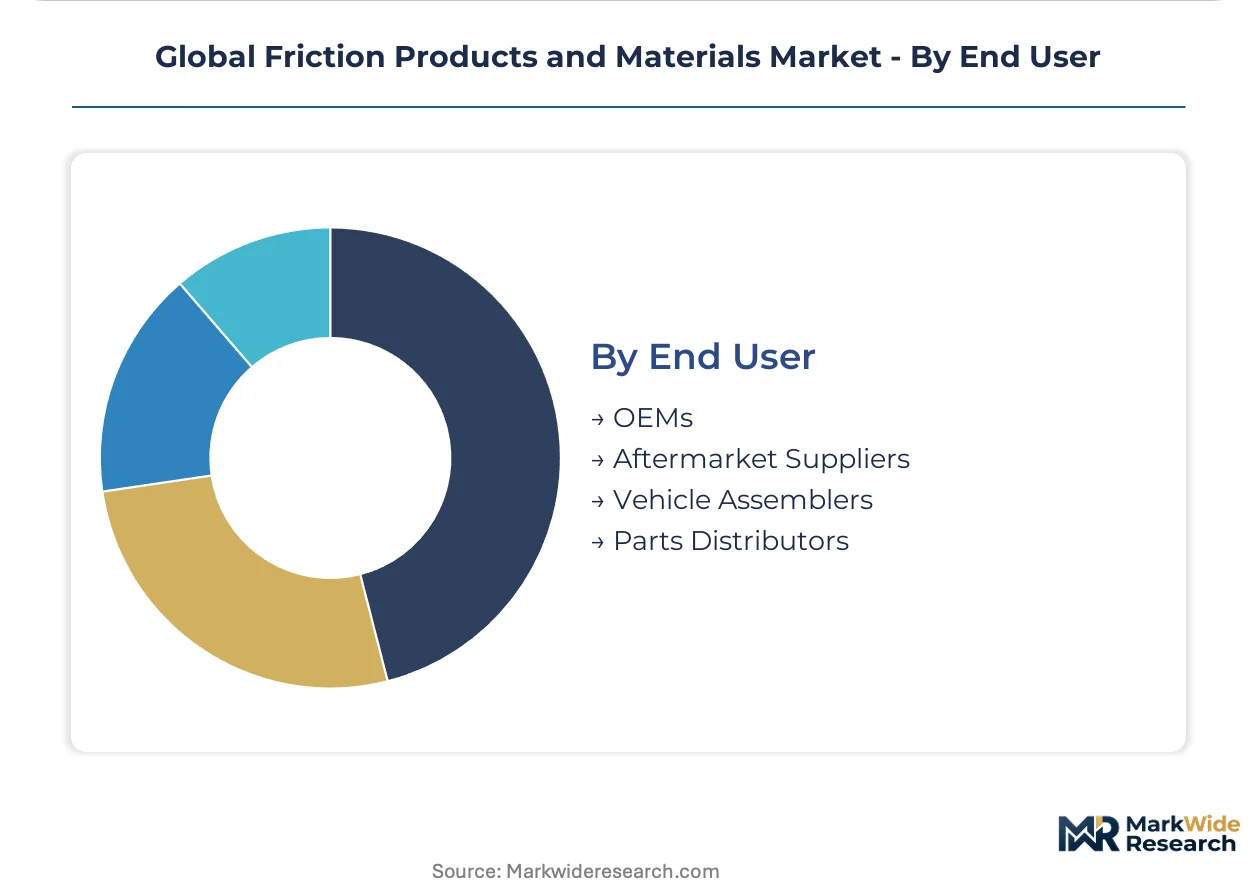
End User:
The end-user segmentation differentiates between channels that purchase friction materials for new vehicle production versus those that serve the replacement market.
- OEMs:Original Equipment Manufacturers integrate friction products directly into new vehicles during the assembly process. Stringent validation and long-term supply agreements characterize procurement from global automotive manufacturers.
- Aftermarket Suppliers:These entities provide replacement friction components for vehicles already in operation. The aftermarket in China and North America is particularly dynamic, driven by vehicle parc growth and consumer upgrade cycles.
- Vehicle Assemblers:Companies that assemble vehicles from components sourced from various suppliers constitute a significant end-user group. Their procurement patterns are often driven by cost efficiency and supply chain reliability.
- Parts Distributors:These intermediaries supply friction products to repair shops, independent garages, and retail channels.
Procurement volume is highest from OEMs. The Aftermarket Suppliers segment shows the most significant growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The friction products and materials market experiences varied growth patterns globally, with established automotive hubs driving innovation alongside rapidly industrializing economies. While the United States prioritizes advanced material adoption in its aftermarket, China's market expansion is heavily influenced by its immense vehicle production volumes.
United States
Aftermarket upgrades and the sustained output of heavy vehicles drive demand for friction materials across the United States. The US EPA's copper-free brake pad standards compel manufacturers to invest in new formulations to maintain market access. Automotive manufacturing clusters in regions like Detroit continue to integrate these compliant materials into their supply chains.
Germany
Germany's market for friction products is characterized by strong demand from its premium passenger car segment and a robust industrial machinery sector. Europe's REACH framework significantly influences material selection, pushing for the elimination of hazardous substances. The Stuttgart region, a prominent automotive engineering hub, remains central to the development and testing of high-performance braking systems.
China
China's expanding vehicle parc and continuous growth in heavy vehicle output fuel significant demand for friction materials. Compliance with national GB standards for automotive components is crucial for suppliers operating within the country. The Yangtze River Delta region, a major manufacturing base, sees extensive production and consumption of both OEM and aftermarket friction products.
India
The Indian market shows strong demand for commercial trucks, buses, and two-wheelers, requiring durable and cost-effective friction solutions. BIS standards for automotive components guide product development and quality control within the domestic industry. Automotive production hubs, such as Chennai, are key centers for the manufacturing and distribution of brake linings and pads.
Brazil
Brazil's market for friction products benefits from demand in agricultural equipment and heavy-duty applications, particularly in its growing industrial sector. CONAMA regulations concerning vehicle emissions and safety standards impact the material composition of brake components. The São Paulo industrial zone serves as a significant hub for manufacturing and distributing friction materials across Latin America.
Global Friction Products and Materials Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a tiered market structure for friction products and materials. This landscape includes global suppliers offering a broad portfolio and regional players specializing in specific applications or material types. Key strategic archetypes include integrated brake system providers, material science innovators, and aftermarket-focused suppliers. Market participants engage in strategic partnerships and continuous R&D investment to secure their positions.
Within the integrated brake system providers, BorgWarner Inc. and Brembo S.p.A exemplify comprehensive offerings across various vehicle segments. Akebono Brake Industry Co., Ltd. represents a major player with deep OEM relationships, particularly within Asian markets. These companies anchor the industry by combining advanced material development with system-level expertise, responding to evolving regulatory and performance demands.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Tenneco Inc. |
| Brembo S.p.A |
| ZF Friedrichshafen AG |
| Aisin Corporation |
| Nisshinbo Holdings Inc. |
| Miba AG |
| BASF SE |
| Akebono Brake Industry Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps in Germany and Japan often leverage long-standing OEM relationships, influencing supply stability and pricing discipline in the friction products market. Their specialized production capabilities allow for premium pricing in niche segments.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity brake pads. The dominant pricing structure is contract-based long-term offtake for OEMs, while the aftermarket often sees per-unit transactional pricing. Price differentiation stems from material quality grade and rigorous OEM certification levels. Pricing softness reflects intense competition from regional manufacturers in Asia, making aftermarket suppliers in emerging economies most price-sensitive. Premium passenger car OEMs prioritize performance over cost.
Supply Chain Analysis
India's BIS standards and CONAMA regulations in Brazil are reshaping sourcing strategies through domestic-content mandates. Supply concentrates in China, India, and Germany for friction materials. The industry relies on phenolic resins, specialized fibers, and metallic powders as key inputs. Commodity price volatility for these raw materials presents a significant structural risk; distribution typically centers on specialized parts distributors for the aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the shift towards advanced ceramic materials in premium passenger vehicle segments. Manufacturers can capture higher value through innovation and compliance with stringent environmental regulations.
For Market Incumbents: Anchor long-term OEM relationships by investing in joint R&D for copper-free formulations. Consolidate production capacity in regions with stable raw material supply to mitigate commodity price volatility. The threat of regenerative braking systems dampens long-term aftermarket demand, necessitating a lever of continuous material science innovation.
For New Entrants and Emerging Players: Begin with specialized friction materials for industrial machinery, such as wind turbine braking systems. Target the aftermarket in Southeast Asian countries, which represents a highly penetrable segment with rising vehicle ownership. A go-to-market angle focusing on bio-based materials offers differentiation and aligns with sustainability goals.
For Investors and Strategic Acquirers: Diversified automotive component conglomerates are the most active acquirers in this space, seeking to broaden their friction product portfolios. The market shows long-term viability over a 5-10 year window, driven by continuous material innovation. Acquisition targets should be material science innovators specializing in advanced ceramics or bio-based formulations. The signal to watch is the acceleration of copper-free mandates into new geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Materials | Expanding production of ceramic brake pads meets rising demand in premium passenger car segments. |
| Joint R&D for Bio-Based Formulations | Collaborative research with chemical companies addresses REACH framework compliance and sustainability objectives. |
| Aftermarket Channel Development in Asia | Establishing distribution networks in China and Southeast Asia captures growth from a large vehicle parc. |
| Acquisition of Niche Industrial Specialists | Integrating specialized friction material manufacturers strengthens positioning in wind turbine and heavy machinery applications. |
| Investment in Copper-Free Testing Facilities | Advanced dynamometer and analytical equipment accelerate validation of compliant brake pad formulations for US EPA standards. |
Research Approach
Direct dialogue with material scientists, OEM procurement leads, aftermarket distributors, and fleet managers provided primary insights. This was validated through secondary research, including US EPA reports, Europe's REACH framework documents, and national GB standards from China. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
The quantitative model produced volume and value projections across the analysis window, segmented by product type, material, application, and end-user. Compound Annual Growth Rates were derived from historical trends and projected technological shifts. Vehicle parc growth in China and copper-free material adoption rates served as key forecast inputs.
Caveats apply where changes in global trade policies or unforeseen advancements in regenerative braking technology could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement and raw material stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Anode Carbon Block Market
Industrial Materials
Industrial Round Wood Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
Petrochemical Fasteners Market
Industrial Materials
Vinyl Extrusion Equipment Market
Industrial Materials
Heat Shrink Tubing and Sleeves Market
Industrial Materials
Elastomeric Couplings Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Encapsulated Gaskets/Seals Market
Industrial Materials
Industrial Seals Market
Industrial Materials
Powder Funnels Market
Industrial Materials
Steel Wire Rope and Plastic Rope Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
Atomizing Metal Powder Market