
 Encapsulated Gaskets/Seals Market | 2026-2036
Encapsulated Gaskets/Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Encapsulated Gaskets/Seals Market Foresight
Modular seal-and-gasket kits is consolidating buyer preference across maintenance procurement channels. Trelleborg AB leverages its polymer compounding depth to supply integrated sealing modules for process equipment. Marco Rubber & Plastics LLC anchors North American distribution through specialized fabricators serving aerospace tier suppliers. Seal & Design Inc competes on rapid-turn custom cutting for regional machinery rebuild programs.
Encapsulated gaskets/seals combine an elastomeric or metallic core with a chemically resistant outer jacket, typically PTFE or fluoropolymer, manufactured through compression molding or sinter bonding to achieve permeation resistance below specified thresholds. These components maintain process containment in aggressive chemical, thermal, or pressure environments where conventional homogeneous seals degrade prematurely. PTFE Gaskets dominate margin pools in semiconductor and pharmaceutical fluid handling due to purity requirements and extended replacement cycles. Rubber Seals sustain volume leadership in automotive assembly and general industrial maintenance, though price compression limits profitability. Metallic Seals occupy the high-reliability tier in oil & gas subsea and aerospace propulsion systems where failure tolerance approaches zero.
EPA emissions regulations and FDA material contact standards in the United States, alongside REACH chemical restrictions and MDR equipment mandates in Europe, compel seal manufacturers to validate compound formulations through certified testing protocols. The EU F-Gas Regulation is progressively constraining fluorinated polymer feedstock availability, forcing reformulation investments across the supply base. Stakeholders must monitor regulatory divergence between North American and European material approval pathways when configuring regional product portfolios.
Market Dynamics
Fluoropolymer feedstock constraints under the EU F-Gas Regulation are forcing compound reformulation across the encapsulated seal supply base, compressing margins while creating tiered supply reliability premiums.
Growth Catalysts
- Pharmaceutical Cleanroom Expansion:Aseptic processing facilities in Germany and Switzerland specify PTFE-encapsulated seals for sterile fluid containment, tightening vendor qualification requirements.
- REACH Chemical Restrictions:ECHA substance evaluations are disqualifying legacy elastomer formulations, accelerating validated fluoropolymer substitution in European process equipment.
- Semiconductor Fabrication:Advanced node manufacturing in Taiwan and South Korea demands ultra-high purity encapsulated seals for chemical delivery systems with sub-ppb contamination thresholds.
Market Restraints
- Feedstock Concentration:Virgin PTFE resin production clusters in Chinese industrial zones expose compounders to export licensing volatility and freight cost spikes.
- Reformulation Capex:ECHA SVHC candidate list expansions force multi-year validation cycles for new polymer jackets, freezing product portfolios during regulatory review.
- Metallic Seal Substitution:Oil & gas subsea operators specify Inconel or titanium seals for extreme pressure envelopes, capping fluoropolymer penetration in deepwater applications.
Strategic Opportunities
- Indian Pharma Manufacturing:CDSCO-aligned facilities building active pharmaceutical ingredient capacity lack qualified local encapsulated seal suppliers, opening import substitution windows.
- Modular Seal Kits:Process OEMs bundle encapsulated seals with predictive maintenance sensors, capturing recurring revenue from installed base monitoring.
- Hydrogen Infrastructure:High-pressure electrolyzer and fueling station construction requires permeation-resistant encapsulated seals for H2 containment at 700 bar.
Industry Challenges
- Compound Synthesis Expertise:Formulators fluent in both fluoropolymer sintering and elastomer core bonding command premium compensation, constraining R&D team scaling.
- Multi-Agency Certification:FDA material contact validation, EPA emissions compliance, and REACH substance registration create overlapping documentation burdens with divergent timelines.
- Legacy Equipment Retrofit:Machinery rebuild programs specify dimensional drop-in replacements, limiting design freedom for next-generation encapsulated seal architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Encapsulated Gaskets/Seals Market |
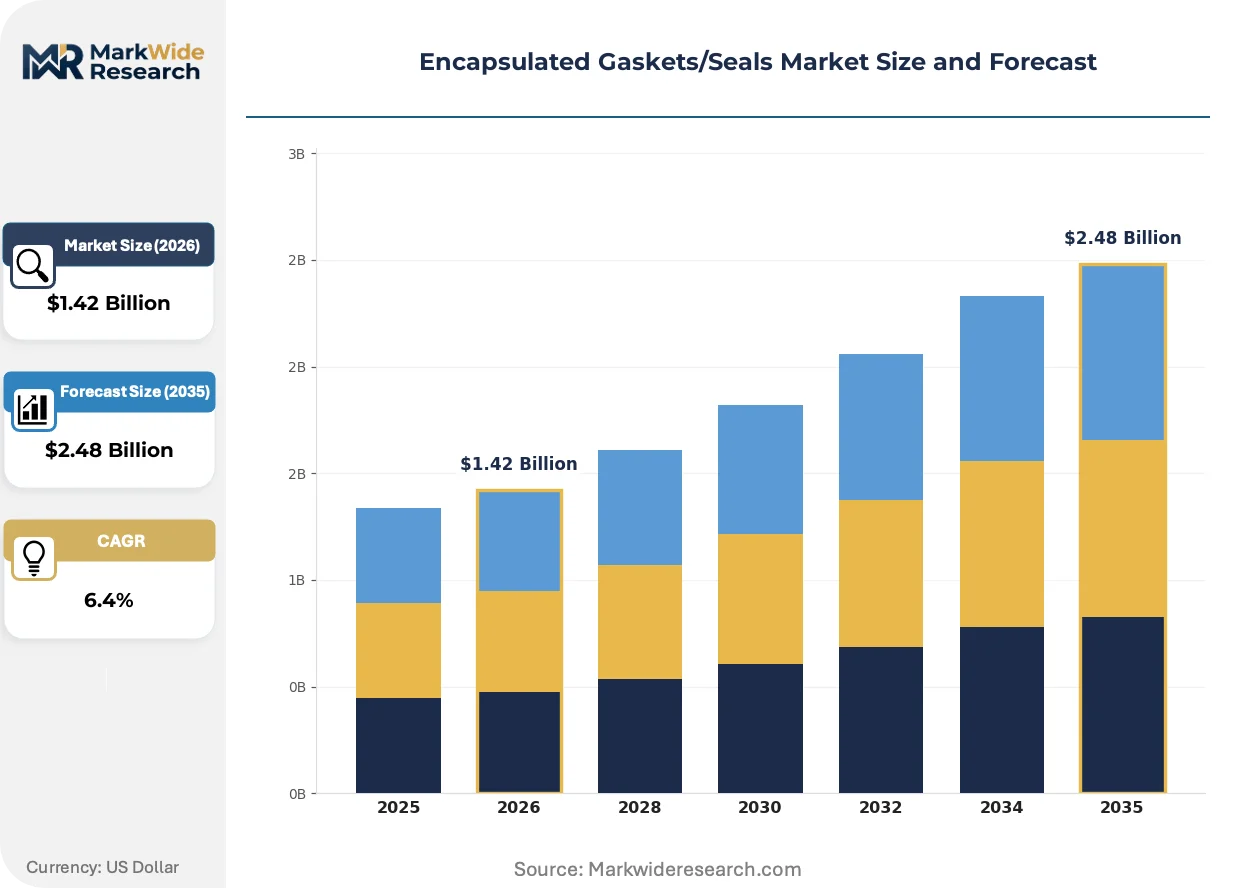
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Seals, PTFE Gaskets, Metallic Seals, Foam Gaskets Industry Vertical: Aerospace, Automotive, Oil & Gas, Pharmaceutical Installation Method: Press-fit, Adhesive Bonding, Screwed, Clamped Application: High Pressure, Low Temperature, Vacuum Sealing, Food Processing |
| Companies Covered | VH Polymers, Seal & Design Inc, Trelleborg AB, Polymax Ltd, MCM SPA, Marco Rubber & Plastics LLC, AS Aston Seals SPA, Vulcan Engineering Ltd, Gasco Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encapsulated Gaskets/Seals Market Shifts & Advancements
Digital manufacturing protocols and material informatics are compressing product development cycles while regulatory divergence between jurisdictions is fragmenting standardization pathways.
Additive manufacturing of fluoropolymer composite jackets is decentralizing prototype-to-production workflows for custom encapsulated seals. Medical device OEMs in Massachusetts and Minnesota now iterate seal geometries in-house before transferring to qualified molders. This capability is compressing minimum viable order quantities and eroding traditional tooling cost barriers for regional fabricators.
EPA emissions standards for fugitive equipment leaks are tightening test protocols for valve and pump seals in refining and chemical processing. The 2024 benzene waste operations NESHAP amendments mandate lower leak detection thresholds, forcing facilities to upgrade from homogeneous rubber to PTFE-encapsulated designs. Gulf Coast petrochemical operators are front-loading seal replacement cycles to preempt enforcement exposure.
Buyer consolidation among pharmaceutical contract manufacturers is concentrating specification authority at fewer procurement desks. Large CDMOs in Ireland and Singapore now mandate pre-qualified seal suppliers with dual-site manufacturing and real-time batch traceability. This pattern is squeezing regional distributors and favoring compounders with integrated quality management systems spanning compounding, molding, and testing.
Encapsulated Gaskets/Seals Market Segmentation
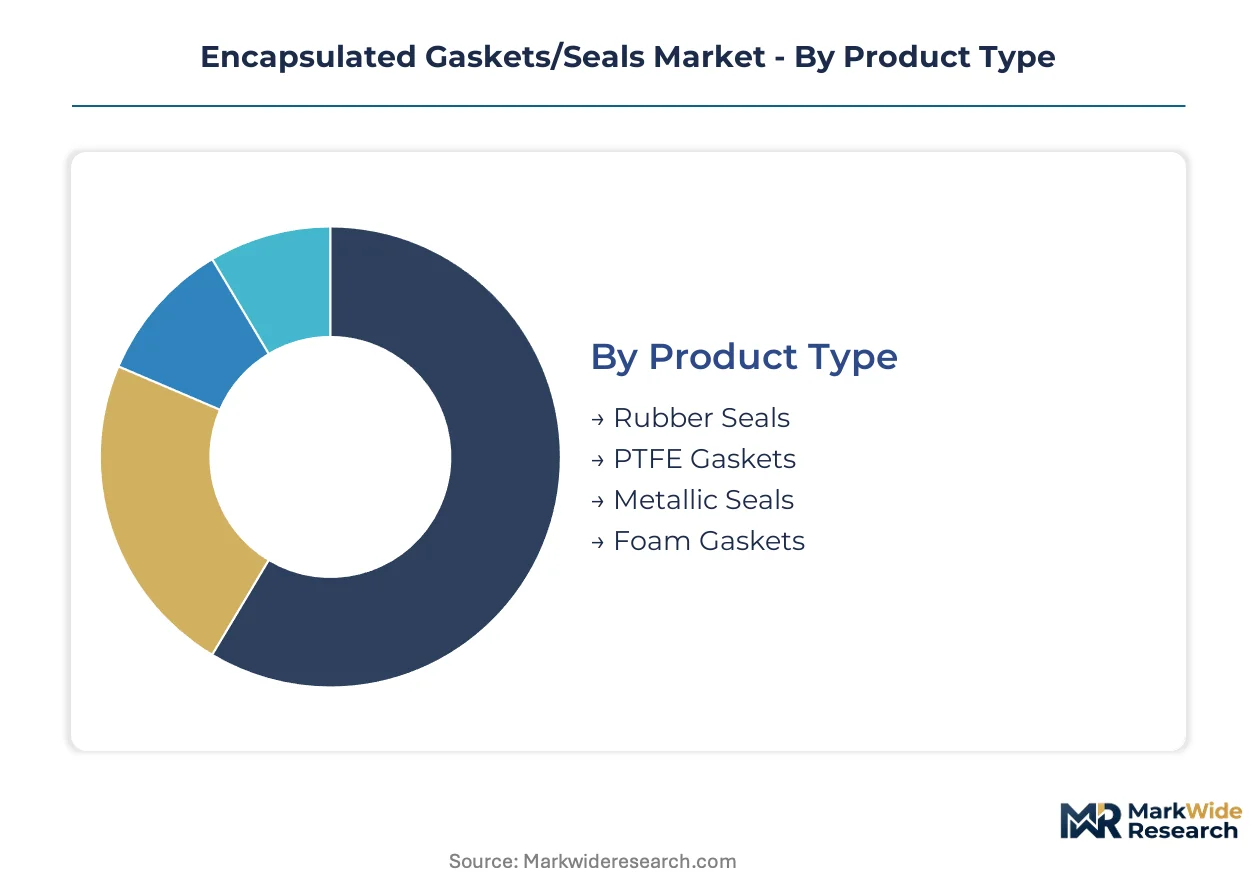
Encapsulated gasket and seal procurement splits sharply between high-volume commodity replacement cycles and precision-engineered specifications where failure costs dwarf component pricing. Understanding these tiered demand patterns reveals where compounders earn sustainable margins versus where distributors fight for share.
Product Type:
Rubber Seals dominate unit volumes through automotive and general industrial maintenance channels, while PTFE Gaskets command price premiums in contamination-sensitive process equipment. The remaining segments occupy specialized niches defined by extreme operating envelopes.
- Rubber Seals:Elastomeric cores with fluoropolymer jackets serve automotive assembly lines and machinery rebuild programs across the US Midwest and Germany's industrial corridor. Price compression limits profitability despite sustaining volume leadership, as OEMs specify validated compounds for EPA emissions compliance in refining applications.
- PTFE Gaskets:Virgin and filled polytetrafluoroethylene encapsulation delivers sub-ppb purity for semiconductor chemical delivery systems and pharmaceutical aseptic processing. Taiwan and South Korea fabrication facilities specify these for extended replacement cycles that minimize cleanroom downtime.
- Metallic Seals:Inconel or titanium cores with diffusion-bonded jackets withstand subsea oil & gas pressures exceeding 15,000 psi.
- Foam Gaskets:Open and closed-cell elastomeric foams fill irregular flange geometries in HVAC and appliance manufacturing.
Today's leader: Rubber Seals. Tomorrow's challenger: PTFE Gaskets.
Industry Vertical:
Application-driven specification authority concentrates in regulated industries where material traceability and batch certification are non-negotiable entry requirements.
- Aerospace:FAA-compliant encapsulated seals for propulsion and fuel systems demand zero-failure tolerance, with Inconel-cored designs specified for turbine environments exceeding 650°C.
- Automotive:Assembly plant consumption of rubber-encapsulated seals runs through just-in-time supply contracts tied to EPA emissions validation for fuel and vapor recovery systems.
- Oil & Gas:Deepwater operators specify metallic seals for extreme pressure envelopes, capping fluoropolymer penetration despite corrosion resistance advantages.
- Pharmaceutical:CDSCO-aligned facilities in India building active pharmaceutical ingredient capacity lack qualified local suppliers, creating import substitution windows for REACH-validated compounders.
Pharmaceutical verticals are climbing the fastest as cleanroom construction accelerates; automotive maintains volume dominance with thinner margins.
Installation Method:
Mounting geometry dictates seal architecture and directly influences replacement labor economics in maintenance scenarios.
- Press-fit:Interference-fit designs with encapsulated jackets serve high-cycling hydraulic and pneumatic actuators where tool-less replacement reduces downtime.
- Adhesive Bonding:Structural acrylic and silicone bonding systems enable lightweight flange designs in aerospace structures, with surface preparation protocols specified by OEM engineering authorities.
- Screwed:Threaded compression seals dominate plumbing and process piping where torque-controlled installation ensures consistent jacket deformation.
- Clamped:Split-flange and tri-clamp configurations facilitate rapid seal exchange in pharmaceutical and food processing equipment requiring frequent cleaning validation.
Press-fit methods anchor current specification standards; clamped designs are gaining fastest through modular maintenance kit adoption.
Application:
Operating envelope severity determines material selection, with extreme conditions justifying premium encapsulation chemistries that conventional seals cannot survive.
- High Pressure:Metallic-cored encapsulated seals with diffusion-bonded jackets contain process fluids in hydraulic fracturing and subsea production trees where elastomer extrusion would cause catastrophic failure.
- Low Temperature:Cryogenic LNG transport and aerospace fuel systems specify fluoropolymer jackets maintaining flexibility below -200°C where nitrile and EPDM compounds glassify and crack.
- Vacuum Sealing:Ultra-high vacuum chambers for semiconductor deposition and space simulation require permeation-resistant PTFE encapsulation with helium leak rates below 10⁻⁹ mbar·l/s.
- Food Processing:FDA material contact validation and 3A sanitary standards govern encapsulated seal selection for dairy and beverage equipment, with clean-in-place compatibility mandating specific jacket formulations.
Vacuum sealing commands the steepest specification premiums; food processing represents the largest addressable expansion segment for validated compounders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor pioneered precision sealing applications for chemical process equipment during the post-war industrial expansion. Swiss pharmaceutical cleanroom engineering and American aerospace propulsion systems subsequently established the material validation protocols that now govern global specification standards.
Germany
Bavarian precision equipment OEMs and North Rhine-Westphalian chemical processors drive specification authority for PTFE-encapsulated seals in sterile fluid containment. ECHA REACH substance evaluations accelerate validated fluoropolymer substitution across process equipment portfolios. Stuttgart's automotive supplier ecosystem consumes rubber-encapsulated seals through just-in-time contracts tied to EPA emissions validation.
United States
Gulf Coast petrochemical operators front-load seal replacement cycles to preempt EPA benzene waste NESHAP enforcement exposure. FDA material contact standards and evolving EPA emissions protocols compel compound formulation validation through certified testing. Massachusetts and Minnesota medical device OEMs iterate seal geometries in-house before transferring to qualified molders.
Switzerland
Swissmedic-aligned aseptic processing facilities in Basel and Zurich specify PTFE-encapsulated seals for sterile pharmaceutical manufacturing with sub-ppb contamination thresholds. EU F-Gas Regulation constraints on fluorinated polymer feedstock force reformulation investments across the supply base. The country's precision engineering heritage sustains vendor qualification requirements that exceed standard European benchmarks.
India
CDSCO-aligned active pharmaceutical ingredient facilities in Maharashtra and Gujarat lack qualified local encapsulated seal suppliers, opening import substitution windows. The country's national pharmaceutical regulator mandates material traceability standards that foreign compounders must satisfy for contract manufacturer approval. Hyderabad's bulk drug manufacturing cluster drives demand for REACH-validated seals in sterile processing environments.
South Korea
Advanced node semiconductor fabrication in Gyeonggi Province demands ultra-high purity encapsulated seals for chemical delivery systems. MFDS pharmaceutical manufacturing standards align with FDA and EMA protocols, creating multi-agency certification requirements for seal suppliers. Busan's industrial equipment sector sources modular seal kits for predictive maintenance integration in process machinery.
Encapsulated Gaskets/Seals Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material validation depth and multi-site manufacturing scale. The market structure tiers between compounders with integrated polymer compounding capabilities and regional fabricators competing on rapid-turn custom cutting. Three archetypes dominate: integrated polymer compounders with captive resin processing, specialized distributors serving aerospace tier suppliers, and rapid-turn fabricators capturing regional machinery rebuild programs. Competitive moves concentrate on geographic expansion through specialized distribution partnerships and portfolio diversification into modular seal-and-sensor kits.
Among European-based integrated compounders, Trelleborg AB exemplifies the polymer compounding depth archetype, while AS Aston Seals SPA occupies a position within Italian precision sealing fabrication. Marco Rubber & Plastics LLC anchors North American distribution through specialized fabricators serving aerospace tier suppliers, representing the regional specialization archetype. These three companies illustrate the tiered competitive structure where material science expertise, geographic proximity to specification authorities, and certification portfolio breadth determine relative positioning.
| Leading Market Players |
|---|
| VH Polymers |
| Seal & Design Inc |
| Trelleborg AB |
| Polymax Ltd |
| MCM SPA |
| Marco Rubber & Plastics LLC |
| AS Aston Seals SPA |
| Vulcan Engineering Ltd |
| Gasco Inc |
| Others |
Supply & Pricing Matrix
Pharmaceutical cleanroom construction in Germany and Switzerland is tightening vendor qualification requirements, forcing compounders to absorb multi-year validation costs that compress margins across standard-grade offerings while creating scarcity premiums for REACH-validated fluoropolymer suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the encapsulated seal market by certification depth and material purity grade. Premium tiers command substantial markups for FDA material contact validation and sub-ppb contamination thresholds demanded by semiconductor fabrication facilities in Taiwan and South Korea. Price erosion runs through rubber-encapsulated automotive seals as Midwest OEMs consolidate procurement desks and squeeze regional fabricators. Pharmaceutical contract manufacturers exhibit lowest price sensitivity due to failure-cost exposure, while general industrial maintenance buyers drive aggressive commodity negotiation.
Supply Chain Analysis
Specialized polymer chemists and sinter-bonding technicians in Germany, the United States, and Japan command compensation premiums that constrain R&D team scaling across the supply base. Virgin PTFE resin production draws from Chinese industrial zones, creating single-source vulnerability for fluoropolymer feedstock availability under EU F-Gas Regulation constraints. Distribution runs through specialized fabricators serving aerospace tier suppliers and rapid-turn regional cutters capturing machinery rebuild programs. Tariff exposure on Chinese resin imports compounds logistics cost volatility for North American compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in encapsulated gaskets/seals hinges on fluoropolymer substitution acceleration and modular seal-and-sensor kit bundling that captures recurring revenue from installed base monitoring.
For Market Incumbents: Hedge against metallic seal substitution in oil & gas subsea by deepening fluoropolymer compounding expertise for hydrogen infrastructure applications at 700 bar pressure envelopes. Secure dual-site manufacturing certifications to satisfy large CDMO procurement mandates in Ireland and Singapore while ECHA SVHC candidate list expansions freeze competitor product portfolios during regulatory review. For New Entrants and Emerging Players: Enter via CDSCO-aligned active pharmaceutical ingredient facilities in Maharashtra and Gujarat where qualified local encapsulated seal suppliers remain absent. Target predictive maintenance sensor integration partnerships with Busan industrial equipment distributors as modular seal kit adoption accelerates. Position around rapid-turn custom cutting capabilities for regional machinery rebuild programs lacking specification authority. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated polymer compounders possessing captive resin processing and REACH-validated formulation libraries spanning compounding, molding, and testing. Long-term viability favors suppliers with demonstrated multi-agency certification navigation across FDA, EPA, and ECHA protocols. Watch EU F-Gas Regulation enforcement intensity as inflection indicator for fluoropolymer feedstock scarcity premiums and reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Virgin PTFE Resin | Reduces Chinese import dependency and secures supply continuity for REACH-validated compounders. |
| Predictive Maintenance Sensor Bundling | Captures recurring revenue from pharmaceutical OEMs in Basel and Singapore monitoring installed base performance. |
| Dual-Site Manufacturing Certification | Satisfies CDMO procurement mandates requiring real-time batch traceability across sterile processing environments. |
| Hydrogen Infrastructure Seal Qualification | Positions compounders for 700 bar electrolyzer and fueling station construction in Germany and South Korea. |
| Regulatory Divergence Monitoring | Enables rapid portfolio reconfiguration as EPA emissions standards and REACH substance evaluations diverge. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through customs data and chemical industry association filings, and technical specification review — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed maintenance directors at Gulf Coast petrochemical facilities, precision equipment OEMs in Bavaria, pharmaceutical contract manufacturing procurement leads in Ireland, and aftermarket service heads at aerospace tier suppliers. Secondary sources included SEC 10-K disclosures from listed compounders, ECHA substance registration databases, and FDA material contact validation records.
Data-stream reconciliation across product type, industry vertical, installation method, and application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand modeling incorporating fluoropolymer substitution rates, cleanroom construction pipelines, and hydrogen infrastructure deployment trajectories. Forecast inputs captured EPA benzene waste NESHAP amendment compliance timelines and EU F-Gas Regulation feedstock constraint intensity.
Inputs from ECHA substance evaluations and FDA validation databases were available through the study window; gaps in real-time CDSCO facility audit schedules introduce uncertainty bands around Indian pharmaceutical penetration assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and feedstock licensing continuity. Material deviation in EU F-Gas Regulation implementation pace or EPA emissions standard tightening warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Asia-Pacific Industrial Flooring Market
Industrial Materials
United States Engineering Plastics Market
Industrial Materials
Modified Wood Market
Industrial Materials
Industrial Absorbents Market
Industrial Materials
Vinyl Extrusion Equipment Market
Industrial Materials
Wire Drawing Dies Market
Industrial Materials
Asia-Pacific Wood Based Panel Market
Industrial Materials
Industrial Mixers Market
Industrial Materials
Anode Carbon Block Market
Industrial Materials
Middle East Activated Carbon Market
Industrial Materials
Wedge Wire Screen Market
Industrial Materials
Plastic Gears Market
Industrial Materials
Continuous Mesh Belt Furnaces Market
Industrial Materials
Plastic Injection Mold Market
Industrial Materials
North America Activated Carbon Market