
 Global Friction Modifiers Market | 2026-2036
Global Friction Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Friction Modifiers Market Foresight
Fleet operators and heavy machinery end users is rotating toward higher-specification lubricants as fuel economy targets tighten across commercial vehicle segments. BASF SE leverages its integrated polymer chemistry portfolio to supply friction modifier intermediates directly to lubricant blenders. Croda International Plc anchors its position through bio-based ester technologies that address renewable content mandates in European formulations. Afton Chemical competes on additive package integration, bundling friction modifiers with detergent-dispersant systems for OEM factory fills.
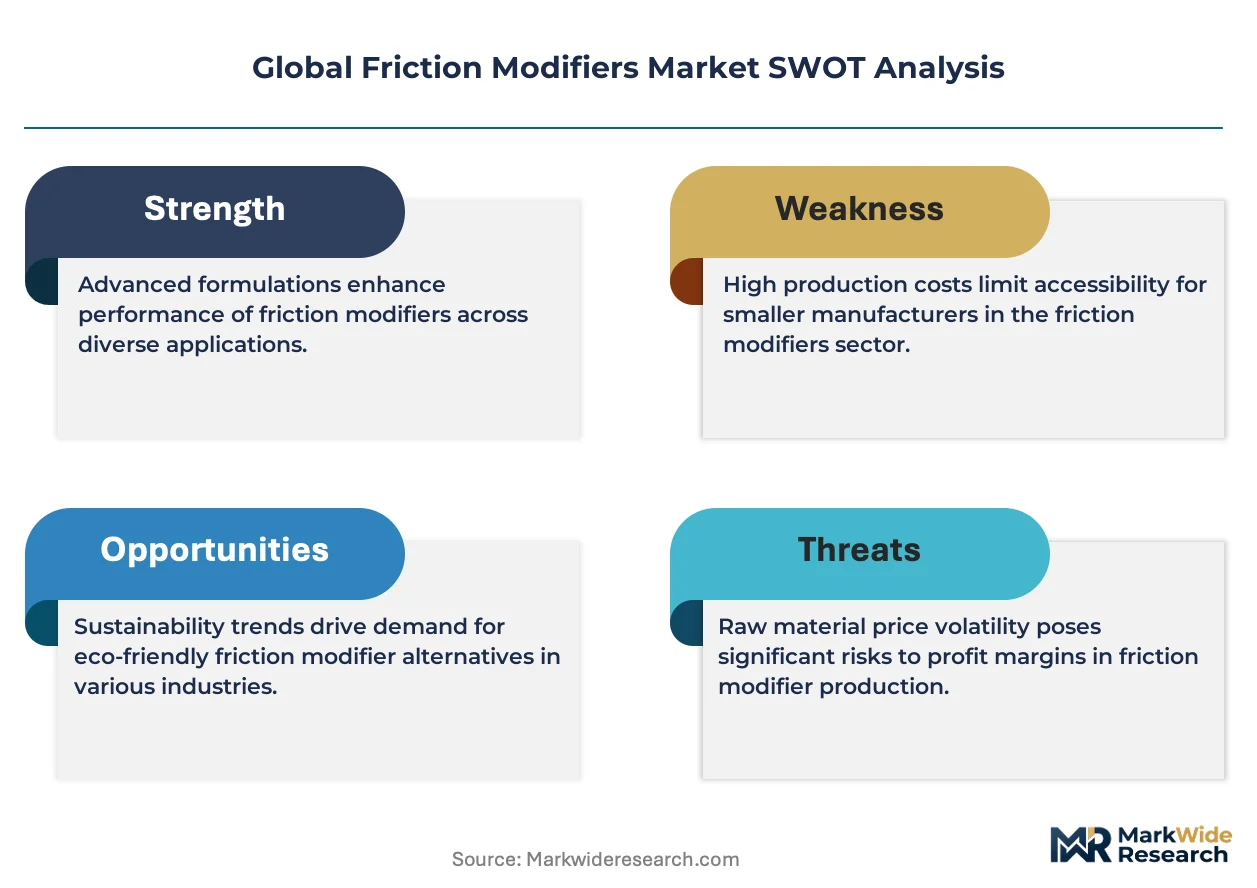
Friction modifiers are surface-active chemical additives—typically organic molybdenum compounds, fatty acid esters, or functionalized polymers—that form tribofilms at metal interfaces to reduce boundary friction coefficients in lubricated systems. These additives operate at concentrations of 0.1–2.0 wt% in finished lubricants, targeting friction coefficients below 0.05 under mixed lubrication regimes to improve mechanical efficiency and component durability. Synthetic friction modifiers lead value generation due to their thermal stability above 150°C and compatibility with Group III/IV base oils, while organic variants occupy the high-volume aftermarket segment where cost sensitivity dominates procurement decisions. Hybrid chemistries represent the fastest-growing product category as formulators seek to balance performance and sustainability credentials across engine oils and metalworking fluids.
The EPA regulates friction modifier components under the Toxic Substances Control Act, while REACH mandates disclosure and restriction of certain organometallic compounds in European lubricant formulations. China's SAMR enforces GB 11121 and GB 11122 standards that specify friction performance benchmarks for gasoline and diesel engine oils, directly shaping product qualification requirements for market access. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
Automotive OEM procurement of low-friction engine oils is concentrating demand among lubricant blenders capable of delivering Group III/IV base oil compatibility, compressing the supplier base toward integrated additive manufacturers.
Growth Catalysts
- EPA emissions mandates:US automotive OEMs are qualifying friction modifier packages that reduce parasitic engine losses to meet Corporate Average Fuel Economy thresholds.
- Hybrid ester chemistry:Formulators combining bio-based feedstocks with synthetic backbones are capturing renewable content mandates without sacrificing thermal stability above 150°C.
- Metalworking fluid reformulation:Japanese precision machinery manufacturers are specifying friction modifiers for minimum quantity lubrication systems to extend tool life in high-speed machining centers.
Market Restraints
- Organomolybdenum supply concentration:Production of molybdenum dithiocarbamate intermediates concentrates among Chinese specialty chemical manufacturers, exposing blenders to raw material allocation risk.
- REACH authorization timelines:ECHA's substance evaluation procedures for certain fatty acid derivatives are extending reformulation qualification cycles by 18-24 months.
- Mineral oil base stock displacement:Group I base oil refinery closures are forcing aftermarket formulators toward higher-cost Group II/III stocks that narrow friction modifier dosage flexibility.
Strategic Opportunities
- India automotive aftermarket:BIS implementation of IS 13656 lubricant standards is creating first-mover advantage for friction modifier suppliers establishing local technical service laboratories.
- Wind turbine gearbox fluids:OEMs specifying 10+ year fill intervals are driving demand for thermally stable polymer friction modifiers that maintain boundary lubrication across temperature cycling.
- EU Green Deal bio-content mandates:Renewable fuel and lubricant blending obligations are accelerating qualification of ester-based friction modifiers derived from non-food crop feedstocks.
Industry Challenges
- Tribochemistry expertise scarcity:Formulation laboratories lack sufficient surface science specialists to model tribofilm formation kinetics across mixed lubrication regimes.
- OEM factory fill qualification cycles:Volkswagen, Toyota, and Ford each maintain distinct friction performance test protocols, multiplying development resource requirements for additive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Friction Modifiers Market |
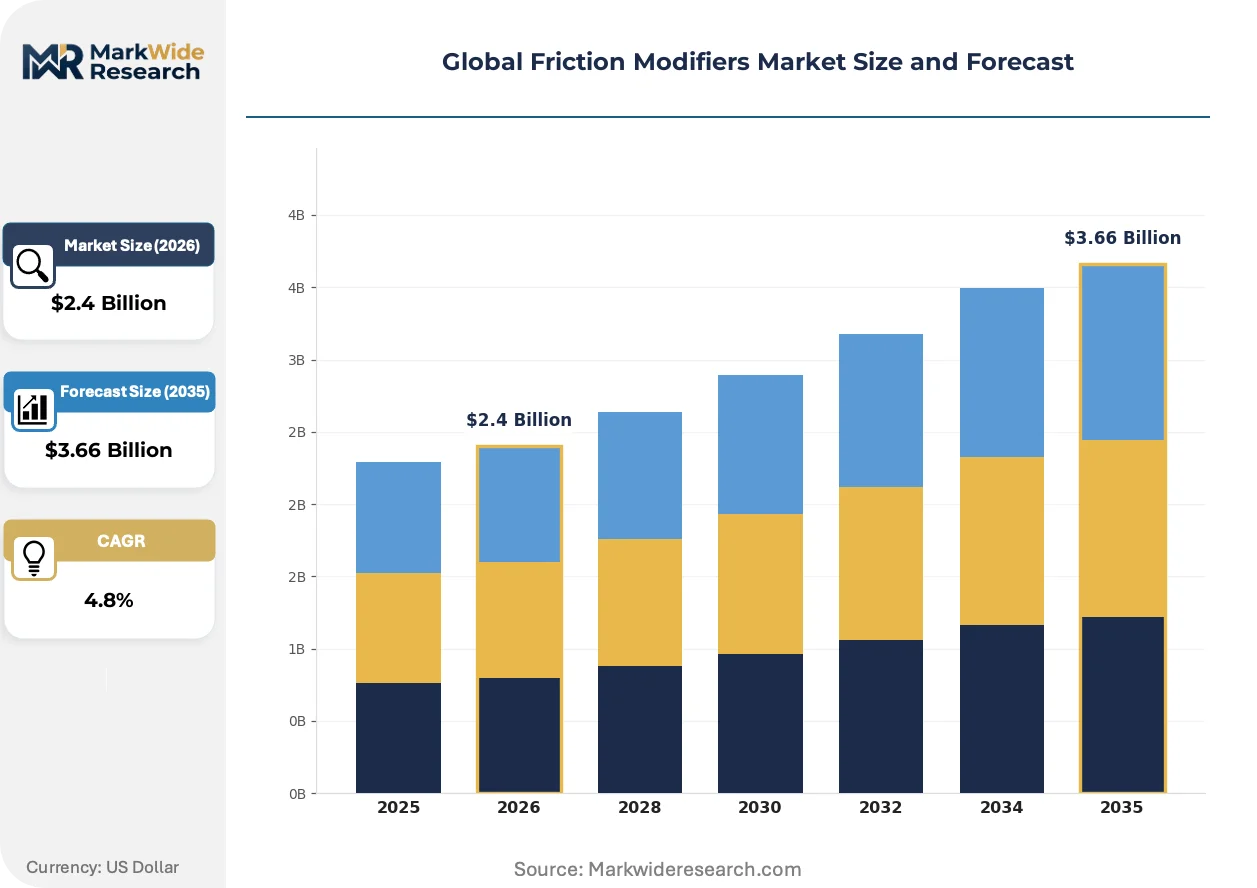
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Inorganic, Synthetic, Hybrid Application: Engine Oils, Gear Oils, Hydraulic Fluids, Greases, Metalworking Fluids End User Industry: OEMs, Aftermarket Suppliers, Heavy Machinery, Agricultural Equipment Distribution Channel: Direct Sales, Distributors, Online Retailers, Industrial Suppliers |
| Companies Covered | BASF SE, Croda International Plc, Afton Chemical, ADEKA CORPORATION, Chevron Corporation, Lubrizol Corporation, Evonik Industries AG, Royal Dutch Shell PLC, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Friction Modifiers Market Shifts & Advancements
Synthetic friction modifier architectures are diverging from legacy organic formulations as thermal stability requirements climb alongside electrified powertrain lubrication demands.
Polymer-based friction modifiers with functionalized methacrylate backbones are supplanting traditional fatty acid esters in hybrid electric vehicle transmission fluids. Japanese and German OEMs are qualifying these chemistries for e-axle applications where electrical conductivity and friction control must coexist. The shift is compressing addressable volume for commodity ester suppliers while expanding margin capture for polymer synthesis specialists.
REACH restriction proposals targeting certain organometallic compounds are forcing reformulation roadmaps across European lubricant blenders. ECHA's 2024-2026 rolling action plan specifically scrutinizes molybdenum-containing additives used in high-performance engine oils. German and French formulators are accelerating hybrid chemistry development to preempt authorization bottlenecks that would disqualify factory fill positions with domestic OEMs.
Fleet operators are consolidating lubricant procurement through direct master service agreements with additive suppliers, bypassing traditional distributor channels. Large US trucking and construction equipment fleets are negotiating specification control that locks in friction modifier chemistry for multi-year contract periods. This concentration is most visible in North American Class 8 commercial vehicle segments where total cost of ownership modeling dominates supplier selection criteria.
Global Friction Modifiers Market Segmentation
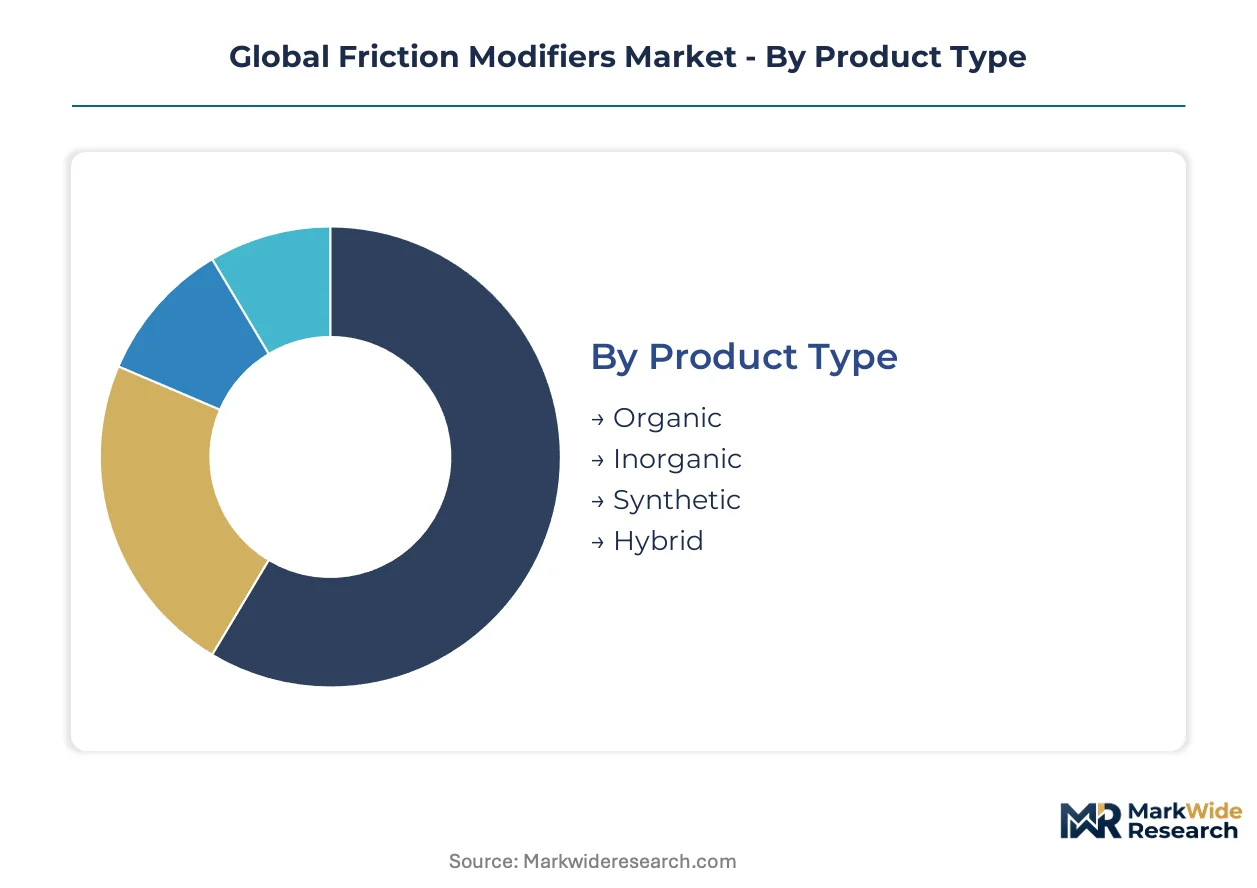
Friction modifier procurement patterns diverge sharply across product chemistries and end-use specifications. Formulators must align additive architectures with base oil groups, regulatory constraints, and OEM qualification protocols that vary by application.
Product Type:
Domestic production dominates organic and inorganic categories in China and India, while synthetic and hybrid formulations flow through export-oriented supply chains centered in Germany, Japan, and the United States.
- Organic:Fatty acid esters and natural oil derivatives constitute the high-volume segment for aftermarket engine oils. Demand concentrates in India's commercial vehicle sector where BIS IS 13656 compliance drives specification upgrades among independent lubricant blenders.
- Synthetic:Polymer-based architectures with functionalized methacrylate or polyalphaolefin backbones deliver thermal stability above 150°C for Group III/IV base oil compatibility. Japanese and German OEMs specify these chemistries for factory fill positions in hybrid electric vehicle transmissions where electrical conductivity requirements complicate formulation.
- Inorganic:Organomolybdenum compounds, primarily molybdenum dithiocarbamates, serve high-performance engine oil applications. Chinese specialty chemical manufacturers control intermediate production, creating raw material allocation exposure for European and North American blenders.
- Hybrid:Bio-synthetic combinations merge renewable ester feedstocks with synthetic backbones to satisfy EU Green Deal bio-content mandates without sacrificing oxidative stability. REACH authorization pressures on pure organometallic additives are accelerating qualification timelines for these formulations.
Synthetic holds the largest share; momentum sits with hybrid.
Application:
Cost tier differentiation separates premium factory fill specifications from price-sensitive aftermarket formulations, with metalworking fluids occupying a distinct technical tier driven by tool life economics.
- Engine Oils:The dominant application by volume, spanning passenger car motor oils and heavy-duty diesel formulations. EPA Corporate Average Fuel Economy mandates and China's GB 11121/11122 standards directly specify friction performance benchmarks that shape additive package design.
- Gear Oils:Hypoid axle and transmission lubricants require extreme pressure compatibility alongside friction reduction. E-axle applications in battery electric vehicles demand polymer friction modifiers that manage electrical conductivity while maintaining boundary lubrication across temperature cycling.
- Hydraulic Fluids:Construction and agricultural equipment specifications prioritize shear stability and filterability over absolute friction coefficient reduction. OEM procurement through direct sales channels concentrates volume among integrated additive suppliers.
- Greases:Thickener compatibility constraints limit friction modifier selection to specific ester and polymer chemistries. Wind turbine OEMs specifying 10+ year fill intervals for main bearing applications drive demand for thermally stable, non-migratory additives.
- Metalworking Fluids:Minimum quantity lubrication systems in Japanese precision machining centers require friction modifiers that extend tool life under high-speed, high-temperature cutting conditions. Reformulation away from chlorinated paraffins under REACH restrictions is expanding addressable volume for synthetic alternatives.
Engine oils command the greatest volume; gear oils are climbing the fastest on electrification demand.
End User Industry:
Customer type fragmentation creates divergent procurement patterns, with OEMs demanding multi-year qualification cycles and aftermarket suppliers prioritizing formulation flexibility and cost responsiveness.
- OEMs:Volkswagen, Toyota, and Ford each maintain proprietary friction performance test protocols that multiply development resource requirements. Factory fill positions lock in additive chemistry for contract periods spanning 3-5 years.
- Aftermarket Suppliers:Independent lubricant blenders serving the automotive service sector dominate organic friction modifier consumption. Group I base oil refinery closures are forcing migration to higher-cost Group II/III stocks that narrow dosage flexibility.
- Heavy Machinery:Fleet operators in North American Class 8 commercial vehicle segments are consolidating procurement through direct master service agreements with additive suppliers, bypassing traditional distributor channels.
- Agricultural Equipment:Seasonal demand patterns and dealer network distribution create specification fragmentation. Equipment manufacturers specify hydraulic fluid and grease friction performance through proprietary test methods that limit supplier switching.
OEMs anchor value capture; heavy machinery is gaining share fastest through fleet consolidation.
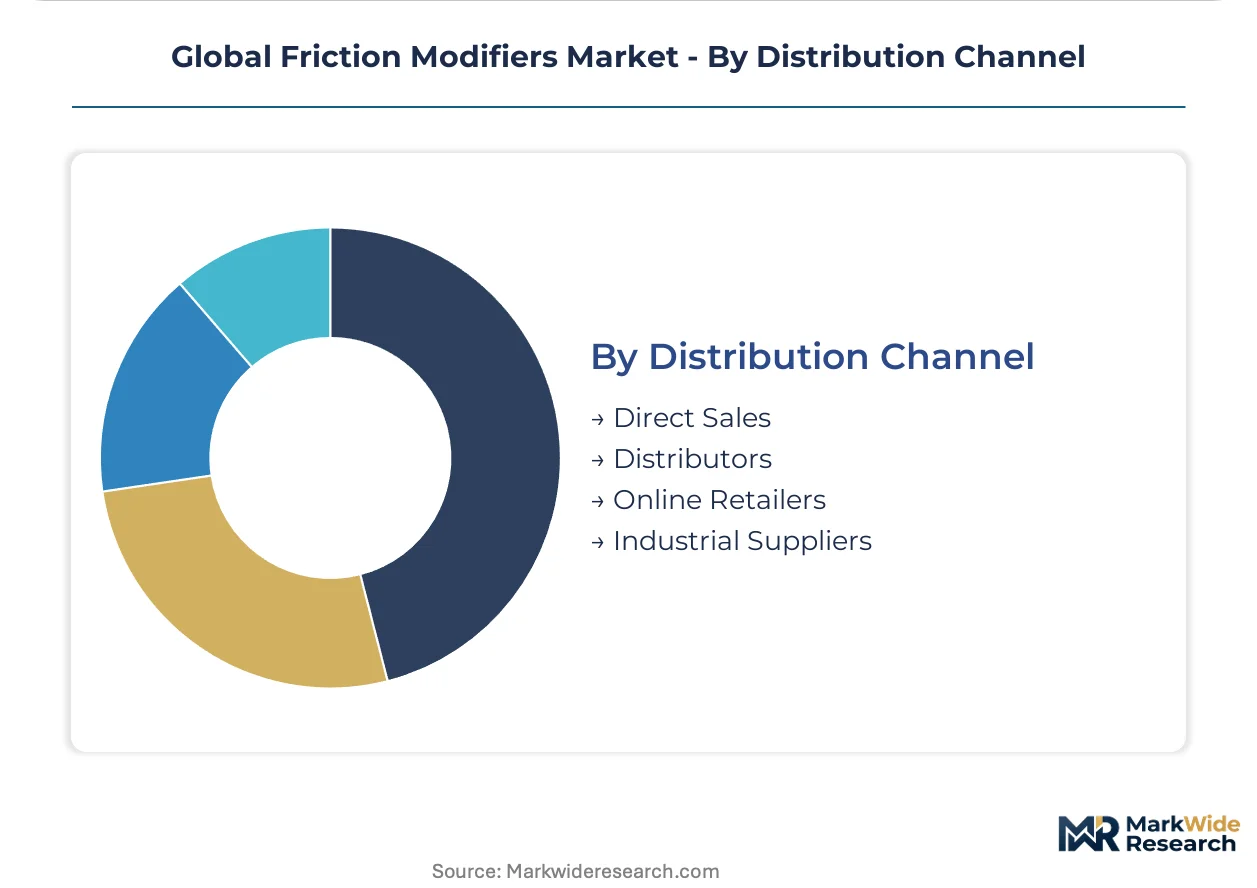
Distribution Channel:
Supply concentration varies by channel, with direct sales capturing integrated additive packages and distributors retaining relevance in fragmented aftermarket segments.
- Direct Sales:Integrated additive manufacturers supply complete friction modifier packages to major lubricant blenders under long-term supply agreements. BASF SE and Afton Chemical leverage direct relationships to bundle friction modifiers with detergent-dispersant systems.
- Distributors:Regional chemical distributors serve mid-tier lubricant blenders and metalworking fluid formulators with smaller volume requirements. Inventory pooling reduces working capital burdens for buyers lacking direct supplier relationships.
- Online Retailers:E-commerce penetration remains limited to specialty lubricant additives for consumer and light commercial applications. Technical specification complexity constrains friction modifier sales through digital channels.
- Industrial Suppliers:Maintenance, repair, and operations distributors serve fleet and heavy machinery end users with packaged lubricants containing pre-formulated friction modifier systems. Specification control by large fleet operators is compressing this channel's relevance.
Direct sales holds the largest share; momentum sits with industrial suppliers as fleet procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp pipeline corridor underwrites Europe's dominance in synthetic friction modifier logistics, connecting German chemical clusters to blending facilities across the continent. This infrastructure anchors the regional supply chain for Group III/IV base oil formulations serving automotive OEMs.
United States
The Houston Ship Channel concentration of lubricant blenders drives procurement of low-friction engine oil packages. EPA Corporate Average Fuel Economy mandates shape additive qualification timelines. Detroit-based automotive headquarters coordinate factory fill specifications directly with integrated additive suppliers.
Germany
REACH authorization pressures on organomolybdenum compounds accelerate reformulation toward hybrid ester chemistries. ECHA's rolling action plan scrutinizes molybdenum-containing additives through 2026. The Ruhr industrial corridor hosts lubricant laboratories developing bio-synthetic friction modifiers for domestic OEM qualification.
China
SAMR enforcement of GB 11121 and GB 11122 standards specifies friction performance benchmarks for gasoline and diesel engine oils. Shanghai and Tianjin lubricant blending hubs concentrate demand for organomolybdenum intermediates. Domestic specialty chemical manufacturers control molybdenum dithiocarbamate production, exposing international blenders to allocation risk.
Japan
Precision machinery manufacturers in the Chubu region specify friction modifiers for minimum quantity lubrication systems. METI industrial standards guide metalworking fluid reformulation away from chlorinated paraffins. Nagoya-based automotive OEMs maintain proprietary friction performance test protocols for e-axle applications in hybrid electric vehicles.
India
BIS implementation of IS 13656 lubricant standards creates specification upgrade pressure in the commercial vehicle aftermarket. Mumbai and Pune lubricant blending clusters drive demand for organic fatty acid esters. Domestic independent blenders migrate from Group I base oils toward Group II/III stocks, narrowing friction modifier dosage flexibility.
Global Friction Modifiers Market Competitive Landscape
Concentration sits with integrated chemical conglomerates possessing polymer synthesis capabilities and direct OEM relationships. The supplier base compresses toward additive manufacturers capable of bundling friction modifiers with complete detergent-dispersant packages. Three archetypes dominate: diversified chemical majors with lubricant additive divisions, specialty ester and polymer synthesis specialists, and petroleum majors with captive additive operations. Competitive moves center on backward integration into bio-based feedstock supply chains and technology licensing agreements for hybrid chemistry platforms.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify the polymer synthesis specialists capturing share in thermally stable friction modifier architectures. Croda International Plc occupies a position among bio-based ester technology providers addressing renewable content mandates. Afton Chemical represents the additive package integrators bundling friction modifiers with factory fill systems for automotive OEMs.
| Leading Market Players |
|---|
| BASF SE |
| Croda International Plc |
| Afton Chemical |
| ADEKA CORPORATION |
| Chevron Corporation |
| Lubrizol Corporation |
| Evonik Industries AG |
| Royal Dutch Shell PLC |
| LANXESS |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between integrated additive manufacturers and automotive OEMs lock in multi-year supply commitments while providing price visibility against volatile organomolybdenum intermediate costs. These arrangements concentrate procurement power among lubricant blenders with direct relationships to Chinese specialty chemical producers, compressing margin flexibility for aftermarket formulators dependent on spot market purchases.
Pricing Analysis
Volume-discount tiering separates factory fill contracts from aftermarket spot purchases, with OEM direct agreements commanding 15-30% price advantages on synthetic polymer friction modifiers. Price differentiation rests on REACH compliance certification and Group III/IV base oil compatibility grades. Cost compression in the organic ester segment is intensifying as Group I base oil refinery closures force blenders toward higher-cost stocks. Aftermarket suppliers exhibit the highest price sensitivity, while wind turbine OEMs prioritize thermal stability over unit cost.
Supply Chain Analysis
Port congestion on the Shanghai-Rotterdam trade lane elevates inbound logistics costs for European blenders sourcing organomolybdenum intermediates. Production concentrates in China, Germany, and Japan, with Chinese manufacturers controlling molybdenum dithiocarbamate output. Raw material dependencies include molybdenum disulfide, fatty acid feedstocks, and functionalized methacrylate monomers. Single-source vulnerability around Chinese intermediate supply creates allocation risk during demand spikes. Distribution runs through direct sales channels for integrated additive packages, with regional distributors serving fragmented metalworking fluid formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Friction modifier demand sits in early-cycle expansion as electrified powertrain lubrication requirements multiply addressable applications beyond traditional engine oils. Hybrid chemistry platforms capturing both performance and sustainability mandates represent the primary penetration vector for new supply capacity.
For Market Incumbents: Secure backward integration into bio-based ester feedstocks to preempt EU Green Deal renewable content mandates. Lock in multi-year factory fill positions with Toyota and Volkswagen through dedicated technical service laboratories. Capacity expansion in the Ruhr industrial corridor addresses REACH authorization bottlenecks threatening organomolybdenum formulations. For New Entrants and Emerging Players: Anchor in India's commercial vehicle aftermarket where BIS IS 13656 implementation creates specification upgrade demand among independent blenders. Target metalworking fluid reformulation away from chlorinated paraffins under Japanese METI standards. A technical licensing partnership with established polymer synthesis specialists accelerates qualification timelines. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid chemistry platforms bridging bio-based feedstocks with synthetic thermal stability. The five-to-ten year viability window favors acquisition of mid-cap ester technology providers with existing OEM technical relationships. Monitor ECHA rolling action plan decisions on molybdenum-containing additives as inflection signals for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Croda International Plc and BASF SE secure renewable ester supply chains against EU Green Deal mandates. |
| Hybrid Chemistry Platform Development | German and French formulators preempt REACH authorization bottlenecks on organomolybdenum additives. |
| Direct Technical Service Laboratory Expansion | Afton Chemical locks in factory fill positions with Detroit-based automotive headquarters. |
| Long-term Supply Agreement with Fleet Operators | North American Class 8 commercial vehicle segments consolidate procurement through master service agreements. |
| Joint Venture for Molybdenum Intermediate Security | European blenders reduce allocation risk from Chinese specialty chemical manufacturers. |
Research Methodology
Operator-level perspectives from lubricant formulation chemists, OEM procurement directors, and additive package engineers anchored the qualitative base for this study. Primary interviews with technical R&D directors at integrated chemical manufacturers and fleet maintenance managers at heavy machinery operators were cross-referenced with secondary validation from customs trade data, SEC filings of petroleum majors, and ECHA substance evaluation databases. Bottom-up volume estimates by product chemistry and application were triangulated against top-down market sizing from regional production cluster analysis.
Sensitivity analysis around base oil group displacement rates and REACH authorization timeline scenarios shaped the forecast framework. Segmentation dimensions modeled include product chemistry tier, end-use application, base oil compatibility grade, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections across the projection horizon. Industry-specific inputs incorporated OEM factory fill qualification cycle durations and metalworking fluid reformulation rates away from chlorinated paraffins.
Decision-makers should treat outputs as directional under assumptions of sustained EPA Corporate Average Fuel Economy mandates and continued Group I base oil refinery closures; material deviation would warrant model refresh. Specific risks include ECHA restriction decisions on molybdenum compounds and Chinese export allocation policies for dithiocarbamate intermediates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Industrial Lubricants Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Plastic Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Global Finished Lubricant Market
Lubricants
Africa Heavy Equipment Lubricants Market
Lubricants
US Industrial Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Mexico Lubricants Market
Lubricants
Iraq Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
Poland Lubricants Market
Lubricants
Mexico Automotive Lubricants Market
Lubricants
Brazil Automotive Lubricants Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
Sri Lanka Lubricants Market