
 Atomizing Metal Powder Market | 2026-2036
Atomizing Metal Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Atomizing Metal Powder Market Intelligence
The European Union's REACH regulation is pivoting the competitive landscape by increasing compliance costs for handling specific metal alloys, effectively raising barriers to entry. Höganäs AB leverages its extensive R&D in sustainable powder production to navigate these complex requirements. Sandvik AB differentiates through its specialization in gas-atomized powders for demanding applications like additive manufacturing. Meanwhile, Carpenter Technology Corporation sustains its market position via a broad portfolio of specialty alloys.
Atomized metal powder consists of fine, typically spherical particles produced by disintegrating a stream of molten metal using high-pressure gas or water jets. The process controls critical properties like particle size distribution and morphology, making these powders essential for precision manufacturing applications. Water atomization remains the dominant production technique for high-volume steel powders due to its cost-effectiveness. However, gas atomization is expanding rapidly, driven by demand for high-purity titanium and nickel powders required in aerospace.
Global quality standards, such as ISO 9001, govern production consistency and material traceability, which are critical for aerospace and medical buyers. Concurrently, worker safety regulations from bodies like the U.S. Occupational Safety and Health Administration (OSHA) and equivalent European agencies mandate strict dust control measures. Decisions on production technology investment will hinge on balancing the cost of water atomization against the performance premiums achievable with gas or plasma atomization.
Market Dynamics
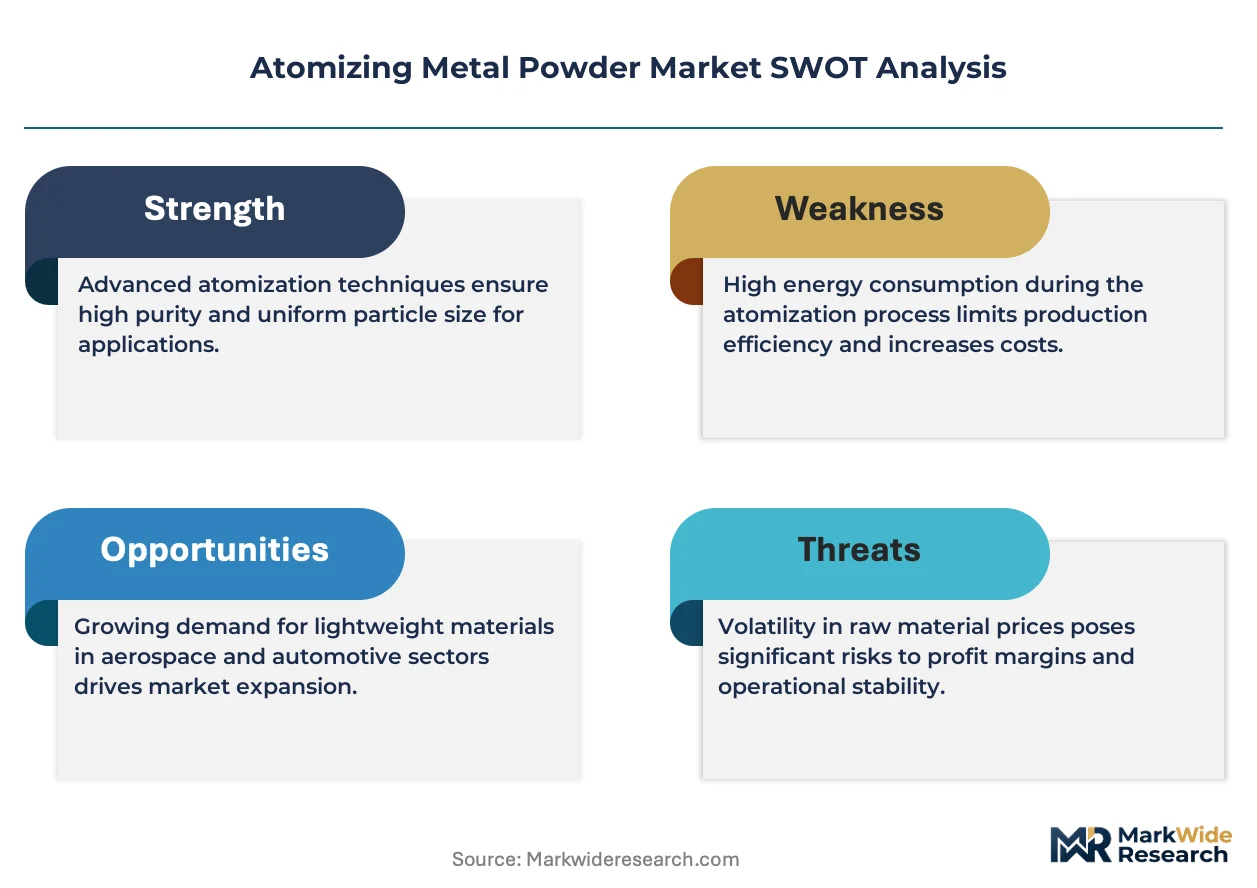
The market's core dynamic is the technological divergence between high-volume, cost-effective water atomization for steel powders and the expanding demand for high-purity, gas-atomized powders for specialized sectors like aerospace, creating a split in technology investment and supply chain focus.
Growth Catalysts
- Additive Manufacturing Expansion:The proliferation of 3D printing technologies, particularly in the aerospace sector for producing complex, lightweight components, directly accelerates consumption of high-performance titanium and nickel alloy powders.
- Automotive Lightweighting Initiatives:Demand from the automotive industry for powder metallurgy parts to reduce vehicle weight and improve fuel efficiency propels consumption of steel and aluminum powders, especially in manufacturing centers like Germany.
- Advanced Material Development:Ongoing R&D in materials science is creating novel alloy compositions with superior thermal and mechanical properties, opening new applications in tooling, energy, and electronics that were previously inaccessible.
Market Restraints
- High Energy Consumption:Atomization processes, especially gas and plasma methods required for high-purity powders, are extremely energy-intensive, making production costs highly susceptible to volatile electricity prices in key manufacturing regions.
- Stringent Regulatory Compliance:Environmental and safety regulations, such as the EU's REACH framework, increase the complexity and cost of handling specific metal alloys, raising barriers to entry for new and smaller producers.
- Raw Material Price Volatility:Fluctuations in the prices of key raw materials like nickel, cobalt, and titanium directly impact powder production costs, creating margin pressure and uncertainty in final product pricing.
Strategic Opportunities
- Medical Device Manufacturing:The growing use of additive manufacturing for custom orthopedic implants and dental prosthetics creates a high-value opportunity for biocompatible powders, including titanium and cobalt-chrome alloys.
- Sustainable Powder Production:Developing processes that utilize recycled metal scrap as feedstock or employ greener atomization gases offers a path to differentiation and meets rising customer demand for sustainable supply chains. *Emerging Geographic Markets: Expanding industrial manufacturing capabilities in countries like India and Mexico present new growth frontiers for powder suppliers beyond the mature markets of North America and Europe.
Industry Challenges
- Complex Quality Certifications:Adhering to multiple quality standards, such as ISO 9001 for general consistency and specific aerospace or medical-grade certifications, involves lengthy and expensive validation processes for each product line.
- Specialized Talent Scarcity:The operation of advanced atomization equipment and the development of new alloy powders require highly skilled metallurgists and process engineers, a talent pool that remains limited globally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atomizing Metal Powder Market |
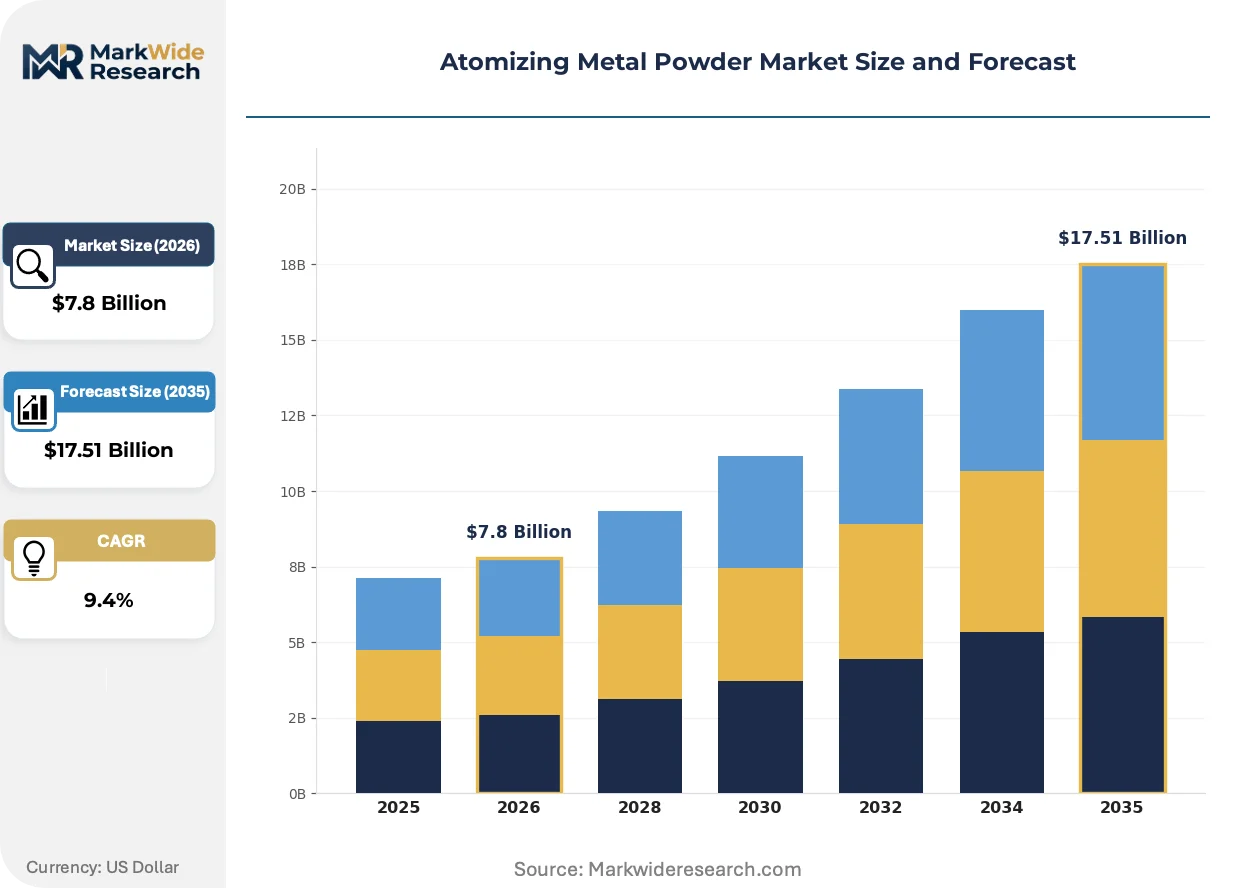
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Atomization Technique: Water Atomization, Gas Atomization, Centrifugal Atomization, Plasma Atomization, Ultrasonic Atomization Metal Type: Steel, Aluminum, Titanium, Copper, Nickel, Zinc Application: Additive Manufacturing, Thermal Spraying, Powder Metallurgy, Surface Coating, Reactive Sintering End User Industry: Aerospace, Electronics, Energy Equipment, Defense, Tooling |
| Companies Covered | Höganäs AB, GKN Powder Metallurgy, Sandvik AB, Carpenter Technology Corporation, Rio Tinto Metal Powders, Pometon, Kobelco, Kymera International, JFE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atomizing Metal Powder Market Strategic Shifts & Innovations
The market is defined by a push towards finer powder specifications and greater process control. This evolution is driven by the demands of next-generation manufacturing technologies and stricter end-use performance criteria, particularly in regulated industries, reshaping supplier capabilities.
Plasma atomization produces highly spherical and pure metal powders with minimal satellite particles, making it ideal for critical applications. It is being adopted by producers of refractory metals and superalloys for the aerospace and medical sectors, where material integrity is paramount. This advanced process is integrating computational fluid dynamics simulation to optimize gas flow and particle formation, enabling unprecedented control over powder characteristics.
U.S. Occupational Safety and Health Administration (OSHA) standards on combustible dust specifically address the hazards posed by fine metal particles. These regulations mandate significant investment in sophisticated dust collection, inert gas handling, and explosion suppression systems within production facilities. Producers of highly reactive powders, such as aluminum and titanium, are most affected, forcing redesigns of plant layouts and workflows to ensure compliance.
Buyers in critical sectors are increasingly demanding lot-to-lot consistency and full material traceability backed by extensive data packages. This shift moves purchasing decisions beyond price, favoring suppliers who can provide comprehensive quality assurance documentation that aligns with standards like ISO 9001. This trend is most pronounced in the aerospace and medical device industries, where component failure carries extreme consequences and regulatory oversight is intense.
Atomizing Metal Powder Market Segmentation
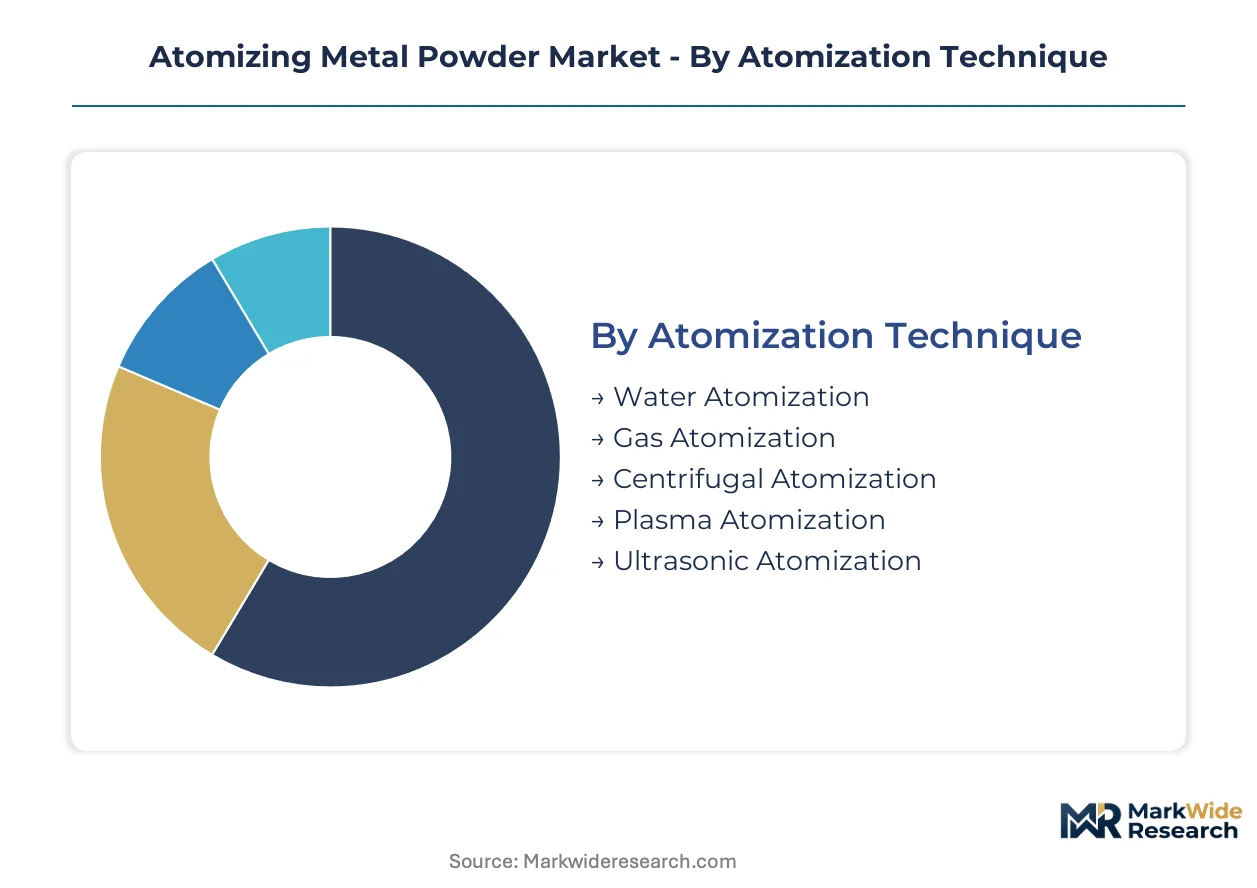
The atomizing metal powder market segmentation provides a granular view of distinct production methods and end-use applications. Understanding these divisions reveals varying cost structures and performance requirements across diverse industries. This analysis clarifies where technological innovation and material science converge to meet specific manufacturing demands.
Atomization Technique:
The atomization technique segment highlights the fundamental trade-off between high-volume, cost-effective production and specialized, high-purity powder manufacturing.
- Water Atomization:This technique utilizes high-pressure water jets to disintegrate molten metal, producing irregularly shaped particles suitable for high-density applications. Demand concentrates in the automotive industry for cost-effective steel powder metallurgy components, reducing vehicle weight.
- Gas Atomization:This process employs inert gas jets to create fine, spherical powders with high purity and controlled particle size distribution. Demand is rapidly expanding in the aerospace sector for complex titanium and nickel alloy components requiring superior mechanical properties.
- Centrifugal Atomization:This technique involves rotating molten metal at high speeds, producing spherical particles primarily used for reactive metals like titanium and superalloys.
- Plasma Atomization:This advanced method generates ultra-pure, spherical powders for critical applications in medical devices and aerospace where material integrity is paramount.
- Ultrasonic Atomization:This emerging process uses high-frequency vibrations to produce extremely fine and narrow particle size distribution powders, finding niches in advanced electronics.
Mature deployment sits with Water Atomization. Newer deployment is concentrated in Plasma Atomization.
Metal Type:
Metal type segmentation reveals varying material properties and cost considerations that dictate powder selection across diverse manufacturing processes.
- Steel:Comprising iron alloys, steel powders are widely used for their strength, cost-effectiveness, and versatility in various powder metallurgy applications. Automotive manufacturers in Germany drive significant demand for steel powders in lightweighting initiatives.
- Titanium:Known for its high strength-to-weight ratio and biocompatibility, titanium powders are crucial for demanding applications requiring corrosion resistance. The aerospace and medical device sectors are driving increased consumption of these high-performance materials.
- Aluminum:Aluminum powders enable lightweighting solutions for automotive and aerospace structures, valued for their density and thermal conductivity.
- Copper:Copper powders are utilized for their electrical and thermal conductivity in electronics, heat sinks, and specialized electrical contacts.
- Nickel:Nickel-based superalloys offer excellent high-temperature strength and corrosion resistance, essential for aerospace engine components and energy applications.
- Zinc:Zinc powders find applications in corrosion protection coatings, batteries, and chemical processes due to their reactive properties.
Steel powders maintain substantial market volume, while titanium powders are expanding most quickly in specialized sectors.
Application:
The application segment illustrates how atomized metal powders are integrated into manufacturing processes to achieve specific functional outcomes.
- Additive Manufacturing:This application leverages metal powders to build complex, customized components layer by layer, enabling geometric freedom and material efficiency. The aerospace industry heavily utilizes additive manufacturing for lightweight, high-performance parts.
- Powder Metallurgy:This traditional manufacturing method forms parts by compacting metal powders and then sintering them, offering cost-effective production of intricate shapes. The automotive sector relies on powder metallurgy for engine components and structural parts.
- Thermal Spraying:This surface coating technique applies molten or semi-molten powders onto a substrate, enhancing wear resistance and corrosion protection for industrial machinery.
- Surface Coating:Metal powders are used to create protective or functional layers on surfaces through various deposition techniques, improving material performance.
- Reactive Sintering:This process involves chemical reactions between powder constituents during sintering to form new phases, crucial for advanced materials development.
Powder Metallurgy represents established industrial use, with Additive Manufacturing demonstrating the steepest expansion trajectory.
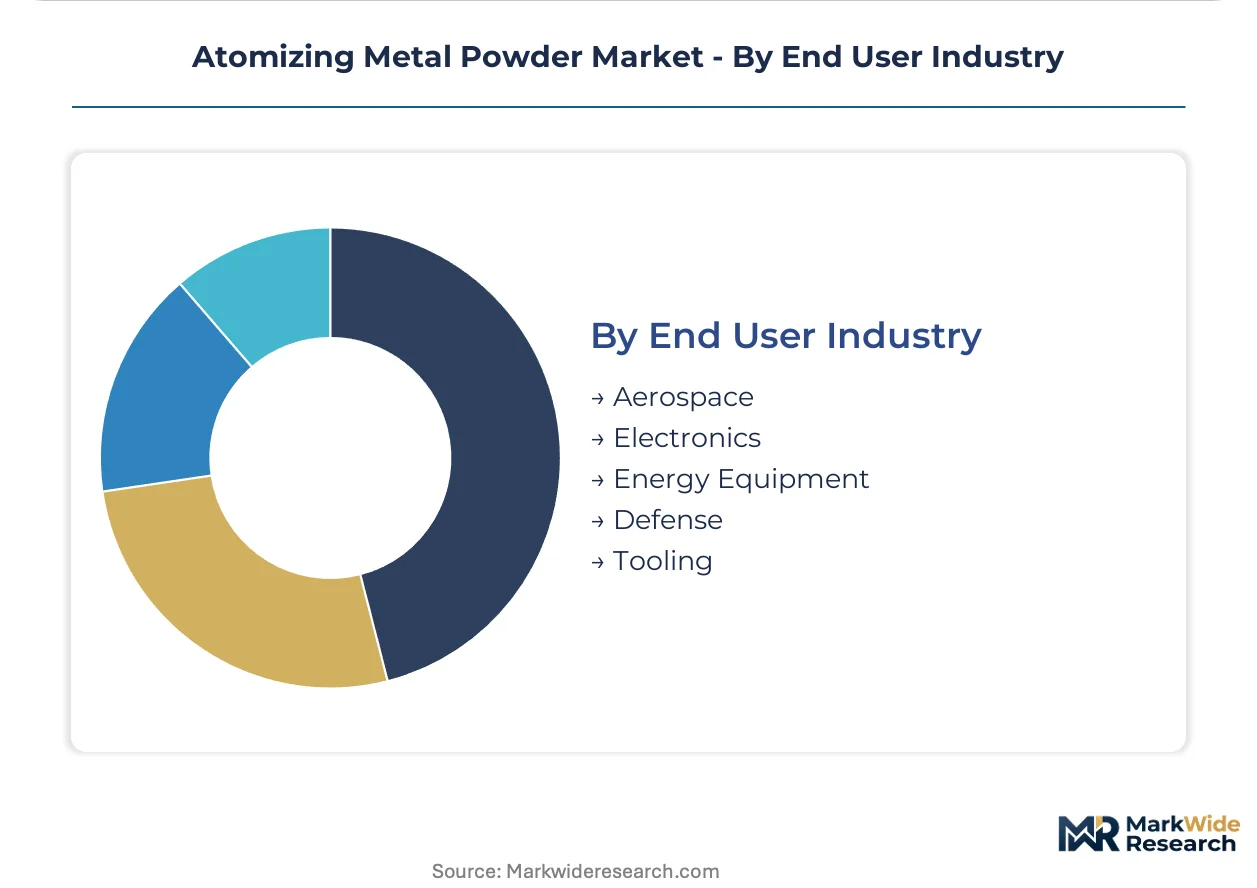
End User Industry:
End user industry segmentation highlights the diverse sectors driving demand for atomized metal powders based on their unique performance requirements.
- Aerospace:This industry requires metal powders for critical, high-performance components that demand exceptional strength, lightweight properties, and temperature resistance. Manufacturers rely on gas-atomized titanium and nickel powders for jet engines and structural parts.
- Tooling:Tooling manufacturers utilize atomized metal powders to produce durable molds, dies, and cutting tools with enhanced hardness and wear resistance. This sector demands specialized steel and superalloy powders for high-precision applications.
- Electronics:The electronics sector employs fine metal powders for conductive inks, solder pastes, and magnetic components, supporting miniaturization and advanced circuitry.
- Energy Equipment:Metal powders contribute to components in power generation, oil and gas, and renewable energy, requiring materials resistant to extreme conditions.
- Defense:The defense industry uses atomized powders for ballistic components, armor, and specialized weapon systems, emphasizing strength and reliability.
Aerospace and Tooling industries currently drive significant innovation in powder specifications, while Electronics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing corridors within advanced industrial economies drive significant concentration for atomizing metal powder production, particularly for specialized applications. These regions benefit from established industrial infrastructure and a skilled workforce, supporting both high-volume and niche powder manufacturing.
Germany
Demand for atomized metal powders in Germany stems from its robust automotive sector and advanced tooling industries. EU's REACH framework significantly influences material handling and production standards for German manufacturers. Industrial clusters in Bavaria, including regions around Munich and Stuttgart, concentrate on high-performance steel and aluminum powders for vehicle lightweighting.
United States
The United States market demonstrates strong demand for high-purity powders within its aerospace and medical device sectors. OSHA standards for combustible dust mandate strict safety protocols for powder producers across the nation. Advanced manufacturing hubs in the Midwest, particularly Ohio and Michigan, specialize in gas-atomized titanium and nickel powders.
China
China's expanding industrial base and electronics manufacturing drive substantial consumption of diverse metal powders. The national GB standards establish critical quality benchmarks for material consistency and traceability. Major industrial zones in the Yangtze River Delta focus on high-volume steel powders and emerging applications in additive manufacturing.
India
India's growing manufacturing capabilities and infrastructure development create new frontiers for metal powder suppliers. The PLI scheme incentivizes domestic production and technological advancement in various industrial sectors. Industrial corridors in Gujarat and Maharashtra are seeing increased investment in powder metallurgy for automotive and general engineering applications.
France
France generates demand for atomized metal powders primarily from its established aerospace and defense industries. CE marking ensures product safety and compliance for all metal powders distributed within the European Union. Toulouse, a major aerospace center, focuses on advanced nickel and titanium alloy powders for critical aircraft components.
Atomizing Metal Powder Market Key Industry Players
European producers anchor one tier; North American specialists hold another, creating a tiered market structure for atomizing metal powders. The competitive environment features companies focused on high-volume commodity powders alongside those specializing in high-purity, niche materials. Strategic archetypes include diversified material suppliers, technology-focused innovators, and regional specialists. Portfolio diversification and extensive R&D in sustainable production represent dominant competitive moves.
Companies with broad material portfolios, Carpenter Technology Corporation and Höganäs AB, exemplify robust market positions through extensive product ranges and ongoing material science R&D. Höganäs AB, a Swedish-based entity, leverages its extensive research in sustainable powder production processes. Meanwhile, Sandvik AB, also from Sweden, sits within the specialized segment, differentiating its offerings through expertise in gas-atomized powders tailored for demanding applications. These entities collectively anchor the premium and specialized tiers of the atomizing metal powder market, demonstrating varied approaches to market leadership.
| Leading Market Players |
|---|
| Höganäs AB |
| GKN Powder Metallurgy |
| Sandvik AB |
| Carpenter Technology Corporation |
| Rio Tinto Metal Powders |
| Pometon |
| Kobelco |
| Kymera International |
| JFE |
Cost & Logistics Intelligence
Aerospace and medical device buyers, with their stringent quality demands, drive value-based pricing for high-purity powders. This concentration influences long-term contract structures and supplier relationships.
Pricing Analysis
Short lead times for specialized metal powders command a premium, while readily available high-volume steel powders often trade at commodity spot prices. The market exhibits a hybrid pricing model combining long-term contract-based offtake for critical materials and transactional spot pricing for high-volume commodities. Quality grade, specifically aerospace or medical-grade certifications like ISO 9001, and customization level are key price differentiation drivers. Pricing softness runs through high-volume steel powders due to intense competition and cost-effective water atomization. Automotive manufacturers are highly price-sensitive for steel powders, whereas aerospace and medical buyers prioritize performance and certification over cost.
Supply Chain Analysis
Regional distribution centers and specialized logistics networks are critical for delivering atomized metal powders, particularly for reactive materials like titanium. Supply concentrates in Germany, the United States, and China, reflecting established industrial bases and advanced manufacturing. The supply chain draws from key raw materials such as nickel, cobalt, and titanium, whose price volatility impacts production costs. Commodity price volatility for these critical inputs creates margin pressure and uncertainty in final product pricing. Distribution runs through a mix of direct sales to large industrial customers and specialized distributors for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atomizing metal powder market is experiencing a vertical-integration race, as producers pursue upstream control over critical raw material sourcing to mitigate price volatility. This strategy aims to secure supply and stabilize production costs.
For Market Incumbents:Anchor market share by continuously investing in sustainable powder production processes, especially given the EU's REACH framework. Diversify alloy portfolios to serve multiple end-user industries and deepen vertical integration into raw material processing. This protects against margin pressure from volatile raw material prices and the emergence of lower-cost regional producers. Investing in advanced R&D for next-generation material compositions maintains a competitive edge.
For New Entrants and Emerging Players:Plasma atomization technology offers a significant entry point for producing ultra-pure, spherical powders. Target the medical device and aerospace sectors with specialized biocompatible alloys like cobalt-chrome for custom orthopedic implants. Partner with additive manufacturing service bureaus to accelerate market penetration and gain rapid qualification for high-value components. Focus on emerging geographic markets like India, where industrial capabilities are expanding.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers seeking specialized capabilities in advanced atomization techniques. Long-term viability rests on securing intellectual property in novel alloy development and advanced process control over the next 5-10 years. Target mid-sized firms with proven expertise in gas or plasma atomization for high-purity titanium and nickel powders. The signal to watch is the increasing adoption rate of additive manufacturing in critical aerospace and medical applications, validating demand for premium powders.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Gas Atomization | Increases supply of high-purity powders for aerospace and medical applications. |
| R&D in Sustainable Production | Addresses regulatory compliance like REACH and meets customer demand for greener supply chains. |
| Vertical Integration into Raw Materials | Mitigates price volatility of nickel and titanium, stabilizing production costs. |
| Specialization in Biocompatible Alloys | Captures high-value opportunities in medical device manufacturing, including orthopedic implants. |
| Geographic Expansion into India | Taps into growing industrial manufacturing capabilities and new market demand for powders. |
Research Approach
Multi-period observation of material consumption trends and technological advancements anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary interviews included metallurgists, procurement leads at aerospace OEMs, additive manufacturing specialists, and regulatory affairs managers. Secondary data sources encompassed ISO 9001 certification databases, OSHA compliance reports, national trade statistics, and academic research on alloy development. A rigorous bottom-up and top-down triangulation process validated the market sizing and growth projections.
Segment-specific weighting across atomization technique, metal type, application, and end-user industry formed the quantitative forecast framework. Additional dimensions included purity grades and regional regulatory compliance frameworks across the analysis window. Compound annual growth rates were derived from historical data analysis and projected future demand influenced by technological adoption. Industry-specific forecast inputs included aerospace production forecasts and automotive lightweighting targets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid shifts in raw material prices or new regulatory mandates. Forecasts reflect assumptions regarding the pace of additive manufacturing adoption and global economic stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
High Pressure Braided Tubing (HPBT) Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Plastic Gears Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Metal Molds Market
Industrial Materials
Modified Wood Market
Industrial Materials
Cork Material Market
Industrial Materials
Steel Wire Rope and Plastic Rope Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
Mineral Processing Equipment Market
Industrial Materials
Welding Consumables Market
Industrial Materials
Global Jet Mill Market
Industrial Materials
Pultrusion Products Market