
 Vinyl Extrusion Equipment Market | 2026-2036
Vinyl Extrusion Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Extrusion Equipment Market Analytics
Asset-light leasing and project finance for extrusion lines is reshaping competitive entry in vinyl extrusion equipment, lowering capital barriers for mid-scale processors in emerging manufacturing zones. KraussMaffei leverages its Munich engineering base to sustain premium positioning in twin-screw systems for rigid PVC formulations. Davis-Standard anchors North American supply through extensive retrofit and service infrastructure. Battenfeld-Cincinnati differentiates via co-extrusion technology leadership across multi-layer profile applications.
Vinyl extrusion equipment comprises heated barrel-and-screw assemblies that plasticize polyvinyl chloride resin compounds through controlled shear and pressure, typically operating at barrel temperatures between 160°C and 210°C with L/D ratios from 24:1 to 36:1, to form continuous profiles, sheets, or pipes for downstream fabrication. Twin-screw extruders command the largest installed base due to superior mixing efficiency for rigid and foamed PVC formulations, while co-extrusion technology captures expanding margin pools as multi-layer barrier and aesthetic profiles displace single-material alternatives in construction end uses. Sheet extruders occupy mature demand territory with replacement-driven economics, whereas advanced extrusion systems integrating melt pump controls are gaining fastest among automotive interior trim suppliers seeking tighter dimensional tolerance.
EPA emissions standards under the Clean Air Act constrain volatile organic compound releases from PVC processing facilities, compelling equipment upgrades with enclosed venting and fume capture systems. REACH registration requirements and RoHS substance restrictions in Europe limit phthalate plasticizer formulations, redirecting equipment specifications toward calcium-zinc and organotin stabilizer compatibility. FDA food-contact regulations in the United States additionally govern vinyl compounds entering limited consumer goods segments. Stakeholders must monitor regulatory divergence between jurisdictions to align R&D roadmaps with divergent compliance timelines rather than single-standard designs.
Market Dynamics
Asset-light leasing and project finance for extrusion lines is compressing capital barriers for mid-scale processors, enabling faster capacity scaling across emerging manufacturing zones without traditional ownership burdens.
Growth Catalysts
- REACH compliance mandates:ECHA registration requirements and RoHS substance restrictions in Europe are redirecting equipment specifications toward calcium-zinc and organotin stabilizer compatibility, creating replacement demand across installed bases.
- Construction sector envelope expansion:Residential and commercial building projects are scaling capacity for window profiles and siding systems, pulling twin-screw extrusion capacity into new plant investments.
- Co-extrusion technology maturation:Multi-layer barrier and aesthetic profiles are displacing single-material alternatives in construction end uses, expanding margin pools for equipment suppliers with advanced die-head engineering.
Market Restraints
- Specialized engineering talent scarcity:Deep expertise in screw geometry optimization and melt pump calibration concentrates among aging workforces in Germany's Düsseldorf and Stuttgart corridors, constraining supplier expansion.
- Volatile resin compound pricing:PVC resin feedstock costs fluctuate with chlor-alkali chain economics and energy input volatility, compressing processor margins and deferring equipment upgrade cycles.
- EPA emissions enforcement:Clean Air Act thresholds for volatile organic compound releases compel enclosed venting and fume capture retrofits, adding capital burden to facility upgrades.
Strategic Opportunities
- Automotive interior trim precision demands:Tier-1 suppliers seeking tighter dimensional tolerance are adopting advanced extrusion systems integrating melt pump controls, opening premium equipment tiers.
- Retrofit and service infrastructure gaps:North American processors face limited domestic technical support for legacy line optimization, creating white space for aftermarket service specialization.
- IRA clean manufacturing incentives:United States domestic production credits for energy-efficient equipment deployment are redirecting capital toward modern extrusion line investments.
Industry Challenges
- Screw design calibration complexity:Optimizing L/D ratios between 24:1 and 36:1 for specific rigid versus foamed PVC formulations requires scarce polymer rheology expertise, extending commissioning timelines.
- Legacy control system integration:Melt pump automation and Industry 4.0 sensor arrays must interface with decades-old barrel-and-screw assemblies, creating interoperability friction and downtime risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Extrusion Equipment Market |
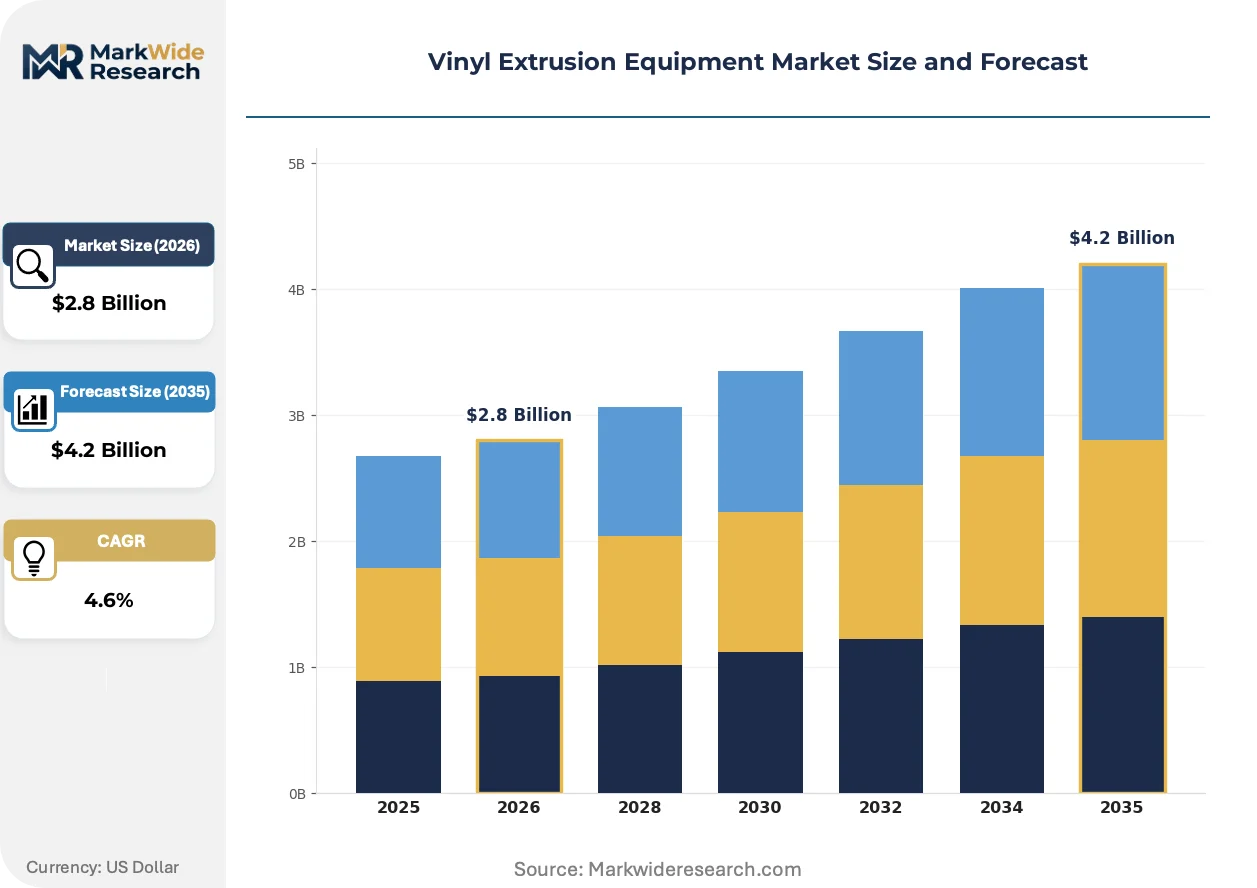
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Screw Extruders, Twin-Screw Extruders, Sheet Extruders, Profile Extruders End User: Construction, Automotive, Consumer Goods, Electronics Size: Small Scale, Medium Scale, Large Scale, Custom Size Technology: Standard Extrusion, Advanced Extrusion, Co-Extrusion, Melt Pump Extrusion |
| Companies Covered | Milacron, Leistritz, KraussMaffei, Reifenhäuser Group, Battenfeld-Cincinnati, Coperion, JWELL, Bandera, Davis-Standard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Extrusion Equipment Market Evolving Landscape
Digital twin simulation and predictive maintenance architectures are virtualizing equipment commissioning and uptime optimization, compressing the traditional engineering-services value chain into software-enabled offerings.
Digital twin platforms for extrusion line design are virtualizing screw geometry testing and thermal profile validation before physical prototyping. Automotive interior trim suppliers in the United States are adopting these tools fastest to reduce tooling iteration cycles. The technology is virtualizing traditional equipment builder engineering margins into recurring software licensing revenue streams.
EPA emissions standards under the Clean Air Act are tightening volatile organic compound release thresholds from PVC processing facilities. Equipment suppliers must now engineer enclosed venting and fume capture systems as standard configurations rather than optional add-ons. Construction sector buyers in the United States are prioritizing compliant system packages to preempt regulatory enforcement exposure.
After-sales service unbundling is fragmenting traditional equipment supply contracts into separate hardware, installation, and maintenance components. Mid-scale processors in emerging manufacturing zones are procuring extrusion lines through third-party technical service providers rather than direct OEM relationships. This pattern concentrates in regions where local engineering capacity outpaces direct supplier presence.
Vinyl Extrusion Equipment Market Segmentation
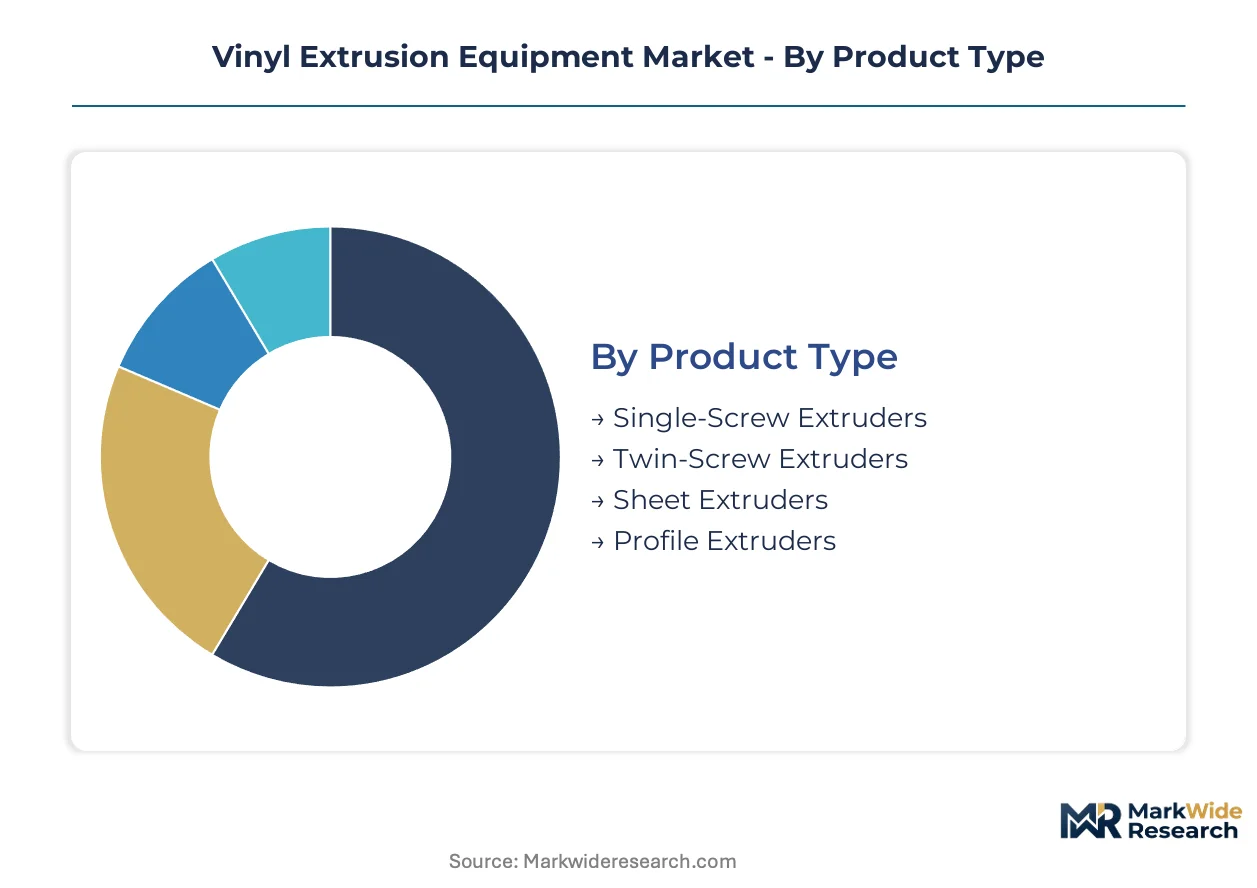
Equipment segmentation in vinyl extrusion reveals divergent service intensity and margin profiles across product architectures. After-sales engineering demands vary sharply between twin-screw systems requiring screw geometry recalibration and mature sheet extruder categories with predictable maintenance cycles.
Product Type:
After-sales service intensity peaks with twin-screw configurations due to screw element wear patterns and barrel lining replacement schedules.
- Twin-Screw Extruders:Intermeshing co-rotating screws deliver superior distributive and dispersive mixing for rigid PVC formulations with high filler loadings. Construction sector buyers in Germany's Düsseldorf engineering corridor specify these systems for window profile lines where output consistency determines downstream fabrication yields. EPA emissions compliance is forcing enclosed venting retrofits that extend commissioning timelines.
- Single-Screw Extruders:A single rotating screw within a heated barrel provides simpler plasticization for homogeneous PVC compounds with lower shear requirements. Consumer goods processors in emerging manufacturing zones favor these units for initial capacity deployment where technical staffing remains limited. REACH plasticizer restrictions are redirecting formulation compatibility specifications.
- Profile Extruders:Die-head engineering for continuous hollow or solid cross-sections serves siding and trim applications with calibrated cooling tank integration.
- Sheet Extruders:Flat die and roll stack configurations for thermoforming feedstock occupy mature replacement-driven demand territory with standardized maintenance protocols.
By volume, single-screw extruders lead. By growth pace, twin-screw systems are expanding most quickly.
End User:
Application-driven cost tiers separate construction sector envelope specifications from automotive interior precision requirements.
- Construction:Window profile and siding system manufacturers command the dominant equipment installed base. Residential and commercial building envelope expansion across Germany and the United States is pulling twin-screw capacity into greenfield plant investments. IRA clean manufacturing incentives are redirecting United States capital toward energy-efficient line deployments.
- Automotive:Interior trim suppliers demand advanced extrusion systems integrating melt pump controls for dimensional tolerance below 0.1 millimeters. Tier-1 processors in the United States are adopting digital twin simulation platforms to compress tooling iteration cycles. Co-extrusion technology captures expanding margin pools as multi-layer aesthetic surfaces displace painted alternatives.
- Consumer Goods:Limited FDA food-contact applications constrain equipment specifications to specific stabilizer compatibility profiles.
- Electronics:Wire jacketing and cable sheathing applications require specialized cross-head die configurations for conductor encapsulation.
Construction maintains volume leadership. Automotive is climbing the fastest on precision equipment premiums.
Size:
Scale-based procurement patterns concentrate aftermarket service specialization around medium-scale installations where technical support gaps persist.
- Large Scale:Integrated extrusion lines exceeding 500 kilograms per hour output dominate high-volume window profile and siding operations. Major construction material producers in Germany cluster capacity around Stuttgart engineering corridors. Asset-light leasing structures are compressing capital barriers for these deployments.
- Medium Scale:Modular extrusion systems between 150-500 kilograms per hour serve regional processors scaling capacity without full ownership burdens. North American aftermarket service infrastructure gaps create white space for third-party technical providers. Project finance structures are enabling faster capacity scaling across emerging manufacturing zones.
- Small Scale:Laboratory and pilot line configurations support formulation development and color matching workflows.
- Custom Size:Application-specific barrel lengths and L/D ratios address specialized medical tubing or oversized pipe requirements.
Large scale leads by installed value. Medium scale is gaining share fastest through leasing penetration.
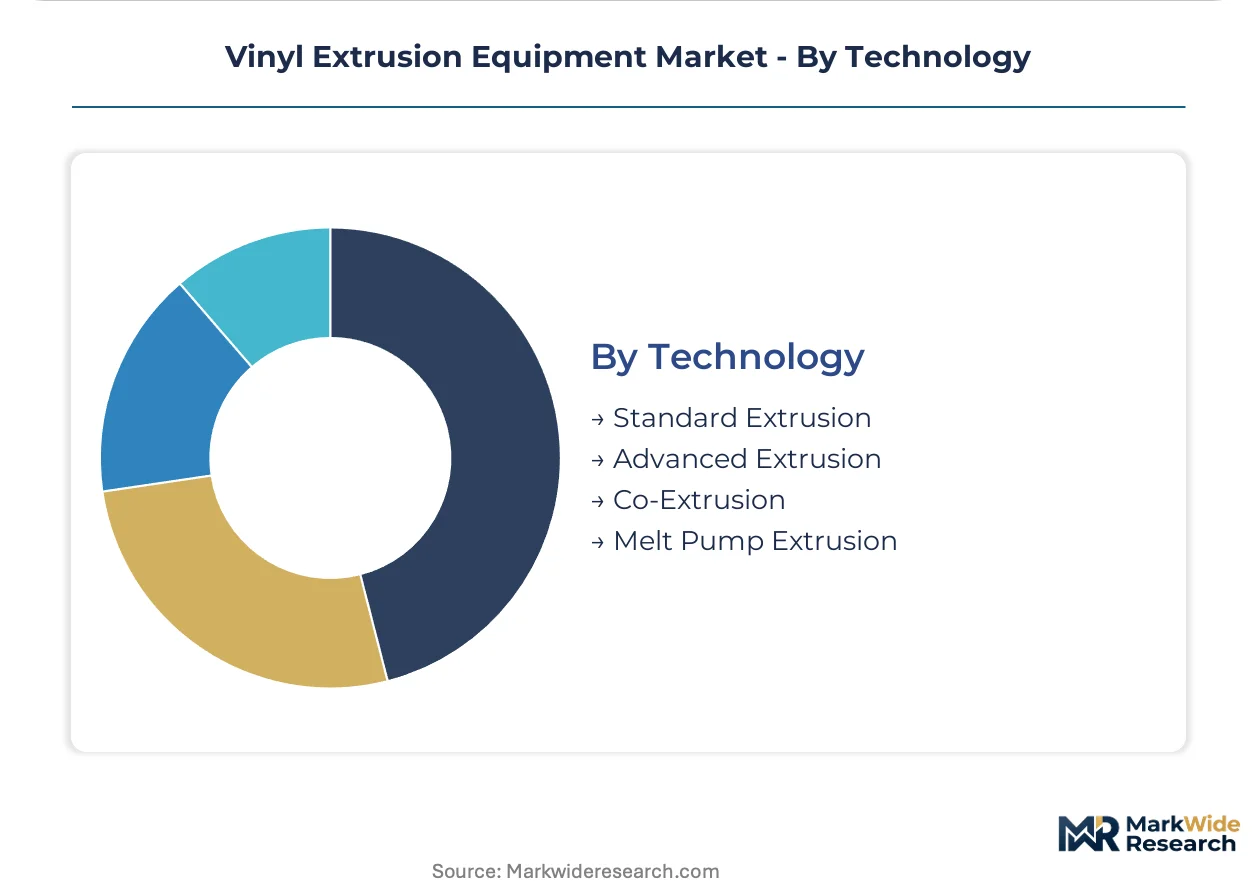
Technology:
Technology maturity curves separate standardized extrusion from premium tiers where melt pump integration commands service premiums.
- Co-Extrusion:Multi-layer die-head engineering enables barrier and aesthetic profile combinations that displace single-material alternatives. Construction sector buyers are prioritizing compliant system packages to preempt regulatory enforcement exposure across multiple jurisdictions. Die design complexity concentrates expertise among aging workforces in German engineering clusters.
- Melt Pump Extrusion:Positive displacement gear pumps between extruder and die stabilize output pressure for tight dimensional tolerance applications. Automotive interior trim suppliers in the United States are adopting these systems fastest to meet Tier-1 supplier quality agreements. Industry 4.0 sensor arrays must interface with legacy control architectures.
- Standard Extrusion:Conventional barrel-and-screw configurations without downstream pressure stabilization serve commodity profile and pipe applications.
- Advanced Extrusion:Integrated thermal profiling and automated gauge control systems target premium construction and automotive specifications.
Standard extrusion leads by unit volume. Co-extrusion shows the steepest expansion trajectory on multi-layer construction adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German engineering corridors where twin-screw system premiums command 15-20% over North American equivalents. Equipment buyers in emerging manufacturing zones face compressed margins and limited technical support infrastructure.
United States
Automotive interior trim suppliers in Michigan and Ohio are adopting melt pump extrusion systems for dimensional tolerances below 0.1 millimeters. IRA clean manufacturing incentives are redirecting capital toward energy-efficient line deployments. EPA emissions enforcement under the Clean Air Act is compelling enclosed venting retrofits across legacy PVC processing facilities in the Southeast.
Germany
Construction sector envelope expansion is pulling twin-screw capacity into greenfield investments around Düsseldorf and Stuttgart engineering corridors. REACH registration requirements and RoHS substance restrictions are redirecting equipment specifications toward calcium-zinc stabilizer compatibility. Machinery builders cluster along these corridors where aging workforces concentrate scarce screw geometry expertise.
China
Mid-scale processors in Yangtze River Delta manufacturing zones are scaling capacity through asset-light leasing structures rather than direct ownership. MIIT energy efficiency standards are tightening equipment specifications for domestic production credits. Zhejiang and Jiangsu provinces host expanding retrofit service providers filling technical support gaps for imported legacy lines.
India
Regional window profile manufacturers in Maharashtra and Gujarat are deploying modular extrusion systems between 150-500 kilograms per hour. BIS certification requirements for construction materials are elevating equipment cleanliness specifications. Ahmedabad and Pune industrial zones concentrate third-party technical service providers enabling faster capacity scaling without OEM relationships.
Japan
Precision automotive suppliers in Aichi Prefecture are integrating Industry 4.0 sensor arrays with legacy barrel-and-screw assemblies. METI carbon neutrality roadmaps are redirecting R&D investment toward energy-efficient thermal profiling systems. Nagoya engineering clusters specialize in melt pump calibration for Tier-1 supplier quality agreements.
Vinyl Extrusion Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying die heads, screws, and control modules. The vendor base organizes around three strategic archetypes: German engineering houses with premium twin-screw positioning, North American retrofit and service infrastructure players, and Asian scale manufacturers with modular system offerings. Competitive dynamics center on geographic expansion through third-party technical partnerships and technology licensing for co-extrusion die-head engineering.
Among German-based engineering specialists, KraussMaffei, Reifenhäuser Group, and Battenfeld-Cincinnati occupy positions representing the premium system tier where screw geometry optimization and multi-layer die-head engineering command service premiums. Davis-Standard anchors North American supply through extensive retrofit infrastructure, while Leistritz exemplifies the specialized component archetype with upstream positioning in intermeshing screw element technology. Coperion and Milacron sit within the diversified industrial equipment tier with cross-material extrusion capabilities extending beyond vinyl formulations.
| Leading Market Players |
|---|
| Milacron |
| Leistritz |
| KraussMaffei |
| Reifenhäuser Group |
| Battenfeld-Cincinnati |
| Coperion |
| JWELL |
| Bandera |
| Davis-Standard |
| Others |
Value Network & Pricing Analysis
German engineering corridors around Düsseldorf and Stuttgart concentrate twin-screw system production, anchoring premium pricing tiers 15-20% above North American equivalents while compressing margin pools for mid-scale processors lacking direct OEM relationships. REACH compliance mandates and EPA emissions thresholds are forcing configured-to-order engineering that separates equipment buyers into distinct price bands based on regulatory exposure and technical support requirements.
Pricing Analysis
Configured-to-order engineering commands 25-40% premiums over standard extrusion configurations, with die-head complexity and screw geometry customization as the primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels stratifies buyers by after-sales bundling intensity and regulatory compliance scope. Cost compression in standard sheet extruder categories is intensifying because replacement-driven demand limits differentiation leverage. Mid-scale processors in emerging manufacturing zones exhibit highest price sensitivity, while automotive Tier-1 suppliers seeking melt pump precision demonstrate lowest sensitivity.
Supply Chain Analysis
Export-control regimes on precision screw element manufacturing limit technology flows from Germany to certain end-use destinations, constraining supply elasticity. Equipment production concentrates in Germany, the United States, and China, with barrel-and-screw assemblies drawing from specialized steel forging operations in Austria and Japan. Supply chain risk centers on single-source vulnerability for intermeshing screw element geometries where aging workforces concentrate expertise. Distribution runs through direct OEM channels for premium systems and third-party technical service providers for modular mid-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin platforms are transforming equipment commissioning from physical engineering services into software-enabled recurring revenue, creating platform-economics inflection points where interoperability with legacy control architectures determines competitive survival.
For Market Incumbents: Build aftermarket service moats through predictive maintenance architectures and captive spare parts logistics. Deepen backward integration into screw element manufacturing to secure supply continuity against forging capacity constraints. Invest in calcium-zinc stabilizer compatibility R&D ahead of REACH enforcement timelines to preempt replacement demand capture by competitors. For New Entrants and Emerging Players: Pursue aftermarket service specialization in North American retrofit infrastructure gaps where legacy line optimization demand exceeds domestic technical support capacity. Target medium-scale modular system deployment through asset-light leasing structures in emerging manufacturing zones. Lead with third-party technical partnerships rather than direct OEM competition to bypass German engineering corridor concentration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision component specialists holding captive screw geometry IP and aging founder-engineer dependencies. Long-term viability hinges on digital twin platform adoption rates and successful workforce transition programs. Watch for inflection in automotive interior trim precision requirements migrating from United States Tier-1 suppliers to Asian electric vehicle platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Development | Virtualizes screw geometry testing for automotive interior trim suppliers compressing tooling iteration cycles. |
| Backward Integration into Screw Elements | Captures intermeshing geometry IP and reduces forging supply vulnerability for twin-screw configurations. |
| Third-Party Technical Partnership Expansion | Enables geographic reach into emerging manufacturing zones without direct engineering corridor presence. |
| Calcium-Zinc Stabilizer Compatibility Investment | Aligns equipment specifications with REACH mandates redirecting replacement demand across installed bases. |
| Asset-Light Leasing Structure Deployment | Compresses capital barriers for mid-scale processors scaling capacity without traditional ownership burdens. |
Research Methodology
A spread of perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and polymer rheology specialists converged on the working assumptions governing screw geometry optimization and melt pump calibration requirements. Primary interviews with equipment operators in Germany's Düsseldorf corridor, North American retrofit specialists, and emerging zone leasing providers combined with secondary validation from customs trade data, machinery builder SEC filings, and ECHA REACH registration databases. Bottom-up equipment unit economics triangulated against top-down construction sector envelope demand projections.
Demand-supply balance modeling across the projection horizon integrated twin-screw versus single-screw technology splits, co-extrusion adoption curves by end-use, and regional regulatory compliance tiering. Segmentation dimensions spanned product architecture, end-user industry precision requirements, scale-based procurement patterns, and technology maturity curves. CAGRs derived from equipment replacement cycle analysis and greenfield capacity announcement tracking, with specific inputs from automotive interior trim tolerance specifications and IRA clean manufacturing incentive qualification thresholds.
Sensitivities concentrate around PVC resin feedstock volatility, REACH enforcement timeline acceleration, and EPA emissions threshold revisions. Forecasts reflect documented assumptions on screw geometry expertise workforce transition rates and digital twin platform adoption curves. Material shifts in chlor-alkali chain economics or multi-jurisdictional regulatory divergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Plastic Molds Market
Industrial Materials
Elastomeric Couplings Market
Industrial Materials
Asia-Pacific Industrial Flooring Market
Industrial Materials
Bamboo Products Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
Anode Carbon Block Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
High Shear Mixer Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
Extruders Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Soil Stabilization Materials Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
High Modulus Polyethylene Rope Market