
 United States Ceramic Tiles Market | 2026-2036
United States Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
United States Ceramic Tiles Market Analytics
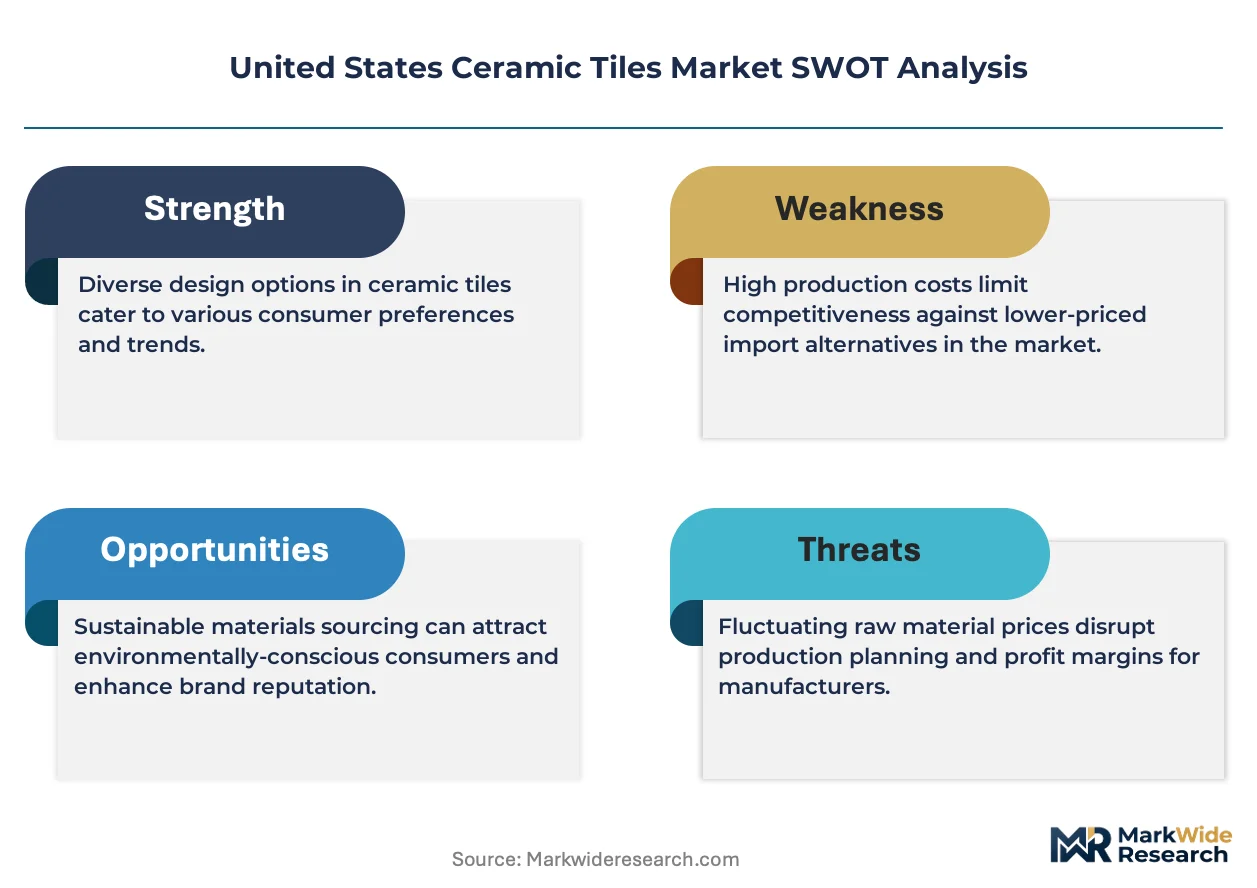
Large-format tile bundling with pre-matched installation systems is repositioning buyer choice toward turnkey solutions rather than standalone product selection. Mohawk Industries leverages captive distribution through its Dal-Tile Corporation subsidiary to control channel economics across the Southwest and Southeast. Florida Tile Inc. anchors its competitiveness through specialized domestic manufacturing of through-body porcelain positioned for high-traffic commercial specifications. Shaw Industries Group competes via vertical integration from raw material sourcing through retail flooring showrooms, sustaining margin capture that pure wholesale brands cannot replicate.
United States ceramic tiles are thin, flat slabs formed from clay, silica, and fluxing agents, then fired at temperatures exceeding 1,000°C to achieve specified water absorption rates below 0.5% for porcelain grades and 3-6% for standard ceramic; these materials serve primarily as surfacing solutions where durability, moisture resistance, and aesthetic flexibility matter for built environments. Porcelain tiles now lead volume growth within product type segmentation due to density and frost resistance enabling exterior applications previously dominated by natural stone. Flooring commands the largest installed base among applications, though wall cladding and backsplashes are expanding faster as open-concept residential design and hospitality renovation cycles elevate vertical surface specification. Specialty stores and wholesale distributors remain the dominant channel pair, with online retail growing fastest among distribution channels as visualizer tools and sample programs reduce purchase friction for residential buyers.
EPA silica dust regulations and OSHA permissible exposure limits are reshaping fabrication workflows, mandating wet-cutting protocols and engineered stone alternatives that redirect specification toward pre-cut ceramic systems. FTC Green Guides and California Proposition 65 labeling requirements further constrain marketing claims and chemical disclosure, raising compliance costs for imported product lines. Stakeholders must monitor evolving federal infrastructure spending allocation and state-level building code harmonization to anticipate which specification tiers will capture public project volume.
Market Dynamics
Large-format porcelain panels are compressing installation timelines and labor costs, fundamentally restructuring how specifiers evaluate surfacing materials against natural stone alternatives in commercial and residential builds.
Growth Catalysts
- EPA Silica Dust Regulations:OSHA permissible exposure limits are mandating wet-cutting protocols that accelerate specification of pre-cut ceramic systems, reducing on-site fabrication demand.
- Sun Belt Housing Concentration:Florida, Texas, and California housing starts outpace national averages, concentrating demand for moisture-resistant porcelain in new construction and renovation cycles.
- Digital Inkjet Decoration:Advanced printing technology enables realistic stone and wood grain replication at lower cost, expanding aesthetic range without natural material price volatility.
Market Restraints
- Natural Gas Input Volatility:Kiln firing consumes substantial fossil fuel energy; price swings in Henry Hub gas benchmarks compress manufacturing margins unpredictably.
- Import Concentration Risk:Domestic production capacity remains limited relative to consumption volume, leaving supply chains exposed to trans-Pacific shipping disruptions and tariff adjustments.
- Weight and Handling Constraints:Large-format panels exceeding 5 feet in dimension require specialized equipment and skilled labor, restricting adoption in renovation projects with access limitations.
Strategic Opportunities
- Rural and Secondary Metro Penetration:Distribution networks historically concentrated in coastal corridors now expand into interior states where porcelain specification rates lag Sun Belt levels.
- Exterior Cladding Applications:Frost resistance and thermal shock durability enable porcelain facade systems to capture share from aluminum composite and fiber cement in commercial envelopes.
- Infrastructure Spending Allocation:Federal transit and public building appropriations favor domestically manufactured materials, creating specification preference for US-sourced tile in public projects.
Industry Challenges
- Certified Installer Scarcity:Thin-set mortar and large-format handling techniques require specialized training; the gap between certified technicians and project volume creates installation bottlenecks.
- Legacy Inventory Systems:Distributors maintaining extensive SKU libraries for pattern matching face working capital pressure as trend cycles compress and obsolescence risk rises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Ceramic Tiles Market |
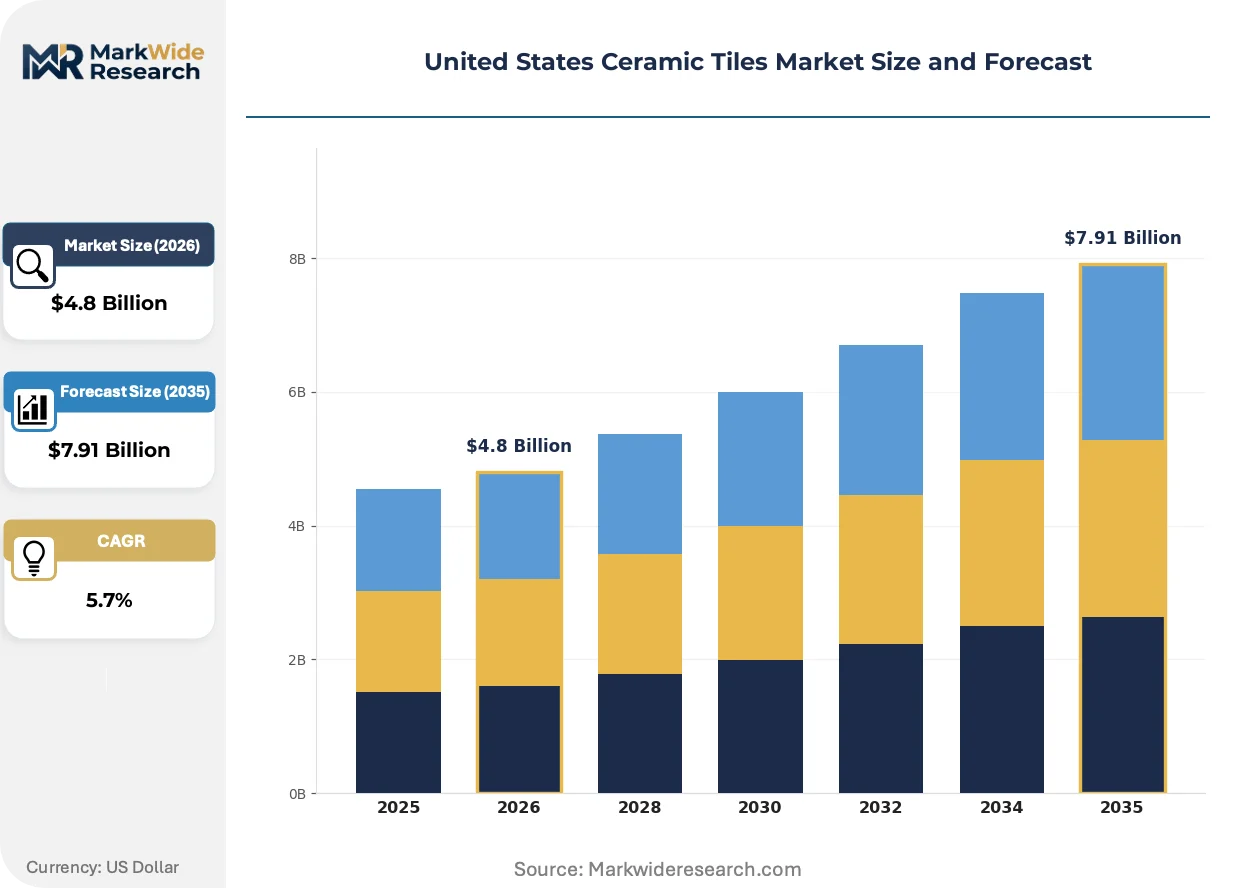
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Tiles, Unglazed Tiles, Porcelain Tiles, Stoneware Tiles Application: Flooring, Wall Cladding, Countertops, Backsplashes Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Specialty Stores End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Florida Tile Inc., Shaw Industries Group, Mohawk Industries, Arizona Tile, Marazzi, Dal-Tile Corporation, Emser Tile, Bedrosians Tile & Stone, Crossville Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Ceramic Tiles Market Evolving Landscape
Material science advances and regulatory compliance pressures are converging to transform specification workflows, with digital tools and pre-fabrication displacing traditional site-based fabrication methods.
Thin large-format porcelain slabs are rewriting installation economics in commercial hospitality and healthcare verticals. Hotel renovation cycles now specify 6mm gauged panels for wall cladding and wet-area surfacing, cutting material weight by 60% versus traditional thickness. General contractors report 40% faster envelope completion timelines, compressing project schedules and reducing skilled labor hour requirements.
OSHA silica dust enforcement is reshaping fabrication workflows across the Sun Belt and industrial Midwest. Wet-cutting mandates and engineered stone restrictions in California and other jurisdictions are redirecting specification toward pre-cut ceramic systems with factory-finished edges. Distributors are consolidating fabrication capacity in centralized facilities to achieve compliance scale that individual contractors cannot replicate.
Visualizer technology adoption is accelerating among residential buyers in suburban markets. Online platforms with augmented reality room rendering and physical sample programs are reducing showroom visit frequency, shifting channel economics toward direct fulfillment models. Specialty retailers in Texas and Florida report 25% of specification decisions now originate from digital exploration before physical contact.
United States Ceramic Tiles Market Segmentation
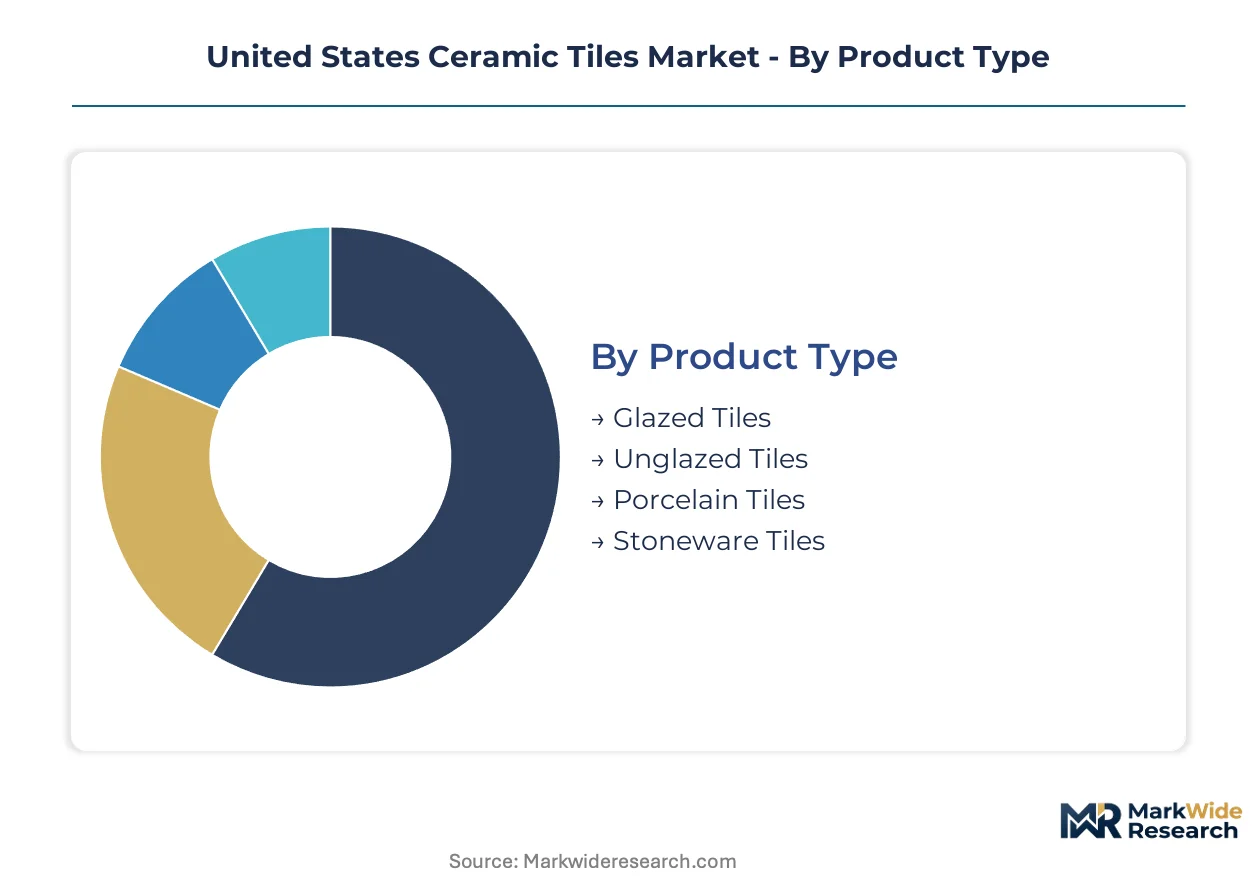
Segmentation in the United States ceramic tiles market reveals how specification workflows, channel economics, and end-use requirements fragment demand across distinct technical and commercial categories. Understanding these divisions exposes where margin pools concentrate and which product configurations align with regulatory and installation constraints.
Product Type:
Supply concentration in kiln-fired manufacturing creates divergent cost structures across water absorption grades and surface finishes, with porcelain commanding premium positioning through density specifications.
- Porcelain Tiles:Fired above 1,200°C to achieve sub-0.5% water absorption, these dense slabs withstand freeze-thaw cycles and heavy commercial traffic. Sun Belt states including Florida and Texas specify porcelain for exterior facades and high-moisture interiors where frost resistance justifies material cost premiums.
- Glazed Tiles:A glass-based coating fused to clay bodies during firing creates stain-resistant, decorative surfaces with unlimited color range. Residential renovation in California and Arizona drives specification for kitchen backsplashes and bathroom walls where aesthetic flexibility outweighs through-body durability requirements.
- Unglazed Tiles:Natural clay surfaces without glass coating offer slip resistance for commercial and industrial flooring where traction safety codes apply.
- Stoneware Tiles:Intermediate density between standard ceramic and porcelain serves budget-conscious commercial projects requiring moderate durability without full porcelain specifications.
Porcelain tiles absorb the bulk of installed capacity; glazed tiles are expanding most quickly as digital inkjet decoration broadens aesthetic replication capabilities.
Application:
Installation labor economics and surface area exposure determine how builders allocate material grades across horizontal and vertical planes in residential and commercial structures.
- Flooring:Horizontal surfaces bear mechanical wear, moisture exposure, and cleaning chemical contact, driving specification toward through-body porcelain and high-density stoneware. Multi-family housing starts in Texas and Florida concentrate volume for entry-level and mid-market residential flooring where durability requirements intersect with cost constraints.
- Wall Cladding:Vertical surfaces in hospitality renovation and luxury residential construction specify large-format gauged panels for seamless aesthetic coverage. Hotel renovation cycles in California and Nevada compress installation timelines using thin 6mm panels that reduce weight handling and substrate preparation costs.
- Countertops:Heat and scratch resistance requirements push specification toward porcelain slabs with engineered stone alternatives facing silica dust regulatory restrictions.
- Backsplashes:Small surface areas with high visual impact favor glazed ceramic and decorative mosaic formats where pattern variety drives selection.
Flooring commands the dominant share of material volume; wall cladding is climbing the fastest as open-concept design elevates vertical surface specification in residential and hospitality segments.
Distribution Channel:
Customer type and project scale fragment procurement patterns across direct relationships, digital platforms, and physical retail networks with divergent service intensity.
- Specialty Stores:Showroom-based retailers with trained staff provide color matching, sample programs, and installation contractor referrals for residential renovation buyers. Florida and California markets sustain dense specialty store networks where visual material selection remains a high-touch purchase process.
- Wholesale Distributors:Inventory-heavy intermediaries serve commercial contractors and regional retailers with bulk logistics and credit terms. Texas distribution hubs supply Sun Belt construction markets with consolidated procurement efficiency that individual manufacturers cannot replicate.
- Direct Sales:Large-volume commercial and institutional buyers bypass intermediaries to negotiate project-specific pricing and just-in-time delivery schedules.
- Online Retail:Digital platforms with augmented reality visualization and sample fulfillment capture growing residential specification share in suburban markets where showroom access is limited.
Wholesale distributors and specialty stores together anchor channel volume; online retail is gaining share fastest as digital tools reduce purchase friction for geographically dispersed residential buyers.
End User:
Project scale, specification authority, and compliance requirements segment demand across building types with divergent procurement processes and performance standards.
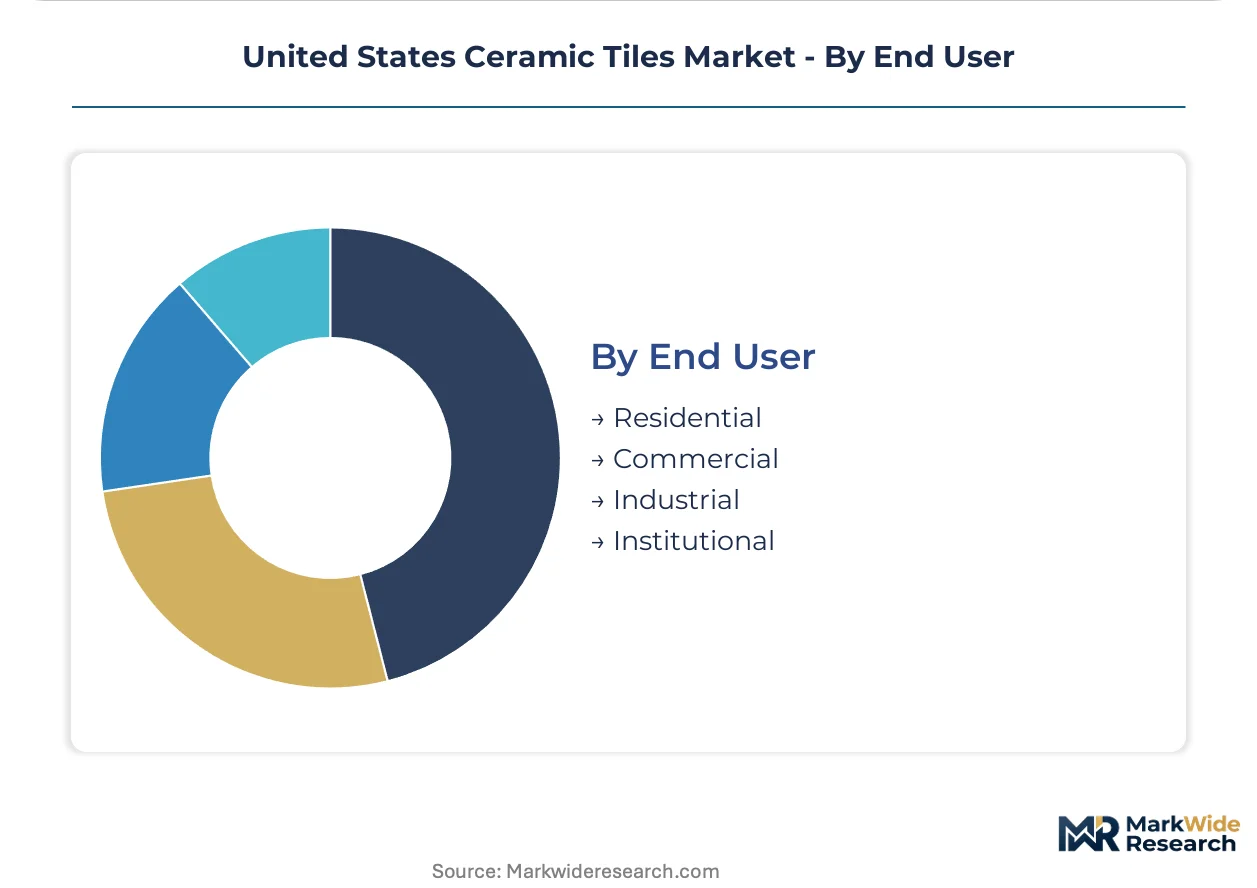
- Residential:Single-family and multi-family housing construction and renovation generates volume through new build specification and replacement cycles. Sun Belt metro areas including Houston, Phoenix, and Miami concentrate residential demand where housing starts outpace national averages and moisture-resistant materials address climate exposure.
- Commercial:Office, retail, and hospitality construction specifies high-traffic porcelain and large-format panels for durability and accelerated installation timelines. California hospitality renovation and Texas office construction drive commercial specification with compressed project schedules favoring pre-fabricated systems.
- Industrial:Manufacturing and warehouse facilities prioritize slip-resistant unglazed surfaces and chemical-resistant epoxy-grouted installations for safety compliance.
- Institutional:Schools, healthcare, and government buildings face domestic content preferences and extended warranty requirements that favor established suppliers with certification documentation.
Residential end users absorb the bulk of volume; commercial projects are expanding most quickly as large-format porcelain panels compress installation economics in hospitality and office renovation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Sun Belt metros accelerate ceramic tile demand concentration through tax-advantaged development incentives. Federal infrastructure spending and state-level housing initiatives further redistribute specification volume across domestic manufacturing clusters.
California
Los Angeles and San Francisco hospitality renovation cycles specify large-format porcelain panels for accelerated project timelines. Cal/OSHA silica dust enforcement mandates wet-cutting protocols that redirect specification toward pre-fabricated systems. San Diego and Orange County distribution hubs consolidate fabrication capacity to achieve compliance scale.
Texas
Houston and Dallas-Fort Worth housing starts outpace national averages, concentrating demand for moisture-resistant porcelain in multi-family construction. Texas Commission on Environmental Quality air quality standards influence manufacturing site selection. Austin and San Antonio specialty retailer networks expand digital visualization tools for suburban specification.
Florida
Miami and Tampa commercial development drives exterior facade porcelain specification for hurricane-resistant envelopes. Florida Building Code wind load requirements elevate technical performance standards. Orlando distribution corridors serve southeastern renovation markets with consolidated logistics.
New York Metro
Five Boroughs institutional renovation specifies domestically manufactured tile for public project domestic content preferences. New York State Department of Labor prevailing wage requirements influence contractor procurement patterns. Westchester and Long Island residential markets sustain premium specialty showroom networks.
Southeast
Atlanta and Charlotte housing expansion absorbs porcelain volume for entry-level residential flooring. Georgia and North Carolina state tax credits for manufacturing investment attract distribution center location. Nashville and Birmingham secondary metros lag Sun Belt specification rates, creating penetration headroom.
United States Ceramic Tiles Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base concentrates around captive distribution networks and specialized fabrication capabilities. Three archetypes dominate: vertically integrated flooring conglomerates with captive retail channels, regional distributors with centralized fabrication compliance infrastructure, and domestic manufacturing specialists with through-body porcelain capabilities. Competitive moves center on distribution network consolidation and pre-fabricated system capacity expansion.
Among Georgia-based diversified manufacturers, Mohawk Industries occupies a position exemplifying captive channel control through subsidiary distribution networks. Dal-Tile Corporation represents the vertically integrated archetype with southwestern and southeastern logistics dominance. Florida Tile Inc. anchors domestic manufacturing specialization for high-traffic commercial specifications.
| Leading Market Players |
|---|
| Florida Tile Inc. |
| Shaw Industries Group |
| Mohawk Industries |
| Arizona Tile |
| Marazzi |
| Dal-Tile Corporation |
| Emser Tile |
| Bedrosians Tile & Stone |
| Crossville Inc. |
| Others |
Value Network & Pricing Analysis
Large-format porcelain panel production methods are compressing fabrication economics while concentrating supply among distributors with centralized wet-cutting facilities. This manufacturing transition simultaneously elevates compliance costs for fragmented contractors and transfers margin capture toward scaled fabricators with OSHA-compliant infrastructure.
Pricing Analysis
Short lead-time premiums dominate pricing structures, with project-based contractors paying markups for expedited fabrication while spot inventory from regional distributors trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates certified pre-cut systems from field-fabricated alternatives and basic ceramic grades. Cost compression in economy-tier glazed ceramic is intensifying because import concentration exposes distributors to trans-Pacific shipping volatility. Multi-family housing developers in Texas and Florida exhibit highest price sensitivity, while hospitality renovation specifiers in California prioritize installation speed over unit cost.
Supply Chain Analysis
Regional distribution centers in Texas, Florida, and California anchor hub-and-spoke patterns that consolidate inventory and fabrication capacity within OSHA-compliant facilities. Manufacturing draws from Italian and Spanish kiln technology, Chinese digital inkjet printing equipment, and domestic clay deposits in Georgia and Tennessee. Single-source vulnerability concentrates in trans-Pacific shipping lanes connecting Asian component suppliers to West Coast ports. Distribution runs through wholesale distributors with bulk logistics networks that individual manufacturers cannot replicate at comparable cost.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States ceramic tiles market is becoming a vertical-integration race where captive fabrication capacity and controlled distribution networks determine margin capture. Players are pursuing downstream control over certified installer networks as the decisive competitive lever.
For Market Incumbents: Anticipate silica dust enforcement expansion by consolidating wet-cutting capacity in centralized facilities before smaller competitors achieve compliance scale. Deepen backward integration into domestic clay sourcing to insulate margins from import tariff volatility. Defend against pure-play digital retailers by embedding visualization tools within captive specialty store networks.
For New Entrants and Emerging Players: Secondary metro contractors in Nashville, Birmingham, and Charlotte represent an underserved buyer archetype with limited access to large-format panel fabrication. Capture share through mobile fabrication units that bring OSHA-compliant wet-cutting to renovation sites with access constraints. Partner with regional distributors for logistics coverage rather than building independent warehouse networks.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by flooring conglomerates seeking geographic fabrication coverage. Long-term viability hinges on domestic manufacturing presence that satisfies federal infrastructure domestic content preferences. Monitor Cal/OSHA enforcement expansion into neighboring states as the inflection signal for pre-fabricated system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Centralized Fabrication Capacity Expansion | OSHA-compliant wet-cutting facilities capture margin from fragmented field fabrication in Sun Belt states. |
| Digital Visualization Platform Integration | Augmented reality tools reduce showroom dependency for suburban residential buyers in Texas and Florida. |
| Domestic Clay Supply Agreement | Georgia and Tennessee mining partnerships insulate production from trans-Pacific shipping disruption. |
| Certified Installer Network Development | Training programs address technician scarcity that bottlenecks large-format panel adoption. |
| Exterior Cladding Product Line Extension | Frost-resistant porcelain facade systems capture share from aluminum composite in commercial envelopes. |
Research Methodology
Independent corroboration across distributor procurement managers, commercial general contractors, and specialty retailer owners underwrites the qualitative findings in this study. Primary interviews with ceramic fabrication technicians, EPA compliance officers, and hospitality renovation specifiers combined with secondary validation from OSHA enforcement records, FTC Green Guide filings, and customs import data. Bottom-up volume estimates from state-level building permit databases triangulate against top-down consumption models derived from distributor revenue disclosures.
Comparable-period anchoring to historical housing start cycles and hospitality renovation timelines established the forecast window boundaries. Segmentation modeling spans product type, application surface, distribution channel, and end-use building category across the projection horizon. CAGRs derive from regression analysis linking ceramic tile consumption to construction spending indices and regulatory compliance cost trajectories. Key inputs include natural gas price volatility for kiln economics and silica dust enforcement intensity by state jurisdiction.
Revisions become necessary when federal infrastructure spending allocation shifts, state building code harmonization accelerates, or trans-Pacific shipping rates experience sustained disruption. Forecasts reflect documented assumptions regarding Sun Belt housing concentration and OSHA enforcement expansion timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Lining Market
Ceramics
India Kaolin Market
Ceramics
Calcined Kaolin Market
Ceramics
Southeast Asia Melamine Market
Ceramics
Thermal Spray Powder Market
Ceramics
Activated Alumina Market
Ceramics
Alumina Slurry Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
Thailand Ceramic Tiles Market
Ceramics
Europe Activated Alumina Market
Ceramics
Malaysia Ceramic Tiles Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Boiler Refractory Material Market
Ceramics
Ceramic Solid End Mills Market
Ceramics
Global Ceramic Balls Market
Ceramics
Traditional Ceramic Market