
 Petrochemical Fasteners Market | 2026-2036
Petrochemical Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Petrochemical Fasteners Market Analytics
Downstream chemical processors is reorganizing procurement priorities toward specialty alloy fasteners that withstand sour gas exposure. Hilti Group leverages its engineered anchoring portfolio to dominate high-load refinery applications. Bumax Specialty Stainless Fasteners anchors its position through super-duplex grades that resist chloride stress corrosion. PCC Fasteners competes on forged large-diameter bolting for pressure vessel flanges.
Petrochemical fasteners are threaded mechanical devices manufactured to ASTM A193, A194, and NACE MR0175 specifications, typically from austenitic stainless or nickel-based alloys, designed to maintain clamping force under cyclic thermal and chemical stress in hydrocarbon processing equipment. Stainless steel and alloy materials command premium positioning due to sulfuric acid resistance requirements in fluid catalytic cracking units. Screws and bolts represent the highest-volume product category, though nuts and washers generate disproportionate margin contributions through captive aftermarket replacement cycles. Oil & gas end use remains the dominant demand pool, while automotive and construction applications are expanding for chemical-resistant fastening in fuel infrastructure and industrial building envelopes.
EPA New Source Performance Standards and MEE atmospheric emission controls are tightening fastener specification thresholds for volatile organic compound containment. ASTM, ISO 898-1, and NACE standards collectively govern material selection, mechanical property verification, and hydrogen embrittlement screening for sour service qualification. Stakeholders must monitor regulatory divergence between US and Chinese emissions protocols when configuring regional supply chain qualification programs.
Market Dynamics
Refinery expansion cycles across Saudi Arabia and the US Gulf Coast are compressing fastener qualification timelines, forcing suppliers to pre-certify super-duplex grades under NACE MR0175 before project award. This front-loaded compliance burden is restructuring competitive positioning toward metallurgical laboratories with in-house hydrogen embrittlement testing.
Growth Catalysts
- EPA New Source Performance Standards:Fugitive emissions mandates for volatile organic compound containment are mandating coated alloy fasteners in fluid catalytic cracking units across Texas and Louisiana refineries.
- Sour gas processing expansion:Hydrogen sulfide-rich feedstock handling in Middle Eastern complexes is accelerating specification of nickel-based alloys for chloride stress corrosion resistance.
- Modular construction methods:Prefabricated pressure vessel skids are concentrating procurement of ASTM A193 bolting into single-source engineered packages.
Market Restraints
- Nickel price volatility:Super-austenitic and nickel-based alloy feedstock costs fluctuate with London Metal Exchange pricing, compressing margin predictability for specialty fastener forgers.
- Supply concentration in European forging:Large-diameter pressure vessel bolting depends on a limited set of German and Italian forging houses with NORSOK qualification.
- Substitution by welded joints:Advanced narrow-gap welding in pipeline construction is displacing mechanical fastening in certain high-pressure hydrocarbon transport applications.
Strategic Opportunities
- India's petrochemical corridor:Dahej and Hazira industrial zones lack qualified domestic suppliers for NACE-compliant sour service fasteners, creating import substitution potential.
- Carbon capture retrofit installations:Amine-based CO2 absorption units require fasteners resistant to alkaline stress corrosion cracking, opening specification windows for duplex stainless grades.
- Digital twin integration:Embedding RFID tags in high-criticality bolting enables predictive maintenance contracts and recurring aftermarket revenue streams.
Industry Challenges
- Metallurgical expertise scarcity:Qualified materials engineers capable of interpreting NACE MR0175/ISO 15156 hardness limits in heat-affected zones remain concentrated at a handful of specialized laboratories.
- Extended certification timelines:Sour service qualification testing under simulated hydrogen sulfide exposure adds six to nine months to new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petrochemical Fasteners Market |
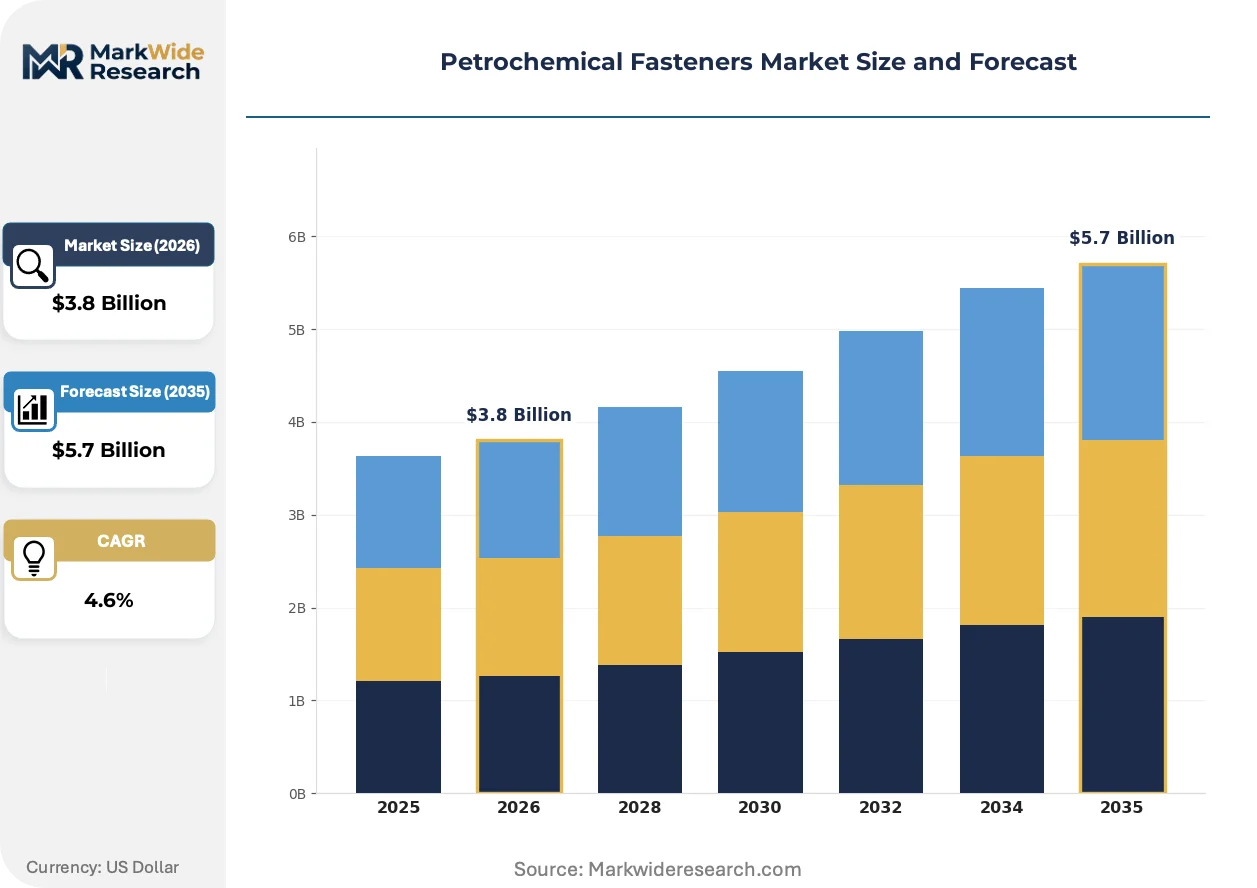
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screws, Bolts, Nuts, Washers Material: Stainless Steel, Carbon Steel, Alloy, Plastic End Use: Automotive, Construction, Shipbuilding, Oil & Gas Coating Type: Zinc Plated, Galvanized, Anodized, Coated |
| Companies Covered | Hilti Group, LISI Group, PCC Fasteners, Nord-Lock Group, Bollhoff Group, Stanley Black & Decker, Acument Global Technologies, Bumax Specialty Stainless Fasteners, Fastenal Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petrochemical Fasteners Market Evolving Landscape
Additive manufacturing of nickel superalloy fastener geometries is compressing lead times for prototype validation in custom flange configurations. Digital thread technologies and embedded sensors are converging with traditional mechanical fastening to create intelligent asset monitoring systems.
Super-duplex stainless steel grades with 25% chromium content are miniaturizing the wall thickness requirements for pressure retaining bolting in subsea manifolds. Offshore engineering contractors in Norway and Brazil are specifying these materials for compact Christmas tree assemblies. The resulting component weight reduction is enabling deeper water deployment without sacrificing clamping force integrity under cyclic fatigue.
MEE atmospheric emission controls in China are mandating low-leakage packing and gasket systems that impose tighter surface finish specifications on mating fastener threads. Domestic refineries in Shandong and Zhejiang provinces are upgrading procurement standards to match EPA-equivalent containment protocols. Fastener distributors with dual US-China certification capabilities are capturing specification influence in this transition.
Integrated supply contracts are consolidating fastener procurement with valve and flange packages under single-source engineering-procurement-construction agreements. Major contractors in Saudi Arabia's Jubail Industrial City are eliminating discrete fastener purchasing in favor of lump-sum turnkey material supply. This bundling is compressing standalone fastener distributor margins while rewarding metallurgical laboratories with full traceability documentation capabilities.
Petrochemical Fasteners Market Segmentation
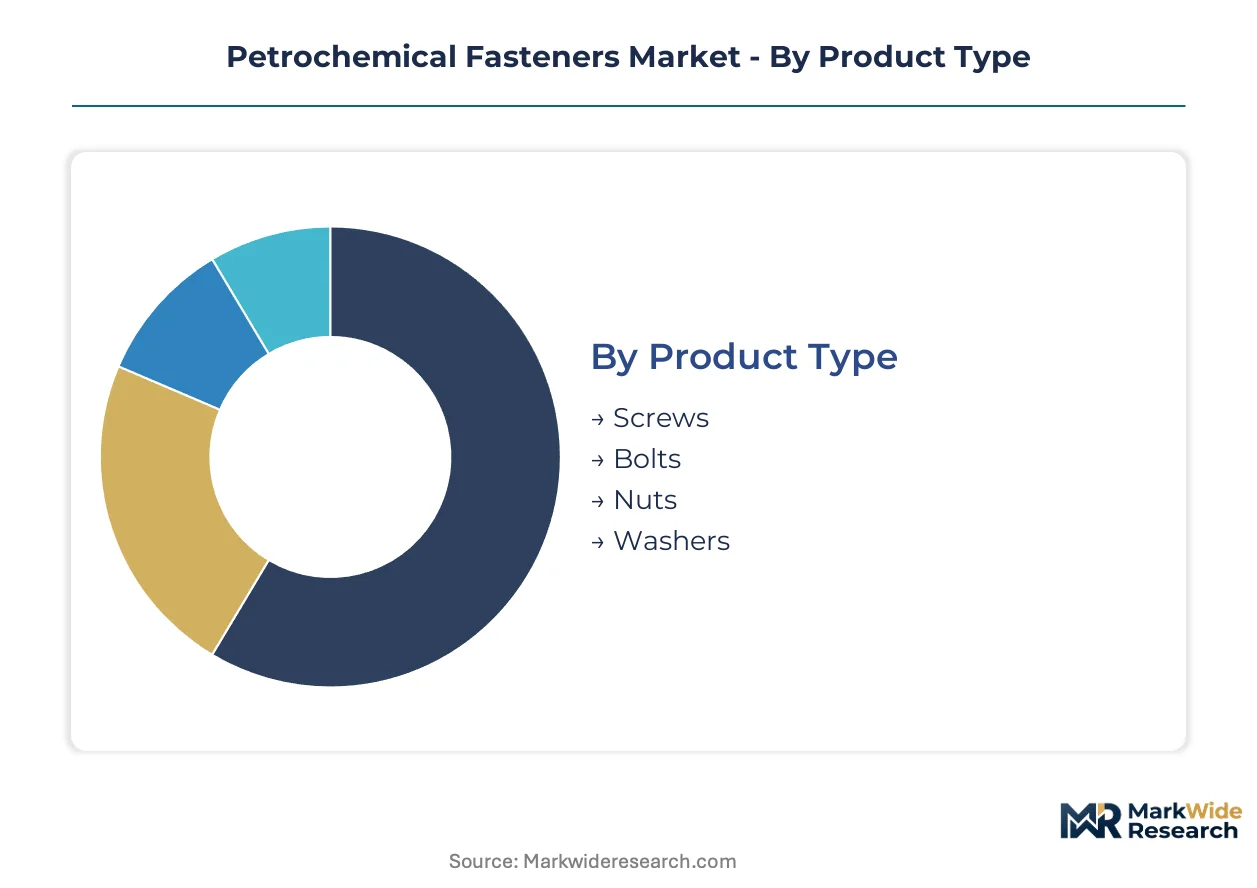
Fastener specification in petrochemical environments varies sharply by mechanical load, chemical exposure, and thermal cycling demands. Procurement channels diverge significantly across product categories, with engineered bolting flowing through specialized distributors while standard hardware moves through industrial supply houses.
Product Type:
Screws and bolts dominate specification volumes in refinery construction, while nuts and washers concentrate margin capture through aftermarket replacement cycles.
- Screws:Threaded fasteners manufactured to ASTM A193 specifications with coarse threads for high-temperature service. Demand clusters in fluid catalytic cracking unit maintenance across Texas and Louisiana refineries facing EPA fugitive emissions enforcement.
- Bolts:Heavy hex head configurations forged from austenitic stainless or nickel-based alloys, designed for pressure vessel flange clamping under cyclic thermal stress. Saudi Arabia's Jubail Industrial City expansion projects are compressing qualification timelines for super-duplex grades.
- Nuts:Heavy hex nuts per ASTM A194, often paired with stud bolts in sour service applications. Captive aftermarket revenue streams emerge from scheduled turnaround cycles.
- Washers:Hardened steel or alloy flat washers distributing clamping load across flange faces. Specification concentrates in modular pressure vessel skids.
Bolts dominate installed base tonnage. Screws are where specification expansion concentrates for emissions-compliant retrofits.
Material:
Material selection directly determines channel access, with NACE-qualified alloys restricted to specialized metallurgical laboratories and standard carbon steel available through broad industrial distribution.
- Stainless Steel:Austenitic grades 304 and 316 provide sulfuric acid resistance in fluid catalytic cracking units. Premium positioning reflects ASTM A193 compliance costs and chloride stress corrosion screening requirements.
- Alloy:Nickel-based alloys and super-duplex stainless grades with 25% chromium content withstand hydrogen sulfide exposure in sour gas processing. Middle Eastern complexes specify these for chloride stress corrosion resistance.
- Carbon Steel:ASTM A307 and Grade B7 bolting for non-corrosive utility applications. Volume procurement flows through integrated supply contracts bundling fasteners with valve packages.
- Plastic:Polymer-based fasteners for electrical isolation and low-load chemical exposure. Niche specification in instrumentation panels and non-structural enclosures.
Stainless steel anchors current installed base value. Alloy grades are climbing the fastest as sour service requirements expand.
End Use:
Application environment dictates certification burden, with oil and gas imposing NACE MR0175 qualification while automotive and construction apply less stringent ASTM standards.
- Oil & Gas:Hydrocarbon processing equipment including pressure vessels, heat exchangers, and pipeline flanges requiring sour service qualification. US Gulf Coast and Saudi Arabian demand pools drive specification of super-duplex bolting systems.
- Construction:Industrial building envelopes and fuel infrastructure requiring chemical-resistant fastening. Specification expansion tracks carbon capture retrofit installations requiring alkaline stress corrosion resistance.
- Automotive:Fuel system components and chemical transport vehicle assembly. Niche demand for corrosion-resistant fastening in alternative fuel infrastructure.
- Shipbuilding:Marine applications including tanker cargo systems and offshore platform structural connections. Compact Christmas tree assemblies in Brazil and Norway specify miniaturized super-duplex bolting.
Oil and gas dominates specification value. Construction is gaining share fastest from carbon capture infrastructure deployment.
Coating Type:
Surface treatment selection determines leakage performance under tightened emissions protocols, with coated systems commanding premium positioning over standard zinc finishes.
- Coated:Fluoropolymer and proprietary low-friction coatings for volatile organic compound containment. EPA New Source Performance Standards mandate these in Texas and Louisiana refinery upgrades.
- Zinc Plated:Electroplated zinc layers providing sacrificial corrosion protection for indoor and low-exposure applications. Cost-effective specification in non-critical utility systems.
- Galvanized:Hot-dip zinc coating for extended outdoor durability. Marine and coastal petrochemical facilities specify these for atmospheric corrosion resistance.
- Anodized:Electrochemical oxide layers on aluminum substrates for electrical isolation and decorative finish. Limited petrochemical application in instrumentation housings.
Coated fasteners dominate new specification for emissions compliance. Zinc plated retains volume share in maintenance procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German forging houses export large-diameter pressure vessel bolting to Saudi Arabia's Jubail Industrial City expansion projects. This trade corridor concentrates NORSOK-qualified supply capacity in European metallurgical laboratories serving Middle Eastern refinery construction timelines.
United States
Texas and Louisiana refineries drive specification of EPA-compliant coated alloy fasteners for fluid catalytic cracking unit retrofits. The EPA New Source Performance Standards mandate volatile organic compound containment upgrades across the US Gulf Coast. Houston's industrial supply corridor compresses qualification timelines for sour service bolting systems.
Saudi Arabia
Jubail Industrial City expansion projects accelerate procurement of super-duplex grades for hydrogen sulfide-rich feedstock handling. The Saudi Standards, Metrology and Quality Organization aligns procurement with NACE MR0175 sour service protocols. Eastern Province complexes specify nickel-based alloys for chloride stress corrosion resistance in offshore manifolds.
Germany
Specialized forging houses with NORSOK qualification anchor European supply of large-diameter pressure vessel bolting. The country's technical standards institute governs mechanical property verification for hydrogen embrittlement screening. Ruhr Valley metallurgical laboratories pre-certify super-duplex grades before Middle Eastern project award.
China
Shandong and Zhejiang refineries upgrade procurement standards to match EPA-equivalent containment protocols under MEE atmospheric emission controls. The Ministry of Ecology and Environment mandates low-leakage packing systems imposing tighter surface finish specifications on fastener threads. Yangtze River Delta distributors with dual US-China certification capture specification influence.
India
Dahej and Hazira industrial zones lack qualified domestic suppliers for NACE-compliant sour service fasteners, creating import substitution openings. The Bureau of Indian Standards develops local certification frameworks for hydrocarbon processing equipment. Gujarat's petrochemical corridor concentrates demand for corrosion-resistant bolting in downstream complexes.
Petrochemical Fasteners Market Competitive Landscape
Player mix skews toward specialized metallurgical laboratories and diversified industrial conglomerates with engineered anchoring portfolios. Market structure concentrates around forging specialists with in-house hydrogen embrittlement testing capabilities and distributors with full traceability documentation. Two strategic archetypes dominate: NACE-qualified alloy forgers serving sour service applications and integrated supply contractors bundling fasteners with valve and flange packages. Competitive moves center on pre-certification capacity expansion and metallurgical laboratory accreditation for accelerated project qualification.
Within the specialty alloy tier, Bumax Specialty Stainless Fasteners and PCC Fasteners occupy distinct positioning vectors. Bumax anchors its market presence through super-duplex stainless grades, while PCC represents forged large-diameter bolting specialists serving pressure vessel flange applications. Hilti Group exemplifies the diversified industrial archetype with engineered anchoring capabilities extending into high-load refinery installations. These three companies illustrate the competitive spectrum from pure-play metallurgical specialists to broad industrial technology providers.
| Leading Market Players |
|---|
| Hilti Group |
| LISI Group |
| PCC Fasteners |
| Nord-Lock Group |
| Bollhoff Group |
| Stanley Black & Decker |
| Acument Global Technologies |
| Bumax Specialty Stainless Fasteners |
| Fastenal Company |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German and Italian forging houses with NORSOK qualification anchors price floors for large-diameter pressure vessel bolting, compressing margin elasticity for distributors lacking in-house metallurgical testing capabilities. This scale concentration rewards laboratories with captive hydrogen embrittlement screening while forcing smaller forgers toward commodity carbon steel segments.
Pricing Analysis
Next-generation super-duplex grades command substantial premiums over standard austenitic stainless configurations, while legacy carbon steel bolting faces persistent cost compression. Three-tier pricing structure across NACE-certified premium, ASTM-compliant standard, and utility-grade economy levels reflects certification burden and traceability documentation depth. Price differentiation hinges on sour service qualification status and captive aftermarket service bundling. Margins are tightening in carbon steel tiers due to integrated supply contract consolidation, while oil and gas procurement teams show lowest price sensitivity for NACE MR0175-compliant alloys.
Supply Chain Analysis
Germany and Italy anchor European forging of large-diameter pressure vessel bolting, while Saudi Arabia and the US Gulf Coast concentrate downstream demand absorption. Raw material feeds draw from nickel superalloy producers, austenitic stainless mills, and chromium feedstock suppliers. Single-source vulnerability concentrates in NORSOK-qualified metallurgical laboratories capable of hydrogen embrittlement screening. Distribution runs through specialized engineering-procurement-construction contractors bundling fasteners with valve and flange packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts embedding RFID-tagged bolting expand faster than hardware procurement, converting capital expenditure into recurring service revenue streams. This service-attach dynamic restructures competitive economics toward digital twin integration capabilities.
For Market Incumbents: Shield specification influence by deepening captive metallurgical testing capacity and securing dual US-China certification capabilities ahead of MEE alignment with EPA protocols. Narrow-gap welding substitution in pipeline construction threatens mechanical fastening volumes in hydrocarbon transport. Pre-certification capacity expansion in super-duplex grades defends positioning against qualification timeline compression. For New Entrants and Emerging Players: Aftermarket RFID integration and digital twin services present under-served white space where incumbents lack predictive maintenance infrastructure. India's Dahej and Hazira corridors offer the most penetrable geography given domestic NACE qualification gaps. Target carbon capture retrofit installations specifying duplex stainless for alkaline stress corrosion resistance, leveraging modular construction procurement concentration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among metallurgical laboratories with in-house hydrogen embrittlement testing and full traceability documentation capabilities. Long-term viability favors sour service specialists with NACE MR0175 accreditation depth over commodity carbon steel distributors. Watch for EPA-MEE regulatory convergence accelerating dual-certification requirements as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification Capacity Expansion | Ruhr Valley laboratories compress project award timelines for Jubail Industrial City expansion. |
| Digital Twin Integration | RFID-embedded bolting enables predictive maintenance contracts and recurring aftermarket revenue. |
| Dual Certification Investment | US-China qualified distributors capture MEE-EPA convergence in Shandong and Zhejiang refineries. |
| Backward Integration into Forging | In-house super-duplex production defends margin against nickel price volatility. |
| Carbon Capture Specification Targeting | Duplex stainless positioning captures amine-based CO2 absorption unit procurement. |
Research Methodology
The analysis maps specialty alloy forgers, carbon steel distributors, and digital service integrators, each validated through procurement directors at downstream refineries, metallurgical laboratory technical leads, and engineering-procurement-construction contract managers. Primary fieldwork combined with secondary validation from customs trade data, ASTM and NACE standard documentation, and EPA and MEE regulatory filings. Bottom-up volume triangulation against top-down expenditure analysis ensures cross-verified outputs.
Consistency checks validated projections against refinery capital expenditure cycles and modular construction procurement patterns across the analysis window. Segmentation dimensions modeled include material grade tier, product type, coating specification, and end-use application intensity. CAGRs derived from expenditure trajectory analysis incorporating sour service qualification expansion rates and emissions compliance retrofit timelines.
Forecasts assume regulatory continuity in EPA New Source Performance Standards and MEE atmospheric emission controls; material policy shifts would require re-modeling. Nickel price volatility, substitution by welded joints, and certification timeline extensions represent specific revision risks. Recalibration cycles align with material shifts in refinery expansion project awards and regulatory protocol convergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Industrial Anti-Fatigue Mat Market
Industrial Materials
Steel Cord Market
Industrial Materials
Wedge Wire Screen Market
Industrial Materials
North America Medical Plastics Extrusion Market
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
Isotropic Graphite Market
Industrial Materials
Industrial Round Wood Market
Industrial Materials
Couplings Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
United States Ceramic Roller Bearings Market
Industrial Materials
Fly Ash Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Argon Knife Market
Industrial Materials
Portable Magnetizer Market