
 Industrial Seals Market | 2026-2036
Industrial Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Seals Market Intelligence
A persistent shortage of certified polymer chemists and precision machining specialists is unwinding capacity expansion timelines at several major suppliers. SKF leverages its integrated materials laboratory network to sustain proprietary compound development across Nordic and Asian production hubs. Freudenberg SE anchors its competitive stance through backward integration into fluoroelastomer resin production, while John Crane dominates aftermarket service contracts for rotating equipment in energy and chemical processing sectors.
Industrial seals are mechanical devices engineered from elastomeric, metallic, or composite substrates to prevent fluid or gas leakage between mating surfaces under pressure differentials up to thousands of psi and temperature extremes spanning cryogenic to above 300°C. Their primary purpose is ensuring operational integrity, environmental containment, and energy efficiency in rotating, reciprocating, and static machinery interfaces. Gaskets and O-rings occupy the largest volume share due to universal applicability across fluid handling and machinery applications, while polymer-based surface mount seals represent the fastest-expanding material-format combination as equipment miniaturization accelerates. Composite formulations are capturing margin pools in aerospace and marine end uses where weight reduction and corrosion resistance command specification premiums.
EPA regulations under the Clean Air Act and OSHA process safety mandates constrain seal material selection and emissions containment protocols in United States manufacturing facilities. REACH substance restrictions and the EU F-Gas Regulation in Europe are phasing out specific perfluorinated compounds, compelling reformulation investments across the supplier base. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions to anticipate raw material substitution cycles and qualification timelines.
Market Dynamics
Automotive electrification programs are compressing seal qualification cycles as OEMs demand polymer formulations that withstand thermal spikes above 150°C in battery thermal management systems. This pressure is cascading through supplier qualification pipelines and forcing simultaneous investments in materials science and precision manufacturing.
Growth Catalysts
- Automotive Electrification:Battery pack and power electronics cooling systems require advanced fluoropolymer seals that tolerate aggressive dielectric fluids. German and Chinese OEMs are driving specification upgrades.
- REACH Phase-Down Mandates:The EU F-Gas Regulation is phasing out high-GWP perfluorinated compounds, compelling suppliers to qualify next-generation hydrogenated nitrile and thermoplastic elastomer formulations.
- Rotating Equipment Aftermarket:Energy sector operators in the United States are extending maintenance intervals through predictive monitoring, expanding demand for premium seal kits and field service contracts.
Market Restraints
- Fluoroelastomer Feedstock Concentration:Specialty monomer production clusters in Japan and limited Western suppliers create vulnerability to force majeure disruptions and price volatility.
- REACH Authorization Timelines:Substance restriction processes extend 18-36 months, freezing material substitutions and delaying new product introductions.
- Metallic Seal Substitution:Advanced metal-to-metal sealing technologies in high-pressure oil and gas applications displace polymer solutions in specific wellhead and subsea niches.
Strategic Opportunities
- Hydrogen Economy Infrastructure:Electrolyzer and fuel cell sealing applications represent underdeveloped demand as hydrogen transmission standards crystallize in Germany and the Netherlands.
- India Manufacturing Expansion:PLI scheme incentives for automotive and chemical processing equipment are attracting seal suppliers to establish localized compounding and machining capacity.
- Digital Twin Integration:Convergence of seal sensorization with industrial IoT platforms enables predictive failure modeling and service contract monetization in chemical processing.
Industry Challenges
- Certified Polymer Chemist Scarcity:Formulation expertise for high-temperature elastomers is concentrated among retiring specialists, extending R&D timelines and inflating compensation costs.
- Multi-Jurisdiction Qualification Burden:Simultaneous EPA, REACH, and China GB standard compliance requires parallel testing protocols that strain laboratory capacity and compress margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Seals Market |
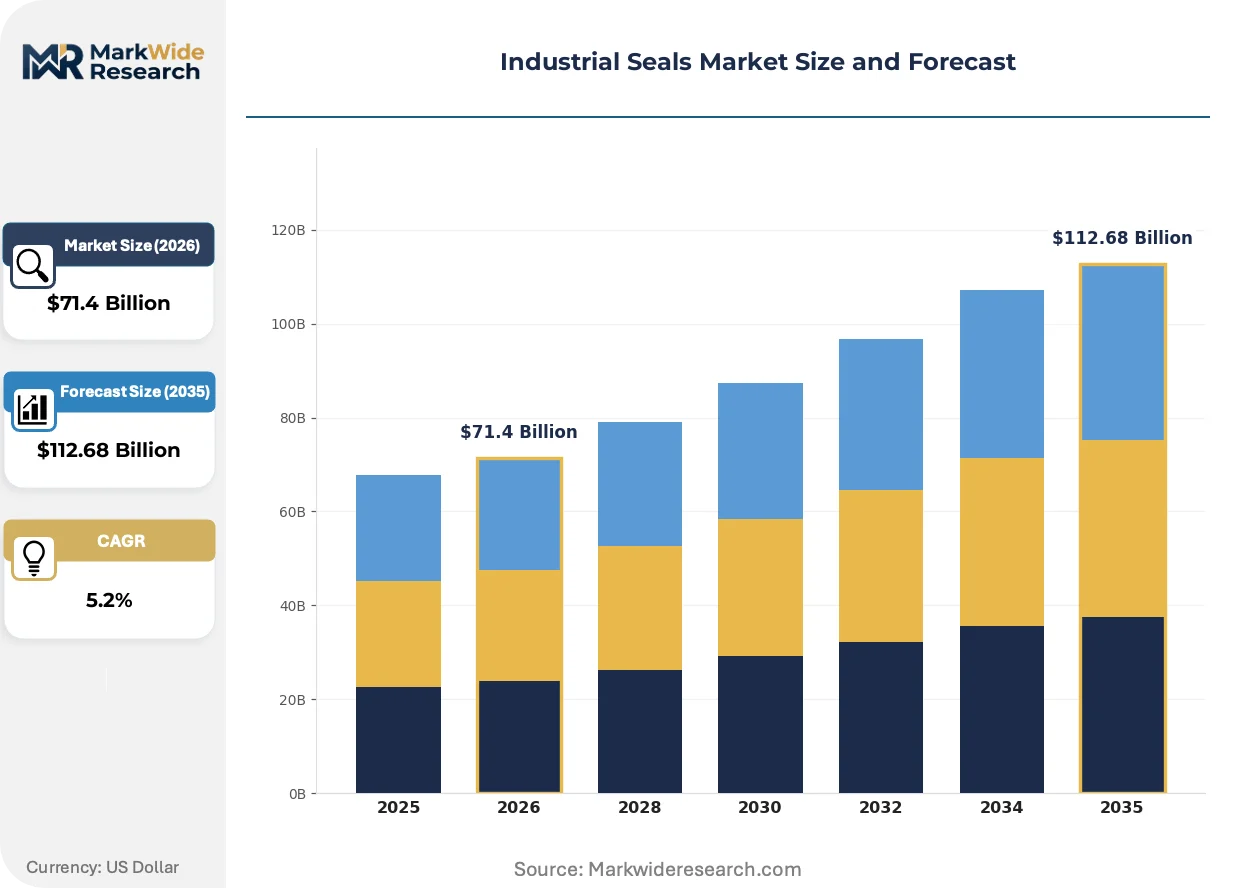
| Market Size in 2026 | $71.4 Billion |
| Market Size in 2035 | $112.68 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O-Rings, Gaskets, Sealing Strips, Surface Mount Seals Material: Rubber, Metal, Polymer, Composite End User: Manufacturing, Automotive, Aerospace, Marine Application: Fluid Handling, HVAC, Packaging, Machinery |
| Companies Covered | Flowserve Corporation, The Timken Company, SKF, AESSEAL, EnPro Industries, Freudenberg SE, Trelleborg AB, Waukesha Bearings Corporation, John Crane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Seals Market Strategic Shifts & Innovations
Polymer science advances and regulatory chemistry restrictions are converging to reshape material portfolios. Equipment miniaturization is compressing seal geometries while elevating performance requirements.
Surface-mount polymer seals are miniaturizing as medical device and semiconductor equipment manufacturers specify sub-millimeter cross-sections for fluid isolation in compact diagnostic and wafer handling systems. Japanese precision molding houses are capturing specification authority through micron-level tolerance capabilities. This format compression is displacing traditional O-ring grooves in equipment designs below 50 millimeters in sealing diameter.
REACH substance restrictions and the EU F-Gas Regulation are compelling fluoroelastomer reformulation investments as ECHA adds perfluoroalkyl substances to candidate lists. Suppliers are accelerating hydrogenated nitrile and perfluoroether development programs to maintain European market access. Aerospace and chemical processing sectors face the steepest qualification burdens due to legacy specification lock-in.
Aftermarket service unbundling is fragmenting traditional supplier-OEM relationships as energy operators in the United States pursue direct procurement of seal kits and field installation services. Distributors are capturing margin pools through inventory consignment and technical support capabilities. This disintermediation is most visible in rotating equipment maintenance across Texas and Louisiana refining corridors.
Industrial Seals Market Segmentation
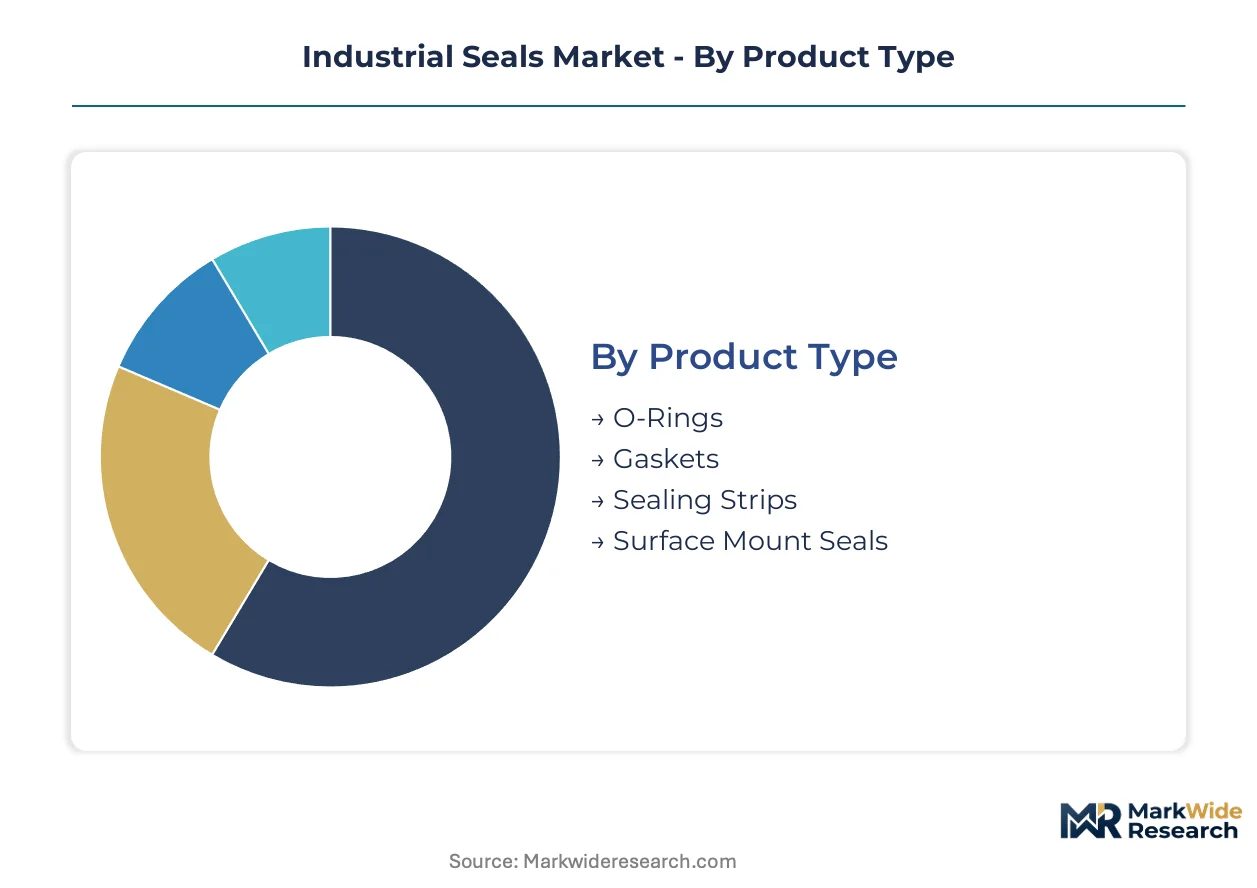
Industrial seals serve heterogeneous performance requirements across pressure, temperature, and chemical exposure spectra. Segmentation reveals how material science investments concentrate in high-margin niches while commodity formats compete on logistics efficiency and certification speed.
Product Type:
Metal-to-metal sealing technologies exert substitution pressure on polymer formats in high-pressure oil and gas wellhead applications, forcing product-level differentiation around temperature tolerance and installation geometry.
- O-Rings:Circular elastomeric loops compressed into grooves create radial seals for static and dynamic interfaces. Automotive electrification programs in Germany and China specify fluoropolymer O-rings for battery thermal management systems handling dielectric fluids above 150°C. REACH substance restrictions on perfluorinated compounds compel reformulation investments across European supply chains.
- Gaskets:Flat mechanical seals engineered from sheet materials conform to flange surface irregularities under bolt preload. Energy sector operators in the United States extend maintenance intervals through predictive monitoring, expanding demand for premium gasket kits in Texas and Louisiana refining corridors. EPA emissions standards constrain material selection for fugitive emissions containment.
- Sealing Strips:Continuous extruded profiles serve linear sealing applications in enclosure and door systems. BIS certification requirements in India shape localized compounding investments under PLI scheme incentives.
- Surface Mount Seals:Miniaturized polymer formats for sub-millimeter cross-sections displace traditional grooves in medical device and semiconductor equipment below 50 millimeters sealing diameter. Japanese precision molding houses capture specification authority through micron-level tolerance capabilities.
Gaskets retain volume leadership; surface mount seals hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity elastomers from aerospace-grade composites commanding specification premiums.
- Rubber:Nitrile, silicone, and EPDM formulations dominate general-purpose fluid handling for cost-sensitive industrial maintenance. Hydrogenated nitrile development accelerates under EU F-Gas Regulation phase-down mandates.
- Metal:Stainless steel, Inconel, and specialty alloys withstand cryogenic to above 300°C extremes in subsea and aerospace applications. Advanced metal-to-metal technologies displace polymers in specific wellhead niches.
- Polymer:Fluoroelastomers and thermoplastic elastomers balance chemical resistance with molding precision. Freudenberg SE anchors competitive stance through backward integration into fluoroelastomer resin production.
- Composite:Fiber-reinforced and multi-layer constructions capture margin pools where weight reduction and corrosion resistance command premiums. Aerospace and marine end uses in Germany and the United States drive qualification cycles.
Rubber retains volume leadership; composite holds the steepest expansion curve.
End User:
Application maturity varies sharply, with electrification forcing qualification compression in automotive while aftermarket service contracts stabilize energy sector procurement.
- Manufacturing:General machinery, pumps, and compressors consume standardized seal formats with emphasis on inventory availability and technical documentation. SKF leverages integrated materials laboratory networks to sustain proprietary compound development.
- Automotive:OEM electrification programs compress seal qualification cycles as battery pack and power electronics cooling systems demand thermal spike tolerance. German and Chinese OEMs drive specification upgrades.
- Aerospace:Legacy specification lock-in creates steep qualification burdens for material substitutions under REACH candidate list additions. Weight reduction priorities favor composite formulations.
- Marine:Corrosion resistance and subsea pressure ratings command premium formulations. Saltwater exposure accelerates elastomer degradation, expanding aftermarket replacement frequency.
Manufacturing retains volume leadership; automotive holds the steepest expansion curve.
Application:
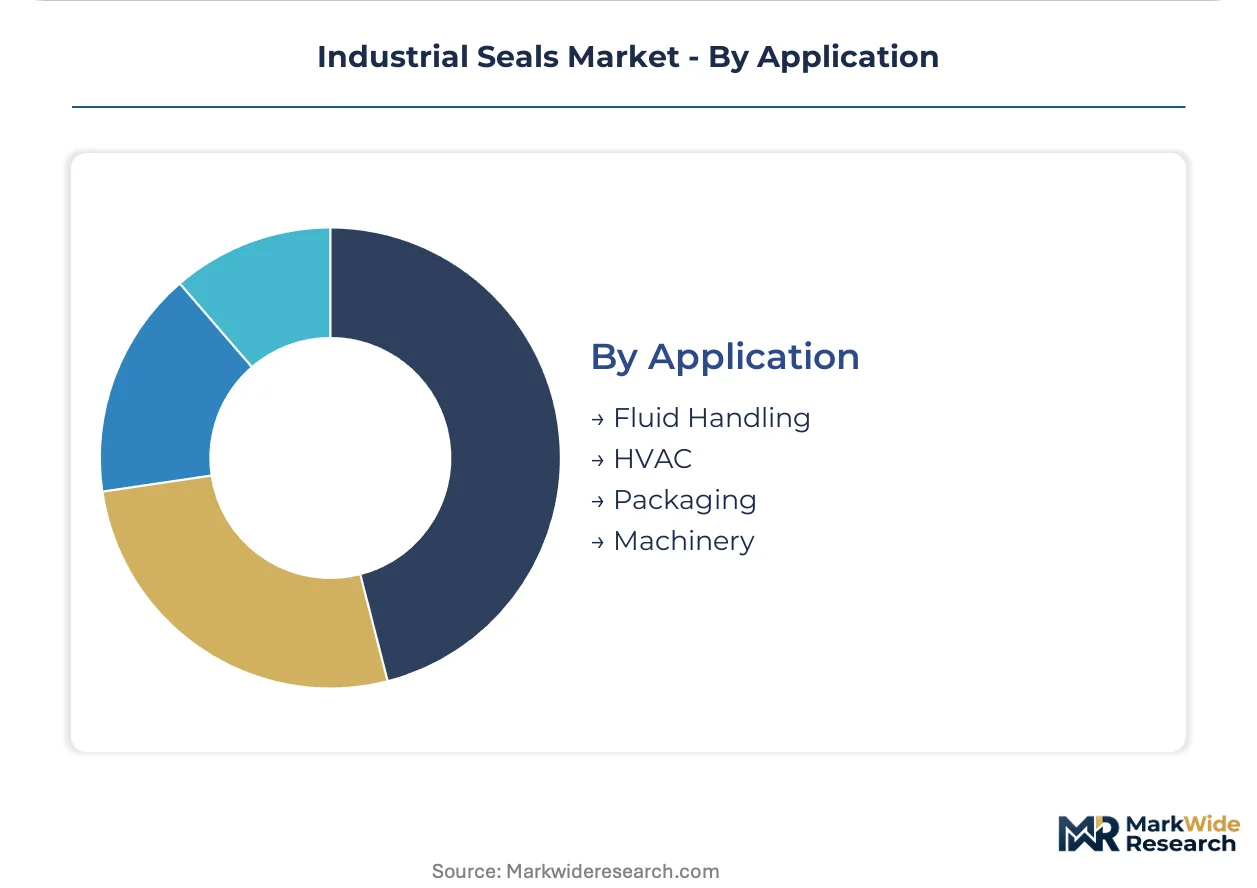
Customer type separation distinguishes specification-driven OEM procurement from price-sensitive MRO purchasing in fluid handling versus machinery end uses.
- Fluid Handling:Pumps, valves, and pipeline systems require chemical compatibility and pressure containment across aggressive media. John Crane dominates aftermarket service contracts for rotating equipment in energy and chemical processing sectors.
- HVAC:Refrigerant containment and thermal cycling resistance align with F-Gas Regulation phase-down timelines in Europe. Hydrocarbon and natural refrigerant transitions compel material reformulation.
- Packaging:Food-grade and pharmaceutical containment specifications invoke FDA and EFSA compliance requirements. Surface mount formats penetrate aseptic filling equipment miniaturization.
- Machinery:Bearing seals, gearbox interfaces, and linear motion systems emphasize friction management and contamination exclusion. Predictive maintenance integration expands premium seal kit demand.
Fluid handling retains volume leadership; packaging holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards under the Clean Air Act anchor regulatory pressure in the United States, while REACH substance restrictions and EU F-Gas Regulation phase-down mandates reshape material qualification timelines across Europe. China GB standards and dual carbon goals drive localization requirements in the world's largest manufacturing base.
United States
Energy sector operators in Texas and Louisiana extend maintenance intervals through predictive monitoring, expanding demand for premium seal kits in refining corridors. OSHA process safety mandates constrain material selection and emissions containment protocols in manufacturing facilities. Houston anchors aftermarket service contract concentration for rotating equipment in chemical processing sectors.
Germany
Automotive OEM electrification programs compress seal qualification cycles as battery thermal management systems demand thermal spike tolerance above 150°C. EU F-Gas Regulation phase-down compels hydrogenated nitrile reformulation investments across supplier networks. Stuttgart and Munich clusters drive specification upgrades for fluoropolymer formulations in power electronics cooling.
China
Battery pack and power electronics manufacturing scale creates concentrated demand for advanced polymer seals handling dielectric fluids. GB standards and MIIT dual carbon goals tighten material certification requirements for domestic and export markets. Yangtze River Delta manufacturing hubs attract localized compounding capacity from multinational suppliers.
Japan
Precision molding houses capture specification authority through micron-level tolerance capabilities for medical device and semiconductor equipment miniaturization. METI industrial policy supports advanced materials development for sub-millimeter cross-section surface mount formats. Nagoya and Osaka clusters dominate high-tolerance seal geometries below 50 millimeters sealing diameter.
India
PLI scheme incentives for automotive and chemical processing equipment attract seal suppliers to establish localized compounding and machining capacity. BIS certification requirements shape material selection and testing protocols for domestic procurement. Maharashtra and Gujarat industrial corridors concentrate new capacity investments from European and Japanese manufacturers.
Industrial Seals Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the Industrial Seals Market. Backward integration into fluoroelastomer resin production and captive materials laboratory networks separate the upper tier from component assemblers. Three archetypes dominate: integrated compound developers with in-house polymer science, precision machining specialists serving miniaturization trends, and aftermarket service providers capturing rotating equipment maintenance contracts. Competitive moves concentrate on strategic partnerships for hydrogen economy qualification and geographic expansion into India under PLI scheme incentives.
Among European-integrated compound developers, Freudenberg SE anchors the backward-integrated archetype through captive fluoroelastomer resin production. SKF exemplifies the laboratory-network model with proprietary compound development across Nordic and Asian production hubs. John Crane occupies a position within the aftermarket service tier, representing the field-installation and predictive maintenance contract archetype for energy sector operators.
| Leading Market Players |
|---|
| Flowserve Corporation |
| The Timken Company |
| SKF |
| AESSEAL |
| EnPro Industries |
| Freudenberg SE |
| Trelleborg AB |
| Waukesha Bearings Corporation |
| John Crane |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between German automotive OEMs and fluoroelastomer compounders lock in both supply access and price visibility for thermal management seals, insulating qualified suppliers from spot market volatility while freezing out unqualified competitors during electrification ramp-ups.
Pricing Analysis
Price spreads between Japanese precision-molded surface mount seals and commodity nitrile O-rings from India span three-tier pricing structure across premium, standard, and economy levels. Certification grade under EU REACH and EPA emissions standards drives differentiation, with F-Gas-compliant hydrogenated nitrile formulations commanding premiums over legacy fluoroelastomers. Cost compression in standard-grade rubber seals is intensifying because of BIS certification requirements and PLI scheme localization pressures in India. Tier 1 automotive OEMs show least price sensitivity for battery thermal management specifications, while general manufacturing maintenance buyers prioritize inventory availability over performance tier.
Supply Chain Analysis
Specialty monomer production clusters in Japan and limited Western suppliers create chokepoint vulnerability for fluoroelastomer feedstock, exposing seal compounders to force majeure disruptions. Manufacturing concentrates in China, Germany, and the United States, with Yangtze River Delta and Stuttgart-Munich corridors anchoring high-performance polymer output. Raw material sourcing draws from fluoropolymer resin producers, hydrogenated nitrile rubber suppliers, and precision machining equipment manufacturers. Single-source vulnerability in Japanese monomer supply represents structural risk. Distribution runs through authorized distributor networks with inventory consignment models dominating aftermarket service contracts in Texas and Louisiana refining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial seals sit in early-cycle expansion as automotive electrification programs compress qualification timelines and force simultaneous materials science and manufacturing investments before specification standards crystallize.
For Market Incumbents: Secure captive fluoroelastomer resin production or hydrogenated nitrile formulation expertise to defend against backward-integrated competitors like Freudenberg SE. Anchor aftermarket service contracts through predictive monitoring integration, as energy operators in Texas and Louisiana disintermediate traditional supplier-OEM relationships. Prioritize certification laboratory capacity expansion to manage parallel EPA, REACH, and China GB standard compliance timelines.
For New Entrants and Emerging Players: Aftermarket seal kit technical support gaps in India's Maharashtra and Gujarat industrial corridors offer white-space entry, as European and Japanese manufacturers localize capacity under PLI scheme incentives. Target medical device and semiconductor equipment miniaturization segments where Japanese precision molding houses currently dominate sub-millimeter cross-section specifications. Pursue direct procurement relationships with hydrogen electrolyzer developers in Germany and the Netherlands before transmission standards crystallize.
For Investors and Strategic Acquirers: Capital is best deployed toward compound developers with in-house polymer science capabilities and captive materials laboratory networks, as certified polymer chemist scarcity extends R&D timelines and inflates compensation costs. Mid-cap specialists with backward integration into fluoroelastomer or thermoplastic elastomer production offer defensive positioning. Watch hydrogen economy infrastructure qualification timelines as inflection indicator for next-generation sealing demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoroelastomer Resin | Freudenberg SE anchors competitive positioning through captive monomer supply control. |
| Digital Twin Integration for Predictive Maintenance | Convergence with industrial IoT platforms enables service contract monetization in chemical processing. |
| Hydrogen Economy Qualification Programs | Electrolyzer and fuel cell sealing applications represent underdeveloped demand as German standards crystallize. |
| India PLI Scheme Localization | Maharashtra and Gujarat corridors attract compounding and machining capacity from multinational suppliers. |
| REACH-Compliant Reformulation Investment | Hydrogenated nitrile and perfluoroether development maintains European market access under F-Gas Regulation. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from seal and bearing manufacturers, ACC and Cefic chemical industry reports, and EPA emissions compliance disclosures. Interviews with maintenance directors at Texas and Louisiana refineries, OEM procurement teams at German and Chinese automotive manufacturers, aftermarket service heads at rotating equipment specialists, and technical R&D directors at polymer compounders informed demand-side validation. Bottom-up segmentation by product type, material, end user, and application triangulates against top-down macroeconomic indicators.
Segmentation dimensions modeled include product format, material chemistry tier, end-use industry maturity, and geographic regulatory cluster across the analysis window. CAGRs derive from installed base growth, replacement rate assumptions, and content-per-unit expansion in electrified vehicle architectures. Forecast inputs incorporate battery pack thermal management specification trends, REACH substance restriction phase-down timelines, and hydrogen infrastructure deployment trajectories.
Forecasts assume regulatory continuity in EPA emissions standards, EU F-Gas Regulation, and China GB certification regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as per- and polyfluoroalkyl substance restrictions evolve across multiple jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
High Performance Random Packing Market
Industrial Materials
United States Engineering Plastics Market
Industrial Materials
Wood Fiber Insulation Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Isotropic Graphite Market
Industrial Materials
Welding Consumables Market
Industrial Materials
Plastics in Electrical and Electronics Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Metal Molds Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Global Friction Products and Materials Market
Industrial Materials
Encapsulated Gaskets/Seals Market