
 LAMEA Driveline Additives Market | 2026-2036
LAMEA Driveline Additives Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Driveline Additives Market Analytics
Specialty lubricant distribution channels across Latin America, the Middle East, and Africa is reconfiguring as regional blenders consolidate procurement networks to secure additive supply certainty. The Lubrizol Corporation leverages its technical service infrastructure to anchor premium formulations in Brazil and Mexico. Infineum International Ltd. competes through tailored driveline additive packages calibrated for high-temperature Middle Eastern operating conditions. Afton Chemical Corporation specializes in friction modifier technologies that sustain OEM approval rates across diverse transmission architectures.
LAMEA driveline additives comprise chemically engineered compounds—typically organo-molybdenum complexes, sulfur-phosphorus extreme pressure agents, and polymethacrylate viscosity index improvers—blended into transmission fluids and axle lubricants to reduce wear, manage friction, and extend component life under severe mechanical stress. Their primary commercial purpose centers on protecting gears, bearings, and clutch packs in vehicles and equipment subjected to heavy loads, frequent stop-start cycles, or abrasive contaminants. Friction modifiers command sustained margin pools as dual-clutch and continuously variable transmissions proliferate across passenger vehicle segments in the region. Anti-wear additives anchored on zinc dialkyldithiophosphate chemistry retain volume dominance in commercial vehicle and heavy-duty equipment applications where equipment uptime economics override fluid cost sensitivity. Viscosity index improvers represent the fastest-growing product category as multi-grade lubricant specifications displace monograde stocks in markets with wide ambient temperature ranges.
Brazil's national petroleum regulator ANP enforces lubricant quality standards that directly shape additive minimum performance requirements for products sold domestically. South Africa's National Regulator for Compulsory Specifications (NRCS) administers SABS-mark certification that governs driveline fluid compliance across the Southern African Customs Union, while Saudi Arabia's SASO standards align with API and ACEA specifications to facilitate import market access. Stakeholders must monitor divergence between national certification regimes and OEM factory-fill specifications as electrified driveline architectures begin demanding thermally stable, copper-corrosion-resistant additive chemistries distinct from legacy internal combustion formulations.
Market Dynamics
Driveline additive procurement across Latin America, the Middle East, and Africa is tightening around sulfur-reduction mandates and electrification-readiness specifications. Brazil's ANP enforcement of stricter lubricant quality tiers is compressing formulation windows for legacy additive packages.
Growth Catalysts
- ANP sulfur limits:Brazil's national petroleum regulator mandates lower sulfur content in commercial lubricants, forcing fleet operators toward premium additive formulations that maintain wear protection under tighter chemical constraints.
- Mining fleet expansion:Heavy-duty equipment operators in Brazil's Carajás and Minas Gerais corridors are scaling additive procurement to match extended drain intervals and severe-duty operating cycles.
- Dual-clutch transmission proliferation:Passenger vehicle manufacturers across Mexico and Brazil are factory-filling friction-modified fluids, pulling specialized organo-molybdenum chemistries into higher volume tiers.
Market Restraints
- Base oil supply concentration:Group II and III base oil production clusters in the US Gulf Coast and Middle East Gulf create import dependency for LAMEA blenders, exposing formulations to freight rate volatility and currency mismatch.
- ZDDP technical ceiling:Zinc dialkyldithiophosphate chemistry faces hard limits in electrified drivelines due to copper corrosion risks, forcing premature abandonment of proven anti-wear architectures.
- SASO-API divergence:Saudi Arabia's standards body maintains alignment gaps with ACEA sequences, requiring dual-certification investments that fragment packaging and inventory economics.
Strategic Opportunities
- Copper-corrosion-resistant chemistries:Electric vehicle thermal management fluids demand additive packages free of legacy sulfur-phosphorus compounds, opening formulation white space for ionic liquid and ashless alternatives.
- Nigeria's informal blending sector:Substandard lubricant prevalence in West Africa creates upgrade potential as the country's standards organization moves toward mandatory product registration.
- Direct-to-fleet distribution:Mining and logistics operators in Chile and Peru are bypassing traditional distributor networks, enabling additive suppliers to capture service revenue through technical field support contracts.
Industry Challenges
- Formulation chemist scarcity:LAMEA regional headquarters of multinational additive houses struggle to retain tribology specialists capable of bridging OEM factory-fill specifications with local regulatory minimums.
- Electrification timeline compression:Automaker announcements of battery-electric platform rollouts in Brazil and South Africa are collapsing the revenue window for internal-combustion-optimized additive investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Driveline Additives Market |
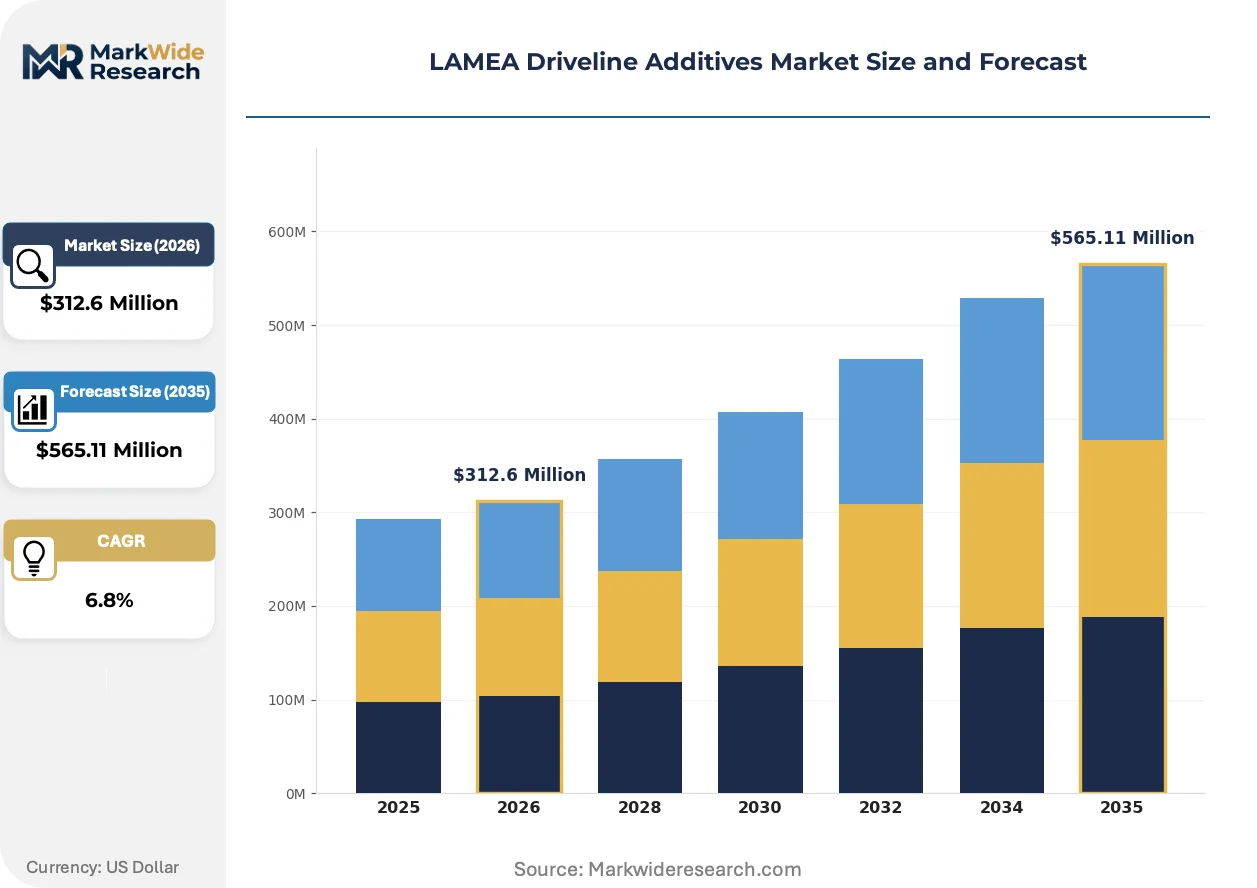
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Friction Modifiers, Extreme Pressure Agents, Anti-Wear Additives, Viscosity Index Improvers Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Equipment, Two-Wheelers Form: Liquid, Powder, Concentrate, Semi-Solid End User: OEMs, Aftermarket Providers, Fleet Operators, Maintenance Shops |
| Companies Covered | The Lubrizol Corporation, Infineum International Ltd., Afton Chemical Corporation, Chevron Oronite Company, LLC, BASF SE, Evonik Industries AG, LANXESS, Vanderbilt Chemicals, LLC, BRB International B.V., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Driveline Additives Market Evolving Landscape
Additive chemistry across LAMEA is pivoting toward thermal stability and electrical compatibility as electrified drivelines displace conventional architectures. Formulation priorities are fragmenting between legacy commercial vehicle protection and emerging e-axle cooling requirements.
Polymethacrylate viscosity index improvers are migrating from monograde legacy stocks toward multi-grade synthetic blends capable of spanning desert heat and high-altitude cold starts. Brazilian commercial fleet managers are specifying these polymers for year-round operational flexibility. The shift is compressing demand for conventional olefin copolymer chemistry in favor of more shear-stable architectures.
South Africa's NRCS is tightening SABS-mark enforcement for driveline fluids entering the Southern African Customs Union, creating compliance bottlenecks for imported finished lubricants. Local blenders are responding by captive-producing additive masterbatches to preserve certification agility. The regulatory friction most affects mid-tier distributors lacking technical service infrastructure to navigate specification updates.
Fleet procurement departments are consolidating lubricant supplier relationships around full-fluid-management contracts that bundle additive replenishment with used-oil analysis and drain interval optimization. Chilean mining operators are displacing spot purchasing with multi-year technical service agreements. The behavioral shift is most pronounced in copper and iron ore extraction verticals where equipment availability economics dominate total cost of ownership calculations.
LAMEA Driveline Additives Market Segmentation
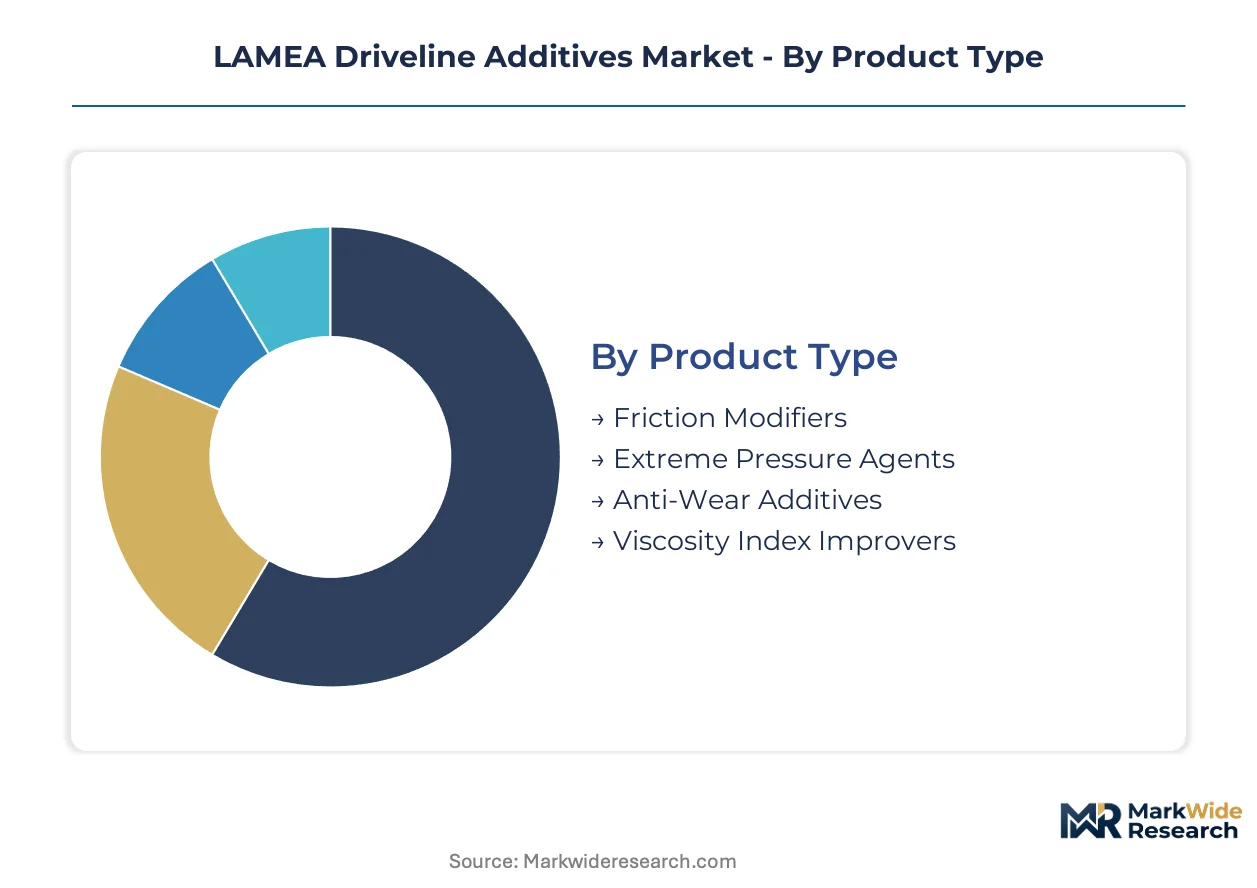
Driveline additive purchasing patterns fragment across four structural dimensions in LAMEA. Product chemistry, vehicle application, physical form, and procurement channel each govern margin capture and technical service requirements differently.
Product Type:
Cost tier determines formulation complexity and procurement concentration across the four additive chemistries.
- Viscosity Index Improvers:Polymethacrylate polymers enable multi-grade lubricants to span desert heat and high-altitude cold starts without seasonal changeouts. Brazilian commercial fleet managers specify these for year-round operational flexibility in Minas Gerais corridors.
- Friction Modifiers:Organo-molybdenum complexes reduce energy losses in dual-clutch and continuously variable transmissions. Passenger vehicle manufacturers across Mexico and Brazil factory-fill friction-modified fluids, pulling specialized chemistries into higher volume tiers.
- Extreme Pressure Agents:Sulfur-phosphorus compounds protect hypoid gears under severe loading.
- Anti-Wear Additives:Zinc dialkyldithiophosphate chemistry dominates commercial vehicle applications where equipment uptime economics override fluid cost sensitivity.
Anti-wear additives hold installed capacity. Viscosity index improvers are rotating up the share rankings.
Application:
Vehicle duty cycle intensity shapes additive performance specifications and drain interval economics.
- Heavy-Duty Equipment:Mining excavators and haul trucks in Brazil's Carajás corridor demand sulfur-reduced formulations that maintain wear protection under ANP-mandated chemical constraints. Extended drain intervals compound additive stress.
- Commercial Vehicles:Long-haul fleets across the Southern African Customs Union specify SABS-mark certified fluids with anti-wear packages calibrated for high-temperature operation.
- Passenger Vehicles:Dual-clutch transmission proliferation drives friction-modified fluid demand.
- Two-Wheelers:Wet clutch compatibility requirements constrain additive selection.
Commercial vehicles hold installed capacity. Heavy-duty equipment is rotating up the share rankings.
Form:
Supply chain configuration and blending infrastructure determine which physical states dominate regional procurement.
- Liquid:Standard delivery format for high-volume transmission fluid and axle lubricant production. Brazilian domestic blenders prefer liquid concentrates for continuous mixing operations.
- Concentrate:Reduced freight costs and extended shelf life favor masterbatch formats for remote mining sites in Chile and Peru.
- Powder:Limited to specialty grease compounding.
- Semi-Solid:Niche applications in sealed gearbox assemblies.
Liquid concentrates hold installed capacity. Concentrate formats are rotating up the share rankings.
End User:
Procurement authority and technical capability split additive demand across four channel structures.
- Fleet Operators:Mining and logistics operators in Chile and Peru are bypassing traditional distributor networks, enabling additive suppliers to capture service revenue through technical field support contracts and used-oil analysis programs.
- OEMs:Factory-fill specifications in Brazil and Mexico demand additive packages that bridge ANP minimums with ACEA sequences, requiring dual-certification investments.
- Aftermarket Providers:Regional distributors consolidate around full-fluid-management contracts bundling additive replenishment with drain interval optimization.
- Maintenance Shops:Informal sector prevalence in West Africa constrains premium additive penetration pending mandatory product registration.
Aftermarket providers hold installed capacity. Fleet operators are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands additive pricing power through domestic blending scale while Chilean mining corridors absorb freight premiums for concentrate delivery. Middle Eastern procurement networks leverage Gulf base oil proximity against African import dependency.
Brazil
Minas Gerais mining fleets and São Paulo commercial vehicle density drive formulation demand. ANP sulfur limits compress legacy additive windows toward premium chemistry. Domestic blenders in Paulínia industrial clusters captive-produce masterbatches to preserve certification agility under shifting quality tiers.
Saudi Arabia
High-temperature operating conditions across desert logistics corridors necessitate thermally stable additive packages. SASO standards maintain partial alignment gaps with ACEA sequences, forcing dual-certification investments. Eastern Province petrochemical infrastructure anchors regional supply chain concentration for Gulf blenders.
South Africa
Southern African Customs Union long-haul fleets specify SABS-mark certified fluids with anti-wear calibration. NRCS enforcement tightening creates compliance bottlenecks for imported finished lubricants. Gauteng industrial corridors concentrate blending capacity to navigate specification update cycles.
Chile
Copper extraction verticals in Atacama and Antofagasta regions displace spot purchasing with multi-year technical service agreements. Mining procurement departments consolidate supplier relationships around full-fluid-management contracts. Concentrate formats gain preference for remote site logistics against liquid freight economics.
Mexico
Passenger vehicle manufacturers factory-fill friction-modified fluids for dual-clutch transmission proliferation. OEM specifications bridge domestic regulatory minimums with export-market ACEA sequences. Bajío automotive clusters anchor additive demand from transmission and axle lubricant production.
LAMEA Driveline Additives Market Competitive Landscape
Integrated petrochemical conglomerates and specialized additive houses split the market along formulation complexity vectors. Structure tilts toward consolidation at the premium tier where technical service infrastructure anchors long-term supply contracts. Three archetypes dominate: multinational lubricant technology providers with regional headquarters, European chemical majors with backward integration into base oil streams, and mid-scale blenders serving national certification niches. Competitive moves concentrate on capacity rationalization around electrification-ready chemistries and direct-to-fleet distribution bypasses.
Within the multinational technology tier, The Lubrizol Corporation and Infineum International Ltd. exemplify archetypes differentiated by regional technical service depth. Afton Chemical Corporation occupies a position emphasizing friction modifier specialization. European majors including BASF SE and Evonik Industries AG represent integrated chemical platforms with captive additive synthesis capabilities. These named entities anchor competitive dynamics without exhausting the participant set, as regional blenders and captive petrochemical operations retain material volume positions in national markets.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| Infineum International Ltd. |
| Afton Chemical Corporation |
| Chevron Oronite Company, LLC |
| BASF SE |
| Evonik Industries AG |
| LANXESS |
| Vanderbilt Chemicals, LLC |
| BRB International B.V. |
| Others |
Value Network & Pricing Analysis
Undercapacity in Brazilian domestic additive synthesis is compressing supplier margins while amplifying pricing power for importers serving ANP-compliant formulations. Paulínia industrial cluster blenders are absorbing freight premiums from US Gulf Coast Group II base oil sources, passing through cost volatility to mining fleet procurement departments locked into extended drain interval contracts.
Pricing Analysis
The customization-premium spread separates configured-to-order friction modifier packages for dual-clutch transmissions from standard anti-wear additive volumes. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—ANP Tier 1 compliance commands substantial premiums over minimum statutory formulations. Price differentiation hinges on SABS-mark certification investment and after-sales technical service bundling. Cost compression in standard-tier ZDDP chemistry is intensifying because electrification timelines are collapsing demand visibility for legacy architectures. Aftermarket maintenance shops exhibit highest price sensitivity; mining fleet operators show lowest sensitivity due to equipment uptime economics.
Supply Chain Analysis
Extended payment terms from Chilean mining procurement departments are forcing additive suppliers into supply-chain finance facilities to bridge working capital gaps. Geographic supply concentration centers on the US Gulf Coast, Middle East Gulf, and Paulínia industrial corridor in Brazil. Raw material dependencies draw from Group II/III base oil streams, organo-molybdenum friction modifier precursors, and polymethacrylate polymer feedstocks. Single-source vulnerability around Gulf base oil production exposes LAMEA blenders to freight rate volatility and currency mismatch. Distribution runs through consolidated regional distributor networks with direct-to-fleet bypasses gaining share in mining verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAMEA driveline additives market is positioned for cyclical recovery as mining capital expenditure cycles turn and Brazil's commercial vehicle parc renewal accelerates under ANP enforcement timelines.
For Market Incumbents: Pre-empt electrification-readiness obsolescence by captive-producing copper-corrosion-resistant additive masterbatches in Paulínia and Gauteng corridors. Deepen backward integration into viscosity index improver polymer synthesis to defend margin position against Gulf base oil freight volatility. Anchor long-term supply contracts through technical service infrastructure investments that lock in mining fleet relationships before dual-certification requirements fragment procurement. For New Entrants and Emerging Players: Build out direct-to-fleet distribution capabilities in Chilean copper extraction verticals where spot purchasing displacement creates service revenue capture opportunities. Target Nigeria's informal blending sector upgrade trajectory as mandatory product registration enforcement opens formulation white space. Penetrate through ashless additive chemistry specialization for electric vehicle thermal management fluids where incumbent ZDDP investments create architectural inertia. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among additive houses with captive technical service infrastructure anchoring full-fluid-management contracts. Long-term viability over a five-to-ten year window favors targets with electrification-ready chemistry pipelines and regional certification agility. Acquisition focus should center on mid-scale blenders serving ANP-SABS dual-certification niches. The signal to watch is ANP quality tier enforcement acceleration as inflection indicator for premium formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Synthesis | Captive production of organo-molybdenum complexes in Paulínia insulates Brazilian blenders from import dependency. |
| Dual-Certification Investment | ANP-ACEA bridging capabilities unlock OEM factory-fill specifications in São Paulo automotive clusters. |
| Direct-to-Fleet Distribution Buildout | Technical field support contracts in Atacama mining corridors displace traditional distributor margin capture. |
| Electrification-Ready Chemistry Pipeline | Ionic liquid and ashless alternatives address copper corrosion risks in e-axle thermal management fluids. |
| Regional Masterbatch Production | Gauteng captive synthesis preserves SABS-mark certification agility under NRCS enforcement tightening. |
Research Methodology
A spread of perspectives from lubricant blending plant managers, mining fleet procurement directors, ANP regulatory affairs specialists, and aftermarket distributor principals converged on the working assumptions. Primary interviews combined with secondary validation from customs trade data, ANP quality tier enforcement records, SABS-mark certification databases, and SEC filings from listed additive houses. Bottom-up volume triangulation across product chemistry segments was cross-checked against top-down value estimates derived from regional base oil consumption patterns.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning product chemistry, vehicle application, physical form, and procurement channel. CAGRs were derived from installed base dynamics, drain interval extension trends, and electrification penetration assumptions. Industry-specific forecast inputs included mining fleet utilization rates in Carajás and Minas Gerais corridors and dual-clutch transmission factory-fill penetration in Mexican Bajío automotive clusters.
Stress conditions across ANP enforcement acceleration, Gulf base oil supply disruption, and copper-corrosion-resistant chemistry adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Marine Fuel Additives Market
Additives
Sorbitan Oleate Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Global UV Absorbers Market
Additives
United Kingdom Feed Additives Market
Additives
Asia Pacific Silage Additives Market
Additives
Europe Citric Acid Market
Additives
Lecithin and Phospholipids Market
Additives
Global Lubricating Oil Additives Market
Additives
Amino Acids Premixes Market
Additives
Pearlizers Market
Additives
Plastics Modifiers Market
Additives
Polyols and Sorbitols Products Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Cassia Gum Market
Additives
Sorbitan Esters Market