
 Grouting Materials Market | 2026-2036
Grouting Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Grouting Materials Market Foresight
Capital-intensity divergence between integrated formulators and regional blenders is collapsing as raw material volatility squeezes mid-tier operators. Sika leverages its global supply network to sustain margin stability across cementitious and epoxy formulations. Mapei anchors its position through specialized distribution partnerships with large infrastructure contractors. Fosroc competes in emerging markets by navigating local specification standards without full manufacturing footprints.
Grouting materials are pumpable mixtures—typically cementitious slurries, epoxy resins, polyurethane foams, or acrylic dispersions—engineered to fill voids, transfer loads, or seal against water ingress under pressures ranging from gravity feed to several hundred bar. Their primary industrial purpose is ground improvement and structural void filling in civil engineering, mining, and building restoration. Cement-based grouts occupy the dominant volume position due to cost efficiency in dam foundation sealing and tunnel lining backfill. Epoxy grouts command premium positioning in precision machinery baseplate installations where vibration damping and chemical resistance justify higher material costs. Polyurethane grouts are gaining fastest in leak-sealing applications where rapid cure times reduce construction downtime.
OSHA's respirable crystalline silica standard and EPA hazardous waste disposal rules are elevating compliance costs for cement-based product lines while creating specification advantages for low-silica and resin-based alternatives. REACH registration requirements in Europe and China's GB standards for construction chemicals are fragmenting formulation portfolios across jurisdictions. Stakeholders must monitor regulatory divergence between silica exposure limits and resin chemical classifications to align R&D pipelines with shifting compliance thresholds.
Market Dynamics
Raw material volatility is compressing mid-tier formulators while integrated operators capture margin through captive cement and resin supply. This structural squeeze is reshaping competitive tiers across cementitious, epoxy, and polyurethane product lines.
Growth Catalysts
- OSHA silica exposure limits:Tightened workplace standards are accelerating specification shifts toward low-silica cementitious blends and resin-based alternatives in U.S. tunneling and mining projects.
- Polyurethane rapid-cure chemistry:Infrastructure contractors facing liquidated damages clauses are specifying foams that achieve structural strength within minutes rather than hours.
- China's state infrastructure programs:State-backed rail and hydropower investments are concentrating demand for high-performance ground stabilization systems in Sichuan and Yunnan provinces.
Market Restraints
- Epoxy resin feedstock concentration:Bisphenol-A and amine hardener supply chains concentrate in Gulf Coast petrochemical complexes, exposing formulators to hurricane-related disruption.
- REACH registration burdens:European ECHA chemical classification requirements are fragmenting formulation portfolios and elevating compliance costs for multi-jurisdictional product lines.
- Portland cement carbon intensity:Embodied CO2 in traditional grouts faces mounting scrutiny from infrastructure owners with net-zero procurement mandates.
Strategic Opportunities
- India's dam rehabilitation pipeline:Central Water Commission programs are creating specification windows for high-performance injection grouts in seepage control applications.
- Geopolymer chemistry convergence:Alkali-activated binders combined with industrial waste streams are opening formulation paths outside traditional cement-resin dichotomies.
- Digital specification platforms:Contractor procurement portals are disintermediating traditional distribution and enabling direct technical engagement between formulators and project engineers.
Industry Challenges
- Injection equipment technician scarcity:Specialized pump operators capable of managing multi-component resin systems at high pressure command premium wages and constrain project scaling.
- Batch certification timelines:Project-specific testing protocols for dam foundation grouts extend qualification cycles and compress working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grouting Materials Market |
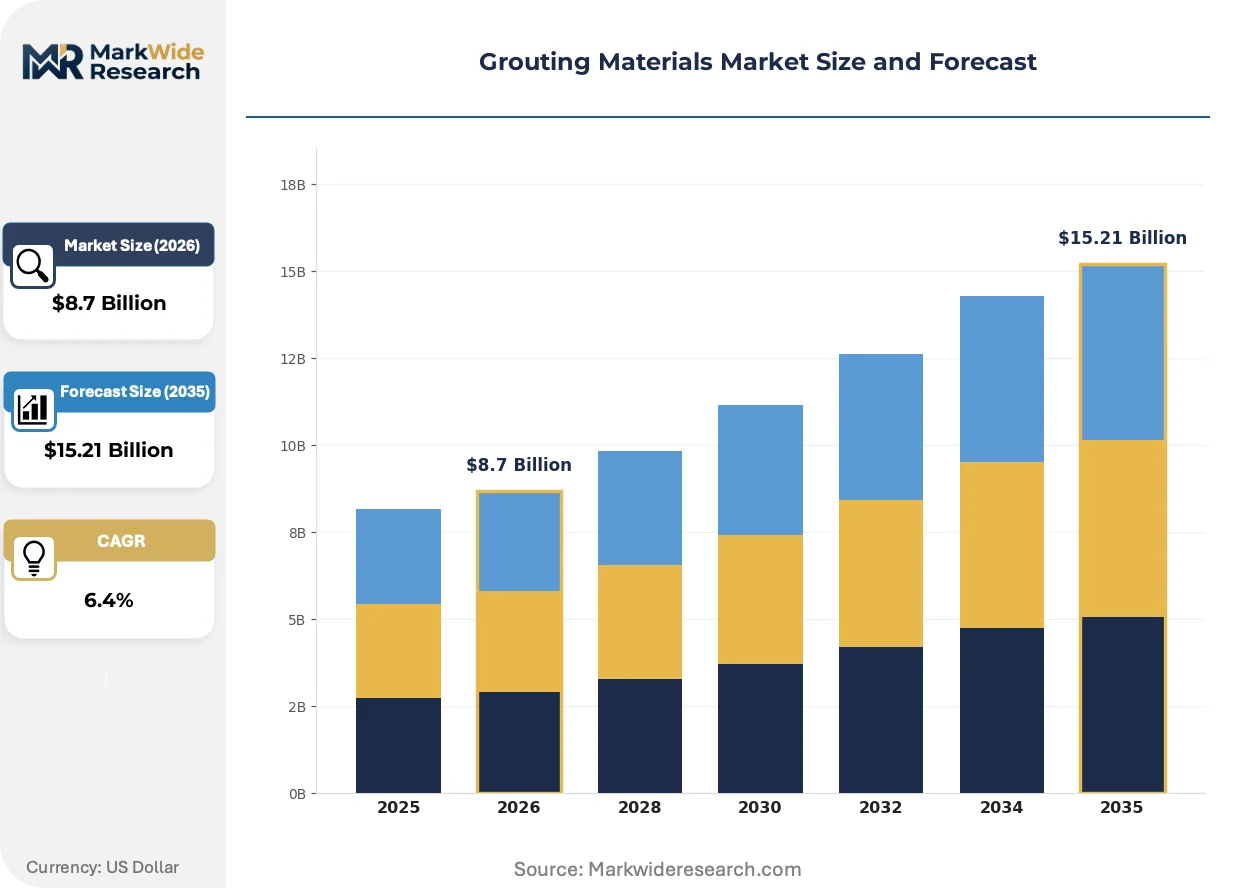
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement-based Grouts, Epoxy Grouts, Polyurethane Grouts, Acrylic Grouts Application: Construction, Infrastructure, Residential, Industrial End User: Contractors, Homeowners, Architects, Engineers Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Sika, LATICRETE, Custom Building Products, Mapei, Fosroc, BASF, Ardex Group, Five Star Products, GCP Applied Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grouting Materials Market Shifts & Advancements
Formulation chemistry and procurement mechanics are diverging simultaneously. Material scientists are engineering performance outside traditional binder categories while buyers restructure supplier relationships around outcome guarantees rather than commodity supply.
Ultrafine cement grouts with particle distributions below 10 microns are penetrating micropile and rock bolt applications previously reserved for chemical systems. Geotechnical contractors in Alpine tunneling projects are specifying these materials for fissure widths below 0.2 millimeters. The technology is supplanting low-viscosity epoxy injections in cost-sensitive ground stabilization where chemical resistance requirements are moderate.
China's GB standards for construction chemicals are tightening classification requirements for VOC content and heavy metal leachate in resin-based products. Domestic formulators are reformulating acrylic and polyurethane lines to meet MEE environmental compliance windows. Export-oriented manufacturers are maintaining parallel product portfolios to serve GB-compliant domestic projects and REACH-registered European specifications simultaneously.
Major infrastructure owners are unbundling material supply from placement service contracts and awarding them to separate specialist contractors. French and German rail operators have separated grout procurement from tunneling machine contracts, forcing formulators to certify directly with asset owners rather than equipment suppliers. This pattern is most visible in European rail and hydropower sectors where owner-engineer relationships dominate project structuring.
Grouting Materials Market Segmentation
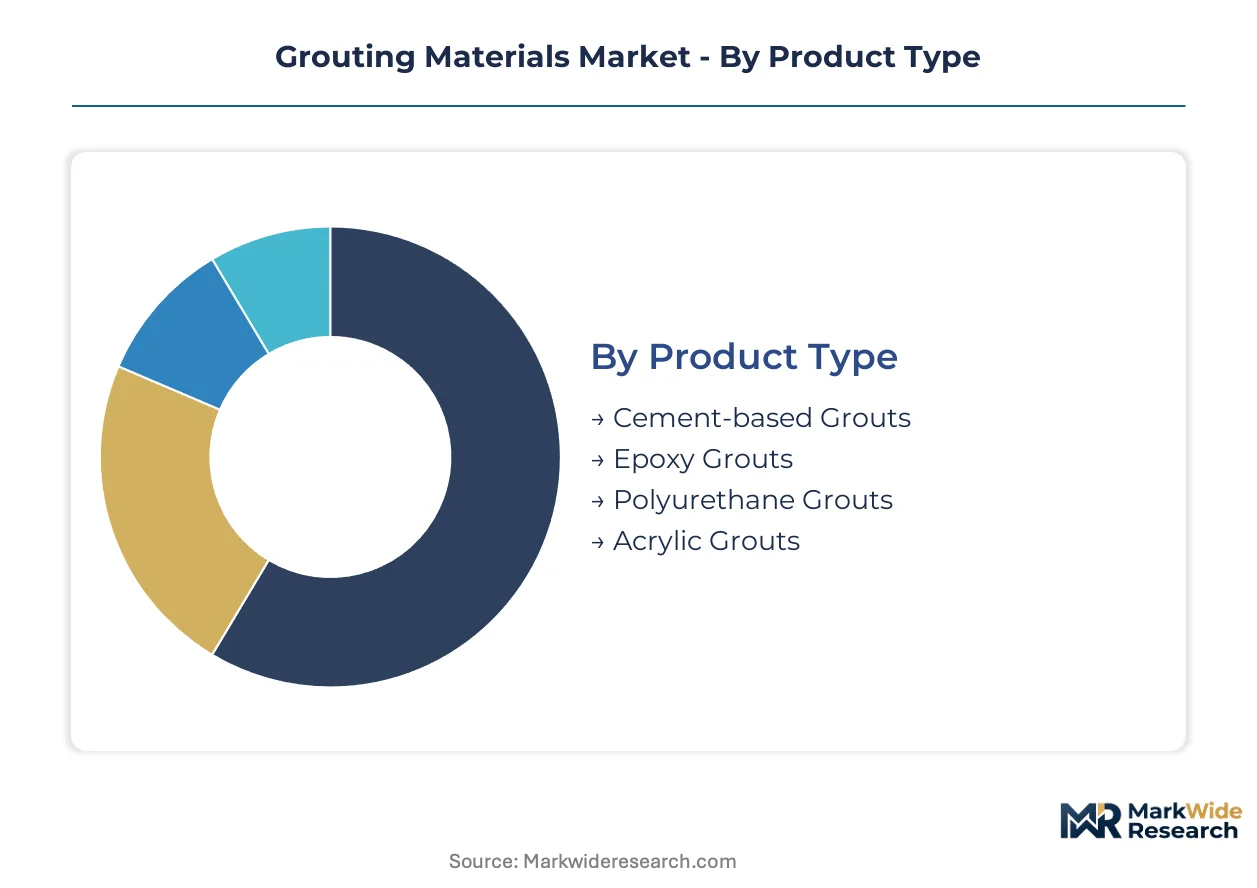
Segmentation in grouting materials reveals where formulation chemistry and procurement mechanics diverge. Product type boundaries are blurring as ultrafine cements displace epoxies in precision applications and geopolymers challenge both categories.
Product Type:
Cement-based formulations face the most acute substitution pressure from low-carbon binders and resin systems as infrastructure owners impose embodied carbon limits.
- Cement-based Grouts:Portland cement and supplementary cementitious material blends dominate dam foundation sealing and tunnel lining backfill. China's state rail programs in Sichuan and Yunnan provinces absorb the largest volume of high-performance cementitious systems for ground stabilization.
- Epoxy Grouts:Two-component systems based on bisphenol-A and amine hardeners deliver precision load transfer for machinery baseplates and chemical resistance in industrial containment. German rail operators specify these for vibration-critical installations where dimensional stability under dynamic loading justifies material cost premiums.
- Polyurethane Grouts:Rapid-cure foams and elastomers seal water ingress in underground structures. Infrastructure contractors facing liquidated damages clauses specify these systems for leak-sealing where cure times compress construction schedules.
- Acrylic Grouts:Flexible dispersions penetrate fine cracks in masonry restoration and building envelope remediation. French heritage conservation specifications favor these for reversible interventions on historic structures.
Cement-based grouts anchor the volume base while polyurethane formulations gain share at the steepest rate.
Application:
Cost tier stratification separates specification-grade infrastructure from commodity residential use, with margin compression concentrated in mid-tier construction segments.
- Construction:Commercial building envelopes and structural void filling consume standardized cementitious blends. Indian dam rehabilitation programs under the Central Water Commission create specification windows for high-performance injection grouts in seepage control.
- Infrastructure:Tunneling, mining, and hydropower applications demand certified batch performance and extended qualification timelines. Alpine tunneling contractors in Switzerland and Austria specify ultrafine cement grouts for rock bolt installations in fissured geology.
- Residential:Foundation repair and basement waterproofing drive volume through retail and contractor channels. Product differentiation centers on ease of mixing and pumpability rather than engineered performance.
- Industrial:Chemical containment, precision machinery installation, and heavy equipment anchoring require epoxy and metallic aggregate systems. OSHA silica exposure limits are accelerating shifts toward resin-based alternatives in U.S. manufacturing facilities.
Infrastructure applications command the highest specification intensity while residential volumes expand most quickly through distribution channel diversification.
End User:
Technical capability scarcity concentrates value capture among specialist contractors capable of managing multi-component resin systems at high pressure.
- Contractors:Geotechnical specialists and tunneling operators procure directly from formulators for project-specific batch certification. French and German rail operators now require direct supplier certification with asset owners rather than equipment manufacturers.
- Homeowners:DIY repair applications drive retail channel demand for pre-packaged cementitious and polyurethane crack repair kits. Product selection prioritizes ease of application over engineered performance specifications.
- Architects:Specification authority in restoration and heritage projects favors acrylic and lime-based systems compatible with substrate breathability requirements.
- Engineers:Ground improvement and structural remediation designs determine grout selection based on rheological properties, strength development, and durability criteria. Digital specification platforms are enabling direct technical engagement between design engineers and formulator technical services.
Contractors control the value chain for engineered applications while homeowners represent the largest addressable population through retail channels.
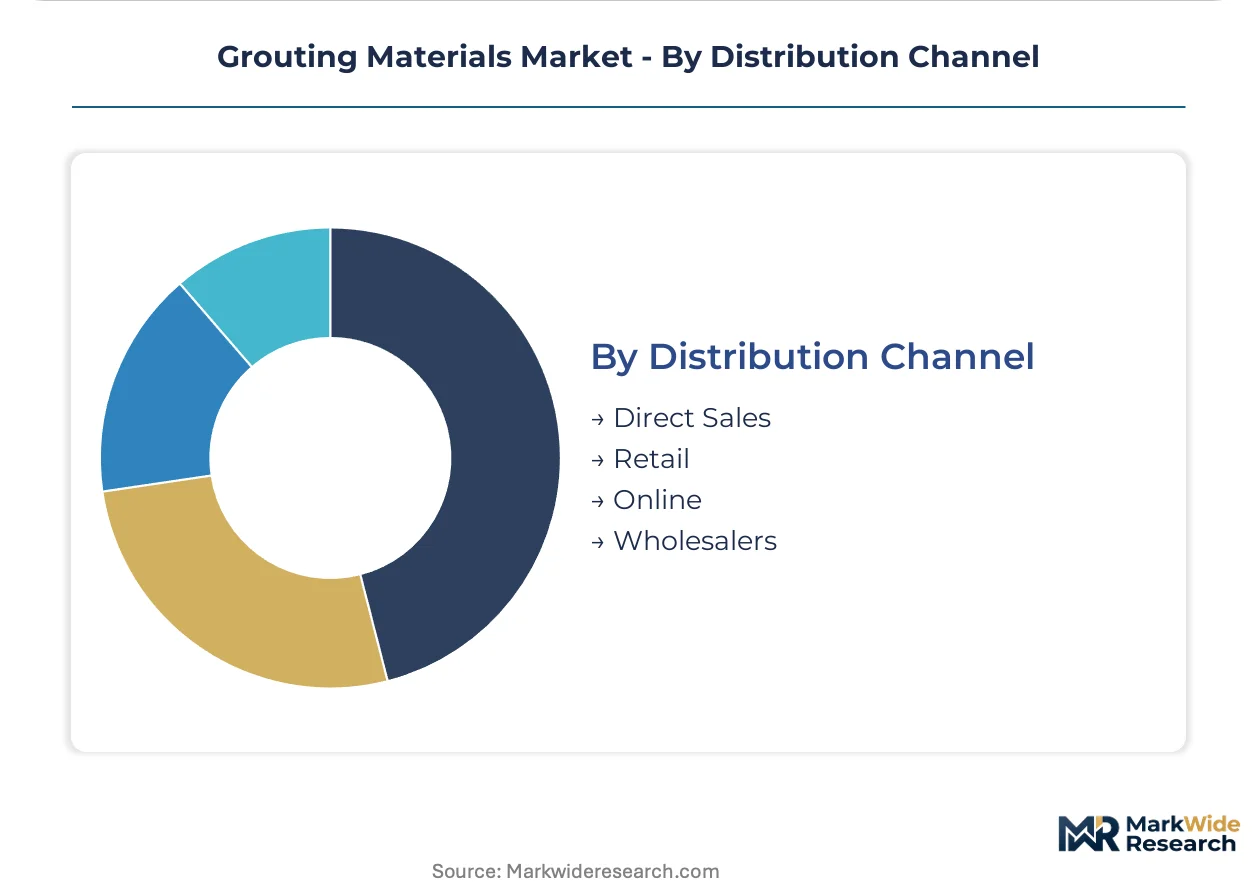
Distribution Channel:
Supply concentration in direct sales to large infrastructure projects contrasts with fragmentation across retail and digital channels serving maintenance and repair segments.
- Direct Sales:Formulator technical teams engage project engineers and specialist contractors for specification development and batch certification. European hydropower and rail sectors increasingly unbundle material supply from placement service contracts.
- Retail:Building material merchants and specialty construction supply stores serve residential and small commercial repair markets. Product portfolios emphasize bagged cementitious mixes and cartridge-dispensed polyurethane foams.
- Online:Contractor procurement portals and digital specification platforms disintermediate traditional distribution for standardized products. Technical documentation and cure-time calculators support self-service specification.
- Wholesalers:Regional distributors aggregate demand from mid-tier contractors and maintain inventory for construction seasonality. Mapei anchors market position through specialized distribution partnerships with large infrastructure contractors in this channel.
Direct sales capture the highest margin applications while online channels expand most quickly through procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in grouting materials tilt toward net-import dependence in infrastructure-heavy economies while manufacturing-anchored nations sustain trade surpluses in specialty formulations. China absorbs the largest import volumes for dam and tunnel applications. Germany and Switzerland maintain export positions in precision epoxy systems.
China
State-backed rail and hydropower investments in Sichuan and Yunnan provinces drive demand for high-performance ground stabilization systems. GB standards for construction chemicals impose tightening VOC content and heavy metal leachate requirements on resin-based products. Domestic formulators in the Yangtze River Delta maintain parallel portfolios for GB-compliant domestic projects and export specifications.
United States
Underground construction in tunneling and mining applications accelerates material consumption across the Mountain West and Pacific Northwest. OSHA's respirable crystalline silica standard elevates compliance costs for cement-based product lines while creating specification advantages for low-silica alternatives. Gulf Coast petrochemical complexes concentrate epoxy resin feedstock supply, exposing formulators to hurricane-related disruption risk.
Germany
Rail operators specify epoxy grouts for vibration-critical installations where dimensional stability under dynamic loading justifies material cost premiums. REACH registration requirements fragment formulation portfolios and elevate compliance costs for multi-jurisdictional product lines. Alpine tunneling contractors in Bavaria and Baden-Württemberg specify ultrafine cement grouts for rock bolt installations in fissured geology.
India
Central Water Commission dam rehabilitation programs create specification windows for high-performance injection grouts in seepage control applications. BIS standards govern construction chemical classifications while state-level procurement rules vary across Maharashtra, Gujarat, and Karnataka. Mumbai-Pune infrastructure corridors concentrate demand for ground improvement materials in urban tunneling projects.
Switzerland
Alpine tunneling and hydropower maintenance sustain demand for precision injection systems in rock stabilization. Swissmedic and federal environmental offices enforce chemical classification requirements that exceed baseline EU thresholds. The Gotthard Base Tunnel corridor and surrounding cantons represent concentrated consumption zones for certified batch performance materials.
Grouting Materials Market Competitive Landscape
Concentration sits with integrated formulators possessing captive supply networks and specialized distribution partnerships. Mid-tier regional blenders face structural margin compression from raw material volatility. Three archetypes dominate: global integrated suppliers with upstream control over cement and resin inputs, regional specialists anchored through contractor certification relationships, and commodity blenders serving price-sensitive construction segments. Competitive moves center on strategic partnerships with infrastructure asset owners and portfolio diversification into low-carbon binder chemistries.
Within the integrated formulator tier, Sika leverages global supply network positioning across cementitious and epoxy formulations. Mapei anchors market presence through specialized distribution partnerships with large infrastructure contractors. Fosroc occupies a position in emerging market access by navigating local specification standards. These three exemplify how scale and technical service capabilities separate premium-tier positioning from commodity competition.
| Leading Market Players |
|---|
| Sika |
| LATICRETE |
| Custom Building Products |
| Mapei |
| Fosroc |
| BASF |
| Ardex Group |
| Five Star Products |
| GCP Applied Technologies |
| Others |
Supply & Pricing Matrix
Project-based procurement contracts with take-or-pay clauses lock in both cement and resin supply access while anchoring price visibility for infrastructure contractors across multi-year tunneling programs in Sichuan and Yunnan provinces. These structures transfer raw material volatility risk from formulators to asset owners while preserving margin stability for integrated suppliers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in precision machinery baseplate applications. Price differentiation hinges on ISO 9001 certification grade and volume scale commitments exceeding bulk tanker deliveries. Cost compression in standard-grade cementitious blends is intensifying because Portland cement carbon intensity scrutiny forces reformulation investments. Residential repair contractors exhibit highest price sensitivity, while German rail operators demonstrate lowest sensitivity given vibration-critical performance requirements.
Supply Chain Analysis
Strategic stockpile preferences dominate cementitious raw material procurement, with formulators maintaining 60-90 day inventories of Portland cement and supplementary cementitious materials to buffer against construction seasonality. Supply concentrates in China, the United States, and Germany for precision epoxy systems. Bisphenol-A and amine hardener feedstocks draw from Gulf Coast petrochemical complexes. Hurricane-related disruption risk exposes formulators to resin supply interruptions. Distribution runs through direct technical sales teams for infrastructure projects and specialized distribution partnerships for mid-tier contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as infrastructure owners unbundle material supply from placement services, creating specification niches for formulators capable of direct asset owner certification. Digital procurement platforms accelerate this disintermediation.
For Market Incumbents: Compound technical service capabilities through captive supply network expansion into alkali-activated binder chemistries. Deepen certification relationships with French and German rail operators as tunneling machine suppliers lose specification gatekeeper status. Defend against geopolymer substitution by accelerating low-carbon formulation pipelines ahead of net-zero procurement mandates. For New Entrants and Emerging Players: Differentiate on rapid-cure polyurethane chemistry for leak-sealing applications where liquidated damages clauses compress contractor schedules. India's dam rehabilitation pipeline under Central Water Commission programs offers the most penetrable specification window. Pursue direct engagement with project engineers through digital specification platforms rather than traditional distribution channels. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists possessing contractor certification relationships and GB standards compliance capabilities for China's state infrastructure programs. Five-to-ten year viability favors formulators with backward integration into cement or resin inputs. The signal to watch is REACH registration burden escalation fragmenting European formulation portfolios and elevating compliance costs for non-integrated operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cement Supply | Sika's captive network sustains margin stability across volatile raw material cycles. |
| Specialized Distribution Partnership | Mapei anchors infrastructure positioning through contractor certification relationships. |
| Geopolymer Chemistry Development | Alkali-activated binders open formulation paths outside traditional cement-resin dichotomies. |
| Digital Specification Platform Launch | Direct technical engagement disintermediates traditional distribution for standardized products. |
| GB Standards Compliance Investment | Domestic formulators maintain parallel portfolios for Chinese and European specifications. |
Research Methodology
Operator-level perspectives from tunneling contractors, geotechnical engineers, cement plant managers, resin procurement leads, and infrastructure asset owners anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, SEC 10-K filings, China GB standard documentation, and ECHA REACH registration databases. Bottom-up project pipeline analysis triangulated against top-down construction spending forecasts.
Sensitivity analysis tested volume and value outputs across formulation chemistry, application intensity, and regional regulatory cluster dimensions over the projection horizon. CAGRs derived from segment-level growth rate convergence modeling. Industry-specific inputs included dam rehabilitation program timelines, OSHA silica exposure limit implementation trajectories, and polyurethane rapid-cure chemistry adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained state infrastructure spending levels in China and India would require recalibration. Forecasts reflect assumptions regarding regulatory divergence between silica exposure limits and resin chemical classifications. Revision becomes warranted when geopolymer chemistry cost parity crosses commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
North America Non-Structural Stainless Steel Fasteners Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
Hose Reinforcement Wire Market
Industrial Materials
Encapsulated Gaskets/Seals Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Lip Seals Market
Industrial Materials
Argon Knife Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Global Friction Materials Market
Industrial Materials
Paint Knife Market
Industrial Materials
Neoprene Foam Market
Industrial Materials
Magnetic Separator Market