
 North America Airport Baggage Handling Systems Market | 2026-2036
North America Airport Baggage Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Airport Baggage Handling Systems Market Analytics
FAA Part 139 airport certification is rotating the competitive landscape by requiring compliant materials handling infrastructure for operational authorization. Vanderlande Industries leverages its established North American install base to sustain recurring service contracts across major hub airports. BEUMER Group anchors its position through specialized high-speed sortation engineering for large-scale conveyor deployments. Daifuku competes by extending its automated guided vehicle portfolio into baggage tractor automation for apron operations.
Airport baggage handling systems encompass the integrated electromechanical infrastructure that transports, sorts, and tracks passenger luggage from check-in through aircraft loading, typically operating at belt speeds of 1.5–2.5 meters per second with RFID tag read rates exceeding 99.5 percent accuracy. Conveyor systems dominate installed value due to their ubiquity in legacy terminal retrofits, while automated guided vehicles represent the fastest-expanding technology segment as airports seek to reduce tarmac vehicle congestion and fuel consumption. RFID technology leads the tracking technology mix, though barcode scanning maintains substantial presence in cost-constrained regional airport upgrades.
The FAA enforces Part 139 operational standards that dictate baggage area safety clearances and equipment fire-resistance ratings, while TSA regulations mandate explosive detection system integration at all checked-baggage screening points. The EPA's evolving refrigerant and emissions standards for ground support equipment indirectly shape electric vehicle adoption in baggage tractor fleets. Stakeholders must monitor how anticipated FAA infrastructure grant prioritization and TSA screening technology refresh cycles will reshape capital deployment timelines across hub and spoke facilities.
Market Dynamics
FAA NextGen infrastructure mandates are accelerating the obsolescence of mechanical baggage sortation across major US hub airports, forcing wholesale terminal retrofits that favor integrated automation architectures over incremental upgrades.
Growth Catalysts
- Part 139 Certification Mandates:The FAA's updated operational standards require compliant fire-resistant materials and safety clearances in baggage handling areas, compelling airports to modernize legacy conveyor infrastructure.
- Hub Modernization Programs:Major southeastern US airports including Atlanta Hartsfield-Jackson and Charlotte Douglas are executing terminal expansions that incorporate automated guided vehicle systems for apron operations.
- RFID Tracking Accuracy Thresholds:Baggage system specifications now demand tag read rates exceeding 99.5 percent, driving replacement of barcode-only scanning infrastructure at Tier 1 facilities.
Market Restraints
- Copper and Steel Input Volatility:Conveyor system fabrication depends on commodity metals whose price swings compress equipment margins and delay procurement decisions.
- Specialized Integrator Concentration:Large-scale automated baggage deployments require engineering capabilities concentrated among a handful of European-headquartered system integrators, creating bottleneck risk.
- Explosive Detection Integration Complexity:TSA mandates for checked-baggage screening impose physical space and throughput constraints that limit retrofit options in older terminal footprints.
Strategic Opportunities
- Electric Ground Support Equipment Transition:EPA refrigerant and emissions standards for baggage tractor fleets create demand for electrified apron automation solutions.
- Regional Airport Upgrade Cycles:Cost-constrained spoke facilities present retrofit opportunities for hybrid barcode-RFID tracking systems at lower price points than full hub deployments.
- Service Contract Unbundling:Airlines and airport authorities are separating long-term maintenance agreements from initial capital purchases, creating recurring revenue streams for technical service specialists.
Industry Challenges
- Mechatronics Talent Scarcity:The convergence of mechanical conveyor engineering with RFID diagnostics and automated vehicle control requires skill sets in short supply across US technical labor markets.
- Legacy System Integration Friction:Brownfield terminal retrofits must interface new automation with decades-old mechanical infrastructure, extending commissioning timelines and inflating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Airport Baggage Handling Systems Market |
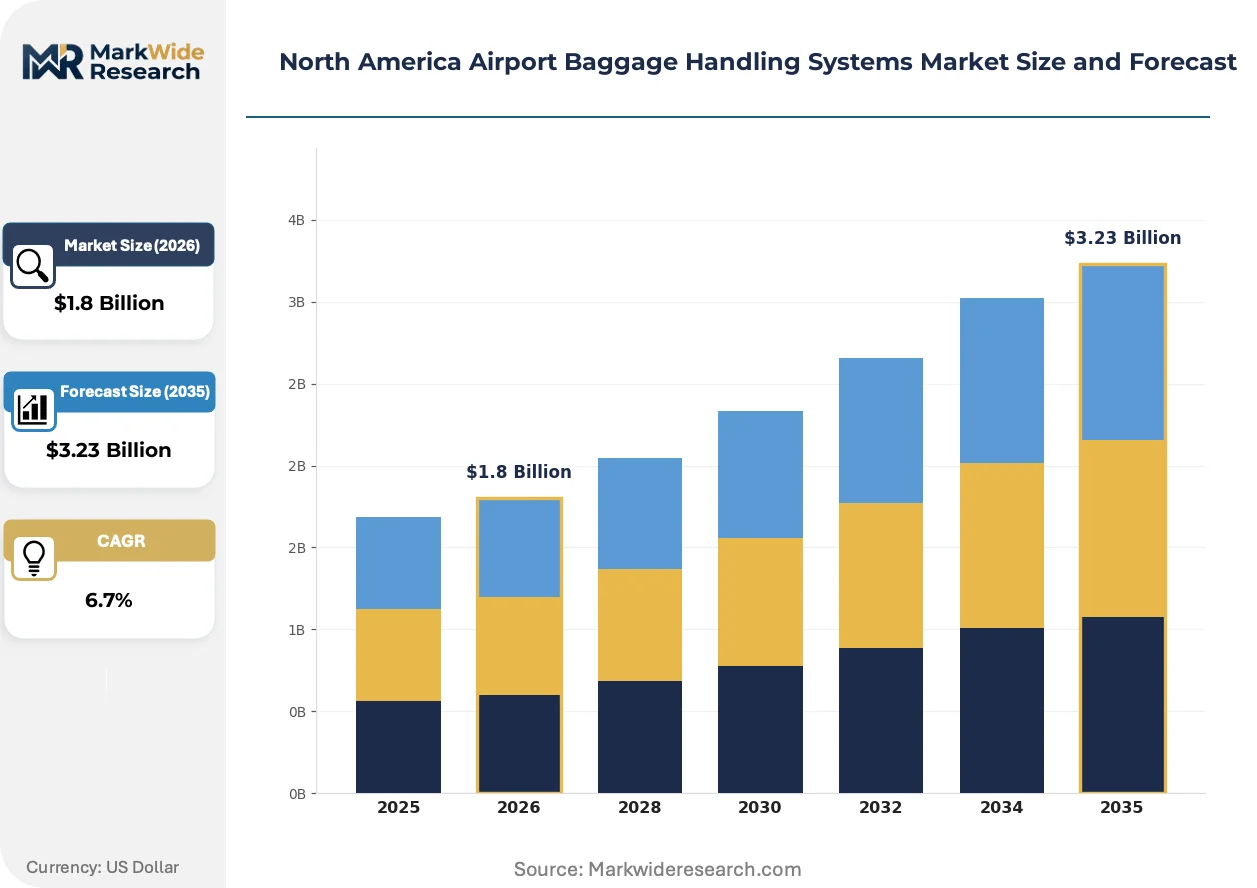
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Systems, Sortation Systems, Automated Guided Vehicles, Baggage Carts Technology: RFID, Barcode Scanning, Automated Systems, Manual Handling End User: Airlines, Airports, Ground Handlers, Service Providers Capacity: Low-Capacity, Medium-Capacity, High-Capacity, Ultra-High Capacity |
| Companies Covered | Vanderlande Industries B.V., BEUMER Group GmbH & Co. KG, Daifuku Co., Ltd., Smiths Group plc, Rapiscan Systems, Inc., Alstef Group SAS, Fives SAS, G&S Airport Conveyor, Pteris Global Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Airport Baggage Handling Systems Market Evolving Landscape
Automated guided vehicles are displacing diesel baggage tractors on congested aprons, while RFID tracking architectures are compressing the operational role of legacy barcode infrastructure.
Automated guided vehicle technology for baggage transport is decomposing the traditional diesel tractor fleet model at major hubs. Delta Air Lines and American Airlines are piloting electric AGV deployments at Atlanta and Charlotte facilities to reduce fuel consumption and tarmac congestion. This shift is decomposing the market position of conventional ground support equipment lessors who lack electrification and automation capabilities.
FAA Part 139 certification requirements are mandating fire-resistant conveyor materials and expanded safety clearances in baggage make-up areas. These standards force airports to replace legacy PVC belt systems with compliant alternatives before operational authorization renewal. Tier 1 hubs in the southeastern United States face the most compressed compliance timelines due to concurrent terminal expansion schedules.
Airline procurement departments are unbundling long-term service agreements from initial system capital expenditure, favoring multi-year technical support contracts with performance-based uptime guarantees. This model displaces the traditional single-source purchase-and-install arrangement. The shift is most visible among legacy network carriers modernizing their hub infrastructure under fleet renewal programs.
North America Airport Baggage Handling Systems Market Segmentation
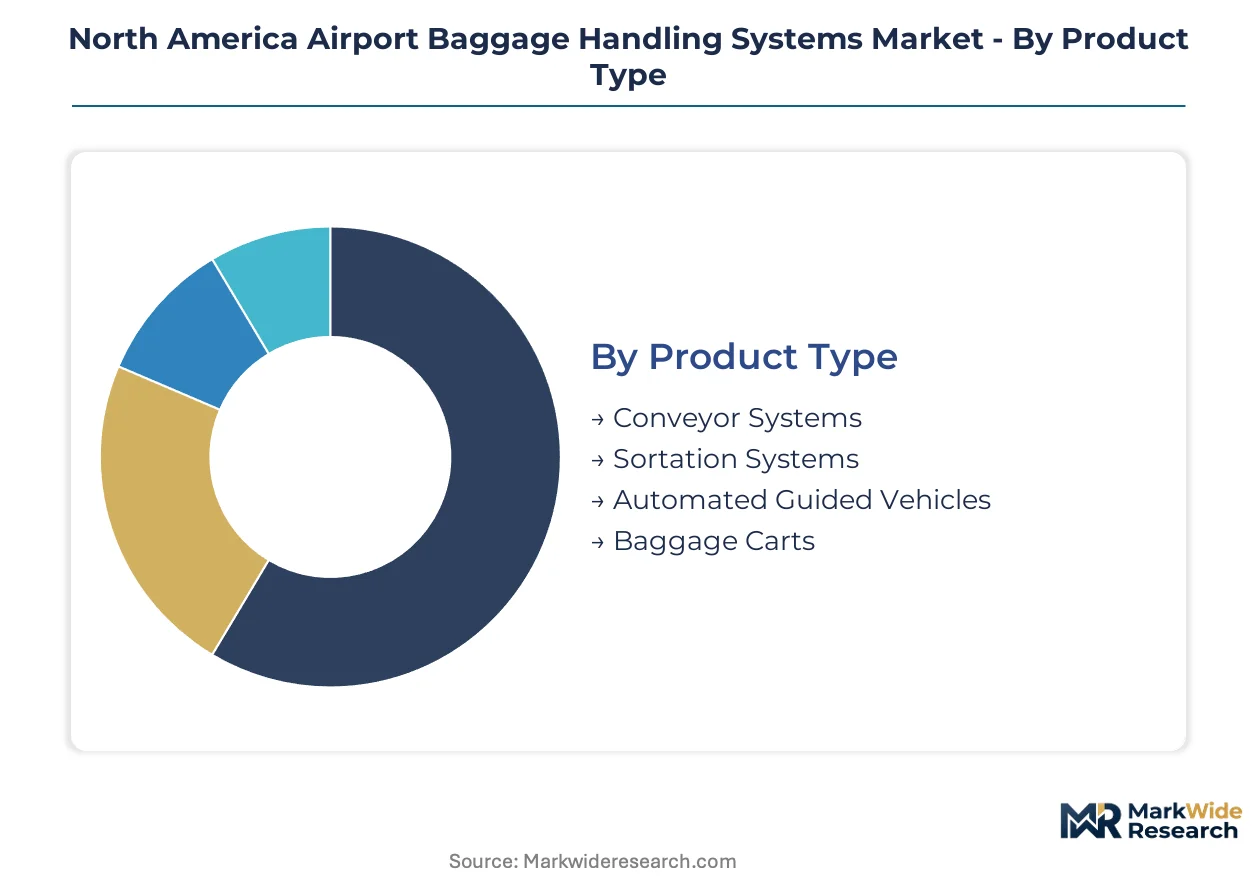
Segmentation in North American airport baggage handling reveals how capital flows diverge between hub modernization and regional retrofit cycles. Equipment specifications, tracking technologies, and throughput tiers each command distinct procurement channels and vendor relationships.
Product Type:
Conveyor systems flow through established integrator-direct channels to major hub airports, while emerging automation formats reach customers via specialized ground support distributors.
- Conveyor Systems:Belt-driven electromechanical infrastructure operating at 1.5–2.5 meters per second dominates legacy terminal retrofits across the southeastern United States. Atlanta Hartsfield-Jackson and Charlotte Douglas are replacing PVC belt systems with FAA Part 139-compliant fire-resistant alternatives during concurrent expansion programs.
- Automated Guided Vehicles:Battery-electric autonomous tractors for apron baggage transport are displacing diesel fleets at Tier 1 facilities. Delta Air Lines and American Airlines are piloting AGV deployments to reduce tarmac congestion and meet EPA ground support equipment emissions standards.
- Sortation Systems:High-speed diverters and tilt-tray sorters handle peak throughput demands at hub airports. These systems require specialized European engineering capabilities concentrated among a handful of integrators.
- Baggage Carts:Non-powered dollies and container loaders remain prevalent at regional spoke facilities with constrained capital budgets. Procurement flows through ground support equipment lessors with limited electrification portfolios.
Conveyor systems dominate installed base. Automated guided vehicles are where expansion concentrates.
Technology:
Technology selection stratifies by airport tier, with RFID commanding premium hub deployments and barcode scanning persisting in cost-constrained regional upgrades.
- RFID:Radio-frequency identification tags deliver 99.5 percent read accuracy at belt speeds exceeding two meters per second. Tier 1 facilities in the southeastern United States mandate RFID infrastructure for baggage tracking compliance with airline service level agreements.
- Barcode Scanning:Laser and camera-based optical recognition maintains substantial presence in legacy infrastructure where tag read rates below 99 percent remain operationally tolerable. Regional airports defer full RFID conversion during phased modernization cycles.
- Automated Systems:Integrated sensor networks and machine vision reduce manual sortation intervention. These architectures require mechatronics expertise in short supply across US technical labor markets.
- Manual Handling:Human-operated baggage transport persists in ultra-small general aviation terminals and temporary terminal configurations. Labor cost pressures are compressing this segment's addressable market.
RFID commands new capital deployment. Barcode scanning retains the largest installed footprint.
End User:
Procurement authority fragmentation shapes how system vendors structure sales relationships and service contract terms across the value chain.
- Airlines:Network carriers with hub operations drive specifications for integrated automation architectures. Fleet renewal programs at Delta and American are unbundling long-term maintenance agreements from initial capital purchases.
- Airports:Port authorities manage infrastructure grants and FAA certification compliance for terminal-wide systems. Southeastern US airports face compressed Part 139 renewal timelines due to concurrent expansion schedules.
- Ground Handlers:Third-party ramp service providers procure apron equipment with shorter replacement cycles than terminal infrastructure. Swire Aviation and dnata are evaluating electric tractor fleet conversions.
- Service Providers:Technical maintenance specialists capture recurring revenue from performance-based uptime guarantees. This segment is expanding as airlines separate service contracts from system procurement.
Airports control infrastructure authorization. Airlines are where specification influence concentrates.
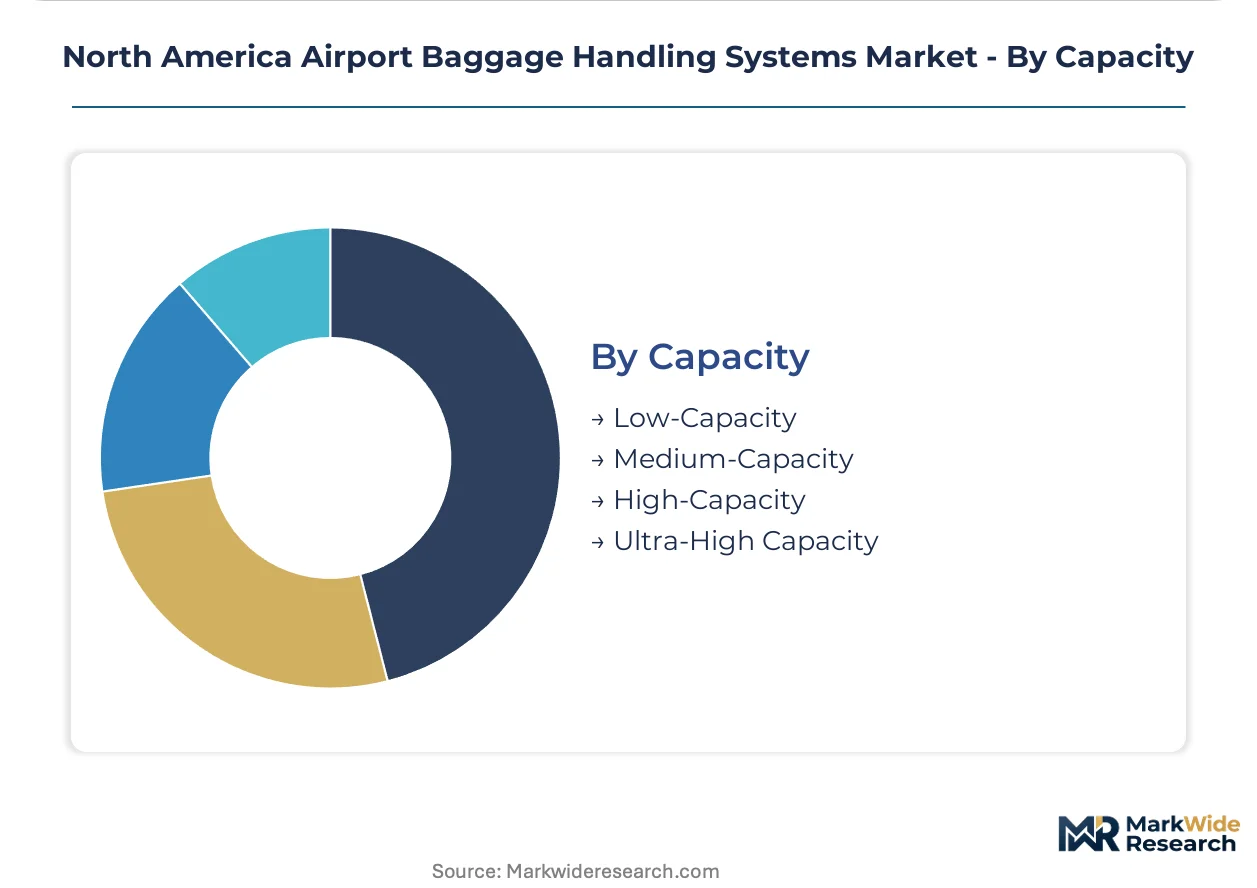
Capacity:
Throughput tier determines equipment redundancy requirements and integration complexity with TSA explosive detection systems.
- High-Capacity:Systems processing over 5,000 bags per hour require redundant sortation lanes and parallel screening architectures. Major southeastern hubs deploy this tier to accommodate connecting bank schedules.
- Ultra-High Capacity:Architectures exceeding 10,000 bags per hour incorporate multiple independent conveyor loops and automated storage buffers. Only Atlanta Hartsfield-Jackson operates at this tier among North American facilities.
- Medium-Capacity:2,000–5,000 bag per hour configurations serve focus-city operations and secondary hubs. These systems balance automation depth with retrofit feasibility in constrained terminal footprints.
- Low-Capacity:Sub-2,000 bag per hour installations at regional spoke airports prioritize capital efficiency over throughput redundancy. Hybrid barcode-RFID tracking systems address this tier at lower price points.
High-capacity systems anchor hub modernization investment. Medium-capacity is where regional airport upgrade activity concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airport authorities and network carriers concentrate procurement authority across three national markets, with fleet renewal programs and hub modernization driving specification divergence between high-throughput automation and cost-constrained retrofits.
United States
Atlanta Hartsfield-Jackson, Charlotte Douglas, and Miami International anchor demand through concurrent terminal expansions incorporating automated guided vehicle systems. FAA Part 139 certification mandates compel fire-resistant conveyor replacements before operational authorization renewal. The southeastern United States faces compressed compliance timelines as hub modernization accelerates.
Canada
Toronto Pearson and Vancouver International drive capital deployment toward RFID tracking infrastructure and explosive detection system integration. Transport Canada harmonizes baggage area safety standards with FAA operational benchmarks. Western Canada concentrates retrofit activity as Pacific gateway airports modernize connecting infrastructure.
Mexico
Mexico City International and Cancun International pursue medium-capacity system upgrades to accommodate passenger volume recovery. DGFT import regulations shape equipment procurement timelines for European-originated conveyor components. Central Mexico industrial corridors host emerging ground support equipment distributors expanding electrified fleet offerings.
North America Airport Baggage Handling Systems Market Competitive Landscape
Player mix skews toward European-headquartered system integrators with established North American install bases. Market structure concentrates around a handful of engineering-intensive vendors capable of large-scale automated deployments, with regional specialists capturing service contract unbundling opportunities. Two strategic archetypes dominate: full-service integrators with recurring maintenance revenue streams, and technology-focused specialists in high-speed sortation or apron automation. Competitive moves center on geographic expansion through local service subsidiaries and portfolio diversification into electric ground support equipment.
Among Dutch and German engineering groups, Vanderlande Industries B.V. and BEUMER Group GmbH & Co. KG exemplify the full-service integrator archetype with substantial North American footprint. Japanese industrial automation conglomerates occupy a distinct position through diversified material handling portfolios extending beyond airport-specific applications. These three anchors represent the engineering capability concentration that constrains rapid capacity scaling across major hub deployments.
| Leading Market Players |
|---|
| Vanderlande Industries B.V. |
| BEUMER Group GmbH & Co. KG |
| Daifuku Co., Ltd. |
| Smiths Group plc |
| Rapiscan Systems, Inc. |
| Alstef Group SAS |
| Fives SAS |
| G&S Airport Conveyor |
| Pteris Global Limited |
| Others |
Value Network & Pricing Analysis
Eighteen-month component lead times for European-originated sortation modules concentrate procurement leverage among Vanderlande, BEUMER, and Daifuku, compressing margin flexibility for regional integrators and amplifying cost-pass-through power at Tier 1 hub deployments.
Pricing Analysis
Cost-plus contracts with steel and copper indexation dominate large-scale conveyor deployments at southeastern US hubs. Price differentiation rests on FAA Part 139 certification grade and bundled after-sales uptime guarantees. Pricing pressure intensifies as commodity metal volatility compresses equipment margins and delays procurement decisions. Regional spoke airports exhibit highest price sensitivity, while network carriers prioritize performance guarantees over capital cost.
Supply Chain Analysis
Rotterdam port congestion and transatlantic freight bottlenecks constrain delivery of tilt-tray sorters and high-speed diverters from Dutch and German manufacturing centers. Component fabrication draws from Germany, the Netherlands, and Japan for precision mechatronics, with steel belting and fire-resistant PVC sourced from domestic US mills. Single-source vulnerability concentrates in specialized European engineering capabilities for ultra-high-capacity architectures. Distribution runs through integrator-direct channels to airport authorities and airline procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated guided vehicles threaten incumbent conveyor-centric revenue streams as Delta and American Airlines pilot electric apron automation, forcing legacy system integrators to defend their installed base against electrification substitutes.
For Market Incumbents: Fortify recurring service contract positions by unbundling long-term maintenance from capital sales and embedding performance-based uptime guarantees. Deepen captive supply of fire-resistant belting materials to offset commodity price volatility. Counter AGV substitution threats through hybrid conveyor-AGV integration offerings at Atlanta and Charlotte hub expansions. For New Entrants and Emerging Players: Anchor in regional airport retrofit cycles where hybrid barcode-RFID tracking systems address cost-constrained spoke facilities at lower price points than full hub deployments. Target medium-capacity tier installations processing 2,000–5,000 bags per hour for fastest procurement velocity. Pursue ground support equipment distributor partnerships to reach apron automation opportunities outside integrator-direct channels. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because European engineering concentration and mechatronics talent scarcity create durable moats around full-service integrators with North American install bases. Target technical service specialists capturing unbundled maintenance revenue from airline fleet renewal programs. Monitor FAA infrastructure grant prioritization announcements as inflection signals for capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Ground Support Equipment Transition | EPA emissions standards for baggage tractor fleets drive electrification procurement at Tier 1 facilities. |
| Service Contract Unbundling | Airlines separating maintenance agreements from capital purchases create recurring revenue for technical specialists. |
| Regional Airport Hybrid Retrofit | Cost-constrained spoke facilities present white-space for barcode-RFID tracking at lower price points. |
| Part 139 Compliance Upgrade | FAA fire-resistant material mandates compel conveyor replacement before operational authorization renewal. |
| AGV-Apron Integration Partnership | Delta and American pilot programs validate electric autonomous tractor architectures for tarmac congestion relief. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across airport authorities, airline procurement executives, ground handling service managers, and conveyor system maintenance directors. Primary fieldwork combined with secondary validation from FAA infrastructure grant disclosures, TSA screening technology procurement records, EPA ground support equipment emissions filings, and SEC 10-K equipment supplier reports. Bottom-up installation base analysis and top-down infrastructure spending triangulation anchored market sizing.
Across the analysis window, forecasts incorporated equipment type segmentation by throughput tier, tracking technology mix, and end-user procurement authority. Modeled dimensions spanned conveyor, AGV, and sortation system architectures alongside RFID and barcode scanning technology splits. CAGRs derived from infrastructure grant pipeline analysis and airline fleet renewal program timelines, with sensitivity testing against copper and steel price trajectory scenarios.
Decision-makers should treat outputs as directional under stable FAA funding authorization and commodity price band assumptions; material deviation would warrant model refresh. Specific risks include TSA screening technology refresh cycle delays, mechatronics labor shortage intensification, and tariff disruption to European component imports. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
Airport Information Systems Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Europe Smart Airport Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Middle-East and Africa Airport Ground Handling Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market