
 Global Aircraft Antenna Market | 2026-2036
Global Aircraft Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Antenna Market Foresight
North American defense electronics manufacturing is realigning around multi-band satellite communication requirements. Collins Aerospace leverages its avionics integration depth to sustain program wins across both commercial and military platforms. L3Harris Technologies, Inc. anchors its position through classified waveform expertise and hardened antenna architectures. Honeywell International Inc. competes aggressively on retrofit channel access, using its installed base of flight management systems to pull through antenna upgrades.
An aircraft antenna is a transducer that converts electrical signals to electromagnetic waves and vice versa, typically operating across VHF, UHF, L-band, Ku-band, and Ka-band frequencies with gain specifications ranging from 0 dBi to 30 dBi depending on mission profile. These devices enable critical functions including air-to-ground voice communication, GPS navigation precision approach, weather radar data reception, and satellite-based broadband connectivity for cockpit and cabin systems. Communication antennas occupy the largest revenue pool given inflight connectivity monetization, while electronically steered arrays represent the fastest-growing technology segment as flat-panel designs eliminate mechanical gimbal maintenance and reduce drag profiles. Military aviation end users command premium pricing due to hardened specifications and low-rate initial production volumes, though commercial aviation delivers scale economies that compress unit costs across generations.
FAA airworthiness directives and EASA certification standards jointly govern antenna electromagnetic compatibility, lightning strike protection, and ice accretion performance, creating dual-compliance burdens for suppliers serving transatlantic programs. The EU AI Act and emerging spectrum allocation frameworks from the FCC and Ofcom are reshaping connectivity architecture decisions, particularly for LEO constellation integration. Stakeholders must monitor regulatory divergence between FAA streamlined certification pathways and EASA's evolving CS-25 special conditions for novel antenna installations.
Market Dynamics
The transition from mechanically gimbaled to electronically steered antenna arrays is compressing retrofit timelines while elevating electromagnetic compatibility requirements across certification regimes.
Growth Catalysts
- FAA NextGen Mandates:Airworthiness directives for ADS-B Out and satellite-based augmentation systems are forcing narrow-body fleet upgrades, creating pull-through demand for multi-band communication suites.
- LEO Constellation Integration:Flat-panel antennas capable of tracking Starlink and OneWeb satellites are expanding into commercial aviation as carriers monetize passenger broadband.
- Ka-band Spectrum Allocation:FCC and Ofcom frequency assignments for high-throughput satellite services are enabling gigabit-class inflight connectivity that mechanical systems cannot support.
Market Restraints
- Gallium Nitride Substrate Costs:Wide-bandgap semiconductor substrates for high-power RF amplification face supply concentration in Japanese and Chinese foundries, creating input cost volatility.
- EASA CS-25 Special Conditions:Novel antenna installations on composite airframes trigger extended certification timelines that compress program margins for retrofit suppliers.
- Copper-Aluminum Interconnect Substitution:Lightweight cable assemblies using aluminum conductors introduce galvanic corrosion risks at antenna feed points, limiting adoption in salt-spray environments.
Strategic Opportunities
- Unmanned Aerial Systems:Beyond-visual-line-of-sight C-band and Ku-band datalinks for cargo drones represent underpenetrated demand in Australian and Canadian remote logistics corridors.
- EU AI Act Compliance:Automated beam-steering algorithms for interference mitigation qualify as high-risk AI systems, creating first-mover advantage for suppliers pre-certifying interpretability documentation.
- Software-Defined Apertures:Convergence of phased-array hardware with cognitive radio firmware enables single-antenna platforms to switch between SATCOM, radar, and electronic warfare modes.
Industry Challenges
- RF Systems Engineering Talent:Microwave circuit design and electromagnetic simulation expertise concentrates in defense contracting hubs, creating recruitment bottlenecks for commercial antenna developers.
- Legacy ARINC 429 Integration:New antenna systems must bridge to obsolete avionics buses on aging Boeing 737NG and Airbus A320ceo fleets, adding software validation burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Antenna Market |
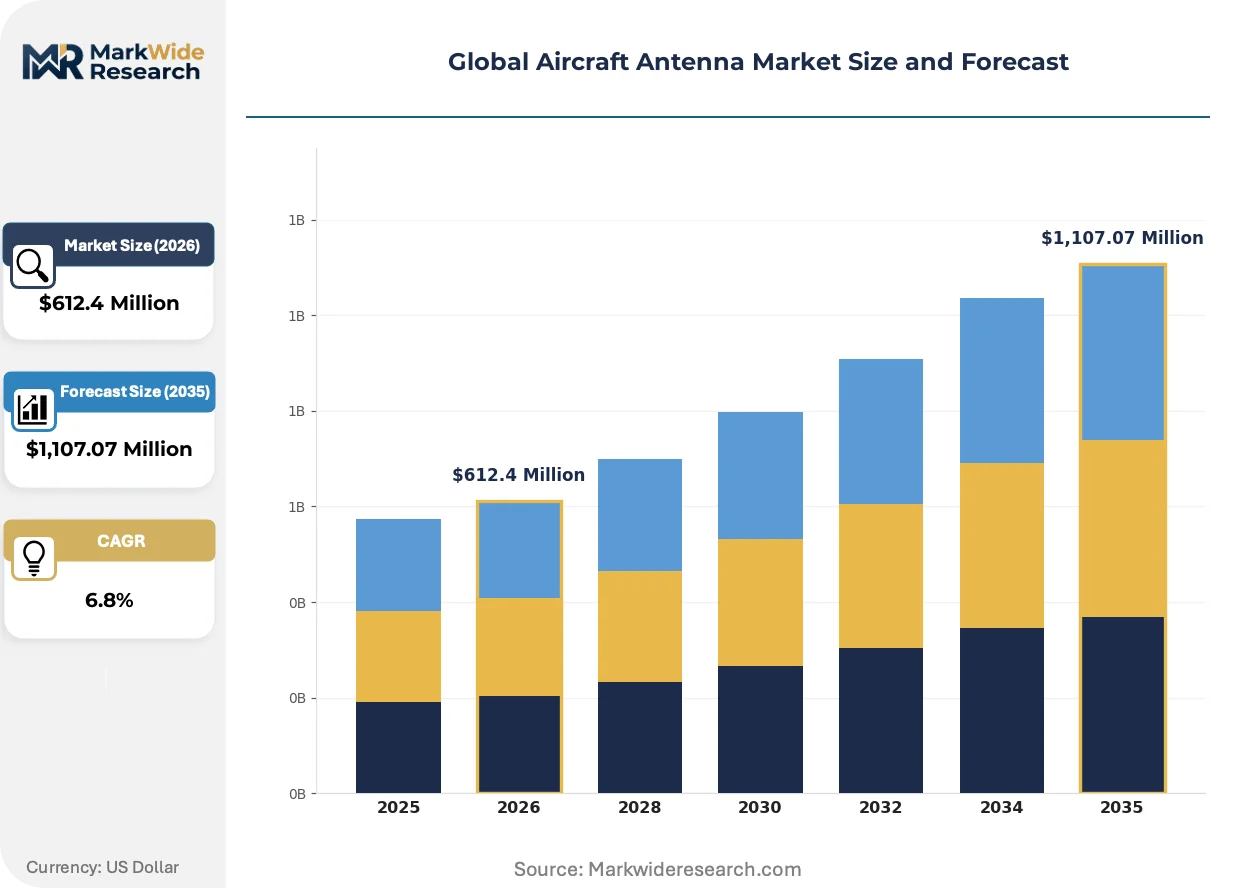
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communication Antennas, Navigation Antennas, Surveillance Antennas, Weather Antennas Technology: Active, Passive, Electronically Steered, Fixed End User: Commercial Aviation, Military Aviation, Private Aviation, Cargo Operators Installation: Integrated, Standalone, Avionics, Retrofit |
| Companies Covered | Collins Aerospace, Antcom Corporation, Honeywell International Inc., Sensor Systems Inc., RAMI Aviation, L3Harris Technologies, Inc., Cobham plc, Thales Group, The Boeing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Antenna Market Shifts & Advancements
Active electronically scanned arrays are displacing parabolic reflectors across both commercial and military platforms, while regulatory fragmentation around AI-enabled beam management is reshaping supplier certification strategies.
Metamaterial surface antenna technology (MSA-Tech) uses engineered electromagnetic structures to achieve directional gain without mechanical steering. Regional jet operators in the United States and turboprop fleets in Norway are piloting these ultra-thin installations for satellite connectivity. The technology is expanding into radome-constrained nose and tail positions where gimbal volume is unavailable.
EU AI Act classification of autonomous interference-nulling algorithms as high-risk AI systems imposes documentation and human-oversight requirements on European-registered aircraft. Manufacturers serving Lufthansa, Air France-KLM, and International Airlines Group must now embed explainability modules in beam-steering firmware. This regulatory divergence from FAA performance-based standards is forcing dual-track software development for transatlantic programs.
Airline procurement departments are consolidating antenna specifications into fleet-wide master service agreements rather than airframe-specific contracts. Maintenance, repair, and overhaul providers at Dubai Aerospace Enterprise and ST Engineering are capturing installation volume through long-term performance contracts. This channel shift is most visible in Asia-Pacific where lessors dominate narrow-body placement and demand standardized connectivity packages across mixed fleets.
Global Aircraft Antenna Market Segmentation
Aircraft antenna procurement hinges on mission-critical performance thresholds rather than unit economics alone. Fleet operators weigh electromagnetic compatibility, drag coefficients, and certification pathway complexity against connectivity monetization potential.
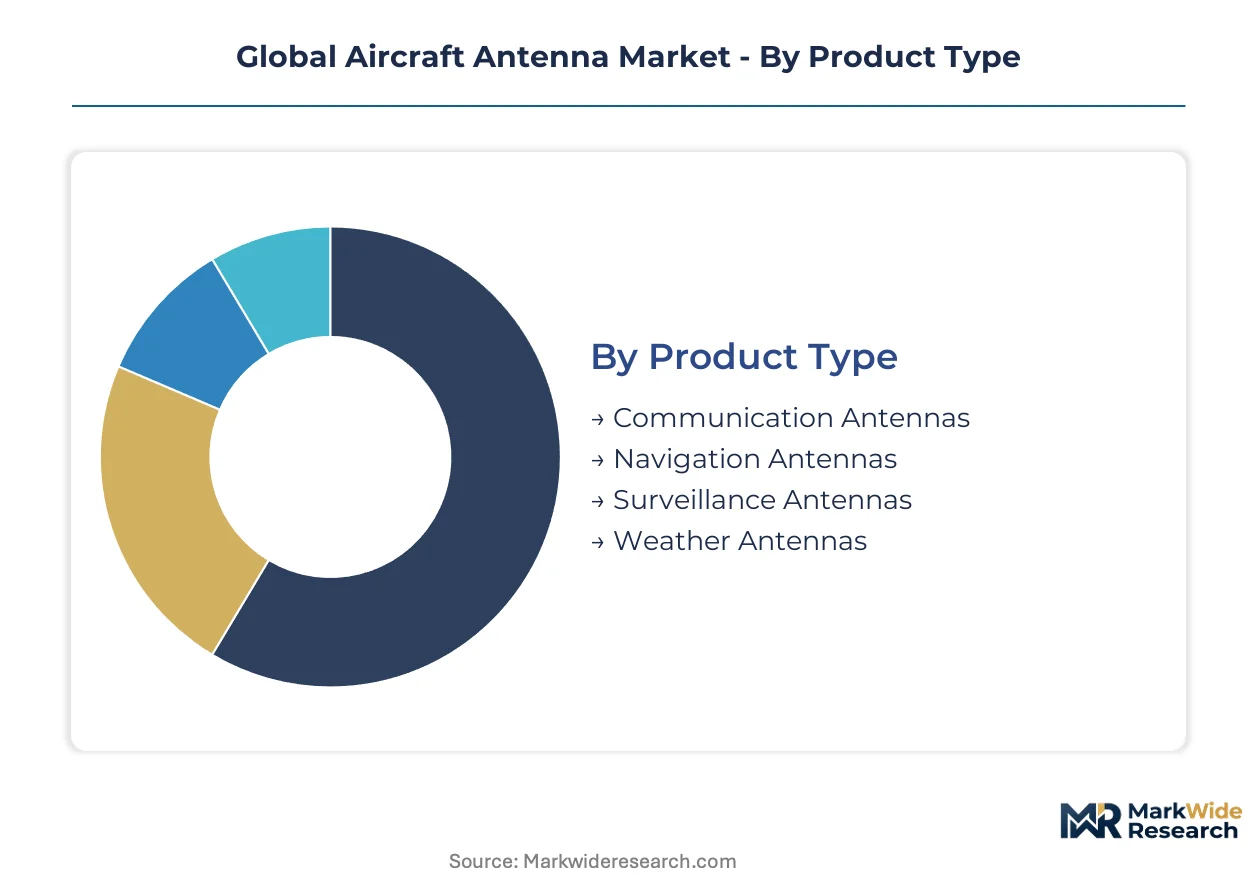
Product Type:
Airline procurement departments prioritize bandwidth scalability and regulatory compliance breadth when selecting antenna categories for fleet-wide deployment.
- Communication Antennas:Multi-band transducers operating across VHF through Ka-band enable air-to-ground voice, datalink, and satellite broadband. Demand concentrates in United States commercial aviation as carriers retrofit narrow-body fleets for passenger Wi-Fi monetization under FAA NextGen mandates.
- Navigation Antennas:GPS and GNSS precision-approach systems with anti-jam capabilities support required navigation performance approaches. Military aviation end users in Germany and France command hardened specifications and low-rate production premiums for encrypted waveform compatibility.
- Surveillance Antennas:ADS-B Out and TCAS transponder systems ensure airspace compliance across transatlantic corridors.
- Weather Antennas:X-band and C-band radar receivers provide precipitation and turbulence data for flight path optimization.
Volume sits with Communication Antennas; growth tilts toward Navigation Antennas as GPS-denied environment countermeasures proliferate.
Technology:
Retrofit channel economics and maintenance interval reduction drive technology selection for aging fleet upgrades.
- Electronically Steered:Phased-array architectures eliminate mechanical gimbals, reducing drag and maintenance burden. Flat-panel designs are gaining share fastest in commercial aviation as Starlink and OneWeb LEO integration demands rapid beam reacquisition.
- Active:Transmit-receive modules with embedded amplification enable high-power SATCOM links. Japanese and South Korean defense programs specify active arrays for electronic warfare resilience.
- Passive:Simple resonant structures without amplification suit legacy VHF communication and marker beacon reception.
- Fixed:Static installations for GPS and DME applications dominate turboprop and general aviation segments.
Active arrays command margin premiums; Electronically Steered systems are climbing the fastest as mechanical obsolescence accelerates.
End User:
Contract structure and certification liability exposure differentiate procurement behavior across operator categories.
- Commercial Aviation:Full-service carriers and low-cost operators demand standardized connectivity packages across mixed fleets. Lessors in Singapore and Ireland drive master service agreements that compress unit costs through volume commitments.
- Military Aviation:Classified waveform requirements and hardened environmental specifications sustain premium pricing. United States Department of Defense programs anchor demand for multi-function apertures combining communications, radar, and electronic attack.
- Private Aviation:Business jet operators prioritize radome integration aesthetics and installation speed.
- Cargo Operators:Long-haul freighter fleets require minimal passenger connectivity but demand robust SATCOM for crew welfare and operational control.
Commercial Aviation holds installed base dominance; Military Aviation exhibits steepest expansion trajectory as contested electromagnetic spectrum investments intensify.
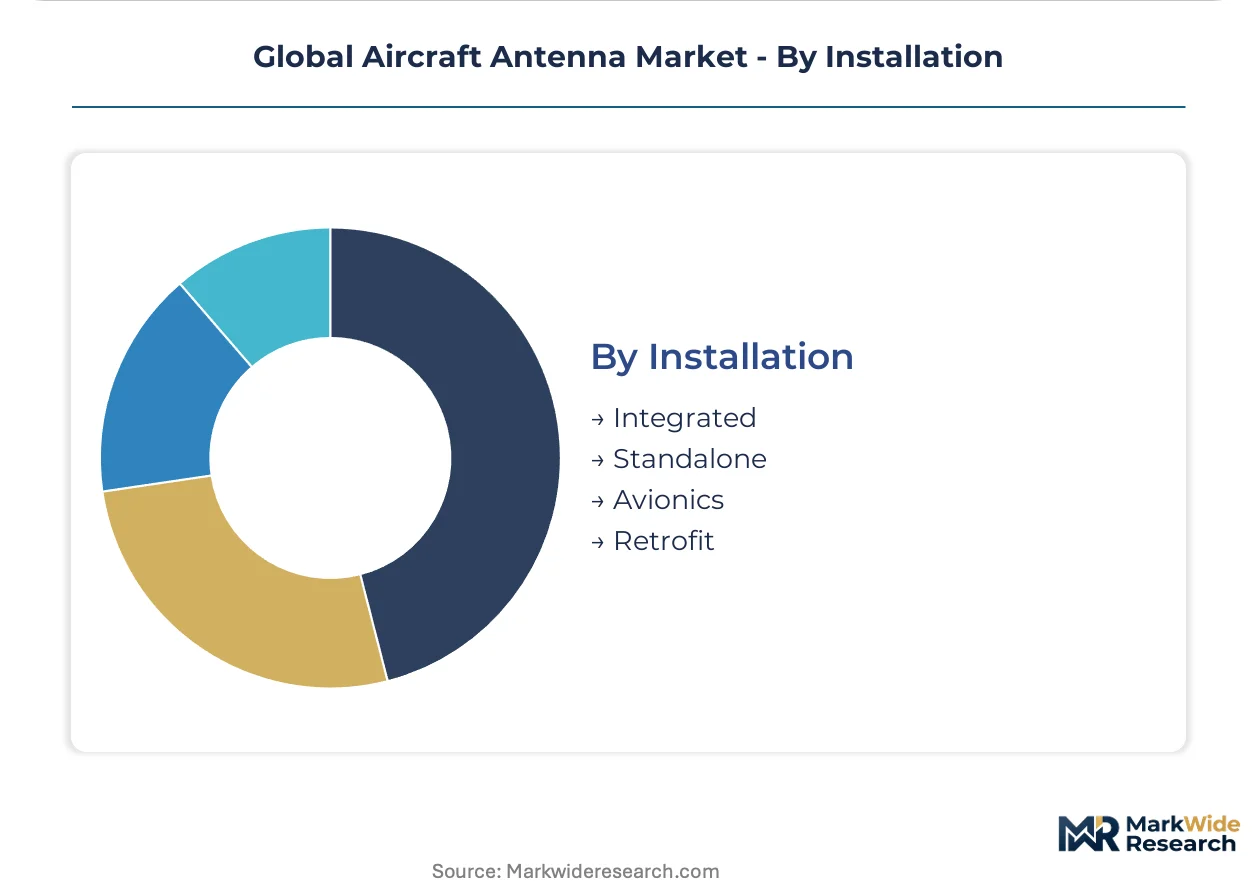
Installation:
Airframe modification scope and downtime cost determine installation pathway selection for fleet modernization programs.
- Retrofit:Aftermarket antenna replacement on Boeing 737NG and Airbus A320ceo fleets addresses FAA ADS-B mandates. MRO providers in United Arab Emirates and Turkey capture installation volume through long-term performance contracts.
- Integrated:Factory-installed antenna suites on new-generation airframes reduce electromagnetic interference risk through co-design with radome and airframe structures.
- Standalone:Discrete antenna pods for special mission aircraft allow rapid reconfiguration between ISR and transport roles.
- Avionics:Rack-mounted systems within the equipment bay serve backup communication and navigation redundancy requirements.
Retrofit commands near-term volume; Integrated installations are expanding most quickly as clean-sheet airframe programs multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium nitride substrate supply from Japanese foundries anchors antenna manufacturing economics across major aviation hubs. Defense modernization programs and commercial fleet retrofits are redrawing procurement geography.
United States
FAA NextGen mandates for ADS-B Out and satellite-based augmentation systems are forcing narrow-body fleet upgrades. The FCC's Ka-band spectrum allocations enable gigabit-class inflight connectivity. Dallas-Fort Worth and Seattle aerospace clusters concentrate antenna integration facilities serving both commercial carriers and Department of Defense programs.
Germany
Lufthansa Group's fleet-wide connectivity monetization drives demand for multi-band communication suites. EASA CS-25 special conditions for novel antenna installations on composite airframes extend certification timelines. Munich and Hamburg defense electronics hubs specialize in hardened specifications for encrypted waveform compatibility.
China
Domestic narrow-body production at COMAC creates integrated antenna demand for clean-sheet airframes. MIIT spectrum coordination for LEO constellation integration shapes connectivity architecture decisions. Xi'an and Chengdu aerospace clusters house phased-array development for military and civil applications.
Japan
Wide-bandgap semiconductor substrate supply concentration creates input cost leverage for antenna manufacturers. METI programs support metamaterial surface antenna technology pilots for regional connectivity. Nagoya and Tokyo aerospace corridors focus on transmit-receive module miniaturization for electronically steered arrays.
United Arab Emirates
Dubai Aerospace Enterprise and Emirates fleet lessors demand standardized connectivity packages across mixed narrow-body placements. GCAA alignment with FAA certification pathways streamlines transatlantic program approvals. Dubai and Abu Dhabi MRO hubs capture installation volume through long-term performance contracts.
Global Aircraft Antenna Market Competitive Landscape
Global majors compete with regional champions across avionics integration depth and classified waveform expertise. The supplier base consolidates around three tiers: diversified aerospace conglomerates with program-of-record relationships, defense-electronics specialists with hardened environmental capabilities, and connectivity-focused challengers leveraging LEO constellation partnerships. Strategic moves center on retrofit channel capture through flight management system installed bases and dual-use technology licensing for civil-military crossover.
Among US-based conglomerates, Collins Aerospace and L3Harris Technologies, Inc. exemplify contrasting archetypes. Collins Aerospace occupies a position emphasizing avionics integration breadth across commercial and military platforms. L3Harris Technologies, Inc. anchors the classified waveform tier through electromagnetic resilience specialization. Honeywell International Inc. represents the retrofit-channel vector, leveraging flight management system penetration to pull through antenna upgrades.
| Leading Market Players |
|---|
| Collins Aerospace |
| Antcom Corporation |
| Honeywell International Inc. |
| Sensor Systems Inc. |
| RAMI Aviation |
| L3Harris Technologies, Inc. |
| Cobham plc |
| Thales Group |
| The Boeing Company |
| Others |
Supply & Pricing Matrix
Defense-electronics conglomerates with program-of-record relationships anchor supply discipline through multi-year offtake commitments that insulate tier-two antenna manufacturers from spot-market volatility in wide-bandgap substrates. Their captive demand pools compress working-capital cycles for Japanese and South Korean foundries, translating into preferential pricing tiers for Collins Aerospace and L3Harris Technologies that regional challengers cannot replicate.
Pricing Analysis
Warranty and service-bundling arrangements separate Collins Aerospace's integrated avionics suites from unbundled component sales by smaller specialists. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity and electromagnetic compatibility testing depth. Cost compression in the retrofit channel is intensifying because MRO providers at Dubai Aerospace Enterprise and ST Engineering are consolidating procurement into fleet-wide master service agreements. Cargo operators and regional turboprop fleets exhibit highest price sensitivity, while military aviation end users in Germany and France accept premium positioning for hardened waveform specifications.
Supply Chain Analysis
Dual-sourcing qualification requirements mandated by Boeing and Airbus procurement teams force antenna suppliers to maintain qualified secondary relationships across Japanese, South Korean, and domestic US substrate foundries. Gallium nitride wafers, aluminum-nitride ceramic packages, and precision-machined radome composites constitute critical input dependencies. Single-source vulnerability concentrates in Japanese wide-bandgap semiconductor capacity, where METI industrial policy constrains export expansion. Distribution runs through avionics integrators and MRO networks rather than direct OEM supply, with long-term performance contracts capturing installation volume in Singapore and Ireland lessor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride substrate foundry capacity in Japan and South Korea operates at effective utilization ceilings, propping pricing discipline for active electronically scanned arrays across the projection horizon.
For Market Incumbents: Hedge against LEO constellation integration disruption by securing exclusive channel partnerships with Starlink and OneWeb certification programs before flat-panel architectures commoditize. Deepen backward integration into transmit-receive module assembly in Nagoya and Dallas-Fort Worth aerospace corridors to defend margin position against emerging metamaterial surface antenna technology specialists. Prioritize EASA CS-25 special conditions pre-certification to compress approval timelines for composite airframe installations. For New Entrants and Emerging Players: Capture unmanned aerial systems C-band and Ku-band datalink demand in Australian and Canadian remote logistics corridors where incumbent presence remains thin. Target software-defined aperture development for military-civil crossover applications, positioning cognitive radio firmware as the differentiable layer above commodity phased-array hardware. Pursue direct engagement with Dubai Aerospace Enterprise and Emirates fleet lessors through standardized connectivity package proposals that bypass avionics integrator markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor metamaterial surface antenna technology specialists with EASA pre-certification documentation and Norwegian regional airline pilot program traction. Five-to-ten-year viability hinges on LEO constellation interoperability and AI-enabled beam-steering interpretability module deployment. Monitor FCC and Ofcom spectrum allocation announcements as the inflection indicator for Ka-band terminal demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| LEO Constellation Certification Partnership | Starlink and OneWeb interoperability locks in retrofit channel access for electronically steered arrays. |
| Wide-Bandgap Substrate Backward Integration | In-house gallium nitride wafer sourcing from Japanese foundries reduces input cost volatility exposure. |
| EASA CS-25 Pre-Certification Investment | Early special conditions documentation compresses approval timelines for composite airframe antenna installations. |
| Software-Defined Aperture Development | Cognitive radio firmware enables single-platform switching between SATCOM, radar, and electronic warfare modes. |
| MRO Performance Contract Capture | Long-term agreements with Dubai Aerospace Enterprise and ST Engineering secure installation volume in lessor-dominated markets. |
Research Methodology
Document review covered FAA airworthiness directives, EASA certification standards, FCC spectrum allocation dockets, and METI industrial policy filings, complemented by interviews with avionics integration engineers, airline procurement directors, MRO operations managers, and defense electronics program officers. Secondary validation drew from customs trade data, SEC 10-K aerospace segment disclosures, and IHS Markit aircraft production databases. Bottom-up antenna shipment estimates triangulated against top-down fleet retrofit projections.
Unit shipment and revenue outputs calibrated across product type, technology architecture, end-user category, and installation pathway dimensions over the projection horizon. CAGRs derived from log-linear trend fitting against historical narrow-body fleet age profiles and mandate-driven retrofit acceleration patterns. Gallium nitride substrate pricing trajectories and LEO constellation launch schedules fed industry-specific sensitivity modules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FCC Ka-band auction timing and EASA AI Act enforcement interpretation for autonomous beam-steering algorithms. Deviation in gallium nitride foundry capacity expansion or LEO constellation constellation bankruptcy filings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Europe Air Traffic Management Market
Aircraft Navigation and Communication
Airborne Radars Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
Airspace and Procedure Design Market
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market
Aircraft Navigation and Communication
Air Traffic Management Market
Aircraft Navigation and Communication
Electronic Navigational Charts (ENC) Market
Aircraft Navigation and Communication
Airborne High Frequency Radio Market
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Aviation Weather Radar Market