
 Inertial Navigation System Market | 2026-2036
Inertial Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Inertial Navigation System Market Analysis
Aftermarket service revenue for IMU recalibration and sensor drift correction is fragmenting across regional maintenance hubs and original equipment channels. Honeywell International Inc. leverages its captive avionics service network to retain platform-level contracts. Northrop Grumman Corporation anchors its position through deep integration with U.S. defense procurement cycles. Safran Electronics & Defense competes by specializing in dual-use aerospace and naval retrofit programs.
An inertial navigation system computes position, orientation, and velocity by integrating accelerometer and gyroscope outputs without external references, typically achieving drift rates below one nautical mile per hour in marine-grade configurations. Fiber Optic Gyroscope platforms dominate high-precision defense and space budgets where mechanical resilience outweighs unit cost. Microelectromechanical Systems segments capture volume in commercial robotics and automotive driver-assistance modules where silicon batch fabrication collapses per-axis pricing. Defense applications sustain the largest absolute margin pools due to extended qualification cycles and sole-source contracting conventions.
The U.S. Department of Defense imposes MIL-STD-1553 and DO-178C software assurance standards that extend vendor qualification timelines and protect incumbent positions. The EU AI Act and CE marking requirements under the Machinery Directive shape product liability frameworks for autonomous navigation platforms sold across Europe. Stakeholders must monitor how export control reclassification of precision inertial sensors affects cross-border supply arrangements and foundry access.
Market Dynamics
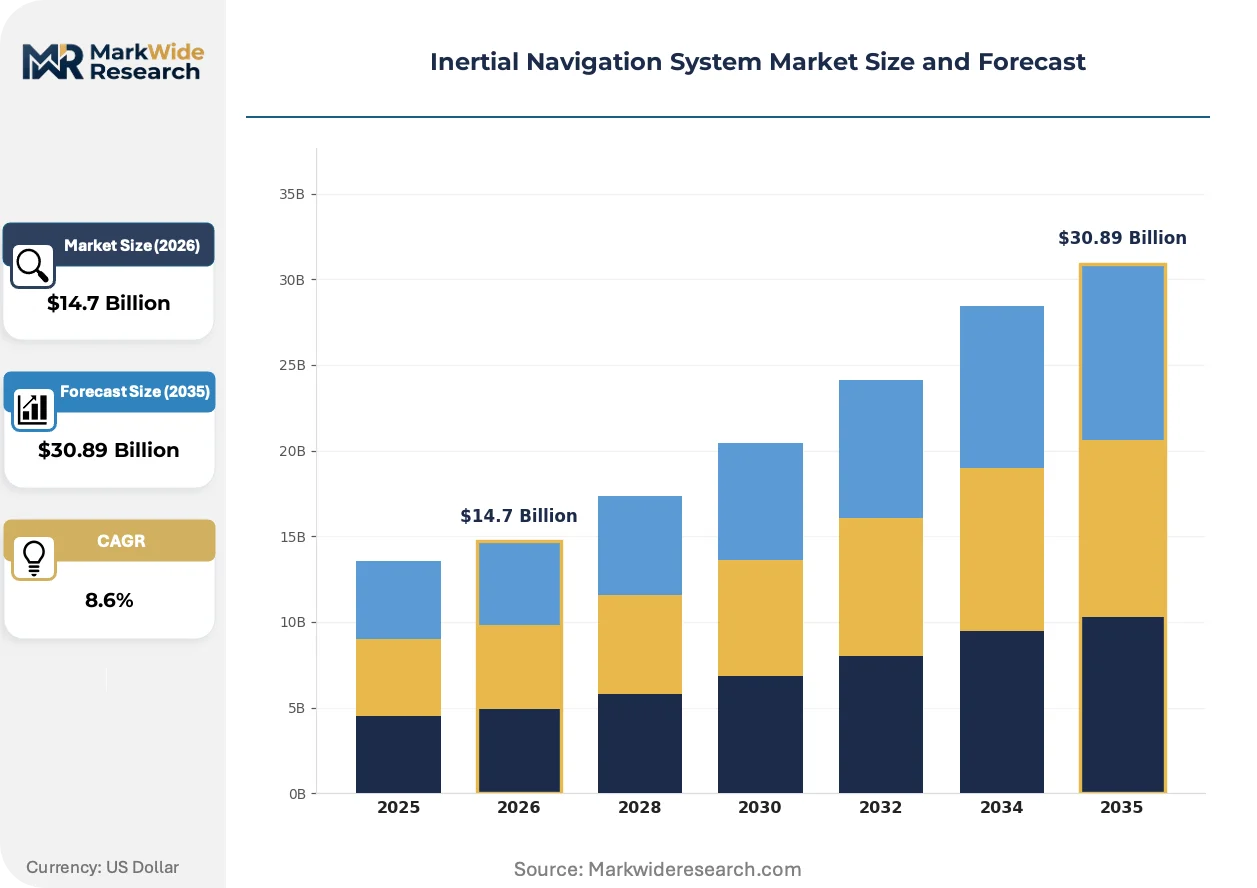
The Inertial Navigation System market is experiencing a fundamental restructuring as defense procurement cycles lengthen and commercial autonomous platforms demand silicon-grade cost structures previously reserved for consumer electronics. This tension between precision heritage and volume economics is forcing technology bifurcation.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:The European Commission's push for lower-power IMU designs is accelerating MEMS adoption in battery-constrained platforms.
- Autonomous underwater vehicle deployment:Deep-sea survey and subsea infrastructure inspection programs are creating sustained demand for marine-grade fiber optic gyroscope systems.
- Germany's aerospace corridor concentration:Munich and Hamburg's integrated supplier ecosystems are compressing development timelines for dual-use navigation platforms.
Market Restraints
- Precision sensor export controls:U.S. Department of Commerce reclassification of ring laser gyroscopes and advanced MEMS is restricting foundry access for non-domestic integrators.
- Extended qualification timelines:MIL-STD-1553 and DO-178C software assurance standards stretch vendor onboarding to 24-36 months, protecting incumbent positions.
- Raw material concentration:Specialty optical fiber and high-purity silicon substrate supply concentrates in East Asian foundries, creating single-source vulnerability.
Strategic Opportunities
- Retrofit naval modernization programs:European and Asia-Pacific fleets are upgrading legacy platforms with strapdown INS architectures, bypassing full platform replacement cycles.
- Automotive L3+ autonomy sensor fusion:High-volume driver-assistance modules are absorbing automotive-grade IMU output, creating secondary supply base scale effects.
- EU AI Act liability frameworks:CE marking requirements under the Machinery Directive are creating certification moats for compliant autonomous navigation platforms.
Industry Challenges
- Multi-physics simulation talent scarcity:The intersection of inertial sensor modeling, thermal drift compensation, and Kalman filter implementation requires specialized expertise concentrated in defense-adjacent labor pools.
- Legacy platform integration friction:Strapdown systems must interface with mechanical gimbal architectures through custom signal conditioning, extending field deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inertial Navigation System Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microelectromechanical Systems, Fiber Optic Gyroscopes, Ring Laser Gyroscopes, Accelerometers Technology: Inertial Measurement Unit, Kalman Filter, Strapdown System, Navigation Algorithms Application: Aerospace, Marine, Automotive, Defense End User: Commercial Aviation, Military, Space Exploration, Robotics |
| Companies Covered | Honeywell International Inc., Northrop Grumman Corporation, Safran Electronics & Defense, Thales Group, RTX Corporation, Gladiator Technologies Inc., Lord Microstrain, VectorNav Technologies LLC, Inertial Labs Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inertial Navigation System Market Emerging Trajectories
Silicon photonics and advanced packaging are converging to collapse the cost-precision tradeoff that historically segmented defense and commercial inertial navigation markets. This technological compression is enabling new entrant strategies previously blocked by capital barriers.
Photonic integrated circuit technology is digitizing inertial sensing by replacing discrete fiber optic coils with lithographically defined waveguide structures on semiconductor substrates. Defense primes and space integrators are piloting these platforms for satellite attitude determination where radiation tolerance and mechanical resilience outweigh unit cost. The structural consequence is digitizing the supply chain by collapsing batch fabrication economics previously reserved for telecom transceivers into navigation-grade sensor production.
The EU AI Act's risk-based classification system is reshaping product liability frameworks for autonomous navigation platforms sold across Europe. Manufacturers must now document algorithmic decision pathways for high-risk applications including unmanned maritime and aerial systems. Naval retrofit programs and autonomous ferry deployments in Scandinavian waters are most affected, with integrators accelerating formal verification workflows to maintain CE marking eligibility.
Platform integrators are unbundling after-sales service contracts from hardware procurement, creating standalone revenue streams for calibration and drift correction. This shift is compressing traditional OEM service margins while enabling third-party maintenance hubs to capture regional contracts. The pattern is most visible in Germany's aerospace corridor, where independent avionics shops are winning platform-level service agreements previously held by captive manufacturer networks.
Inertial Navigation System Market Segmentation
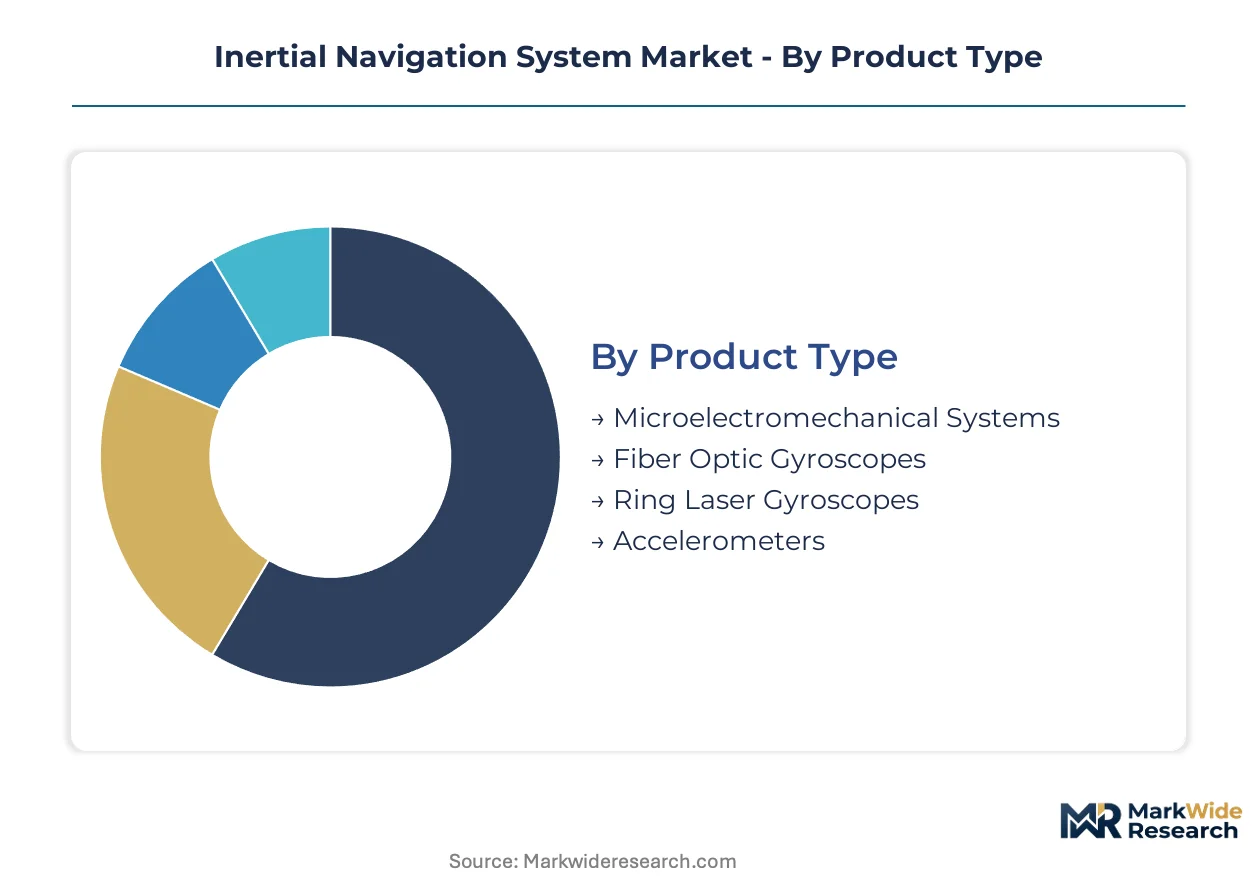
Inertial navigation markets fragment sharply across precision grades and cost structures, with defense-grade fiber optic platforms commanding margins above 60% while automotive MEMS units compete on sub-dollar per-axis pricing. Understanding these segment boundaries reveals where technology spillover occurs and where qualification moats protect incumbent positions.
Product Type:
Mature high-precision platforms anchor defense procurement budgets while emerging silicon architectures capture volume in battery-constrained autonomous systems.
- Microelectromechanical Systems:Silicon batch fabrication collapses per-axis pricing to consumer-electronics levels. Automotive L3+ autonomy modules and warehouse robotics in Germany's aerospace corridor absorb the highest shipment volumes, though drift rates limit deployment to GPS-aided architectures.
- Fiber Optic Gyroscopes:Coiled optical fiber sensing coils achieve mechanical resilience unmatched by solid-state alternatives. Deep-sea survey programs and satellite attitude determination sustain demand despite unit costs exceeding MEMS by orders of magnitude.
- Ring Laser Gyroscopes:Cavity-based optical interference delivers the lowest drift rates available in production systems. U.S. Department of Commerce export controls restrict foundry access for non-domestic integrators.
- Accelerometers:Piezoelectric and capacitive sensing elements measure linear acceleration across all precision tiers. Strapdown INS architectures integrate these with gyroscopic outputs for complete six-degree-of-freedom navigation.
Fiber optic platforms handle the majority of defense throughput; MEMS is gaining share fastest in commercial autonomy.
Technology:
Cost tier separation runs from discrete component stacks through fully integrated algorithmic platforms, with integration depth determining qualification burden and margin structure.
- Inertial Measurement Unit:Packaged accelerometer and gyroscope arrays output raw sensor data requiring external fusion. Marine-grade configurations achieve drift rates below one nautical mile per hour.
- Kalman Filter:Recursive estimation algorithms fuse inertial outputs with external references to bound error growth. The EU AI Act's documentation requirements for high-risk autonomous systems extend verification timelines for implementations in unmanned maritime platforms.
- Strapdown System:Solid-state architectures eliminate mechanical gimbals through computational coordinate transformation. European and Asia-Pacific naval modernization programs favor these for retrofit upgrades bypassing full platform replacement.
- Navigation Algorithms:Software implementations determine how sensor fusion responds to GPS denial or multipath interference. DO-178C assurance standards stretch vendor qualification to 24-36 months for aerospace deployments.
Strapdown systems command the dominant installed base; Kalman Filter implementations are climbing the fastest as autonomy complexity increases.
Application:
Customer type bifurcation separates sole-source defense contracting from price-sensitive commercial procurement, with dual-use platforms attempting to bridge both.
- Aerospace:Flight control and navigation systems demand MIL-STD-1553 bus compatibility and extended temperature operation. Munich and Hamburg supplier ecosystems compress development timelines for integrated avionics platforms.
- Marine:Subsea positioning and surface vessel navigation tolerate higher drift rates than aerial applications. Autonomous underwater vehicle deployment for infrastructure inspection drives marine-grade fiber optic adoption.
- Automotive:Driver-assistance modules absorb automotive-grade IMU output in sensor fusion architectures with lidar and camera stacks. Silicon photonics convergence threatens to collapse cost-precision tradeoffs historically segmenting this tier.
- Defense:Extended qualification cycles and sole-source contracting conventions sustain the largest absolute margin pools. Honeywell's captive avionics service network and Northrop Grumman's procurement cycle integration protect incumbent positions.
Defense applications capture the dominant revenue share; automotive is expanding most quickly on unit volume.
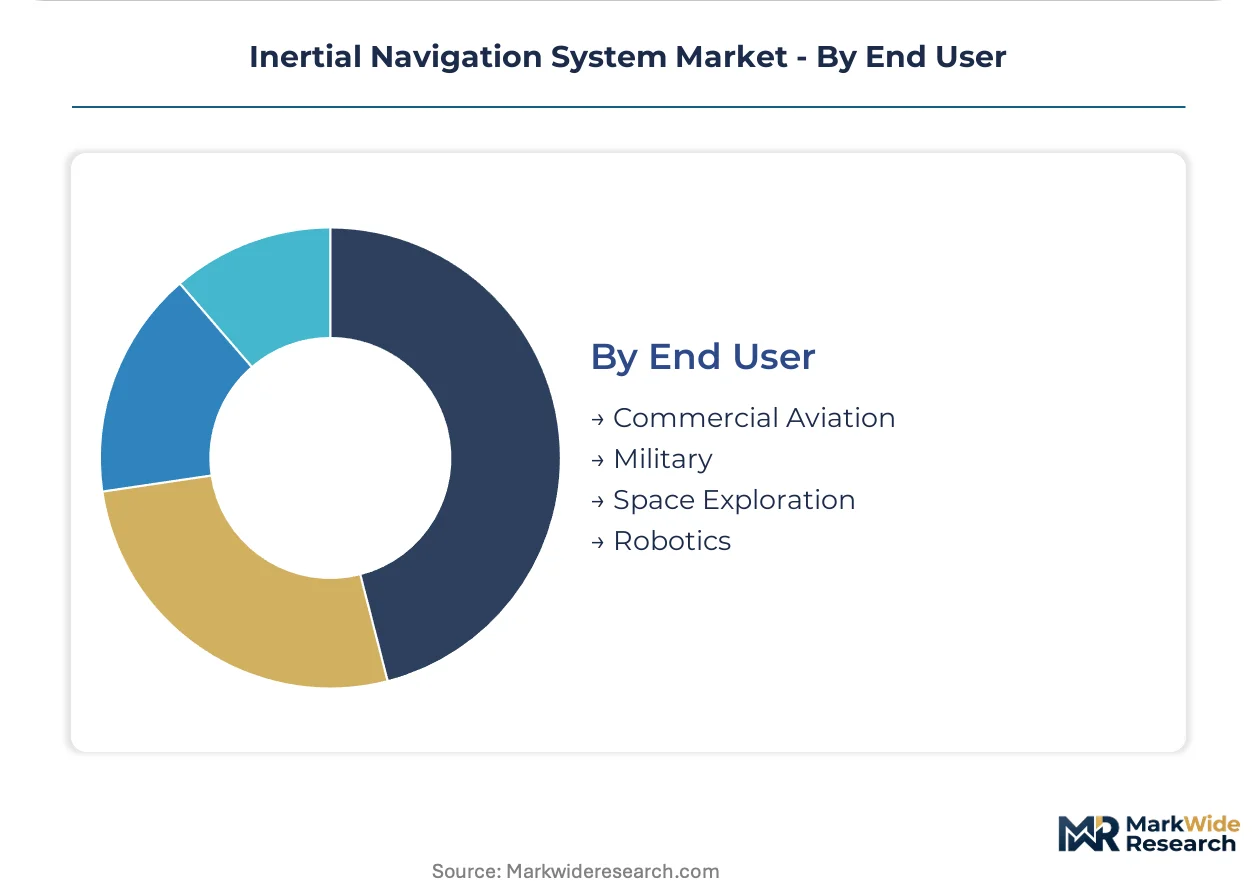
End User:
Volume concentration clusters in aviation maintenance hubs while emerging demand fragments across robotics integrators and space launch providers.
- Commercial Aviation:Aftermarket recalibration and sensor drift correction fragment across regional maintenance hubs and OEM channels. Independent German avionics shops are winning platform-level service agreements previously held by manufacturer networks.
- Military:Procurement cycles lengthen as platforms extend service life through mid-life upgrades. Safran Electronics & Defense specializes in dual-use aerospace and naval retrofit programs to capture this spend.
- Space Exploration:Radiation tolerance and mechanical resilience outweigh unit cost for satellite attitude determination. Photonic integrated circuit pilots aim to digitize supply chains through lithographic waveguide fabrication.
- Robotics:Warehouse automation and autonomous ground vehicles demand silicon-grade cost structures. Multi-physics simulation talent scarcity constrains development velocity for Kalman filter implementation at this tier.
Commercial aviation maintains the largest installed base; robotics is the fastest mover on share as autonomy deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement in the United States tolerates decade-long qualification cycles and sole-source premiums, while automotive buyers in Germany and robotics integrators in Japan enforce silicon-grade cost discipline. This elasticity gap shapes where fiber optic gyroscopes concentrate versus where MEMS volume scales fastest.
United States
The Department of Defense sustains demand for ring laser gyroscopes through extended platform life cycles and mid-life upgrade programs. MIL-STD-1553 and DO-178C software assurance standards stretch vendor onboarding to 24-36 months, protecting incumbent positions. Defense primes cluster around Washington D.C. and Southern California aerospace corridors, anchoring high-precision navigation procurement.
Germany
The EU Green Deal accelerates MEMS adoption for battery-constrained autonomous platforms across automotive and robotics applications. CE marking requirements under the Machinery Directive and EU AI Act risk classifications reshape product liability frameworks for unmanned systems. Munich and Hamburg's integrated supplier ecosystems compress development timelines for dual-use navigation platforms serving both civil aviation and naval retrofit programs.
China
Domestic foundry capacity for specialty optical fiber and high-purity silicon substrates reduces import dependency for precision inertial sensors. GB standards and MIIT industrial policy guide localization targets for satellite attitude determination and autonomous underwater vehicle programs. Yangtze River Delta manufacturing clusters scale MEMS output for warehouse robotics and consumer drone applications.
Japan
METI technology roadmaps prioritize photonic integrated circuit development for radiation-tolerant satellite navigation. JIS standards govern precision grades for industrial automation and maritime applications. Kanto and Kansai industrial corridors concentrate multi-physics simulation talent for Kalman filter implementation in robotics and autonomous ground vehicle programs.
United Kingdom
Dual-use aerospace and naval retrofit programs sustain demand for strapdown INS architectures bypassing full platform replacement. Ministry of Defence procurement cycles favor deep integration with established defense primes. Southeast England and Midlands engineering clusters specialize in aftermarket recalibration services fragmenting across regional maintenance hubs.
Inertial Navigation System Market Vendor Landscape
Defense-heritage primes and silicon-scale specialists split the market along the precision-versus-cost frontier. Consolidation concentrates around extended qualification cycles and captive service networks, while fragmentation accelerates at the MEMS tier where batch fabrication lowers entry barriers. Two archetypes dominate: integrated platform providers leveraging procurement cycle lock-in, and component specialists capturing retrofit and aftermarket service contracts. Competitive moves center on vertical integration into foundry access and unbundling of after-sales calibration revenue from hardware procurement.
Within the integrated platform tier, Honeywell International Inc. and Northrop Grumman Corporation exemplify archetypes built around defense procurement cycle alignment and captive avionics service networks. Safran Electronics & Defense occupies a position bridging dual-use aerospace and naval retrofit specializations. These three anchors represent how qualification moats and sole-source contracting conventions protect margin structures against silicon-grade cost pressure from below.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Northrop Grumman Corporation |
| Safran Electronics & Defense |
| Thales Group |
| RTX Corporation |
| Gladiator Technologies Inc. |
| Lord Microstrain |
| VectorNav Technologies LLC |
| Inertial Labs Inc. |
| Others |
Supply Flow & Price Mechanics
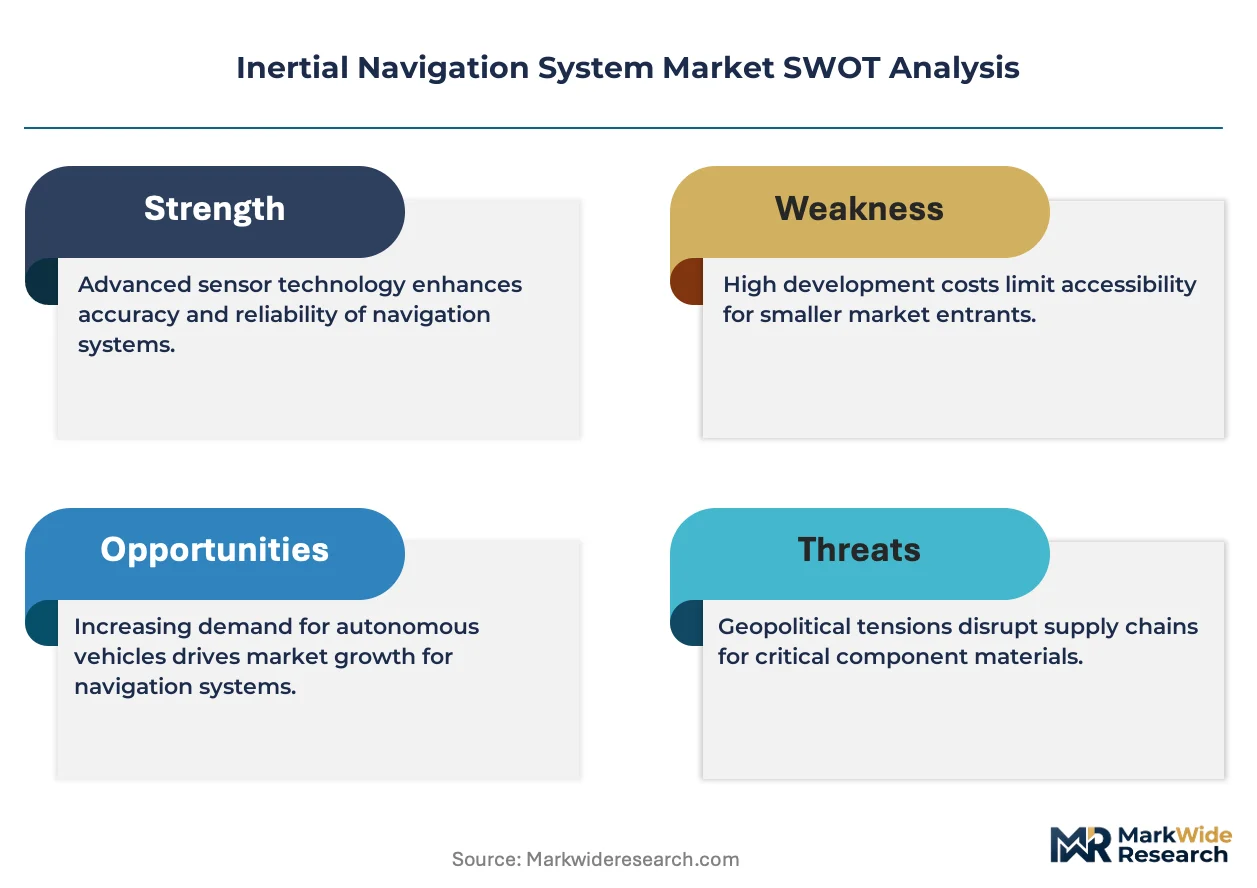
Export control reclassification of precision inertial sensors determines both pricing tier spreads and supply chain shape. U.S. Department of Commerce restrictions on ring laser gyroscopes and advanced MEMS compress foundry access for non-domestic integrators, widening the cost gap between defense-grade platforms and commercial alternatives while forcing procurement patterns toward qualified incumbent channels.
Pricing Analysis
After-sales service revenue drives lifetime value across fiber optic and MEMS platforms alike. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-1553 qualified defense systems from automotive-grade modules and consumer drone components. Price differentiation hinges on certification grade and volume scale, with drift rate specifications and software assurance documentation commanding substantial premiums. Cost compression in silicon photonics segments is intensifying because photonic integrated circuit pilots threaten to collapse batch fabrication economics previously reserved for telecom transceivers. Automotive L3+ autonomy buyers exhibit the highest price sensitivity, while sole-source defense procurement tolerates decade-long qualification premiums.
Supply Chain Analysis
U.S. Department of Commerce export controls on precision inertial sensors limit cross-border flows of ring laser gyroscopes and advanced MEMS to qualified domestic integrators. Specialty optical fiber and high-purity silicon substrate supply concentrates in China, South Korea, and Taiwan, creating single-source vulnerability for European and North American defense primes. Raw material dependencies include coiled sensing fiber, lithographic-grade silicon wafers, and rare-earth doped optical components. Tariff exposure runs through East Asian foundry networks serving both defense and commercial tiers. Distribution runs through captive OEM service networks for aerospace platforms and independent regional maintenance hubs for aftermarket recalibration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent defense primes face substitution pressure from silicon photonics convergence threatening to collapse the cost-precision tradeoff that historically protected their margin structures. Navigation-grade sensor production must now compete with lithographically defined waveguide architectures digitizing supply chains.
For Market Incumbents: Pre-empt silicon photonics displacement by accelerating photonic integrated circuit pilots for satellite attitude determination and radiation-tolerant applications. Lock in sole-source positions through extended qualification cycle alignment with U.S. Department of Defense procurement timelines. Backward integration into specialty optical fiber supply reduces East Asian foundry dependency. Captive avionics service networks must unbundle calibration revenue streams before independent German maintenance hubs capture platform-level contracts.
For New Entrants and Emerging Players: Mid-market automotive L3+ autonomy modules in Germany's aerospace corridor represent the most penetrable entry point for MEMS-based sensor fusion platforms. Warehouse robotics integrators in Japan's Kanto industrial corridor absorb silicon-grade cost structures previously reserved for consumer electronics. CE marking requirements under the EU AI Act create certification moats for compliant autonomous navigation platforms. Target sensor fusion partnerships with lidar and camera stack providers rather than direct OEM qualification.
For Investors and Strategic Acquirers: EU AI Act risk-based classification reshapes the acquisition landscape for autonomous navigation platform developers. Five-to-ten year viability favors component specialists with photonic integrated circuit roadmaps and aftermarket service contract portfolios. Acquisition target archetype: dual-use aerospace and naval retrofit specialists bridging defense procurement cycles and commercial silicon economics. Watch for reclassification of precision inertial sensors under expanded export control schedules as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Development | Digitizes inertial sensing through lithographic waveguide fabrication on semiconductor substrates. |
| Aftermarket Service Unbundling | Creates standalone calibration revenue streams independent from hardware procurement cycles. |
| Dual-Use Platform Certification | Captures naval retrofit spend through CE marking compliance under EU AI Act frameworks. |
| Specialty Fiber Supply Integration | Reduces single-source vulnerability to East Asian coiled sensing fiber concentration. |
| Kalman Filter Verification Investment | Accelerates formal verification workflows for unmanned maritime platform deployments. |
Methodological Framework
A standing panel of defense procurement officers, avionics platform engineers, MEMS foundry operations managers, and autonomous systems integration specialists provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against U.S. Department of Defense budget submissions, EU AI Act regulatory filings, MIIT industrial policy documents, and semiconductor trade flow databases. Bottom-up shipment modeling across precision grades triangulated against top-down defense procurement budget allocations.
Scenario bracketing anchored projections across technology diffusion curves for silicon photonics and export control regime stringency variations. Segmentation dimensions modeled include product type, precision grade, application vertical, end-user category, and regional regulatory cluster across the analysis window. CAGRs derived from unit shipment trajectories weighted by average selling price tier. Industry-specific forecast inputs encompassed autonomous underwater vehicle deployment pipelines and automotive L3+ autonomy regulatory approval timelines.
Macroeconomic conditions sit as an overlay; deviation in defense procurement cycle duration or East Asian foundry capacity expansion would shift the trajectory. Forecasts reflect documented assumptions regarding export control stability and photonic integrated circuit yield maturation. Material shifts in U.S. Department of Commerce precision sensor reclassification or EU AI Act liability framework enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Space Situational Awareness (SSA) Systems Market
Communication Navigation & Surveillance
Military Antenna Market
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
High-End Inertial Systems Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
Flight Tracking System Market
Communication Navigation & Surveillance
Drone Transponders Market
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market