
 Global Aviation Mapping Software Market | 2026-2036
Global Aviation Mapping Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aviation Mapping Software Market Foresight
The capability gap between full-stack avionics OEMs and specialized software vendors is collapsing as cloud-native architectures reduce entry barriers. Boeing sustains enormous R&D budgets across integrated flight deck ecosystems. Garmin differentiates through portable and embedded navigation systems for general aviation. Esri anchors its position by extending geospatial intelligence platforms into airspace visualization tools.
Aviation mapping software comprises digital systems that process geospatial data, aeronautical information, and real-time sensor feeds to generate navigable terrain models, obstacle databases, and dynamic airspace representations with sub-meter positional accuracy for flight crews and ground controllers. Its primary purpose is to enhance situational awareness, optimize routing efficiency, and prevent controlled flight into terrain incidents across civilian and military operations. Cloud-based deployment is capturing the fastest expansion as airlines seek reduced infrastructure overhead and seamless chart updates. Navigation systems and flight planning solutions occupy the deepest margin pools due to recurring data subscription models and mandatory regulatory refresh cycles. Terrain awareness applications lead in military procurement intensity driven by low-level mission profiles and electronic warfare requirements.
The FAA mandates compliance with DO-178C software assurance standards and NextGen performance requirements, while EASA enforces CE-marked avionics certification under EU regulation 965/2012 for air operations. China's CAAC and Japan's JCAB impose parallel type certification protocols that force vendors to maintain multiple software baselines. Stakeholders must monitor how emerging AI-driven predictive routing algorithms interface with existing human-in-the-loop certification frameworks before committing development roadmaps.
Market Dynamics
Cloud-native architectures are collapsing the capability gap between full-stack avionics OEMs and specialized software vendors, redistributing competitive advantage toward modular, API-first platforms that integrate across heterogeneous fleet environments.
Growth Catalysts
- FAA NextGen Mandate:Performance-based navigation requirements are forcing legacy fleet retrofits across US commercial carriers, creating sustained procurement cycles for certified mapping solutions.
- Low-Altitude Economy:Urban air mobility corridors and drone delivery networks in China, Germany, and the United Arab Emirates are generating demand for high-resolution 4D airspace modeling.
- Synthetic Vision Systems:Real-time sensor fusion combining LiDAR, radar, and optical feeds is penetrating military transport and search-rescue rotary platforms.
Market Restraints
- DO-178C Certification Burden:Software assurance compliance for Level A criticality consumes 18-24 month development timelines, freezing agile release cycles.
- Geopolitical Data Fragmentation:China's GB standards and Russia's GLONASS augmentation requirements force vendors to maintain incompatible terrain database baselines.
- Specialized Talent Scarcity:Aerospace software engineers with dual expertise in geospatial informatics and safety-critical systems concentrate in Toulouse, Seattle, and Tel Aviv.
Strategic Opportunities
- India Defense Modernization:The country's indigenous light combat aircraft and helicopter programs lack domestic mapping software suppliers, opening import substitution pathways.
- Predictive Routing AI:Machine learning algorithms optimizing fuel burn through dynamic wind modeling are outrunning current certification frameworks, creating first-mover windows.
- Direct-to-Device Distribution:Electronic flight bag applications are bypassing traditional avionics integrators, letting pilots subscribe to chart services independently.
Industry Challenges
- Human-in-the-Loop Certification:Regulators have not established approval pathways for autonomous routing recommendations, forcing vendors to maintain manual override architectures.
- Legacy Fleet Integration:ARINC 429 and MIL-STD-1553 data buses on aging Boeing 737NG and Airbus A320ceo fleets resist modern Ethernet-based mapping overlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aviation Mapping Software Market |
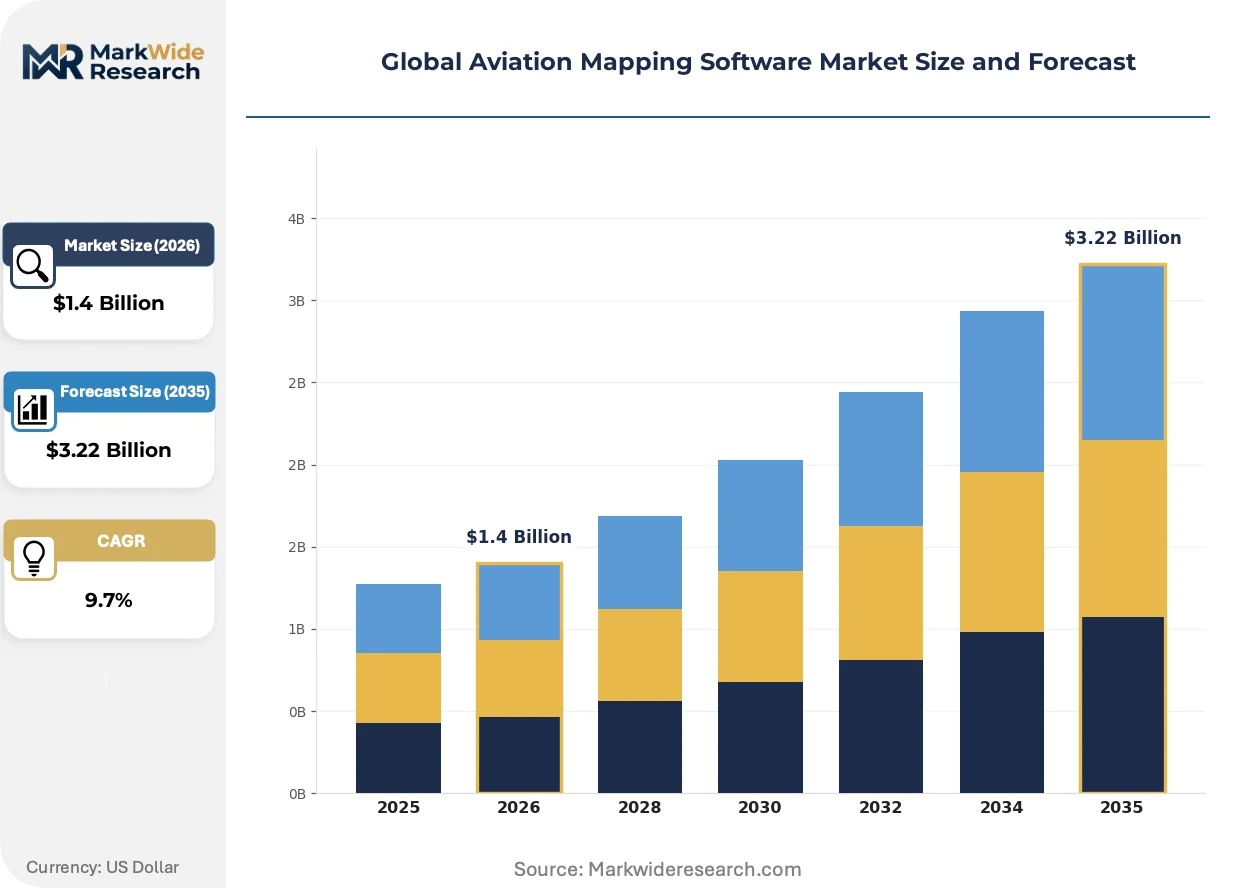
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Hosted Solution Type: Navigation Systems, Flight Planning, Terrain Awareness, Weather Tracking, Airspace Management Application: Commercial Aviation, Military Operations, General Aviation, Unmanned Aerial Vehicles, Search & Rescue End User: Airlines, Defense Agencies, Flight Schools, Cargo Operators, Air Traffic Controllers |
| Companies Covered | Boeing, Airbus, Garmin, Jeppesen, L3Harris Technologies, Honeywell International, Raytheon Technologies, Esri, Trimble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aviation Mapping Software Market Shifts & Advancements
Digital twin architectures are redefining how terrain databases propagate from centralized servers to edge avionics, compressing update cycles from quarterly to near-real-time while fragmenting vendor control over data pipelines.
Digital elevation modeling is bifurcating between photogrammetric point clouds for commercial aviation and interferometric SAR for all-weather military operations. Low-cost carriers are adopting satellite-derived terrain models to avoid proprietary sensor hardware. This compression is eroding margins for traditional survey equipment manufacturers while expanding addressable market for pure-play geospatial data vendors.
Europe's Single European Sky ATM Research program is mandating interoperable flight trajectory exchanges across 27 national air navigation service providers. Industrial consequence includes forced standardization of aeronautical information management protocols. Business aviation and cargo operators face the steepest compliance costs as they lack the scale to amortize system upgrades across large fleets.
Airline procurement departments are unbundling chart data subscriptions from integrated flight deck contracts. Low-cost subsidiaries of full-service carriers are piloting direct relationships with specialized mapping vendors. This disintermediation is most visible in Southeast Asia, where rapid fleet expansion and price-sensitive operations favor modular procurement over OEM-locked ecosystems.
Global Aviation Mapping Software Market Segmentation
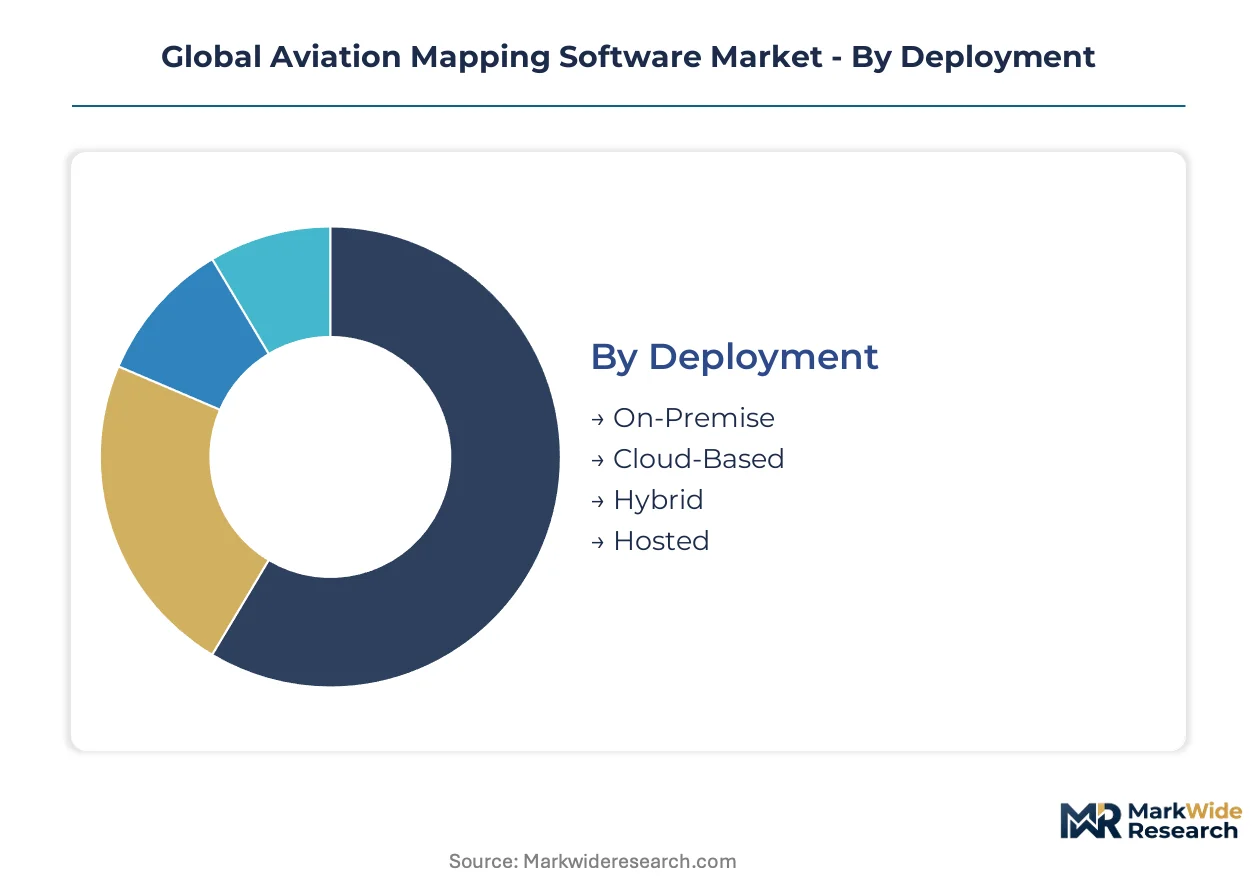
Aviation mapping software vendors must navigate four distinct segmentation axes simultaneously. Deployment choices determine infrastructure economics. Solution types dictate certification complexity. Application scope shapes data resolution requirements. End-user profiles govern procurement authority and budget cycles.
Deployment:
Margin pools concentrate in recurring subscription architectures rather than perpetual license models, rewarding vendors who capture long-term data refresh relationships.
- Cloud-Based:Multi-tenant SaaS architectures deliver automated chart updates without on-ground server maintenance. United States major carriers and European low-cost operators are migrating legacy electronic flight bag installations to cloud-native platforms to reduce IT overhead and accelerate regulatory compliance patches.
- Hybrid:Edge-cached terrain databases sync with centralized servers during ground connectivity windows, preserving operational continuity across oceanic routes. This architecture dominates long-haul fleet retrofits where intermittent satellite bandwidth precludes pure cloud dependency.
- On-Premise:Air-gapped installations serve defense agencies with classified mission profiles.
- Hosted:Single-tenant managed deployments address mid-size cargo operators lacking internal IT aviation expertise.
Cloud-based holds installed capacity. Hybrid is rotating up the share rankings.
Solution Type:
Revenue concentration follows mandatory recertification cycles rather than discretionary upgrade appetites.
- Navigation Systems:Integrated flight management computers process georeferenced waypoint databases with RTK-GNSS augmentation for precision approach operations. Commercial airlines in Germany and Japan are refreshing these systems to meet evolving GNSS interference mitigation standards from EASA and JCAB.
- Terrain Awareness:Synthetic vision overlays fuse digital elevation models with forward-looking sensor feeds for zero-visibility operations. Military transport commands in Australia and rotary wing squadrons across NATO territories are procuring these for nap-of-earth flight profiles.
- Flight Planning:Dynamic route optimization engines calculate fuel-efficient trajectories through four-dimensional wind field modeling.
- Weather Tracking:Real-time meteorological data ingestion supports thunderstorm circumnavigation and volcanic ash avoidance.
- Airspace Management:Collaborative decision-making platforms coordinate slot allocations across multiple ANSP jurisdictions.
Navigation systems anchor current procurement volumes. Terrain awareness is climbing the fastest as defense budgets reallocate toward contested environment survivability.
Application:
Certification stringency varies dramatically across operational domains, fragmenting vendor development roadmaps.
- Commercial Aviation:Part 121 and Part 135 operators require DO-178C Level A certified software for primary flight display integration. United States network carriers and flag carriers in France are driving replacement demand as FAA NextGen and SESAR mandates force avionics refresh cycles.
- Unmanned Aerial Vehicles:Beyond-visual-line-of-sight operations demand centimeter-precision geofencing and dynamic corridor management for urban air mobility. Regulatory frameworks in the United Arab Emirates and Germany are creating first-mover certification pathways for drone delivery networks.
- Military Operations:Electronic warfare resilience and jam-resistant positioning drive specialized procurement.
- General Aviation:Owner-operated aircraft favor portable and panel-mounted solutions with lower certification burdens.
- Search & Rescue:Multi-sensor fusion for maritime and alpine environments requires interoperable data formats.
Commercial aviation dominates current revenue. Unmanned aerial vehicles represent the steepest expansion trajectory as low-altitude corridors proliferate.
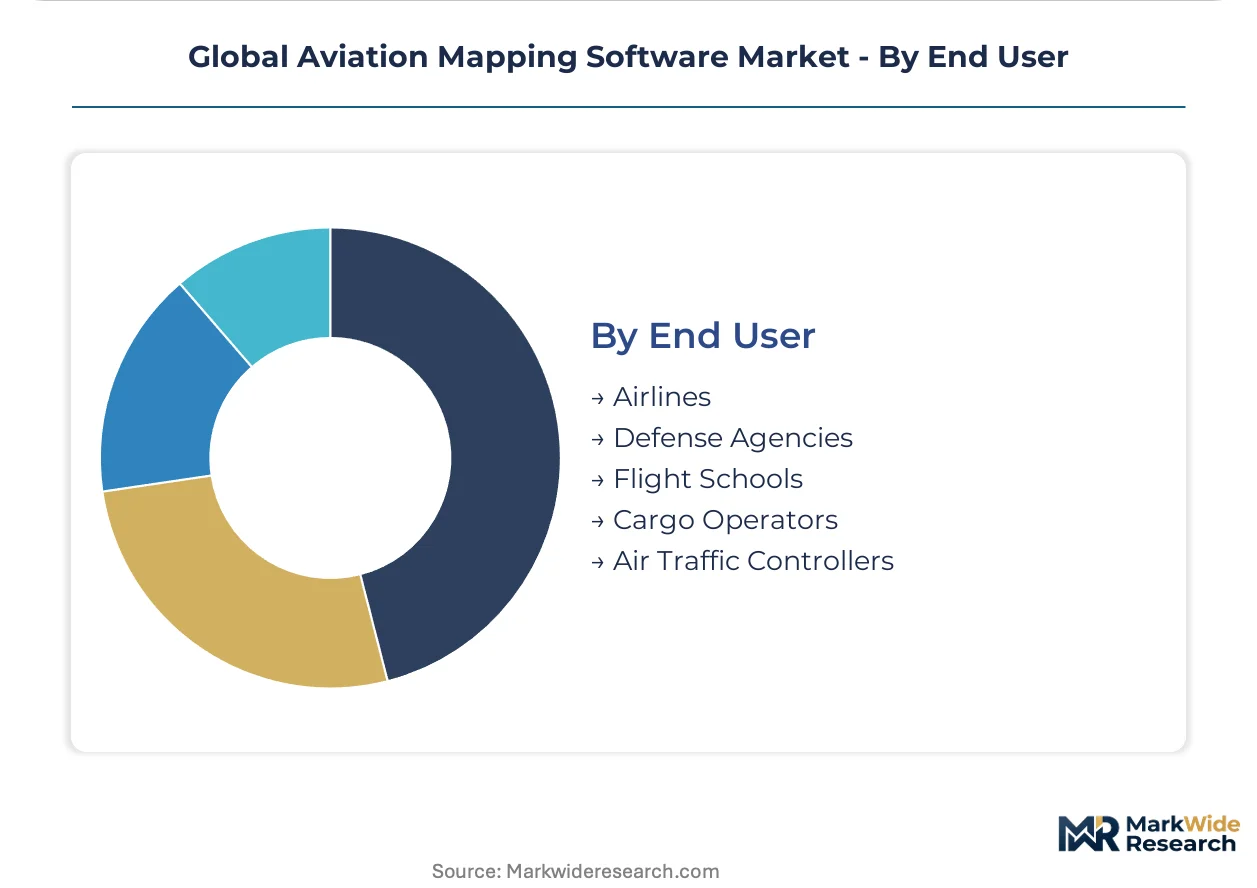
End User:
Procurement authority concentration determines sales cycle length and technical specification depth.
- Airlines:Fleet-wide standardization mandates drive enterprise software contracts with integrated training and support packages. Full-service carriers in the United Kingdom and budget operators in India are unbundling chart subscriptions from OEM flight deck contracts to negotiate directly with specialized mapping vendors.
- Defense Agencies:Classified mission requirements and sovereign data control dictate custom development programs with multi-year funding horizons. Pentagon acquisition commands and ministry of defense procurement offices in Israel prioritize electronic warfare compatibility and anti-jam terrain reference navigation.
- Cargo Operators:Time-critical logistics networks prioritize automated route optimization over passenger safety redundancy.
- Flight Schools:Training device fidelity requirements shape simulator-integrated mapping procurement.
- Air Traffic Controllers:ANSP system modernization programs govern multi-stakeholder interoperability standards.
Airlines command current contract value. Defense agencies are rotating up the share rankings as geopolitical tension accelerates sovereign capability investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while procurement volume accelerates in China, creating a structural asymmetry where American vendors capture premium margins on certified avionics while Chinese state-directed programs scale domestic alternatives.
United States
Major network carriers and defense integrators operate the largest legacy avionics installed bases requiring replacement. FAA NextGen mandates force sustained procurement cycles for DO-178C certified mapping solutions. Seattle and Wichita clusters host Boeing and specialized flight deck suppliers pushing cloud-native architectures.
China
Urban air mobility corridors and drone delivery networks in Shenzhen and Guangzhou generate demand for high-resolution 4D airspace modeling. CAAC imposes parallel type certification protocols that force vendors to maintain separate software baselines. State-directed programs in Shanghai and Xi'an accelerate indigenous avionics development for commercial and military platforms.
Germany
Low-cost operators and business aviation fleets drive unbundling of chart subscriptions from OEM contracts. EASA enforces CE-marked avionics certification under EU regulation 965/2012. Munich and Hamburg industrial clusters concentrate aerospace software engineering talent for terrain awareness and synthetic vision systems.
Israel
Defense agencies prioritize electronic warfare compatibility and anti-jam terrain reference navigation. Ministry of defense procurement offices fund multi-year custom development programs. Tel Aviv and Haifa host concentrated expertise in safety-critical geospatial systems for contested environment operations.
Japan
Commercial airlines refresh integrated flight management computers to meet evolving GNSS interference mitigation standards from JCAB. Precision approach operations in Tokyo and Osaka metro corridors require RTK-GNSS augmentation. Nagoya aerospace cluster supports cockpit upgrades across ANA and JAL long-haul fleets.
Global Aviation Mapping Software Market Competitive Landscape
Concentration sits with full-stack avionics OEMs and specialized geospatial software vendors competing across modular, API-first platforms. Boeing and Airbus sustain integrated flight deck ecosystems through enormous R&D budgets. Garmin and Esri represent divergent specialization archetypes in portable navigation and enterprise geospatial intelligence. Dominant competitive moves include cloud-native architecture shifts and direct-to-device distribution bypassing traditional avionics integrators.
Within the full-stack OEM tier, Boeing and Airbus anchor integrated flight deck ecosystems that bundle mapping software with airframe contracts. Garmin exemplifies the specialized vendor archetype through portable and embedded navigation systems for general aviation. Esri occupies a position extending geospatial intelligence platforms into airspace visualization tools, representing the enterprise software archetype competing against avionics-native solutions.
| Leading Market Players |
|---|
| Boeing |
| Airbus |
| Garmin |
| Jeppesen |
| L3Harris Technologies |
| Honeywell International |
| Raytheon Technologies |
| Esri |
| Trimble |
| Others |
Supply & Pricing Matrix
Photogrammetric point clouds replacing proprietary LiDAR hardware simultaneously compresses supplier margins in Germany and Japan while redistributing procurement power toward cloud-native vendors in Seattle and Tel Aviv. This substitution collapses equipment-intensive supply chains into data-centric architectures where recurring subscription economics displace capital-intensive sensor manufacturing.
Pricing Analysis
The customization-premium spread separates DO-178C Level A certified flight management integrations from standard electronic flight bag chart subscriptions. Pricing stratifies across premium, standard, and economy tiers where certification grade and fleet-scale volume dictate contract structures. Cost compression in the standard tier intensifies because low-cost carriers unbundle subscriptions from OEM flight deck contracts. Cargo operators exhibit highest price sensitivity due to thin operating margins, while defense agencies accept premium pricing for sovereign data control and electronic warfare compatibility.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes from Taiwan and South Korea elevate inbound logistics costs for RTK-GNSS augmentation chipsets. Geographic supply concentration centers on Taiwan for semiconductor components, the United States for safety-critical software engineering, and Germany for precision sensor hardware. The supply chain rests on dual dependencies: photogrammetric processing engines from Esri and proprietary terrain databases from Jeppesen. Single-source vulnerability permeates certified avionics code bases where FAA-mandated DO-178C compliance locks vendors into multi-year validation cycles. Distribution runs through avionics integrators like L3Harris and Honeywell, though direct-to-device electronic flight bag applications increasingly bypass this channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States network carriers and European low-cost operators as fleet-scale procurement departments unbundle mapping subscriptions from integrated flight deck contracts. This consolidation fragments pricing power away from full-stack OEMs toward modular software vendors.
For Market Incumbents: Shield integrated flight deck ecosystems by embedding cloud-native mapping layers deeper into Boeing and Airbus avionics architectures. Acquire specialized terrain database vendors in Israel or Germany to preempt independent subscription models. Certification investment in DO-178C Level A compliance for synthetic vision systems defends against modular entrants targeting the low-altitude economy.
For New Entrants and Emerging Players: Anchor in India's defense modernization programs where indigenous light combat aircraft lack domestic mapping software suppliers. Target urban air mobility corridors in the United Arab Emirates and Germany where 4D airspace modeling regulations are still crystallizing. A direct-to-device electronic flight bag go-to-market angle bypasses entrenched avionics integrator relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed geospatial software vendors holding FAA certification but lacking cloud-native architectures. The five-to-ten year viability window favors modular platforms over hardware-locked ecosystems. Acquisition candidates include terrain awareness specialists with military procurement relationships and API-first charting engines. Monitor JCAB and EASA regulatory harmonization on GNSS interference mitigation as an inflection signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Multi-tenant SaaS platforms reduce IT overhead for United States major carriers accelerating NextGen compliance. |
| Direct-to-Device Distribution | Electronic flight bag applications bypass Honeywell and L3Harris integrators, letting pilots subscribe independently. |
| Defense Certification Investment | DO-178C Level A compliance for terrain awareness systems unlocks Pentagon and NATO rotary wing procurement. |
| API-First Platform Integration | Modular architectures enable heterogeneous fleet environments across merged airline entities and cargo operators. |
| Geospatial Data Vendor Acquisition | Capturing proprietary terrain database suppliers defends against unbundling of chart subscriptions from flight deck contracts. |
Research Methodology
A spread of perspectives from flight operations executives, avionics procurement managers, air traffic control modernization leads, and defense acquisition officers converged on the working assumptions. Primary interviews across these stakeholder roles combined with secondary validation from FAA NextGen implementation reports, EASA SESAR deployment databases, CAAC type certification filings, and airline fleet upgrade disclosures. Bottom-up triangulation across deployment models and solution types intersected with top-down macroeconomic scenario testing.
Segmentation dimensions modeled span deployment architecture, solution type, application domain, and end-user procurement authority across the analysis window. CAGRs derived from regression analysis against regulatory mandate timelines and fleet replacement cycles. Industry-specific forecast inputs include DO-178C certification pipeline durations and urban air mobility corridor regulatory activation schedules.
Material uncertainties — geopolitical data fragmentation, autonomous routing certification delays, and GLONASS augmentation sanctions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization pace and cloud migration adoption curves among legacy fleet operators. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market
Aircraft Navigation and Communication
Aircraft Interface Device Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
Ultra Short Base Line Positioning System Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
GPS and GNSS Receivers in Aviation Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
Global Flight Navigation System Market
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
In Flight Connectivity Market