
 GPS and GNSS Receivers in Aviation Market | 2026-2036
GPS and GNSS Receivers in Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
GPS and GNSS Receivers in Aviation Market Outlook
Market Context with Strategic Players
Buyer concentration among commercial airlines is consolidating as legacy carriers and low-cost operators standardize on multi-constellation receiver platforms. Trimble Inc. leverages its precision agriculture heritage to anchor aviation-grade GNSS module development. Garmin Ltd. sustains dominance in panel-mounted receiver categories through integrated flight deck ecosystems. Hexagon AB differentiates via high-accuracy augmentation services that extend into approach-critical aviation applications.
Technical Definition and Structural Segments
GPS and GNSS receivers in aviation are radio-frequency devices that decode satellite signals from multiple constellations to provide position, velocity, and timing data with sub-meter accuracy for flight navigation and landing guidance. These receivers process L1, L2, and L5 carrier frequencies through specialized correlator architectures to achieve integrity monitoring required for instrument flight rules. Panel-mounted receivers occupy the largest value pool as airlines retrofit aging flight decks with multi-constellation capability. UAV operators represent the fastest-growing end-user segment as beyond-visual-line-ofsight regulations expand commercial drone operations. Dual-frequency technology leads technology migration paths because ionospheric error correction becomes mandatory for precision approach categories.
Regulatory Frame and Forward-Looking Close
FAA NextGen mandates, EU GNSS regulatory frameworks, and ICAO standards collectively shape receiver certification requirements and airworthiness approval pathways. The FAA requires automatic dependent surveillance-broadcast equipage that depends on GNSS position sources, while EASA enforces multi-constellation resilience standards under its approach navigation specifications. Stakeholders must monitor evolving spectrum allocation decisions at WRC conferences that could redefine L-band signal availability for aviation safety services.
Market Dynamics
Dual-frequency receiver architectures are displacing legacy single-frequency units as precision approach mandates tighten across civil aviation authorities. Airlines now face equipage deadlines that force fleet-wide retrofits regardless of remaining airframe service life.
Growth Catalysts
- FAA NextGen Surveillance Mandate:Automatic dependent surveillance-broadcast requirements are compelling commercial carriers to install GNSS-dependent position sources across narrow-body and wide-body fleets.
- Multi-Constellation Resilience Standards:EASA approach navigation specifications now require receivers capable of processing GPS, Galileo, and GLONASS signals simultaneously for redundancy.
- Beyond-Visual-Line-of-Sight Operations:Commercial drone regulations in Germany and China are creating certified receiver demand for unmanned cargo and inspection platforms.
Market Restraints
- Semiconductor Supply Concentration:Advanced correlator chips and RF front-end components depend on fabrication facilities concentrated in Taiwan and South Korea.
- Certification Timeline Friction:FAA TSO-C145 and TSO-C146 approvals require 18-24 month validation cycles that delay product launches.
- Iridium Satcom Substitution:Satellite-based augmentation system providers face competition from L-band satcom services offering position verification alternatives.
Strategic Opportunities
- Urban Air Mobility Integration:eVTOL manufacturers in the United States require aviation-grade GNSS modules with integrity monitoring for autonomous passenger transport.
- India Regional Navigation:GAGAN augmentation network expansion creates demand for IRNSS-compatible receivers in domestic aviation infrastructure.
- Software-Defined Radio Convergence:Flexible receiver architectures combining multi-constellation decoding with programmable signal processing reduce hardware refresh cycles.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized skills in L-band signal processing and ionospheric modeling are concentrated among legacy defense contractors.
- Legacy Flight Deck Integration:ARINC 429 and MIL-STD-1553 interface requirements complicate receiver installation on aging Boeing and Airbus platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GPS and GNSS Receivers in Aviation Market |
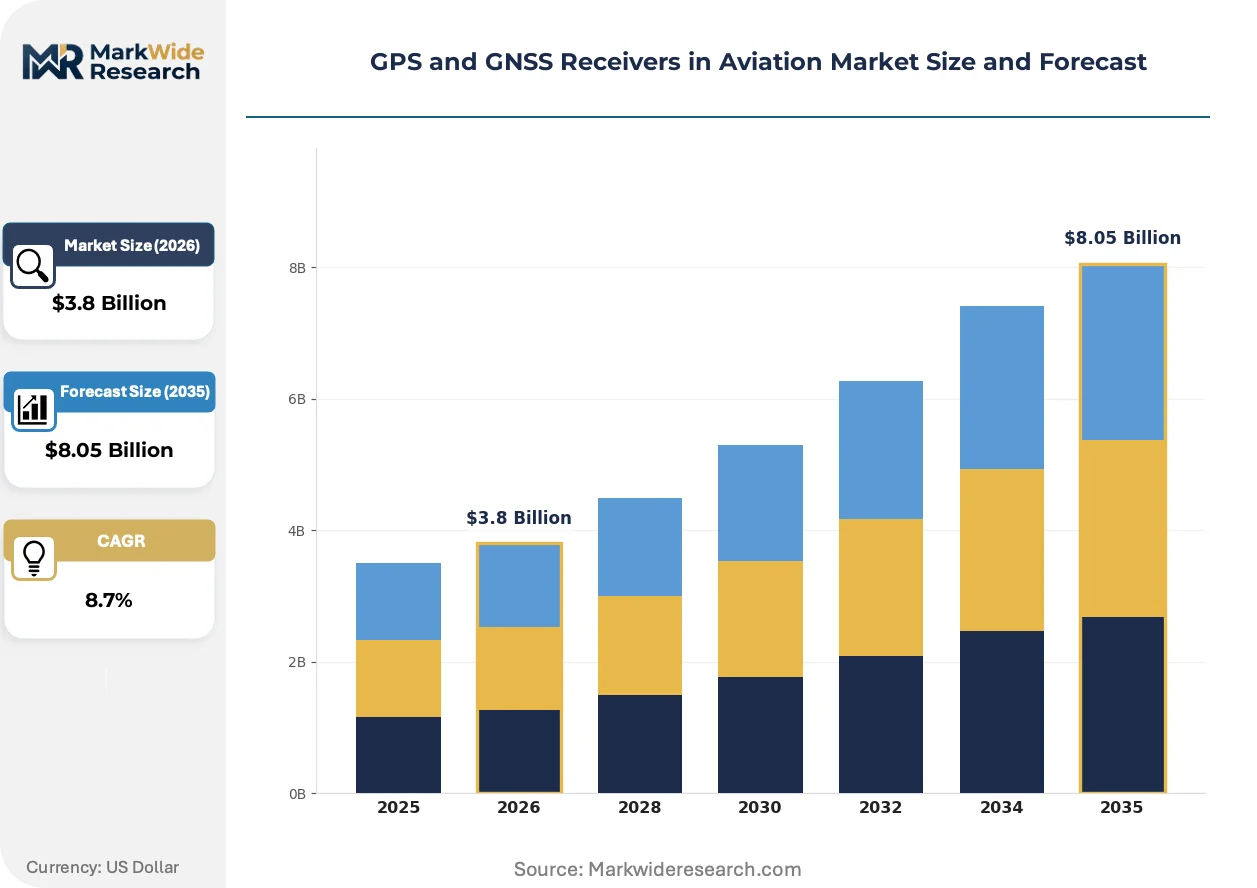
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Receivers, Panel-Mounted Receivers, Portable Receivers, Integrated Receivers End User: Commercial Aviation, Private Aviation, Military Aviation, UAV Operators Technology: Single Frequency, Dual Frequency, Multi-Constellation, Augmented Systems Application: Navigation, Landing, Surveillance, Traffic Management |
| Companies Covered | Topcon Positioning Systems, Inc., Broadcom, Inc., Trimble Inc., Cobham Limited, Qualcomm Technologies, Inc., Garmin Ltd., Hexagon AB, Hemisphere GNSS, L3Harris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GPS and GNSS Receivers in Aviation Market Strategic Shifts
Receiver architectures are evolving from hardware-defined to software-configurable platforms. This shift enables rapid constellation adaptation and reduces recertification burdens when new signals become operational.
Multi-frequency chipsets are expanding into commercial transport categories previously served by single-frequency units. Low-cost carriers in Europe and Asia-Pacific are retrofitting A320 and 737 fleets with L1/L5 capable modules to meet 2028 precision approach deadlines. The technology is expanding into price-sensitive segments that historically deferred capability upgrades.
EU GNSS regulatory frameworks are mandating Galileo authentication service compatibility for all new aviation receiver certifications. EASA implementing rules published in 2024 require receivers to verify signal authenticity through the Open Service Navigation Message Authentication protocol. European airlines are prioritizing receiver swaps during scheduled heavy maintenance checks to avoid operational disruption.
Airline procurement departments are consolidating vendor relationships around integrated flight deck suppliers rather than standalone receiver specialists. Major carriers in the United States and Germany now specify multi-constellation capability as a baseline requirement in flight management system RFPs. This concentration is visible in long-term service agreements that bundle hardware, installation, and augmentation subscriptions into single contracts.
GPS and GNSS Receivers in Aviation Market Segmentation
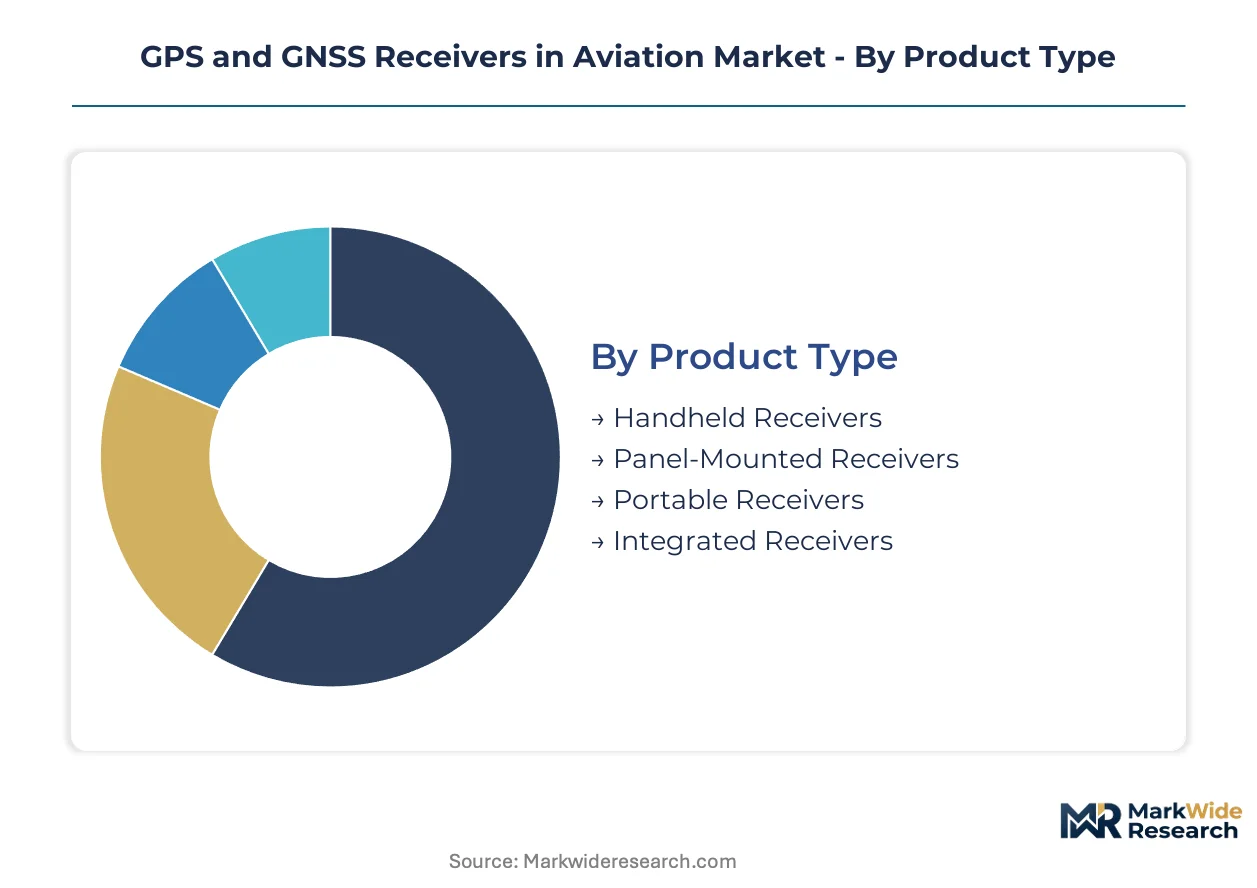
Receiver segmentation in aviation reflects divergent certification burdens across installation types and operational categories. FAA TSO-C145 and TSO-C146 approvals create tiered compliance costs that reshape competitive positioning within each segment cluster.
Product Type:
Certification timelines vary sharply across installation categories, with panel-mounted units facing the most intensive airworthiness validation under FAA and EASA protocols.
- Panel-Mounted Receivers:Permanently installed avionics processing L1, L2, and L5 frequencies through ARINC 429 interfaces. Airlines in the United States and Germany concentrate procurement here as NextGen equipage deadlines force fleet-wide retrofits of aging flight decks.
- Integrated Receivers:Embedded modules within flight management systems combining multi-constellation decoding with inertial reference units. Airbus and Boeing specify these for new production narrow-body aircraft to satisfy EASA multi-constellation resilience mandates.
- Handheld Receivers:Battery-powered portable units for supplemental navigation in general aviation cockpits.
- Portable Receivers:Temporary-mount devices used in rental fleets and flight training aircraft.
Leading the category by volume: Panel-Mounted Receivers. Expanding most quickly: Integrated Receivers.
End User:
Customer procurement patterns range from consolidated airline fleet contracts to fragmented individual operator purchases, with UAV segments showing the steepest certification pathway divergence.
- Commercial Aviation:Scheduled carriers operating narrow-body and wide-body fleets under Part 121 regulations. United States legacy carriers and low-cost operators drive multi-constellation retrofits as FAA ADS-B mandates approach final compliance phases.
- UAV Operators:Beyond-visual-line-of-sight cargo and inspection platforms requiring aviation-grade integrity monitoring. Germany and China regulators are expanding certified receiver demand through new commercial drone frameworks.
- Private Aviation:Part 91 operators in owner-flown and charter aircraft with discretionary upgrade cycles.
- Military Aviation:Defense platforms with classified signal requirements and anti-jam specifications.
Commercial Aviation commands the largest procurement value. UAV Operators are climbing the fastest as regulatory frameworks mature.
Technology:
Frequency architecture determines ionospheric correction capability and precision approach eligibility under ICAO standards.
- Dual Frequency:L1/L5 or L1/L2 architectures enabling real-time ionospheric error correction for Category I/II/III approaches. European low-cost carriers retrofit A320 and 737 fleets to meet EASA precision approach deadlines.
- Multi-Constellation:Simultaneous GPS, Galileo, GLONASS, and BeiDou processing for signal redundancy. EASA implementing rules now mandate this capability for all new aviation receiver certifications.
- Single Frequency:Legacy L1-only units facing displacement as precision approach mandates tighten.
- Augmented Systems:SBAS and GBAS receivers utilizing WAAS, EGNOS, or GAGAN correction networks.
Dual Frequency dominates current airline procurement. Multi-Constellation is gaining share fastest as resilience standards harden.
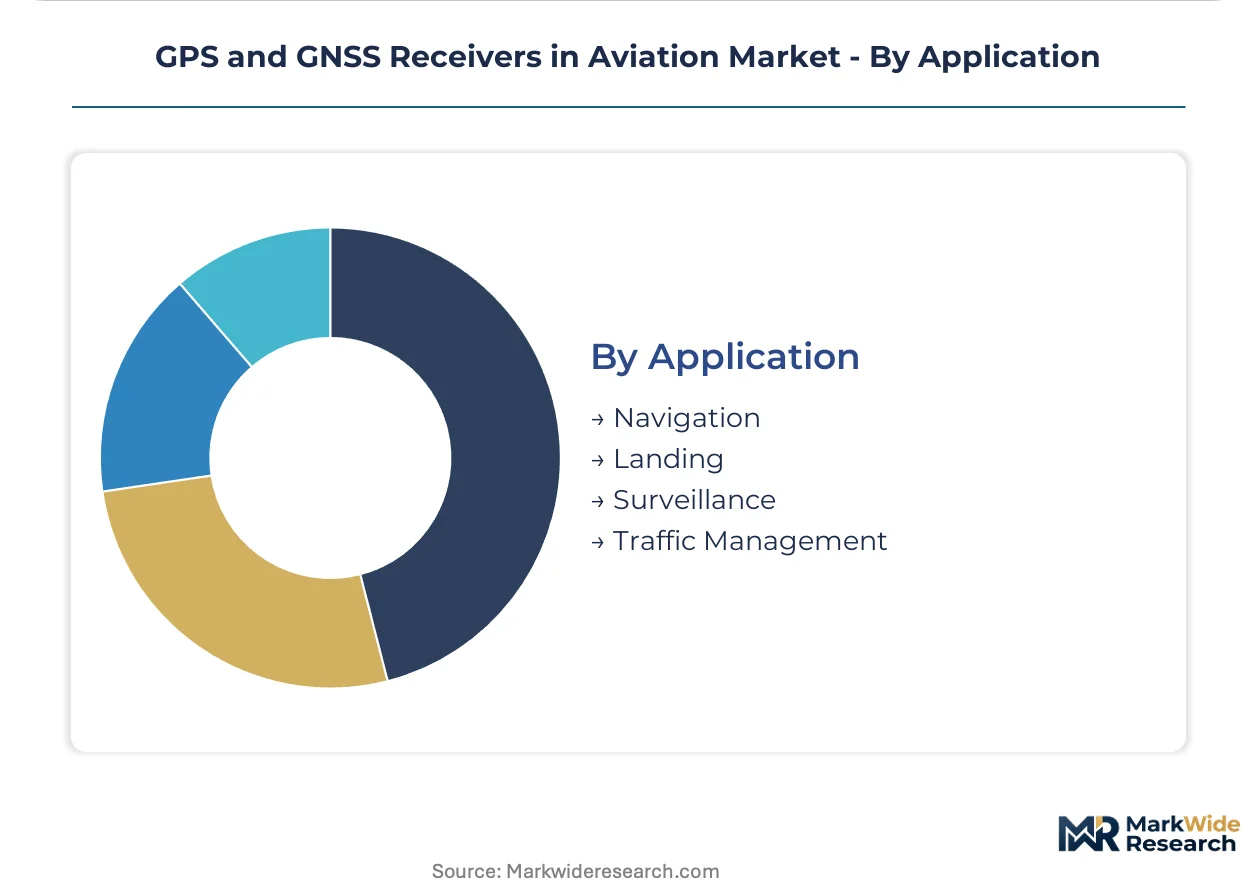
Application:
Functional use cases span from en-route navigation through safety-critical landing guidance, each with distinct integrity and availability requirements.
- Navigation:En-route and terminal area position determination for flight management system guidance. This foundational application spans all user segments with baseline accuracy requirements.
- Landing:Precision approach and landing guidance demanding sub-meter accuracy and integrity monitoring. ICAO standards drive technology migration toward dual-frequency architectures here.
- Surveillance:ADS-B position reporting for air traffic control visibility.
- Traffic Management:Surface movement and sequencing applications at high-density airports.
Navigation generates the highest unit volume. Landing applications show the steepest technology upgrade intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium arsenide foundries in Taiwan supply the RF front-end substrates that underpin aviation-grade receiver production. Receiver assembly concentrates near aerospace clusters where FAA, EASA, and CAAC certification expertise resides.
United States
Commercial airlines retrofit narrow-body fleets ahead of FAA ADS-B mandate deadlines. The FAA requires automatic dependent surveillance-broadcast equipage that depends on GNSS position sources. Dallas-Fort Worth anchors receiver integration activity as American Airlines and Southwest Airlines coordinate fleet-wide avionics upgrades.
Germany
Lufthansa Group drives multi-constellation retrofits across A320 and A350 aircraft to satisfy EASA resilience standards. EASA implementing rules mandate Galileo authentication service compatibility for new aviation receiver certifications. Munich hosts Hexagon AB's European augmentation services hub serving approach-critical applications.
China
Commercial drone operators expand beyond-visual-line-of-sight cargo routes requiring certified aviation-grade receivers. CAAC regulations align with ICAO standards while promoting BeiDou constellation adoption in domestic aviation infrastructure. Shenzhen clusters UAV receiver manufacturing near DJI's headquarters and CAAC certification facilities.
United Kingdom
BAE Systems and Rolls-Royce supply chain partners demand aviation-grade GNSS modules for defense and commercial aerospace platforms. The UK Civil Aviation Authority enforces multi-constellation equipage through its air navigation order amendments. Bristol concentrates receiver testing facilities near Airbus wing manufacturing operations.
Japan
ANA and JAL retrofit 737 and 767 fleets with dual-frequency receivers ahead of 2028 precision approach deadlines. METI promotes QZSS augmentation integration for domestic approach operations. Nagoya clusters avionics integration facilities serving Boeing and Mitsubishi Aircraft supply chains.
GPS and GNSS Receivers in Aviation Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-defined radio architectures and urban air mobility applications. The vendor base concentrates around flight deck integrators and precision positioning specialists. Three archetypes dominate: multi-constellation module suppliers, augmentation service providers, and integrated avionics platforms. M&A activity concentrates on RF front-end capabilities and certification portfolio expansion.
Within the integrated avionics tier, Garmin Ltd. and Trimble Inc. exemplify divergent positioning strategies. Garmin Ltd. anchors panel-mounted receiver categories through flight deck ecosystem integration. Trimble Inc. represents precision agriculture heritage translated into aviation-grade GNSS module development. Hexagon AB occupies a distinct position among augmentation service providers extending into approach-critical applications. Qualcomm Technologies, Inc. and Broadcom, Inc. sit within the semiconductor substrate layer supplying correlator chipsets to downstream avionics integrators.
| Leading Market Players |
|---|
| Topcon Positioning Systems, Inc. |
| Broadcom, Inc. |
| Trimble Inc. |
| Cobham Limited |
| Qualcomm Technologies, Inc. |
| Garmin Ltd. |
| Hexagon AB |
| Hemisphere GNSS |
| L3Harris Technologies, Inc. |
| Others |
Value Chain & Pricing Dynamics
Gallium arsenide wafer costs cascade through RF front-end fabrication into tiered receiver pricing, with Taiwan foundry concentration amplifying margin pressure on panel-mounted units destined for FAA-mandated airline retrofits.
Pricing Analysis
Warranty and augmentation service bundling separates premium aviation-grade receivers from unbundled portable alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier (TSO-C145 vs TSO-C146) and volume scale. Pricing pressure stems from semiconductor supply concentration as correlator chip shortages extend lead times. Low-cost carriers exhibit highest price sensitivity, while integrated flight deck procurement by legacy carriers shows lowest elasticity.
Supply Chain Analysis
Air freight rates from Taiwan and South Korea to United States aerospace clusters directly impact landed costs for RF front-end substrates. Gallium arsenide foundries in Taiwan, South Korea, and Japan anchor upstream supply. Advanced correlator chips, ceramic substrates, and precision oscillators feed from concentrated fabrication facilities. Single-source vulnerability in Taiwan gallium arsenide capacity poses structural risk. Distribution runs through certified avionics integrators serving FAA and EASA approval pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation GNSS receiver supply is tightening around Taiwan gallium arsenide foundry capacity, with that bottleneck sustaining pricing power for certified module producers through the analysis window.
For Market Incumbents: Anticipate software-defined radio entrants by deepening certification portfolio breadth across FAA and EASA jurisdictions. Secure captive supply of RF front-end components through foundry partnerships in Taiwan or South Korea. EASA's Galileo authentication mandate creates leverage for module suppliers with pre-certified architectures. For New Entrants and Emerging Players: Urban air mobility manufacturers in the United States represent an underserved buyer archetype requiring aviation-grade integrity monitoring without legacy flight deck integration burdens. Beyond-visual-line-of-sight cargo operators in Germany and China offer second penetration vector. Lead with software-configurable architectures that reduce recertification friction. For Investors and Strategic Acquirers: EASA implementing rules mandating Galileo authentication compatibility is the leading indicator that certification portfolio depth will concentrate value in approach-critical augmentation services. Five-to-ten-year viability favors augmentation service providers with multi-constellation correction networks. Watch for FAA spectrum allocation decisions at WRC conferences as inflection signal for L-band signal availability.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | TSO-C145 and TSO-C146 approvals unlock FAA and EASA airline procurement channels. |
| Multi-Constellation Module Development | Simultaneous GPS, Galileo, GLONASS processing satisfies EASA resilience mandates. |
| RF Front-End Backward Integration | Gallium arsenide substrate control insulates against Taiwan foundry concentration risk. |
| Augmentation Service Licensing | WAAS, EGNOS, and GAGAN correction networks extend into approach-critical applications. |
| Urban Air Mobility Partnership | eVTOL manufacturers require integrity monitoring modules for autonomous passenger transport. |
Study Parameters
Independent corroboration across FAA certification databases, EASA implementing rule publications, and airline fleet equipage disclosures underwrites the qualitative findings. Primary interviews with avionics procurement directors, flight management system engineers, and regulatory affairs specialists at major carriers and OEMs combined with secondary validation. FAA TSO filings, EASA certification records, ICAO standards documentation, and customs trade data for RF component imports anchored supply-side assessment. Bottom-up unit economics triangulated against top-down fleet retrofit projections.
Rate-of-change decomposition across technology migration paths, regulatory compliance deadlines, and fleet replacement cycles structured the analytical framework. Segmentation dimensions modeled include receiver installation type, end-user operational category, frequency architecture, and application criticality. CAGRs derived from fleet equipage schedules correlated with mandate phase-in timelines. Ionospheric correction capability requirements and multi-constellation resilience standards served as technology-specific forecast inputs throughout the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to WRC spectrum allocation decisions, gallium arsenide foundry capacity expansion, and eVTOL certification pathway evolution. Forecasts reflect documented assumptions about regulatory timeline adherence and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Aircraft Navigation Software Market
Aircraft Navigation and Communication
Military Navigation Systems Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Ultra Short Base Line Positioning System Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
Aircraft Navigation System Market
Aircraft Navigation and Communication
Airborne High Frequency Radio Market
Aircraft Navigation and Communication
Electronic Navigational Charts (ENC) Market