
 Smart Airport 4.0 Market | 2026-2036
Smart Airport 4.0 Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Airport 4.0 Market Analytics
Market Context
Passenger processing is pivoting toward fully automated biometric corridors as airports replace legacy check-in infrastructure. SITA leverages decades of aviation IT integration to sustain its installed base across major international hubs. Honeywell International Inc. anchors its position through building automation and airfield lighting systems that tie into broader digital airport platforms. Cisco Systems Inc. competes on secure network backbone architecture that underpins real-time data flows between IoT endpoints and central operations centers.
Technical Definition and Segments
Smart Airport 4.0 denotes the integration of cyber-physical systems, digital twins, and autonomous decision layers across airport operations, typically requiring sub-100-millisecond latency for safety-critical control loops and 99.999% uptime for passenger-facing services. Its primary commercial purpose is to maximize asset utilization while shrinking turnaround times and labor dependency. IoT Solutions and AI Systems command the deepest margin pools as these layers sit closest to operational intelligence and predictive maintenance value creation. Baggage Management represents the fastest-growing application segment as RFID and computer vision reduce mishandled luggage rates. System Integration services capture disproportionate value relative to standalone hardware or software sales because vendor interoperability remains the dominant buyer pain point.
Regulatory Frame
The EU AI Act, GDPR, and ICAO Annex 17 security standards collectively shape product roadmaps and market access conditions for Smart Airport 4.0 vendors serving European and internationally aligned jurisdictions. FAA Advisory Circulars and TSA directives in the United States impose additional certification burdens on biometric and screening technologies that vendors must satisfy before deployment. Stakeholders must monitor how divergent data sovereignty rules between the European Union, China, and the United States fragment cloud architecture strategies and force region-specific system deployments.
Market Dynamics
Post-pandemic passenger volume recovery is compressing procurement cycles for biometric processing infrastructure, forcing airports to retrofit legacy terminals with AI-driven automation layers rather than greenfield construction.
Growth Catalysts
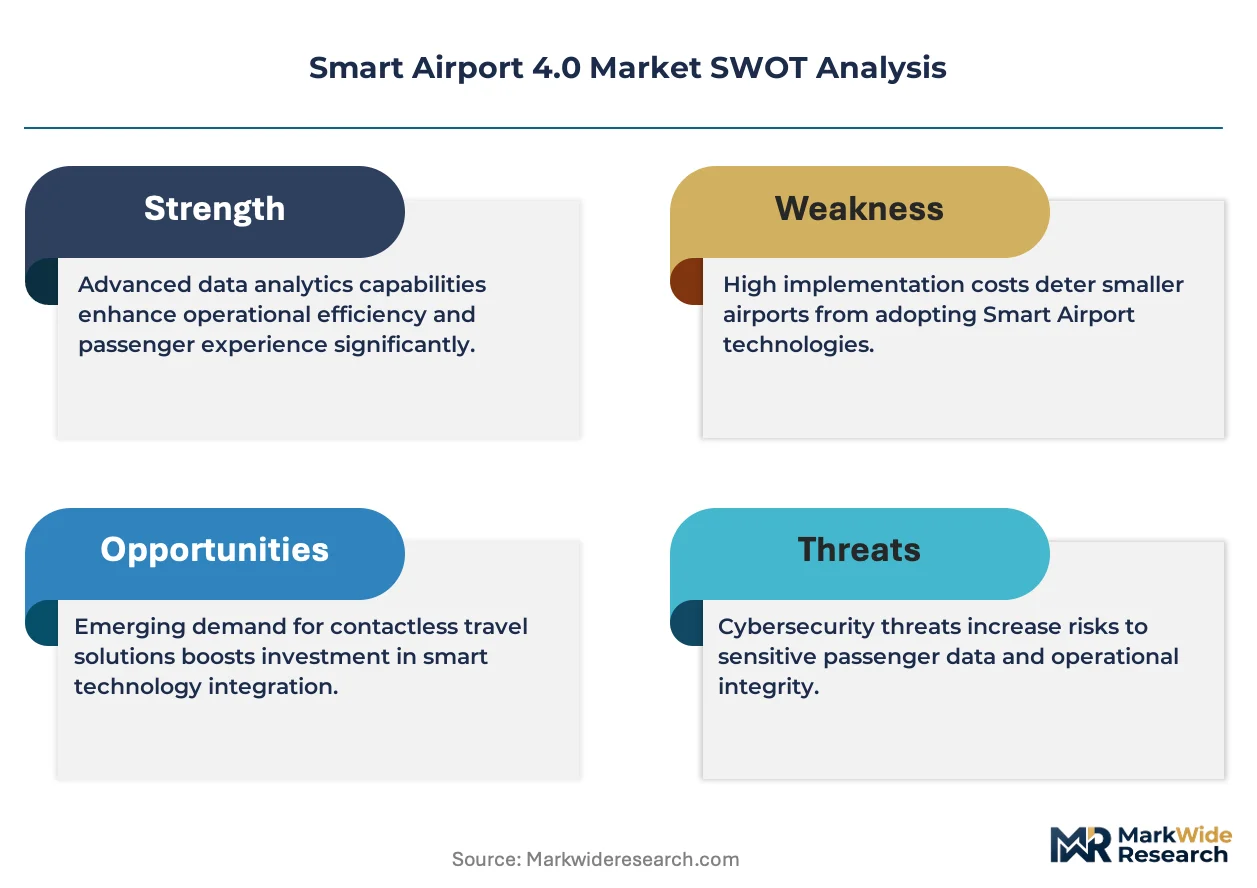
- EU AI Act certification mandates:European hubs must deploy compliant passenger screening algorithms by fixed deadlines, creating guaranteed replacement demand for non-compliant legacy systems.
- RFID-computer vision convergence:Real-time baggage tracking through sensor fusion is slashing mishandled luggage rates, justifying premium system investments at transfer-heavy mega-hubs.
- Singapore Changi and Dubai mega-hub expansions:These anchor projects are standardizing vendor specifications that cascade to secondary airport upgrades across Southeast Asia and the Middle East.
Market Restraints
- Semiconductor supply concentration:Edge AI processors and specialized RFID chips face single-source dependencies from Taiwan and South Korea foundries, exposing deployment timelines to geopolitical disruption.
- GDPR biometric data friction:Strict consent and retention rules for facial recognition templates slow pilot-to-production transitions at EU facilities.
- Legacy system interoperability debt:Proprietary protocols from 1990s-era building automation and baggage handling systems resist API-based integration without expensive middleware layers.
Strategic Opportunities
- India's Greenfield airport pipeline:Navi Mumbai, Jewar, and Mopa terminals offer vendor-neutral procurement environments without retrofit constraints.
- Digital twin predictive maintenance:Converging physics-based modeling with live IoT sensor streams enables condition-based rather than scheduled equipment servicing.
- Outcome-based performance contracts:Risk-sharing agreements where vendors guarantee passenger throughput or baggage mishandling rates are displacing traditional capital purchase models.
Industry Challenges
- Cyber-physical systems engineering talent scarcity:Airport operators compete with automotive and energy sectors for specialists who bridge operational technology and IT security domains.
- Multi-stakeholder certification alignment:Biometric corridor deployments require synchronized approvals from aviation security, data protection, and disability access regulators with non-overlapping review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Airport 4.0 Market |
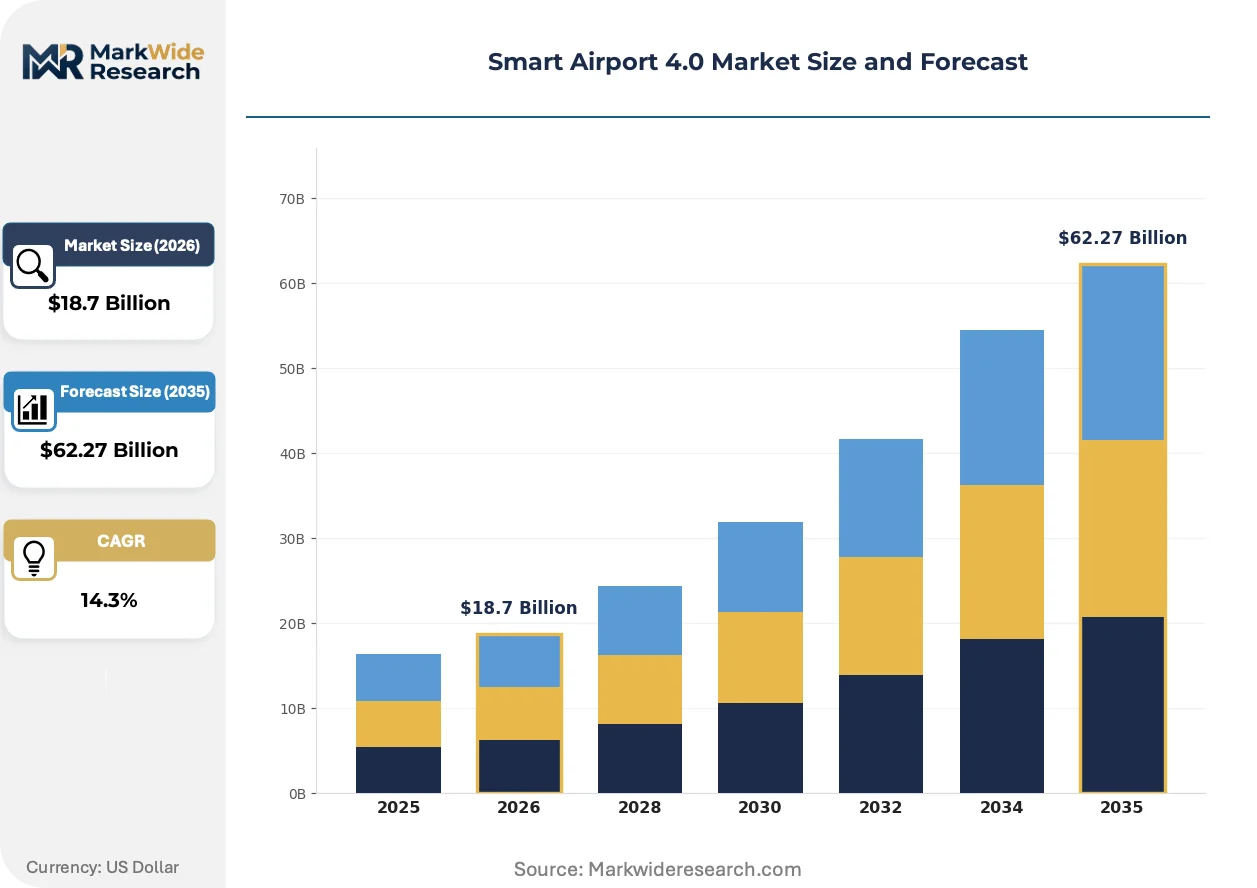
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $62.27 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, AI Systems, Cloud Computing, Data Analytics Application: Passenger Processing, Baggage Management, Security Screening, Flight Management Service Type: Consulting Services, System Integration, Maintenance Support, Training Services End User: Airlines, Airport Authorities, Ground Handlers, Government Agencies |
| Companies Covered | SITA, Cisco Systems Inc., Honeywell International Inc., IBM Corp, Raytheon Technologies, Siemens AG, Huawei Technologies Co. Ltd., Smart Airport Systems SAS, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Airport 4.0 Market Evolving Landscape
Edge computing architectures are redistributing intelligence from central data centers to distributed sensor nodes, collapsing latency for safety-critical control loops while complicating vendor interoperability standards.
Biometric identity tokens stored on passenger mobile devices are decentralizing authentication authority away from airport-operated databases. Lufthansa Group and IATA member carriers are piloting smartphone-based facial verification that eliminates repeated document checks. This architecture compresses infrastructure capex per passenger while shifting liability for data breaches toward device manufacturers and operating system providers.
EU AI Act risk-classification rules are forcing algorithmic audit trails for automated passenger screening decisions. High-risk biometric identification systems must demonstrate accuracy parity across demographic groups before deployment. German and French hub operators are front-loading compliance investments to secure first-mover certification advantages, creating a two-tier vendor landscape between certified and pending suppliers.
Consolidated procurement consortia among airport groups are displacing individual terminal purchasing decisions. AdP, Fraport, and Aena are harmonizing technical specifications across their portfolios to extract volume discounts and simplify vendor management. This concentration is most visible in Southern Europe, where financial stress from pandemic-era debt has accelerated centralization of technology investment authority from local airport managers to group headquarters.
Smart Airport 4.0 Market Segmentation
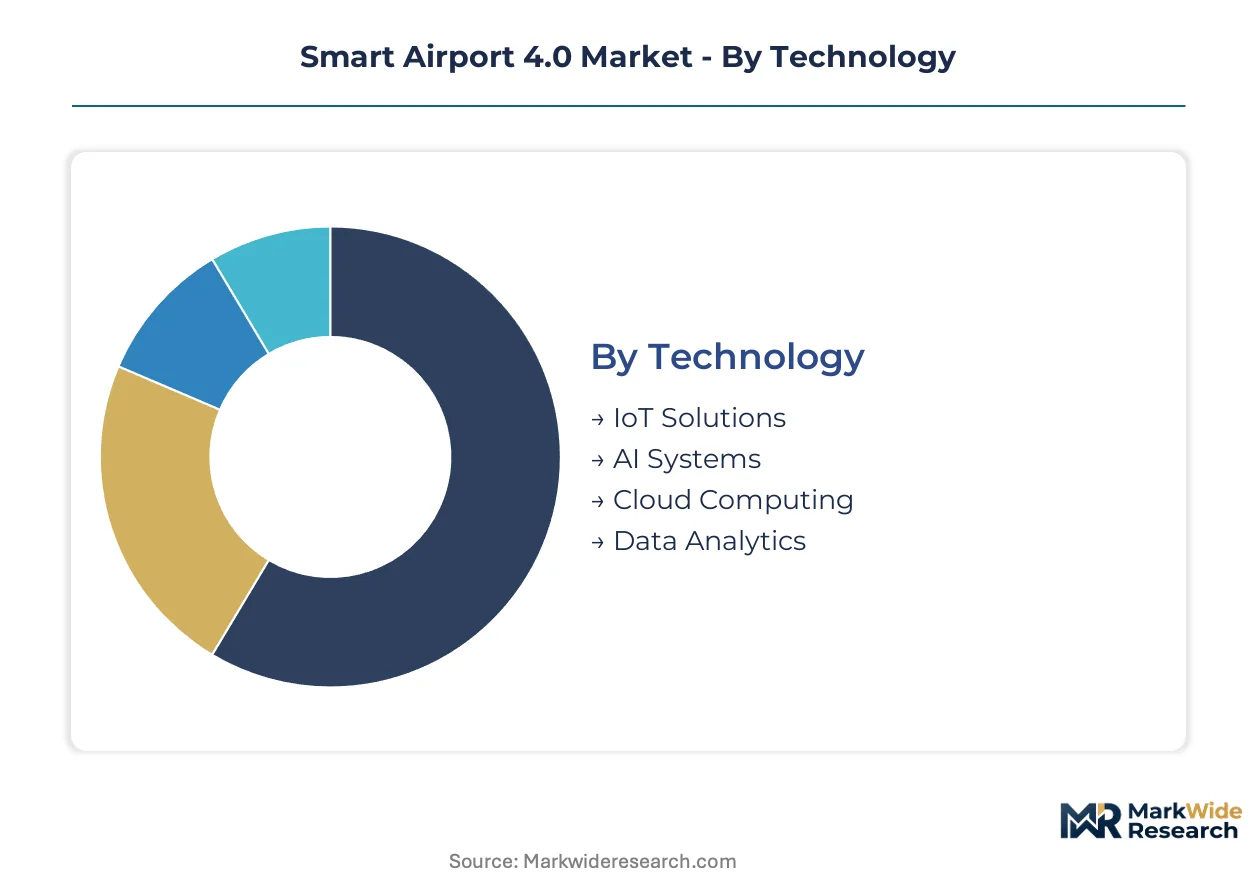
Smart Airport 4.0 procurement decisions fragment across technology layers, operational applications, and stakeholder groups with divergent performance metrics. Understanding these intersections reveals where vendor margins concentrate and where integration complexity creates barriers to entry.
Technology:
Supply concentration in edge AI processors and specialized sensor hardware shapes vendor positioning across the technology stack.
- IoT Solutions:Distributed sensor networks for environmental monitoring, asset tracking, and predictive maintenance require sub-100-millisecond latency for safety-critical loops. Demand concentrates at Singapore Changi and Dubai International where mega-hub expansions mandate unified IoT platforms rather than point solutions.
- AI Systems:Computer vision algorithms for biometric corridors and automated screening decisions sit closest to operational intelligence value creation. European hubs under EU AI Act deadlines are front-loading compliant system replacements, creating guaranteed demand for certified vendors.
- Cloud Computing:Hybrid architectures balance data sovereignty requirements against centralized analytics scale.
- Data Analytics:Real-time passenger flow optimization and predictive maintenance modeling extract value from accumulated operational data.
AI Systems absorb the bulk of installed capacity; Baggage Management applications are expanding most quickly through RFID-computer vision convergence.
Application:
Cost tier differentiation separates greenfield mega-hub deployments from retrofit constraints at legacy terminals.
- Passenger Processing:Biometric corridors and automated check-in infrastructure replace legacy systems as post-pandemic traffic rebounds. Procurement cycles compress at transfer-heavy hubs where throughput directly determines airline slot values.
- Baggage Management:RFID tracking combined with computer vision slashes mishandled luggage rates. German and UAE hub operators justify premium investments through quantified operational savings and reduced compensation liabilities.
- Security Screening:Automated threat detection algorithms face divergent certification requirements across FAA, TSA, and EU jurisdictions.
- Flight Management:Digital twin integration with airfield systems enables predictive turnaround scheduling.
Passenger Processing commands the deepest investment pools; Security Screening faces the steepest regulatory compliance barriers.
Service Type:
Customer type segmentation reveals how airport groups centralize procurement authority versus terminal-level purchasing.
- Consulting Services:Strategic roadmapping for digital transformation and regulatory compliance.
- System Integration:Vendor interoperability remains the dominant buyer pain point as proprietary 1990s-era protocols resist API-based integration. AdP, Fraport, and Aena harmonize specifications across portfolios to extract volume discounts and simplify vendor management.
- Maintenance Support:Condition-based servicing contracts displace scheduled maintenance through converged physics-based modeling and live IoT streams.
- Training Services:Cyber-physical systems engineering talent scarcity elevates vendor-delivered capability building.
System Integration captures disproportionate value relative to standalone hardware sales; Maintenance Support is climbing the fastest as outcome-based performance contracts displace capital purchase models.
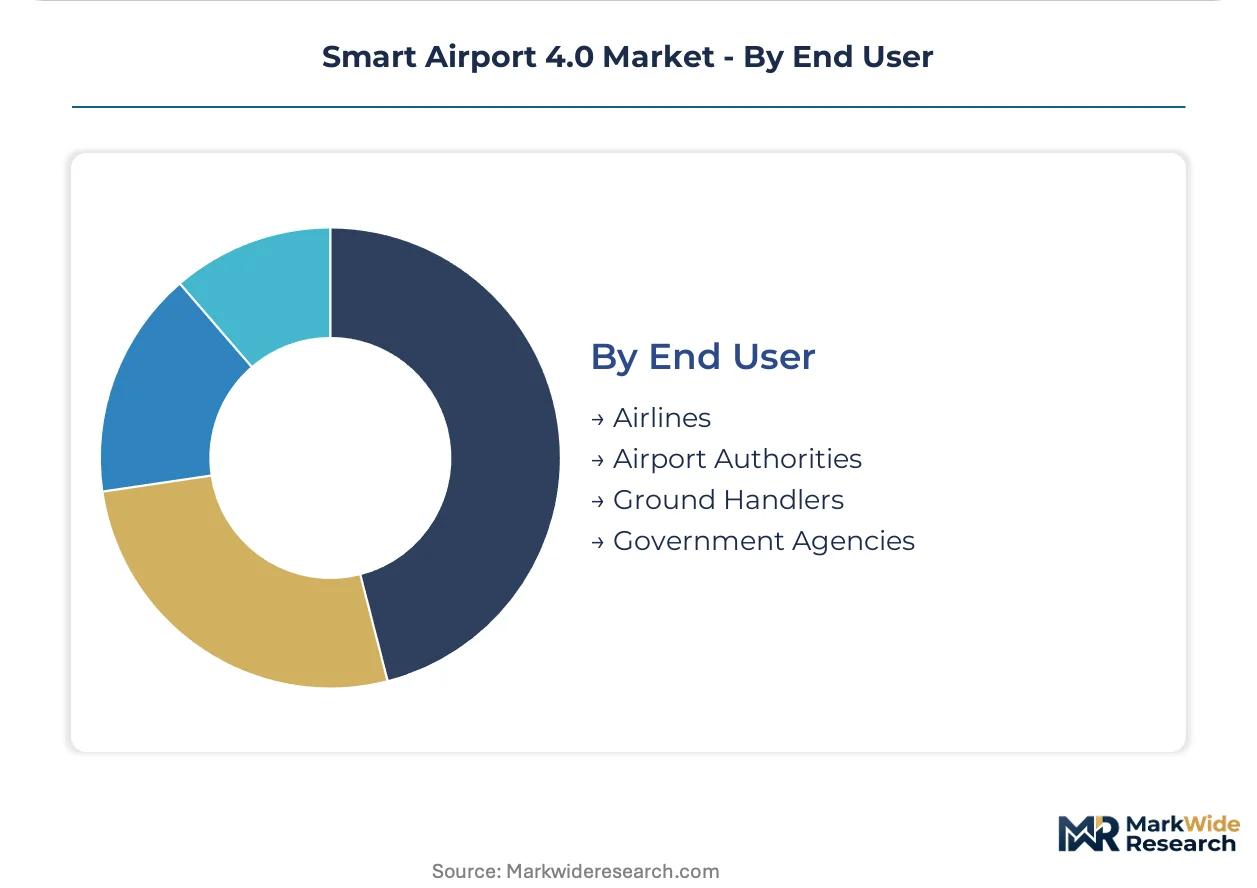
End User:
Volume concentration among mega-hub operators shapes contract scale and vendor specialization requirements.
- Airlines:Lufthansa Group and IATA members pilot smartphone-based biometric verification that shifts authentication authority away from airport-operated databases. This architecture compresses infrastructure capex while redirecting data breach liability.
- Airport Authorities:Consolidated procurement consortia accelerate technology investment centralization from local managers to group headquarters, particularly visible across Southern European airport groups recovering from pandemic-era debt stress.
- Ground Handlers:Turnaround time optimization drives demand for real-time asset tracking and automated guidance systems.
- Government Agencies:Security and customs authorities impose non-overlapping certification cycles that complicate multi-stakeholder deployment timelines.
Airport Authorities direct the majority of procurement volume; Airlines are gaining share fastest through decentralized biometric authentication pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones and airport-centric special economic districts concentrate Smart Airport 4.0 procurement across Germany, Singapore, the United Arab Emirates, the United States, and India. Mega-hub modernization programs in these jurisdictions anchor vendor investment and standard-setting.
Germany
Fraport AG's consolidated procurement authority drives system integration demand across Frankfurt Airport's expansion zones. EU AI Act certification deadlines force algorithmic audit trail investments for biometric screening infrastructure. Munich and Berlin-Brandenburg hubs front-load compliance spending to secure first-mover regulatory advantages.
Singapore
Changi Airport Group's Terminal 5 mega-project standardizes vendor specifications that cascade to Southeast Asian secondary airports. The Civil Aviation Authority of Singapore mandates unified IoT platforms rather than point solutions for environmental monitoring and asset tracking. Jurong Lake District's aerotropolis development concentrates pilot-to-production transitions for mobile biometric authentication.
United Arab Emirates
Dubai Aviation Engineering Projects and Abu Dhabi Airports Company coordinate procurement through Emirates Group holding structures. The General Civil Aviation Authority aligns federal security standards with ICAO Annex 17 requirements for automated threat detection. Dubai South's logistics corridor anchors RFID-computer vision convergence for real-time baggage tracking at transfer-heavy mega-hubs.
United States
FAA Advisory Circulars and TSA directives impose certification burdens on biometric and screening technologies before deployment. Dallas-Fort Worth and Atlanta Hartsfield-Jackson retrofit legacy terminals with AI-driven automation layers rather than greenfield construction. Silicon Valley-edge computing vendors supply distributed intelligence architectures for sub-100-millisecond safety-critical control loops.
India
Navi Mumbai, Jewar, and Mopa greenfield terminals offer vendor-neutral procurement environments without retrofit constraints. The Airports Authority of India and GMR Group coordinate technology roadmapping through public-private partnership frameworks. Maharashtra and Uttar Pradesh state industrial development corporations anchor special economic zone incentives for cyber-physical systems engineering talent recruitment.
Smart Airport 4.0 Market Competitive Landscape
Top-tier vendors anchor aviation IT integration and secure network backbone architecture, while specialized middleware providers and regional system integrators occupy fragmented lower tiers. The market exhibits tiered concentration around legacy installed base holders and cloud-native challengers. Three strategic archetypes dominate: full-stack platform vendors, component specialists in edge AI or RFID hardware, and outcome-based performance contractors. Competitive moves center on strategic partnerships for interoperability certification and portfolio diversification into predictive maintenance services.
Within the full-stack platform tier, SITA leverages decades of aviation IT integration, Honeywell International Inc. anchors building automation and airfield lighting systems, and Cisco Systems Inc. competes on secure network backbone architecture that underpins real-time data flows between IoT endpoints and central operations centers. These entities exemplify how incumbent vendors defend position through installed base relationships and regulatory certification depth.
| Leading Market Players |
|---|
| SITA |
| Cisco Systems Inc. |
| Honeywell International Inc. |
| IBM Corp |
| Raytheon Technologies |
| Siemens AG |
| Huawei Technologies Co. Ltd. |
| Smart Airport Systems SAS |
| Thales Group |
| Others |
Value Network & Pricing Analysis
Cyber-physical systems engineering talent scarcity in Germany and Singapore widens pricing-tier spreads between premium certified integrators and commodity hardware vendors. Labor-cost differentials for EU AI Act compliance specialists versus standard IT contractors compress margins at the mid-market tier while inflating premiums for certified full-stack platforms.
Pricing Analysis
Lead-time-driven pricing stratification rewards vendors with EU AI Act pre-certification and punishes those awaiting algorithmic audit trail approvals. Three-tier pricing structure across certified-premium, compliant-standard, and pending-economy levels separates Fraport-grade deployments from retrofit-constrained legacy terminals. Cost compression in the economy tier stems from semiconductor spot-market volatility and foundry allocation delays. Airport authorities with consolidated procurement authority exhibit lowest price sensitivity; independent terminal managers at secondary hubs face acute budget constraints.
Supply Chain Analysis
EU AI Act and FAA certification gating restricts qualified component sourcing to Taiwan, South Korea, and Germany for edge AI processors and specialized RFID sensor hardware. The vendor base draws from concentrated foundry capacity for neural network accelerators, precision optics for biometric corridors, and hardened IoT gateways for airfield deployment. Single-source vulnerability in Taiwan semiconductor fabrication exposes deployment timelines to geopolitical disruption. Distribution runs through aviation-specialized system integrators holding regulatory certification depth rather than direct OEM-to-airport relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU AI Act certification deadlines and semiconductor supply concentration force weaker middleware vendors toward acquisition or exit. Procurement authority centralization at Fraport, AdP, and Aena accelerates vendor shakeout.
For Market Incumbents: Anticipate margin compression from cloud-native challengers by deepening certification moats around biometric corridor deployments and predictive maintenance service contracts. Secure captive supply of edge AI processors through strategic foundry partnerships in Taiwan and South Korea. Prioritize outcome-based performance contracting to displace capital purchase models at debt-stressed Southern European airport groups.
For New Entrants and Emerging Players: Launch via system integration partnerships with established aviation IT vendors rather than direct airport authority sales cycles. Target India's greenfield airport pipeline at Navi Mumbai and Jewar where vendor-neutral procurement environments lack retrofit legacy constraints. Pursue white-space in digital twin predictive maintenance for ground handling equipment where physics-based modeling capabilities remain scarce.
For Investors and Strategic Acquirers: The window for entry favors certified middleware specialists bridging 1990s-era building automation protocols with API-based integration layers. Long-term viability hinges on regulatory certification depth rather than hardware scale. Watch for inflection when EU AI Act enforcement triggers forced replacement cycles at non-compliant legacy installations.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | Algorithmic audit trail capabilities secure first-mover advantage at Frankfurt and Munich hub expansions. |
| Edge AI Processor Supply Agreement | Foundry partnerships in Taiwan and South Korea insulate deployment timelines from geopolitical disruption. |
| Digital Twin Platform Integration | Physics-based modeling with live IoT streams enables condition-based servicing contracts at Changi Terminal 5. |
| Outcome-Based Performance Contracting | Throughput guarantees displace capital purchases at pandemic-debt-stressed Southern European airport groups. |
| Smartphone Biometric Authentication Pilot | Decentralized verification shifts liability toward device manufacturers and compresses infrastructure capex. |
Research Methodology
ICAO regulatory filings, EU AI Act implementation guidance, and airport authority procurement databases formed the secondary backbone for market sizing and competitive mapping. Primary interviews with aviation IT procurement directors, cyber-physical systems engineering leads, biometric corridor project managers, and regulatory compliance officers at Fraport, Changi Airport Group, and Dubai Aviation Engineering Projects validated technology adoption timelines and vendor selection criteria. Bottom-up terminal-level deployment tracking and top-down airport group capital expenditure analysis were triangulated against semiconductor supply chain disclosures.
Bottom-up modeling aggregated individual airport modernization programs across Germany, Singapore, United Arab Emirates, United States, and India. Segmentation dimensions included technology layer (IoT Solutions, AI Systems, Cloud Computing, Data Analytics), application (Passenger Processing, Baggage Management, Security Screening, Flight Management), and service type (Consulting, System Integration, Maintenance Support, Training). CAGRs were derived from deployment velocity curves weighted by regulatory deadline proximity and foundry capacity allocation forecasts. Industry-specific inputs incorporated EU AI Act compliance spending schedules and mega-hub expansion capex pipelines.
Semiconductor supply disruption, EU AI Act enforcement variance across member states, and passenger traffic recovery volatility are the dominant revision risks to model outputs. Forecasts embed assumptions regarding certification timeline adherence and foundry capacity expansion trajectories. A model refresh is warranted upon material change in EU AI Act implementation guidance or Taiwan Strait logistics conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Global Airport Baggage Handling System Market
Airport Technologies
Global Remote Towers Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Asia-Pacific Airport Ground Handling Systems Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Europe Smart Airport Market
Airport Technologies
Airport Baggage Conveyor System Market
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Smart Airport 3.0 Market