
 Middle-East and Africa Air Traffic Management Market | 2026-2036
Middle-East and Africa Air Traffic Management Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Air Traffic Management Market Foresight
Software-defined surveillance features are restructuring procurement patterns across Middle-East and Africa air traffic management programs. Thales Group leverages its digital tower portfolio to anchor long-term service contracts with aviation authorities in the Gulf. Honeywell International Inc. competes through integrated communication suites that extend hardware lifecycles via remote diagnostics. Raytheon Technologies Corporation dominates radar modernization bids by sustaining engineering presence in key African markets.
Middle-East and Africa air traffic management encompasses ground-based and airborne systems that coordinate aircraft movement through controlled airspace, typically integrating primary and secondary surveillance radar with multilateration and ADS-B transponder networks to maintain safe separation minima. These systems process flight data in real-time to prevent collisions, optimize routing, and manage terminal area congestion for commercial and military operators. Automation Systems command the largest installed base due to legacy air traffic control center investments, though Communication Systems represent the fastest upgrade cycle as nations replace analog voice networks with VoIP infrastructure. Deployment through Cloud-based architectures is gaining traction among mid-tier airports seeking to avoid capital-intensive on-premises installations, while Hybrid models attract major hubs requiring local redundancy with remote backup.
The UAE's General Civil Aviation Authority and Saudi Arabia's General Authority of Civil Aviation enforce equipment certifications that align with ICAO Annex 10 standards, creating compliance barriers for non-compliant suppliers. South Africa's Civil Aviation Authority applies additional technical directives for surveillance accuracy that shape regional product specifications. Stakeholders must weigh sovereign data requirements against cloud migration timelines when structuring service agreements across jurisdictions with diverging regulatory maturity.
Market Dynamics
Software-defined architectures are restructuring procurement patterns across Middle-East and Africa air traffic management programs, as aviation authorities prioritize interoperability over proprietary hardware lock-in.
Growth Catalysts
- ICAO Annex 10 alignment mandates:The UAE's General Civil Aviation Authority requires equipment certifications that match international standards, forcing system upgrades across Gulf airports.
- Hub airport expansion:Saudi Arabia's General Authority of Civil Aviation is driving capacity increases at Jeddah and Riyadh terminals, generating demand for integrated tower systems.
- VoIP infrastructure replacement:Analog voice networks across African control centers are reaching end-of-life, creating immediate procurement windows for digital communication suites.
Market Restraints
- Capital intensity of radar modernization:Primary surveillance radar upgrades require substantial upfront investment, constraining mid-tier African airports with limited fiscal capacity.
- Supply concentration in European vendors:Critical sensor components originate from concentrated manufacturing bases in France and Germany, exposing programs to currency fluctuation risk.
- Technical limitation of legacy integration:Existing automation systems at Cairo and Johannesburg centers use proprietary protocols that resist seamless interface with modern surveillance networks.
Strategic Opportunities
- Underpenetrated East African corridors:Ethiopia and Kenya are expanding Addis Ababa and Nairobi hub roles, creating greenfield demand for multilateration systems.
- Cloud-based service models:Mid-tier airports in Morocco and Tunisia are bypassing capital-intensive on-premises installations through subscription-based remote tower architectures.
- Regulatory tailwind from South African technical directives:Enhanced surveillance accuracy requirements are mandating ADS-B ground station deployment across SADC member states.
Industry Challenges
- Certification timeline compression:ICAO compliance deadlines for ground-based augmentation systems are forcing concurrent engineering and validation cycles that strain quality assurance resources.
- Integration complexity with 1980s-era host computers:Flight data processing systems at legacy centers in Egypt and Nigeria require custom middleware development for ADS-B data fusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Air Traffic Management Market |
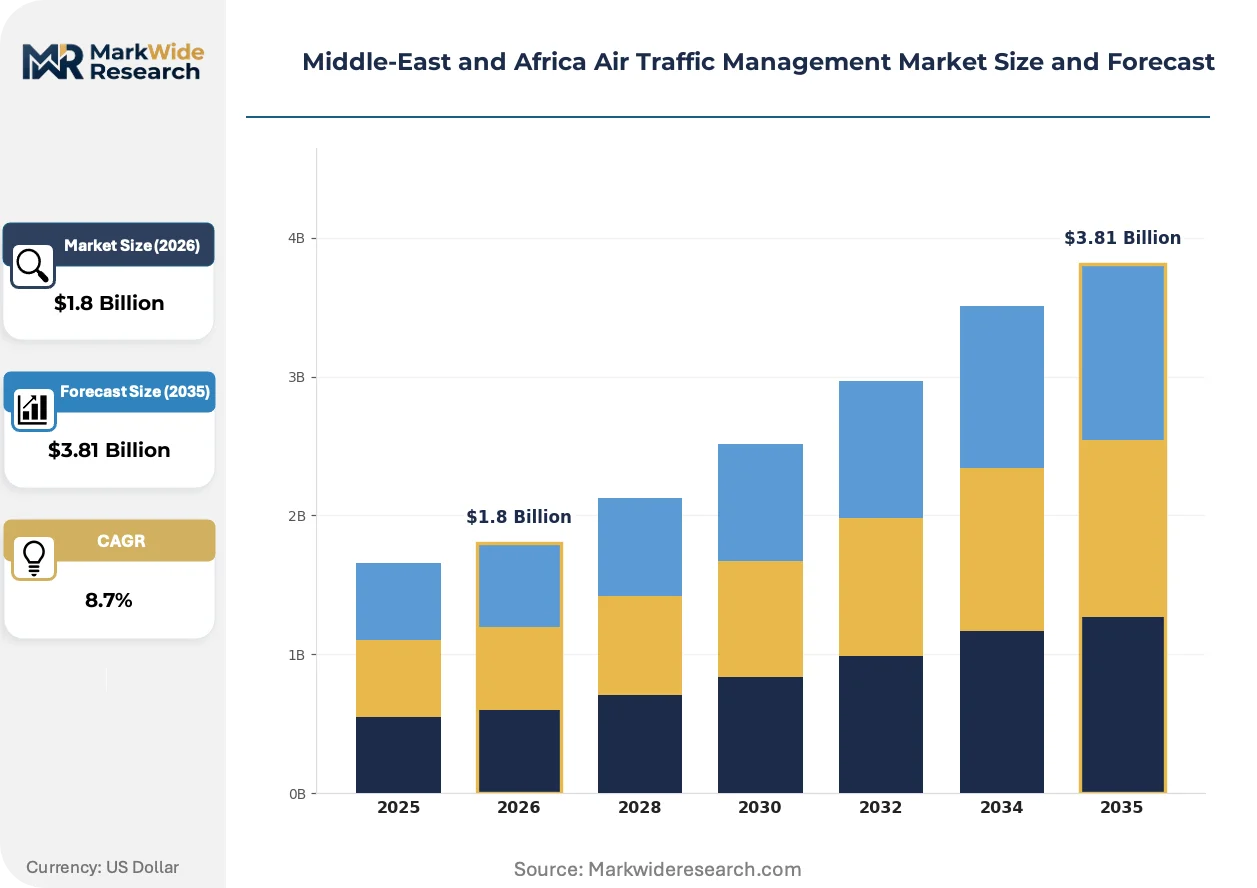
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automation Systems, Communication Systems, Navigation Systems, Surveillance Systems End User: Airports, Airlines, Military, Aviation Authorities Deployment: Cloud-based, On-premises, Hybrid, Managed Services Technology: Artificial Intelligence, Machine Learning, Data Analytics, Internet of Things |
| Companies Covered | Thales Group, Honeywell International Inc., Raytheon Technologies Corporation, Leonardo S.p.A., Indra Sistemas S.A., L3Harris Technologies Inc., Elbit Systems Ltd., Frequentis AG, Saab AB, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Air Traffic Management Market Shifts & Advancements
Digital tower technology is absorbing engineering investment across the region's modernization programs, compressing the traditional radar-centric procurement model.
Remote tower platforms are absorbing controller workstation functions previously requiring physical infrastructure. Gulf aviation authorities are adopting these systems at secondary airports to maintain service during primary tower construction. The technology is absorbing capital budgets that previously funded brick-and-mortar facilities, enabling faster deployment timelines.
South Africa's Civil Aviation Authority has issued technical directives for surveillance accuracy that exceed baseline ICAO requirements. These specifications are reshaping product roadmaps for radar suppliers active in the SADC region. Equipment vendors are responding with enhanced multilateration algorithms tailored to Johannesburg and Cape Town approach corridors.
Buyer preference is compressing toward integrated service contracts rather than discrete hardware purchases. Saudi and UAE aviation authorities are unbundling long-term maintenance from initial system procurement, forcing vendors to restructure revenue recognition. This pattern is most visible in digital tower deployments where authorities prioritize operational availability guarantees over equipment ownership.
Middle-East and Africa Air Traffic Management Market Segmentation
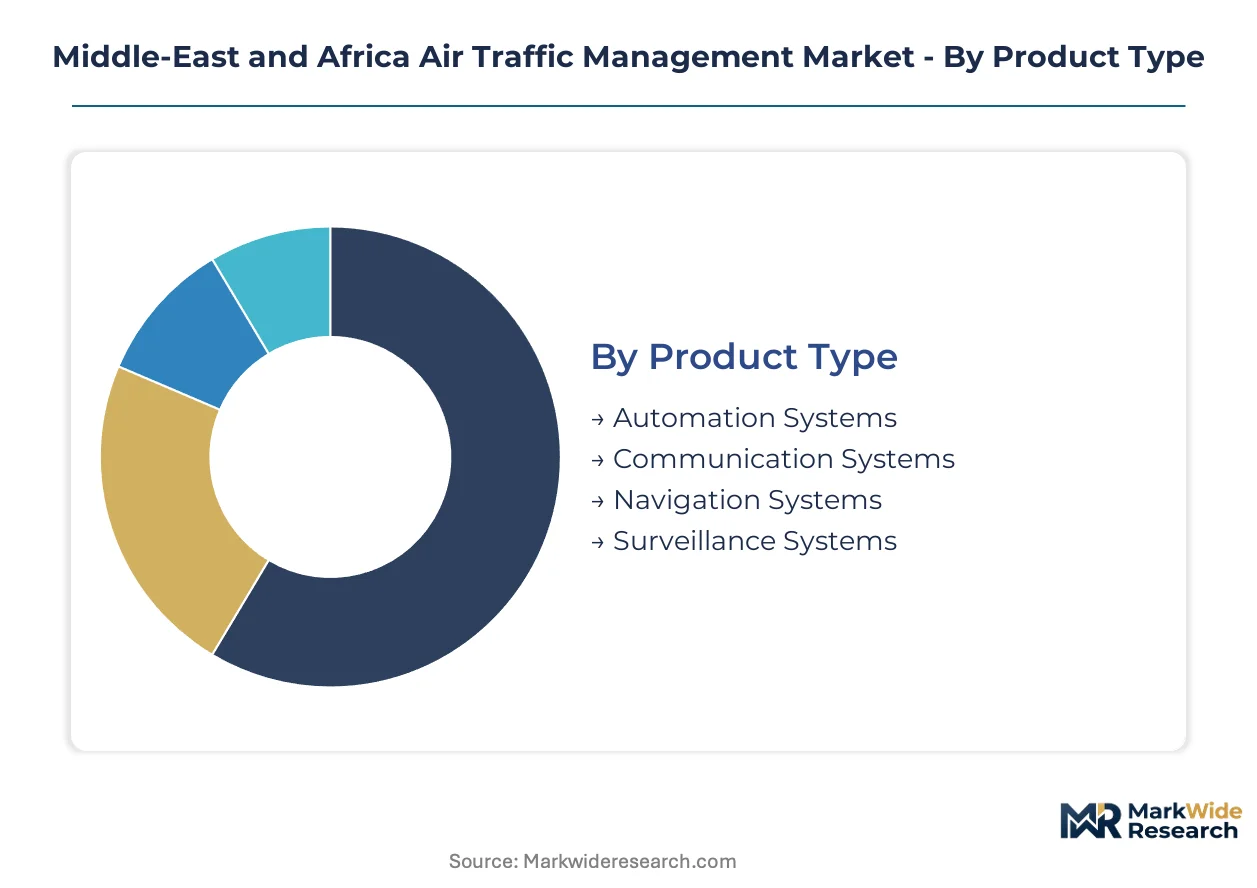
Segmentation in Middle-East and Africa air traffic management reveals how procurement priorities diverge between legacy infrastructure defenders and digital-first adopters. Aviation authorities structure vendor selection around integration depth, operational sovereignty, and regulatory compliance timelines.
Product Type:
Standardization pressures from ICAO Annex 10 compete with customization demands from legacy system architectures across this category.
- Automation Systems:Flight data processing platforms coordinate aircraft separation through centralized control centers. Demand concentrates at Cairo and Johannesburg hubs where 1980s-era host computers require middleware bridges for ADS-B fusion. Integration complexity sustains premium pricing for vendors capable of protocol translation.
- Communication Systems:VoIP infrastructure replaces analog voice networks across African control centers. Procurement windows in Nigeria and Kenya are accelerating as end-of-life equipment failures disrupt operations. This segment is expanding most quickly due to immediate replacement imperatives.
- Navigation Systems:Ground-based augmentation systems and GBAS installations align with ICAO performance-based navigation mandates.
- Surveillance Systems:Primary and secondary radar installations, multilateration networks, and ADS-B ground stations maintain separation minima.
Leading the category by volume: Automation Systems. Climbing the fastest: Communication Systems.
End User:
Volume concentration tracks hub airport expansion cycles, with procurement authority fragmenting between facility operators and national regulators.
- Airports:Terminal area management systems integrate tower automation with ground surveillance. Jeddah and Riyadh expansions under Saudi Arabia's General Authority of Civil Aviation are generating integrated tower system demand. Digital tower deployments at secondary Gulf airports compress traditional construction timelines.
- Aviation Authorities:National regulators mandate equipment certifications and oversee airspace-wide system procurement. The UAE's General Civil Aviation Authority enforces ICAO-aligned standards that shape vendor qualification across Gulf programs. Sovereign data requirements complicate cloud migration timelines.
- Airlines:Fleet operators invest in airborne equipage for ADS-B Out compliance and performance-based navigation capabilities.
- Military:Dual-use airspace coordination requires hardened communication links and encrypted surveillance data distribution.
Dominant procurement authority: Aviation Authorities. Fastest budget expansion: Airports.
Deployment:
Capital availability and data sovereignty concerns create a bifurcated adoption curve across deployment models.
- On-premises:Traditional capital-intensive installations maintain local redundancy for primary hub operations. Major airports in Saudi Arabia and the UAE require physical infrastructure ownership to satisfy sovereign control mandates. High upfront investment constrains mid-tier African facility adoption.
- Cloud-based:Subscription architectures enable mid-tier airports in Morocco and Tunisia to bypass capital expenditure barriers. Remote tower platforms absorb controller workstation functions previously requiring brick-and-mortar construction. Operational availability guarantees replace equipment ownership in procurement evaluation.
- Hybrid:Combined local and remote redundancy attracts major hubs seeking operational continuity guarantees.
- Managed Services:Long-term maintenance unbundling from initial procurement restructures vendor revenue recognition across Gulf programs.
Widest installed base: On-premises. Steepest adoption trajectory: Cloud-based.
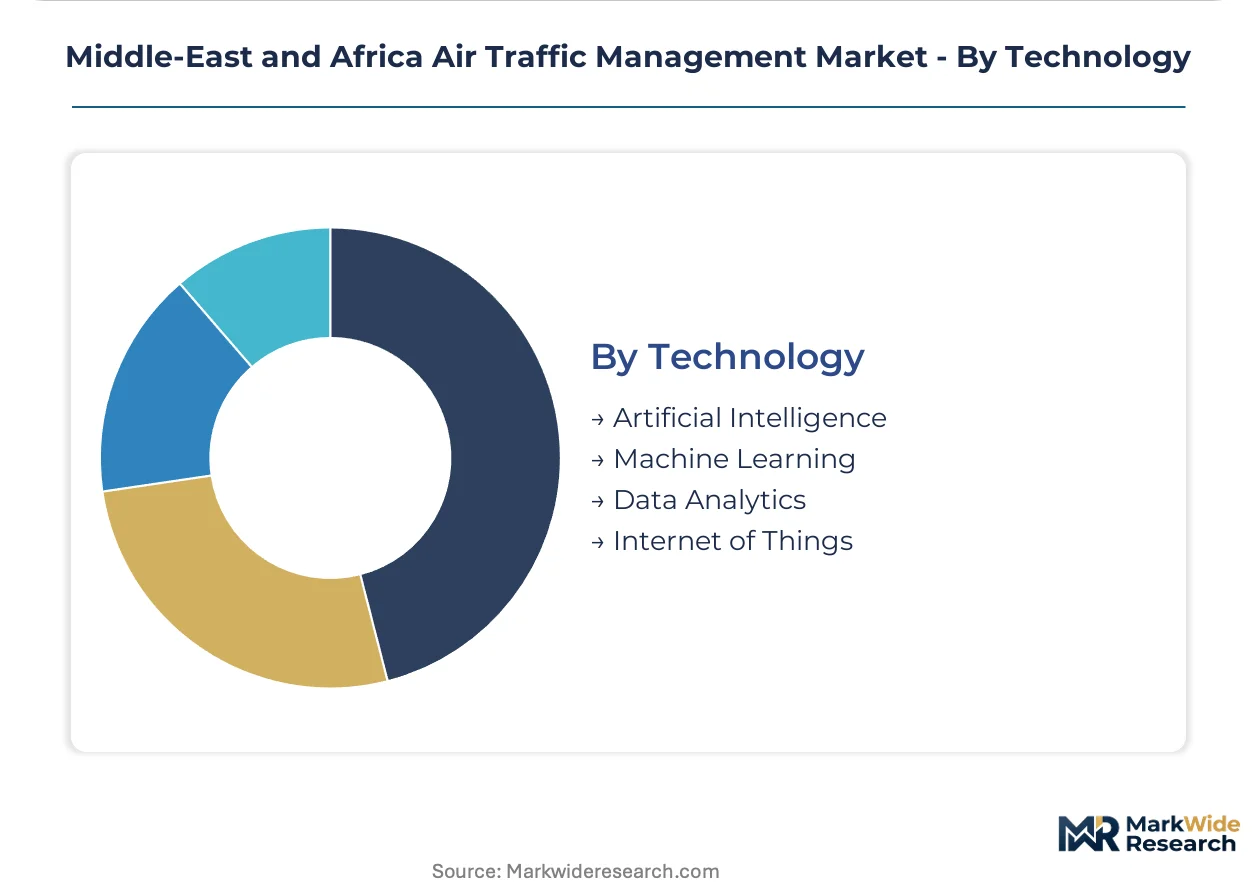
Technology:
Maturity gaps between proven operational tools and experimental applications shape investment sequencing.
- Data Analytics:Flight trajectory optimization and congestion prediction algorithms process real-time surveillance feeds. South Africa's Civil Aviation Authority technical directives for enhanced surveillance accuracy are mandating algorithmic improvements across SADC member states. Predictive maintenance applications extend hardware lifecycles.
- Artificial Intelligence:Machine learning models for conflict detection and resolution advisory systems are entering validation cycles. Concurrent engineering and certification timelines strain quality assurance resources as ICAO compliance deadlines approach. Early deployments concentrate in greenfield East African corridor installations.
- Machine Learning:Pattern recognition systems augment controller decision support in high-density terminal areas.
- Internet of Things:Sensor networks for ground infrastructure monitoring and environmental condition tracking support predictive maintenance.
Most mature operational deployment: Data Analytics. Fastest capability advancement: Artificial Intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
System integration concentrates in Gulf aviation authorities while procurement demand spreads across East African corridors. The production of surveillance hardware remains concentrated in European manufacturing bases, forcing regional buyers to absorb currency fluctuation risk. Consumption patterns diverge between sovereign-controlled hub airports and subscription-seeking mid-tier facilities.
United Arab Emirates
The UAE's General Civil Aviation Authority mandates ICAO Annex 10 alignment for all ground-based augmentation systems, driving procurement at Dubai and Abu Dhabi international airports. The regulator enforces equipment certifications that shape vendor qualification across Gulf programs. Dubai's secondary airports are deploying digital tower platforms to maintain operations during primary facility construction.
Saudi Arabia
Saudi Arabia's General Authority of Civil Aviation is expanding Jeddah and Riyadh terminal capacity, generating integrated tower system demand. The authority unbundles long-term maintenance from initial procurement, restructuring vendor revenue recognition. NEOM's northwest development is incorporating remote tower architectures from project inception rather than retrofitting legacy infrastructure.
South Africa
South Africa's Civil Aviation Authority applies technical directives for surveillance accuracy that exceed baseline ICAO requirements. These specifications mandate ADS-B ground station deployment across SADC member states. Johannesburg and Cape Town approach corridors are driving enhanced multilateration algorithm development from equipment vendors.
Egypt
Egypt's legacy flight data processing systems at Cairo centers use proprietary protocols that resist seamless interface with modern surveillance networks. The country's national aviation regulator is compressing certification timelines for ground-based augmentation systems. Cairo International Airport requires custom middleware development for ADS-B data fusion with 1980s-era host computers.
Kenya
Kenya is expanding Nairobi's hub role for East African corridors, creating greenfield demand for multilateration systems. The national civil aviation authority is accelerating VoIP infrastructure replacement as analog voice networks reach end-of-life. Jomo Kenyatta International Airport is absorbing capital budgets previously allocated to brick-and-mortar facilities through digital tower deployments.
Middle-East and Africa Air Traffic Management Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Middle-East and Africa air traffic management landscape. European radar manufacturers maintain concentrated manufacturing bases in France and Germany, while software-defined specialists deploy subscription architectures without physical infrastructure ownership. The market structure fragments between sovereign-system integrators, component specialists, and remote-service platforms. Dominant competitive moves include long-term service contract unbundling from hardware procurement and cloud-based subscription models that bypass capital expenditure barriers.
Within the sovereign-system integrator tier, Thales Group and Raytheon Technologies Corporation exemplify vendors anchoring long-term aviation authority relationships. Thales leverages its digital tower portfolio to secure operational availability guarantees rather than discrete equipment sales. Raytheon sustains engineering presence across key African markets to dominate radar modernization bids. Honeywell International Inc. occupies a position competing through integrated communication suites that extend hardware lifecycles via remote diagnostics, representing the component-specialist archetype focused on VoIP infrastructure replacement cycles.
| Leading Market Players |
|---|
| Thales Group |
| Honeywell International Inc. |
| Raytheon Technologies Corporation |
| Leonardo S.p.A. |
| Indra Sistemas S.A. |
| L3Harris Technologies Inc. |
| Elbit Systems Ltd. |
| Frequentis AG |
| Saab AB |
| Others |
Supply & Pricing Matrix
Buyer preference for operational availability guarantees over equipment ownership is compressing vendor revenue models across Gulf aviation authorities. This shift toward integrated service contracts forces suppliers to absorb lifecycle cost risks while repositioning pricing structures around performance metrics rather than capital recovery timelines.
Pricing Analysis
Margin tightening in mid-tier African airports reflects constrained fiscal capacity for primary surveillance radar upgrades. Pricing stratifies across ICAO-certified, SADC-enhanced, and baseline compliance tiers, with certification level and after-sales service bundling as primary differentiation drivers. Cost compression accelerates as subscription-based remote tower architectures displace traditional capital-intensive procurement. Aviation authorities in Morocco and Tunisia exhibit highest price sensitivity, while Saudi Arabia's General Authority of Civil Aviation demonstrates lowest sensitivity due to sovereign-backed hub expansion budgets.
Supply Chain Analysis
Freight costs for radar sensor components from France and Germany amplify total landed cost volatility for regional buyers. Manufacturing concentrates in European bases, with critical inputs including gallium nitride semiconductors, precision antenna arrays, and specialized software modules drawing from concentrated supplier networks. Single-source vulnerability in precision sensor fabrication exposes programs to currency fluctuation risk. Distribution runs through sovereign aviation authority procurement channels with extended validation cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICAO Annex 10 alignment mandates erect compliance barriers that favor incumbent vendors with established certification track records, creating sustainable moats against unqualified competitors.
For Market Incumbents: Deepen engineering presence in Addis Ababa and Nairobi to anchor multilateration system deployments across expanding East African corridors. Fortify protocol translation capabilities for 1980s-era host computer integration at Cairo and Johannesburg centers. Invest in enhanced multilateration algorithms tailored to South Africa's Civil Aviation Authority technical directives to defend against specialized surveillance suppliers. For New Entrants and Emerging Players: The price-point gap between premium European radar systems and economy-tier analog replacements creates entry space for software-defined surveillance specialists. Target cloud-based remote tower deployments in Morocco and Tunisia where capital constraints block traditional on-premises procurement. Pursue subscription revenue models with operational availability guarantees to bypass sovereign data hesitation. For Investors and Strategic Acquirers: The window for entry favors component specialists with VoIP infrastructure expertise and established ICAO certification pathways. Long-term viability hinges on positioning against analog voice network replacement cycles across African control centers. Monitor ADS-B ground station deployment velocity across SADC member states as inflection indicator for surveillance accuracy mandate adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Tower Platform Integration | Compresses construction timelines at Dubai secondary airports while enabling remote operations during primary facility upgrades. |
| VoIP Infrastructure Replacement | Captures end-of-life procurement windows across Nigerian and Kenyan control centers with immediate operational imperatives. |
| Enhanced Multilateration Algorithm Development | Aligns product roadmaps with South Africa's Civil Aviation Authority surveillance accuracy mandates across SADC markets. |
| Cloud-Based Service Model Expansion | Bypasses capital expenditure barriers for mid-tier Moroccan and Tunisian airports seeking operational availability guarantees. |
| Legacy System Middleware Investment | Enables ADS-B data fusion with 1980s-era host computers at Cairo and Johannesburg centers requiring custom protocol bridges. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with air traffic control center directors, aviation authority procurement officers, radar system engineers, and airline fleet planning executives combined with ICAO implementation reports, national civil aviation authority certification databases, and equipment vendor technical disclosures. Bottom-up installation tracking and top-down market sizing triangulated volume estimates across deployment models and technology categories.
Granularity-level modeling addressed product type, end user, deployment architecture, and technology maturity across national regulatory clusters. CAGRs derived from installation pipeline analysis and replacement cycle timing throughout the projection horizon. Forecast inputs incorporated ICAO compliance deadline schedules, hub airport expansion timelines, and analog network end-of-life failure rates.
Inputs from aviation authority procurement disclosures and equipment certification registries were available through the study window; gaps in proprietary vendor pricing data introduce uncertainty bands around service revenue projections. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and sovereign budget allocation continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
Global Aircraft Antenna Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Aircraft Interface Device Market
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
Aircraft Navigation System Market
Aircraft Navigation and Communication
Global Flight Navigation System Market
Aircraft Navigation and Communication
Air Traffic Management Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Aircraft Navigation Software Market