
 Airborne Situational Awareness Systems Market | 2026-2036
Airborne Situational Awareness Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne Situational Awareness Systems Market Outlook
Defense electronics manufacturing in the United States is broadening as prime contractors scale sensor integration capacity. Lockheed Martin leverages vertical integration across radar and electro-optical product lines to sustain long-term program margins. RTX Corporation anchors its position through R&D intensity in distributed aperture systems. BAE Systems plc competes on trans-Atlantic program access, with significant manufacturing presence in the United Kingdom and United States.
Airborne situational awareness systems comprise integrated sensor, processing, and display architectures that fuse radar returns, electro-optical imagery, infrared signatures, and LiDAR point clouds into unified threat and terrain pictures for flight crews; typical specifications include multi-spectral sensor coverage from ultraviolet through long-wave infrared, real-time processing latencies below 100 milliseconds, and MIL-STD-1553 or Ethernet-based data bus integration for platform interoperability. Radar systems and sensor suites command the largest revenue share due to platform retrofit cycles and sovereign defense procurement schedules, while electro-optical and LiDAR technology segments attract disproportionate engineering investment as unmanned platforms proliferate. Display systems remain a mature margin pool where specialized vendors occupy entrenched cockpit certification positions.
FAA certification requirements under Title 14 CFR and EU MDR standards for airborne electronics shape product development timelines and market access conditions for non-domestic suppliers. The Department of Defense mandates MIL-STD-810 environmental qualification and MIL-STD-461 electromagnetic compatibility, creating compliance barriers that favor incumbent prime contractors with established test infrastructure. Stakeholders must monitor evolving certification reciprocity agreements between the FAA and EASA, as divergence in software assurance standards could fragment supplier qualification pathways and alter competitive dynamics for cross-border platform integrations.
Market Dynamics
Fleet modernization cycles and sovereign defense procurement schedules are compressing supplier qualification timelines while elevating performance thresholds for integrated sensor architectures.
Growth Catalysts
- FAA NextGen Mandates:The Federal Aviation Administration's Next Generation Air Transportation System mandates are accelerating avionics retrofit programs across commercial and military operator fleets, creating sustained demand for certified display and processing systems.
- Unmanned Platform Proliferation:Defense operators are expanding unmanned aerial vehicle procurement for intelligence, surveillance, and reconnaissance missions, driving engineering investment into electro-optical and LiDAR sensor miniaturization.
- EU MDR Certification Pathways:The European Union's Medical Device Regulation framework for airborne electronics is streamlining cross-border market access for qualified suppliers, reducing duplicate testing burdens for dual-use technologies.
Market Restraints
- Gallium Nitride Substrate Costs:Advanced radar systems depend on gallium nitride semiconductors where supply concentrates among a limited base of foundry operators, creating input cost volatility and allocation risk.
- MIL-STD-810 Qualification Barriers:Department of Defense environmental testing requirements demand specialized climatic and dynamic test infrastructure that excludes smaller suppliers from prime contractor supply chains.
- Electro-Optical Substitution Pressure:Synthetic aperture radar capabilities are encroaching on traditional electro-optical sensor mission sets in all-weather reconnaissance applications, compressing addressable market scope for infrared specialists.
Strategic Opportunities
- Urban Air Mobility Integration:Advanced air mobility platforms in the United States are creating demand for lightweight, low-latency situational awareness architectures that incumbent defense suppliers can adapt from military product lines.
- Sensor Fusion Convergence:The integration of machine learning inference engines with multi-spectral data streams is opening performance tiers previously unreachable with conventional processing architectures.
- India Defense Procurement Liberalization:India's defense offset and indigenization policies are creating partnership pathways for foreign subsystem suppliers to establish local integration and test facilities.
Industry Challenges
- Cleared Workforce Scarcity:Security clearance requirements for program access restrict the available talent pool for software assurance and systems integration roles, extending hiring cycles for classified development efforts.
- Legacy Platform Integration Complexity:Retrofit programs for aging military aircraft must reconcile modern Ethernet-based sensor architectures with existing MIL-STD-1553 data buses, multiplying engineering validation effort.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne Situational Awareness Systems Market |
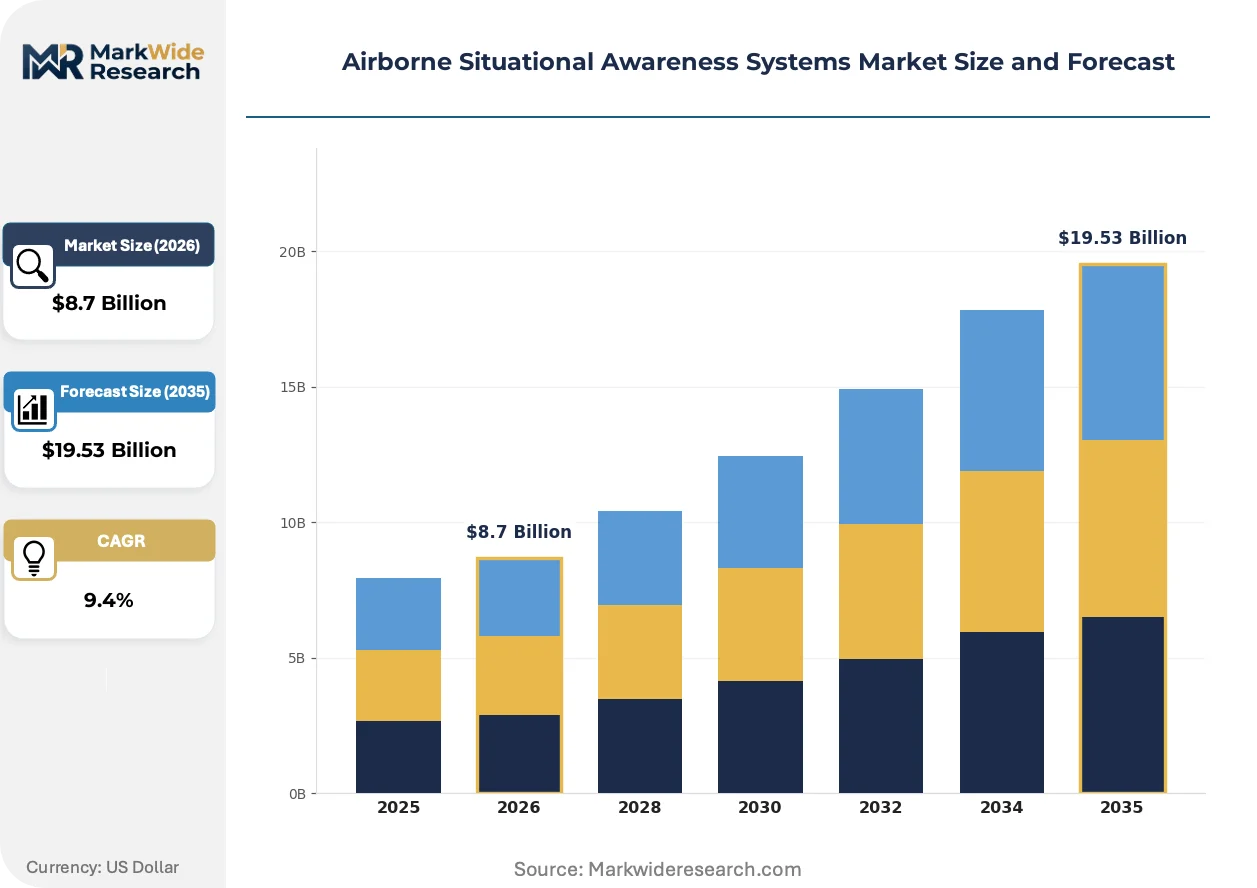
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Systems, Sensor Suites, Communication Equipment, Display Systems End User: Military, Commercial Aviation, Drones, Private Aircraft Technology: Electro-Optical, LiDAR, Synthetic Aperture Radar, IR Sensors Application: Surveillance, Navigation, Threat Detection, Situational Awareness |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, BAE Systems plc, Leonardo S.p.A, Northrop Grumman Corporation, Elbit Systems Ltd., Saab AB, L3Harris Technologies Inc., Thales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne Situational Awareness Systems Market Strategic Shifts
Processing architectures and certification frameworks are undergoing parallel transformation as distributed computing and software assurance standards reshape product development economics.
Edge inference computing is decentralizing sensor data processing from centralized mission computers to individual sensor nodes. Military platform integrators are adopting this architecture to reduce latency and single-point-of-failure risk. The shift is compressing hardware consolidation timelines while elevating thermal management and power distribution requirements across the supply base.
EU MDR software assurance standards are tightening validation requirements for airborne electronics with safety-critical functions. Manufacturers must now demonstrate traceability from requirements through verification for all software components. Commercial-off-the-shelf sensor suppliers serving dual-use markets are responding by segregating product lines between civil-certification and military-qualification variants.
Defense procurement offices are consolidating subsystem awards into platform-level system integrator contracts. Prime contractors are absorbing sensor and display procurement decisions previously executed by airframe operators. This concentration is most visible in United States Department of Defense programs, where Lockheed Martin and RTX Corporation are capturing expanded scope through long-term sustainment arrangements.
Airborne Situational Awareness Systems Market Segmentation
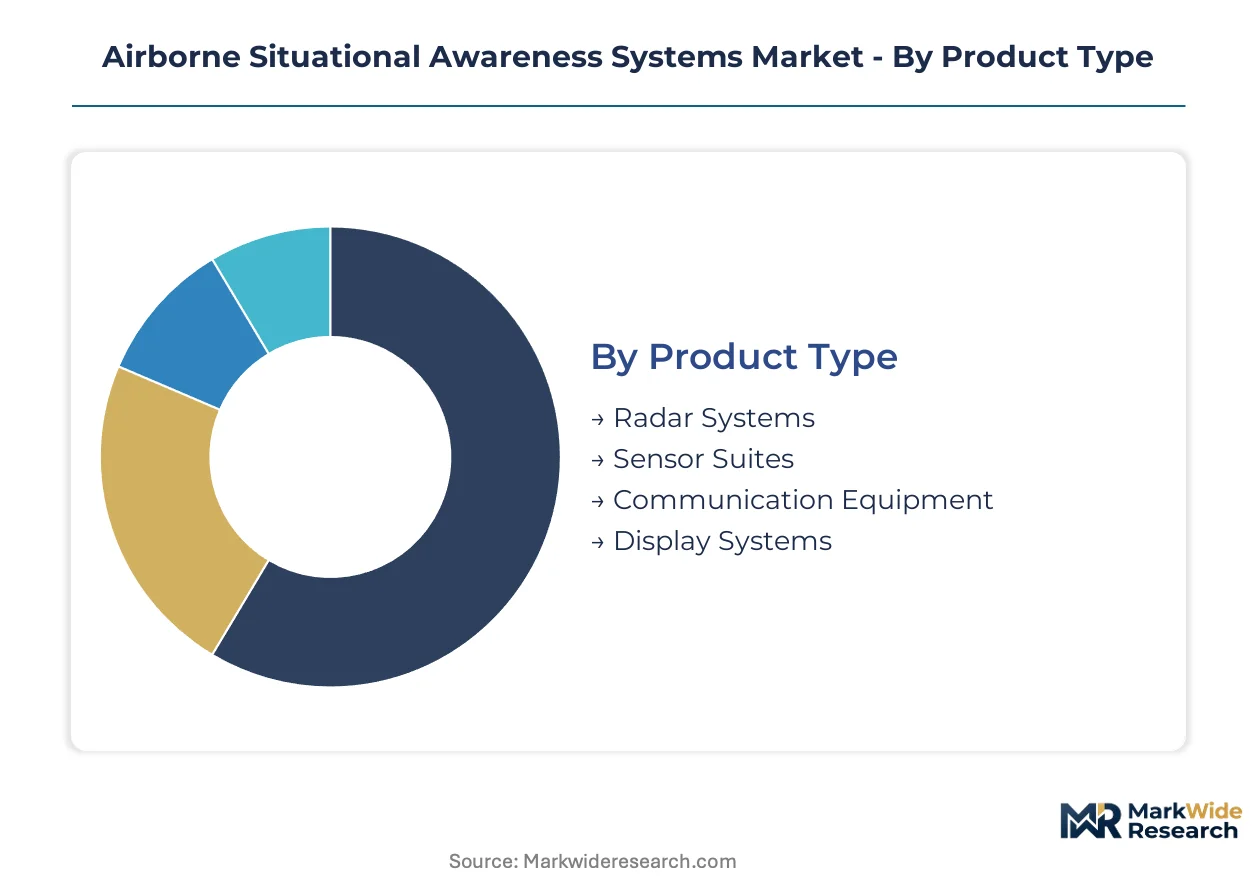
Segmentation in airborne situational awareness systems reveals distinct procurement patterns across defense and civil aviation channels. Platform certification requirements and mission profiles create divergent specification demands that reshape supplier positioning across each category.
Product Type:
Defense procurement officers prioritize integration depth over unit cost, while commercial operators balance acquisition expense against retrofit timeline constraints.
- Radar Systems:Active electronically scanned arrays and mechanically steered platforms deliver weather penetration, terrain mapping, and air-to-air detection capabilities. The United States Department of Defense sustains demand through F-35 and F/A-18 fleet modernization programs, though gallium nitride substrate supply constraints inflate program costs.
- Sensor Suites:Integrated multi-spectral architectures fuse electro-optical, infrared, and radar feeds into unified tactical pictures for flight crews. European NATO members are accelerating procurement of distributed aperture systems for Eurofighter and Rafale platforms under collective defense spending commitments.
- Communication Equipment:Secure datalinks and tactical radios enable platform-to-platform information sharing across contested electromagnetic environments.
- Display Systems:Head-down and helmet-mounted cueing systems present fused sensor data to pilots with latency thresholds below 100 milliseconds.
Radar Systems lead volumes today; Sensor Suites are gaining share fastest.
End User:
Budget authorization cycles and operational tempo differentiate procurement velocity across customer categories.
- Military:Sovereign defense departments fund platform-integrated situational awareness architectures through multi-year appropriations. The United States Navy's Next Generation Jammer and Air Force F-15EX programs exemplify sustained investment in crewed platform sensor modernization despite unmanned system expansion.
- Commercial Aviation:FAA NextGen mandates compel avionics upgrades for terrain awareness, traffic collision avoidance, and synthetic vision across Part 121 and Part 135 operator fleets. United Airlines and Delta Air Lines have accelerated retrofit schedules to meet ADS-B Out equipage deadlines.
- Drones:Unmanned platforms demand miniaturized, low-power sensor packages for intelligence, surveillance, and reconnaissance missions.
- Private Aircraft:Owner-operators select portable or panel-mount systems based on IFR certification requirements and hangar cost constraints.
Military dominates absolute spending; Drones are expanding most quickly.
Technology:
Physics-based performance tradeoffs between all-weather capability and resolution precision determine technology selection for specific mission profiles.
- Electro-Optical:Visible-spectrum and near-infrared imagers provide high-resolution target identification under daylight and marginal night conditions. Israeli Defense Forces procurement of electro-optical/infrared turrets for persistent surveillance missions sustains engineering investment in stabilized gimbal architectures.
- LiDAR:Pulsed laser ranging generates dense three-dimensional point clouds for terrain mapping, obstacle detection, and precision landing in degraded visual environments. Urban air mobility developers in California and Texas are integrating solid-state LiDAR for autonomous navigation in complex airspace.
- Synthetic Aperture Radar:Coherent radar processing achieves fine spatial resolution independent of platform altitude or weather conditions.
- IR Sensors:Mid-wave and long-wave infrared detectors reveal thermal signatures obscured to visible-spectrum systems.
Electro-Optical holds installed base leadership; LiDAR shows steepest expansion trajectory.
Application:
Mission-criticality thresholds and regulatory certification pathways segment demand across operational use cases.
- Surveillance:Wide-area and spot-mode sensor configurations support intelligence collection, border monitoring, and maritime domain awareness. United Kingdom Royal Air Force Protector RG1 procurement exemplifies investment in persistent surveillance architectures for overland and littoral operations.
- Navigation:Terrain-referenced navigation and GPS-denied positioning systems ensure platform safety in contested or signal-degraded environments. Australian Defence Force helicopter fleet upgrades emphasize multi-sensor navigation suites for brownout and whiteout landing conditions.
- Threat Detection:Radar warning receivers, missile approach warners, and laser detection systems alert crews to hostile engagement.
- Situational Awareness:Cockpit display integration and sensor fusion engines synthesize multi-source data into actionable crew information.
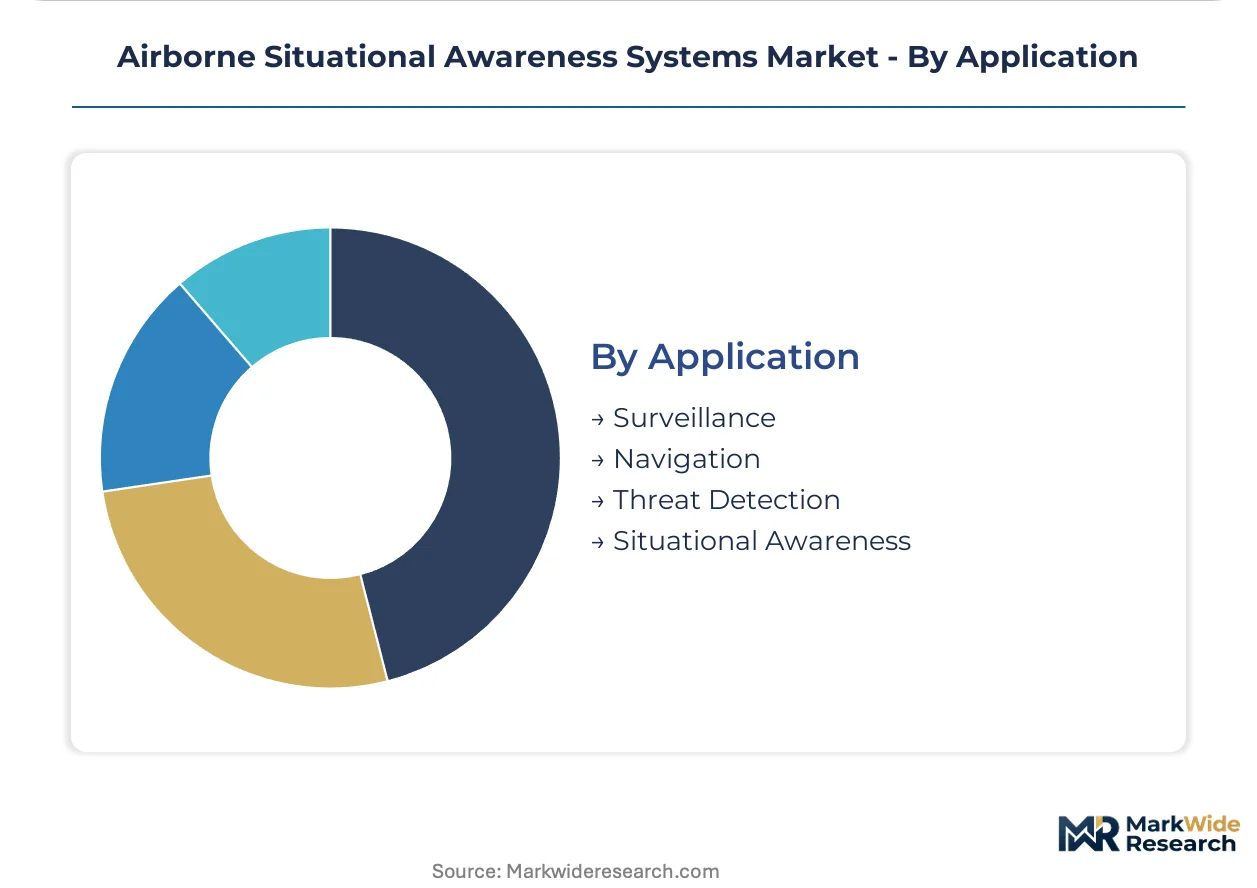
Surveillance commands revenue concentration today; Navigation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping supplier footprints as certification cost differentials between jurisdictions influence where subsystem integration and test facilities locate. Production capacity migrates toward markets with established defense procurement channels and reciprocal certification agreements.
United States
The Department of Defense sustains the largest defense procurement channel globally through F-35 and F/A-18 fleet modernization programs. FAA NextGen mandates under Title 14 CFR compel avionics retrofits across commercial operator fleets. Lockheed Martin and RTX Corporation anchor sensor integration capacity in Texas and Maryland industrial corridors.
United Kingdom
Royal Air Force Protector RG1 procurement exemplifies sustained investment in persistent surveillance architectures for overland and littoral operations. UK defense offset policies under the Strategic Defence Review streamline foreign supplier qualification pathways. BAE Systems plc maintains significant manufacturing presence across Lancashire and Bristol aerospace clusters.
Germany
Luftwaffe Eurofighter platform upgrades drive demand for distributed aperture systems under collective NATO defense spending commitments. EU MDR certification requirements for airborne electronics standardize validation protocols across member states. Sensor subsystem suppliers concentrate in Bavaria and Baden-Württemberg precision engineering corridors.
Israel
Israel Defense Forces procurement of electro-optical and infrared turrets for persistent surveillance missions sustains engineering investment in stabilized gimbal architectures. Israeli national security regulations mandate domestic content thresholds for critical defense subsystems. Elbit Systems Ltd. anchors electro-optical development in Haifa and Beersheba technology zones.
India
Indian Air Force fleet expansion and indigenization policies create partnership pathways for foreign subsystem suppliers establishing local integration facilities. Defence Procurement Procedure offset requirements mandate technology transfer for foreign prime contractors. Defense electronics manufacturing clusters concentrate in Bengaluru and Hyderabad with DRDO test infrastructure proximity.
Airborne Situational Awareness Systems Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue unmanned platform miniaturization and urban air mobility sensor architectures. The vendor base stratifies across three tiers: prime contractors with platform-level integration authority, specialized subsystem suppliers with cockpit certification entrenchment, and component-level vendors serving dual-use commercial markets. Two dominant competitive moves define current positioning: prime contractors absorbing sensor procurement decisions through long-term sustainment arrangements, and electro-optical specialists diversifying into LiDAR through strategic technology licensing.
Within the prime contractor tier, Lockheed Martin Corporation and RTX Corporation exemplify platform-level system integrators capturing expanded scope through vertical integration across radar and electro-optical product lines. BAE Systems plc occupies a trans-Atlantic position leveraging manufacturing presence in both United Kingdom and United States defense procurement channels.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| BAE Systems plc |
| Leonardo S.p.A |
| Northrop Grumman Corporation |
| Elbit Systems Ltd. |
| Saab AB |
| L3Harris Technologies Inc. |
| Thales |
| Others |
Value Chain & Pricing Dynamics
Gallium nitride substrate costs cascade through radar system pricing tiers, concentrating margin pressure on active electronically scanned array manufacturers serving F-35 and F/A-18 fleet modernization programs while elevating procurement leverage for prime contractors with captive foundry arrangements.
Pricing Analysis
Distributor margins compress as prime contractors consolidate sensor procurement decisions under platform-level system integrator contracts. Pricing stratifies across MIL-STD-810 qualified, EU MDR certified, and commercial-off-the-shelf tiers, with certification investment acting as the primary price differentiation driver. Cost compression in electro-optical sensor lines is intensifying because synthetic aperture radar capabilities encroach on traditional infrared mission sets. Commercial aviation operators exhibit highest price sensitivity due to FAA NextGen retrofit timeline constraints, while sovereign defense departments prioritize integration depth.
Supply Chain Analysis
Refurbishment flows for legacy MIL-STD-1553 display systems sustain aftermarket revenue pools as operators defer full cockpit architecture replacements. Component manufacturing concentrates in the United States, United Kingdom, and Germany, with sensor subsystem suppliers clustering near Lockheed Martin and RTX Corporation integration facilities in Texas and Maryland. Supply chains draw from gallium nitride semiconductors, precision optical assemblies, and radiation-hardened processors. Single-source vulnerability in GaN foundry capacity creates allocation risk during defense procurement surges. Distribution runs through prime contractor platform integration channels rather than independent component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement channel concentration in the United States versus EU MDR certification cost advantages in Germany creates geographic-arbitrage opportunities for subsystem suppliers establishing dual-qualified production footprints.
For Market Incumbents: To counter electro-optical substitution pressure from synthetic aperture radar systems, Lockheed Martin and RTX Corporation should deepen backward integration into gallium nitride semiconductor supply while accelerating distributed aperture system R&D investment to sustain platform-level integration authority. For New Entrants and Emerging Players: Solid-state LiDAR miniaturization for urban air mobility platforms offers the most penetrable white-space target, with California and Texas developers seeking lightweight, low-latency architectures; a go-to-market angle through FAA certification partnership with established avionics integrators reduces qualification timeline barriers. For Investors and Strategic Acquirers: Roll-up economics work for electro-optical specialists with cockpit certification entrenchment because prime contractor consolidation into platform-level contracts is displacing independent sensor procurement decisions; long-term viability hinges on machine learning inference engine integration capability; monitor urban air mobility platform certification velocity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform-Level System Integration | Prime contractors capture expanded scope through F-35 and F/A-18 sustainment arrangements. |
| GaN Semiconductor Backward Integration | Captive foundry capacity insulates radar system margins from substrate allocation volatility. |
| EU MDR Certification Pathway | Dual-use suppliers streamline cross-border market access for airborne electronics. |
| Machine Learning Inference Engine Development | Sensor fusion convergence opens performance tiers unreachable with conventional architectures. |
| Urban Air Mobility Sensor Adaptation | Defense suppliers repurpose military product lines for lightweight commercial aviation applications. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, avionics program managers, FAA certification specialists, and electro-optical engineering directors with secondary validation against Department of Defense budget justification materials, FAA NextGen implementation reports, SEC 10-K filings from prime contractors, and EU MDR regulatory guidance documents. Bottom-up segment sizing and top-down macro constraint checks provided triangulation.
Segment-weighting across product type, end user, technology, and application dimensions drove forecast construction over the projection horizon. Modeled categories included radar systems, sensor suites, communication equipment, and display systems crossed with military, commercial aviation, drone, and private aircraft channels. CAGRs derived from platform retrofit cycle analysis, sovereign defense appropriation trajectories, and unmanned system procurement acceleration patterns. Forecast inputs incorporated gallium nitride substrate supply elasticity and FAA-EASA certification reciprocity evolution.
The model holds under stable defense appropriation environments and sustained FAA NextGen enforcement; deviation in congressional authorization delays or EU MDR software assurance standard divergence would shift volume trajectories. Practitioners should monitor gallium nitride foundry capacity announcements and urban air mobility platform certification milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market
Aircraft Navigation and Communication
Airborne Radars Market
Aircraft Navigation and Communication
Electronic Navigational Charts (ENC) Market
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Aircraft Navigation Software Market
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market
Aircraft Navigation and Communication
Global Flight Navigation System Market