
 North America Satellite Launch Vehicle Market | 2026-2036
North America Satellite Launch Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
North America Satellite Launch Vehicle Market Insights
United States launch infrastructure is reconfiguring competitive dynamics across the North America Satellite Launch Vehicle Market. Space Exploration Technologies Corp. leverages reusable first-stage recovery to compress turnaround timelines and reduce per-launch economics. United Launch Alliance anchors national security missions through vertical integration of Atlas and Delta heritage systems. Blue Origin competes via heavy-lift New Glenn development and engine manufacturing scale in Alabama and Florida.
A satellite launch vehicle is a rocket-propelled system designed to deliver payloads to Earth orbit or beyond, typically employing staged propulsion with specific impulse ratings exceeding 300 seconds in liquid-fueled configurations and thrust-to-weight ratios optimized for orbital insertion mechanics. Its primary commercial purpose is deploying satellites for telecommunications, navigation, and remote sensing networks. Expendable technology still dominates revenue pools due to government mission reliability requirements, while reusable systems capture the fastest growth trajectory as commercial operators prioritize cost-per-kilogram reduction. Government agencies represent the most concentrated end-user segment, though private companies are expanding share through constellation deployment contracts.
FAA Office of Commercial Space Transportation licensing requirements and NASA safety standards shape vehicle certification timelines and operational constraints across United States launch sites. FCC spectrum allocations for satellite downlink services directly influence launch demand cadence and payload integration priorities. Stakeholders must monitor evolving debris mitigation rules from the FCC and emerging EPA environmental review requirements for launch operations as regulatory layering intensifies.
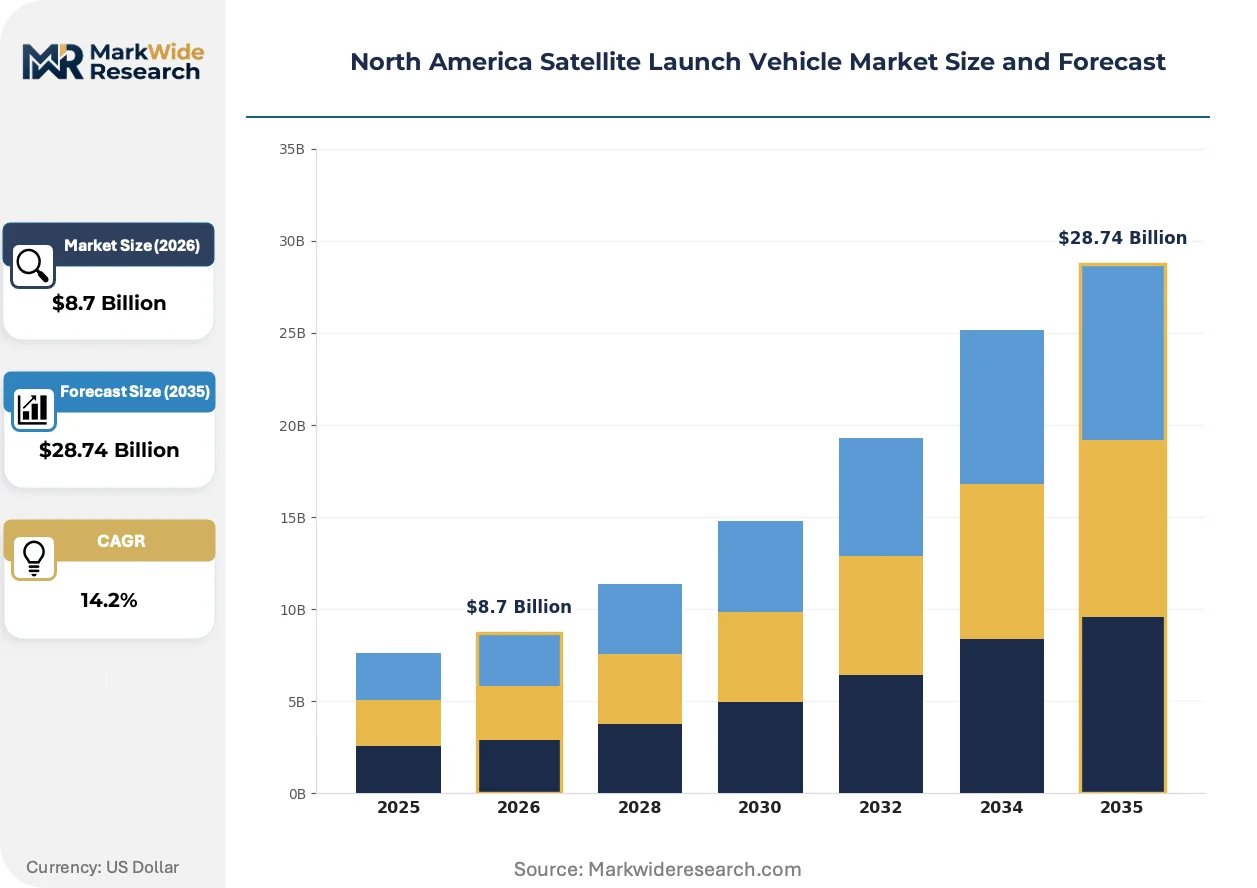
Market Dynamics
Reusable first-stage recovery is compressing turnaround timelines and forcing expendable vehicle economics into structural decline across North America. FAA licensing reforms are simultaneously accelerating commercial approval cadences while tightening environmental review requirements for coastal launch ranges.
Growth Catalysts
- FAA Part 450 Licensing Framework:Streamlined commercial spaceflight regulations reduce approval timelines from years to months for orbital launch operators. Texas and Florida launch ranges report faster mission cadences under the reformed certification structure.
- Broadband Constellation Deployment:Low Earth orbit satellite networks for consumer internet are generating sustained procurement volumes from commercial operators. FCC spectrum allocations for Ka-band downlink services directly correlate with launch manifest density.
- RP-1/LOX Engine Manufacturing Scale:Alabama and Florida production clusters for liquid oxygen/kerosene propulsion systems are reducing engine unit costs through batch fabrication methods.
Market Restraints
- Titanium Forging Concentration:Pressure vessel and turbopump housing supply depends on a limited set of domestic specialty metal suppliers. Aerospace-grade titanium billet lead times extend 18-24 months during demand surges.
- Range Capacity Bottlenecks:Eastern Range and Western Range scheduling constraints limit concurrent launch operations. Range safety modernization funding lags behind commercial manifest growth.
- Expendable Vehicle Cost Structure:Single-use first stages impose irrecoverable hardware costs per mission. Government reliability requirements perpetuate expendable procurement for national security payloads.
Strategic Opportunities
- Mexico Baja California Launch Corridors:Underutilized equatorial-adjacent geography offers reduced plane-change delta-v requirements for specific orbital inclinations. Regulatory harmonization with FAA safety standards would unlock southern launch azimuths.
- On-Orbit Servicing Convergence:Satellite life extension robotics combined with launch vehicle precision deployment enables new orbital logistics architectures. This pairing reduces replacement launch frequency for geostationary operators.
- Canadian Arctic Ground Station Networks:Polar orbit downlink infrastructure expansion in Nunavut and Northwest Territories creates dedicated launch demand for sun-synchronous missions. CSA technology partnerships incentivize domestic payload integration.
Industry Challenges
- Turbomachinery Welding Certification:Inconel superalloy combustion chamber fabrication requires specialized technicians with ASME Section IX qualifications. Training pipelines for orbital-class propulsion welders remain underdeveloped relative to hiring demand.
- Range Environmental Review Complexity:EPA NEPA compliance for new launch sites involves multi-year impact assessments for marine ecosystems and noise propagation. Stakeholders face unpredictable timeline extensions during public comment periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Satellite Launch Vehicle Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Launch Vehicle, Orbital Rocket, Suborbital Rocket, Hybrid Rocket Technology: Reusable, Expendable, Hybrid, Vertical Launch End User: Government Agencies, Private Companies, Research Institutions, International Organizations Application: Telecommunications, Earth Observation, Scientific Research, Space Exploration |
| Companies Covered | Space Exploration Technologies Corp., United Launch Alliance, Blue Origin, Northrop Grumman Corporation, Rocket Lab, Boeing, Lockheed Martin Corporation, L3Harris Technologies, Raytheon Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Satellite Launch Vehicle Market Trends and Innovations
Digital engineering practices are displacing physical qualification campaigns across vehicle development programs. This shift compresses design iteration cycles while introducing new verification risks that hardware-centric organizations must address.
Model-based systems engineering software is virtualizing traditional structural and thermal test sequences for launch vehicle qualification. Spacecraft manufacturers and launch providers adopt these tools at accelerating rates to reduce hardware-in-the-loop dependencies. This virtualization is compressing development timelines from first design to maiden flight by eliminating redundant physical prototype builds.
FAA Part 450 streamlines launch licensing through performance-based safety criteria rather than prescriptive vehicle design mandates. This regulatory architecture permits novel propulsion configurations and recovery methods without case-by-case waivers. Commercial operators in Texas and Florida are restructuring compliance departments to exploit the new risk-based framework.
Constellation operators now contract directly for dedicated rideshare missions rather than purchasing slots through aggregator services. This disintermediation concentrates procurement power with large satellite deployers and marginalizes traditional launch brokers. The pattern is most pronounced among broadband providers with multi-hundred-satellite deployment schedules.
North America Satellite Launch Vehicle Market Segmentation
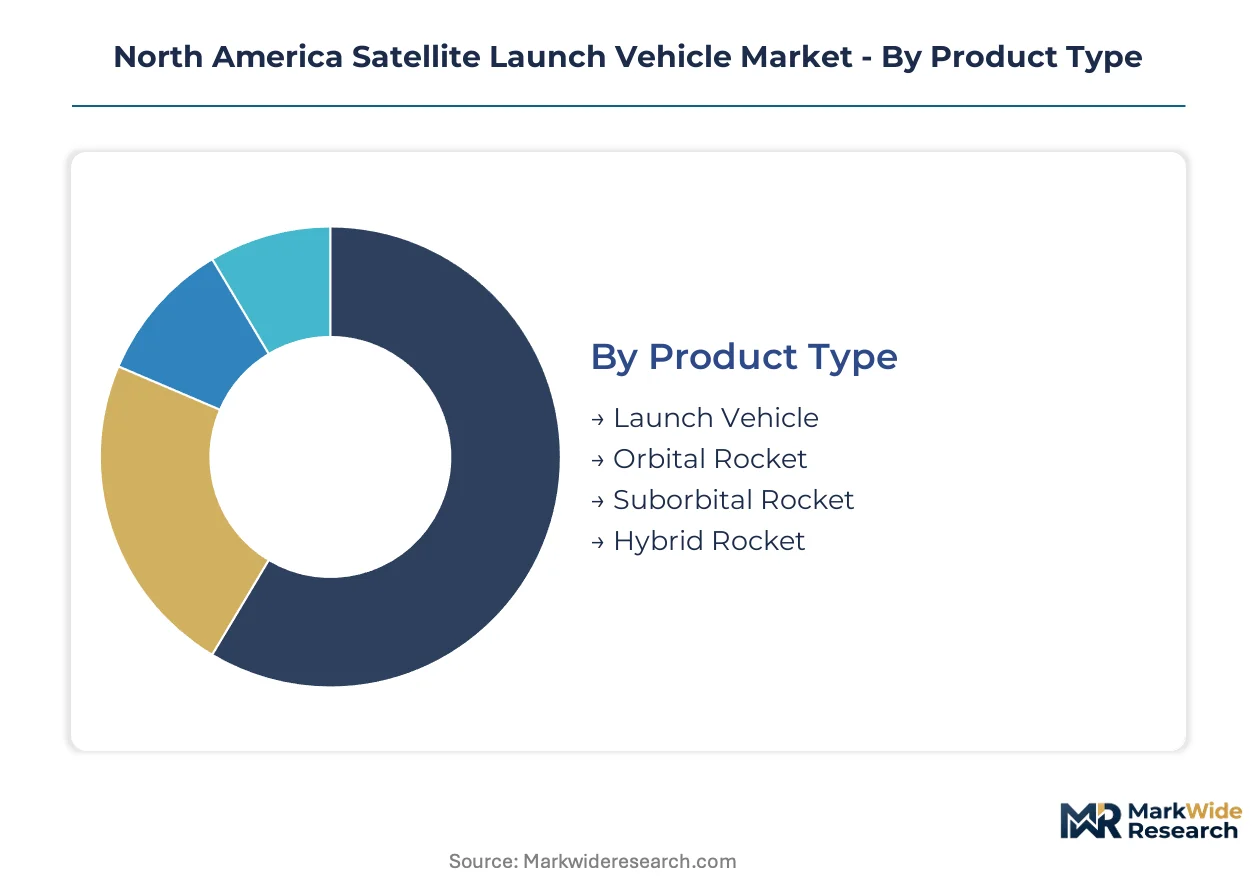
Launch vehicle procurement in North America fragments across mission reliability requirements, payload scale economics, and customer risk tolerance. Segment boundaries increasingly blur as reusable technology penetrates government missions and commercial operators pursue dedicated launch capacity rather than rideshare slots.
Product Type:
Orbital insertion capability spans suborbital research hops through geostationary transfer missions, with propulsion architecture and staging configuration determining addressable payload mass and per-kilogram economics.
- Launch Vehicle:Multi-stage systems with integrated payload fairings and autonomous flight termination capabilities. Demand concentrates in Texas and Florida coastal ranges where FAA Part 450 licensing enables rapid turnaround for constellation deployment schedules.
- Orbital Rocket:Two or three-stage configurations achieving minimum 7.8 km/s delta-v for Low Earth Orbit insertion. Government agencies in the United States anchor procurement volumes through national security payload requirements that prioritize reliability over cost optimization.
- Suborbital Rocket:Single or two-stage systems for microgravity research and technology demonstration flights below orbital velocity. Research institutions drive procurement for payload qualification campaigns prior to orbital mission commitment.
- Hybrid Rocket:Combined liquid-solid propulsion systems leveraging throttlability with structural simplicity. Niche adoption persists in sounding rocket applications where restart capability and safety margins outweigh specific impulse penalties.
Established volume favors orbital rockets; emerging adoption favors suborbital platforms for rapid payload iteration cycles.
Technology:
Cost tier stratification separates development-stage operators pursuing reusability from heritage providers defending expendable mission assurance premiums.
- Reusable:First-stage recovery via propulsive landing or aerial capture, with refurbishment intervals targeting sub-30-day turnaround. Commercial operators in the United States compress per-launch economics through booster inventory amortization across manifest density.
- Expendable:Single-use vehicle configurations optimized for maximum payload mass fraction without recovery system mass penalties. Government mission assurance requirements perpetuate procurement despite structural cost disadvantages for high-cadence operators.
- Hybrid:Partial reusability configurations with recoverable first stages and expendable upper stages. Mid-tier pricing positions attract constellation operators transitioning from rideshare aggregation toward dedicated mission control.
- Vertical Launch:Conventional ground-based liftoff architecture with established range safety protocols and tracking infrastructure. Eastern Range and Western Range scheduling constraints limit concurrent operations despite modernization investments.
Expendable systems retain mission assurance premiums; reusable configurations are expanding most quickly through commercial manifest capture.
End User:
Customer type determines procurement timeline urgency, payload classification restrictions, and contract structure preferences across the United States and Canada.
- Government Agencies:National security and civil space missions with multi-year procurement cycles and reliability-weighted source selection criteria. NASA and Department of Defense budgets anchor demand stability despite appropriation volatility.
- Private Companies:Commercial constellation operators and satellite service providers with high-cadence launch requirements and cost-per-kilogram optimization priorities. Broadband internet providers generate sustained procurement volumes through multi-hundred-satellite deployment schedules.
- Research Institutions:University and laboratory missions with small payload masses and schedule flexibility enabling rideshare aggregation. CubeSat standardization reduces integration complexity for educational and technology demonstration payloads.
- International Organizations:Multilateral space agency collaborations and commercial payload hosting arrangements. Canadian Space Agency partnerships create dedicated demand for polar orbit missions serving Arctic ground station networks.
Government procurement sustains incumbent provider margins; private company demand is climbing the fastest through constellation deployment acceleration.
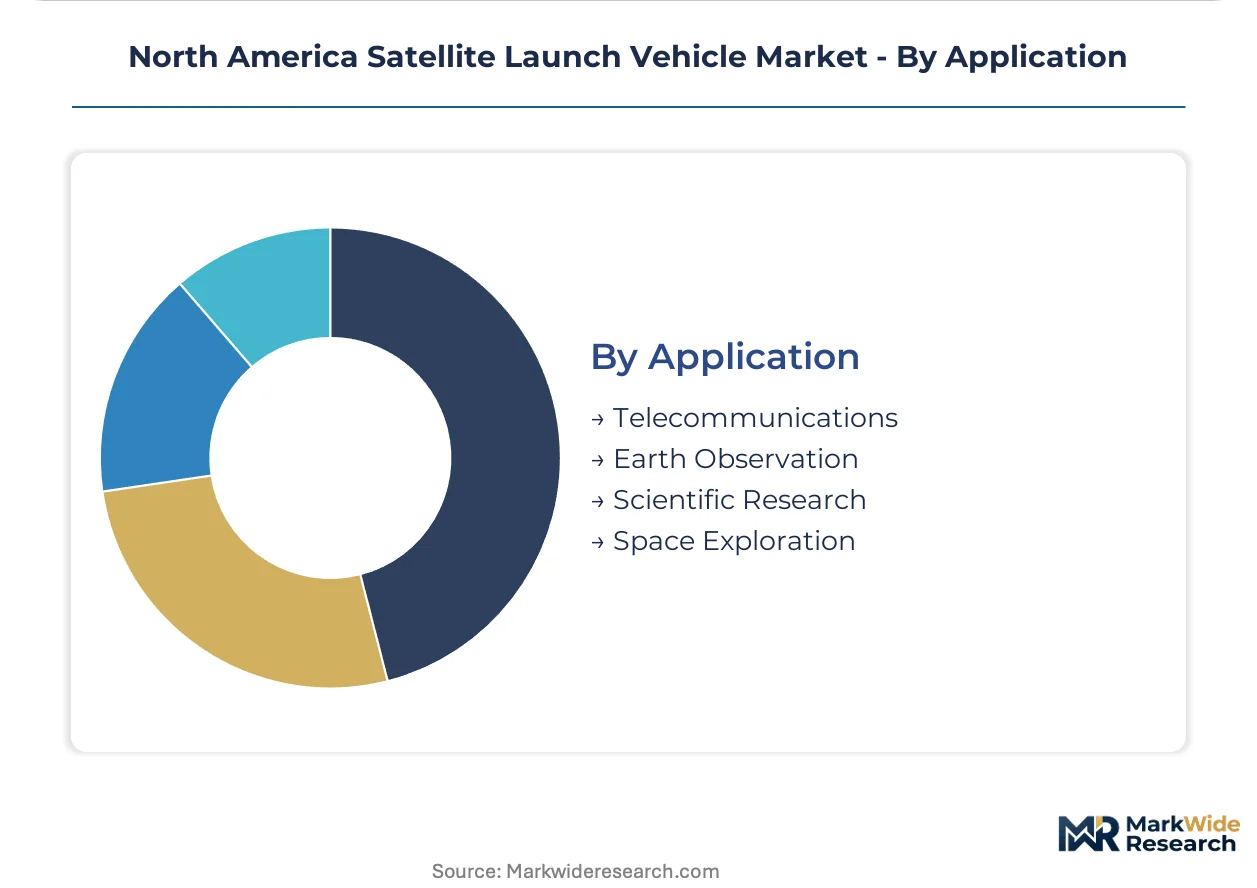
Application:
Mission purpose dictates orbital altitude, inclination, and payload integration complexity, with telecommunications and Earth observation generating recurrent launch cadence.
- Telecommunications:Geostationary and Low Earth Orbit satellite deployment for consumer broadband and broadcast services. FCC spectrum allocations for Ka-band downlink services directly correlate with launch manifest density across United States ranges.
- Earth Observation:Sun-synchronous and polar orbit insertion for remote sensing constellations. Canadian Arctic ground station expansion in Nunavut creates dedicated launch demand for data downlink infrastructure.
- Scientific Research:Astrophysics, heliophysics, and planetary science missions with custom orbital requirements and extended integration timelines. NASA Science Mission Directorate procurement prioritizes payload accommodation over launch cost minimization.
- Space Exploration:Crewed spacecraft, lunar landers, and deep space probes with human-rating and long-duration reliability requirements. Artemis program architecture generates sustained heavy-lift demand for lunar Gateway and surface access missions.
Telecommunications anchors revenue concentration; Earth observation is gaining share fastest through commercial remote sensing constellation proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North America diverge sharply: the United States prioritizes high-frequency reusable launch cadence for commercial constellations, while Canada and Mexico concentrate on specialized polar and equatorial-adjacent missions with lower volume but distinct orbital mechanics requirements.
United States
Texas and Florida coastal ranges generate the densest launch manifests, driven by broadband constellation operators demanding weekly orbital insertion capacity. FAA Part 450 licensing reforms compress approval timelines from years to months, accelerating commercial mission cadence. Alabama and Florida production clusters for RP-1/LOX propulsion systems are scaling batch fabrication methods to reduce engine unit costs.
Canada
Arctic ground station expansion in Nunavut and Northwest Territories creates dedicated demand for sun-synchronous orbit missions serving remote sensing downlink infrastructure. Canadian Space Agency technology partnerships incentivize domestic payload integration for polar orbital trajectories. Quebec and Ontario host satellite manufacturing clusters that feed launch procurement pipelines for Earth observation constellations.
Mexico
Baja California launch corridors offer underutilized equatorial-adjacent geography with reduced plane-change delta-v requirements for specific orbital inclinations. Regulatory harmonization with FAA safety standards would unlock southern launch azimuths currently constrained by bilateral certification gaps. The Yucatán Peninsula and northern border states are evaluating range infrastructure investments to capture rideshare aggregation demand.
North America Satellite Launch Vehicle Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The North America Satellite Launch Vehicle Market exhibits a bifurcated structure where vertically integrated heritage providers anchor national security procurement, while commercial entrants capture manifest density through reusable architecture. Three archetypes dominate: full-stack reusable operators, expendable mission-assurance specialists, and hybrid mid-tier providers bridging cost and reliability. Competitive dynamics center on turnaround timeline compression and engine manufacturing backward integration.
Within the full-stack reusable tier, Space Exploration Technologies Corp. and Blue Origin occupy positions defined by propulsive landing technology and heavy-lift development pipelines. United Launch Alliance exemplifies the mission-assurance archetype through Atlas and Delta heritage system integration for government payloads. These three entities represent the primary competitive anchors shaping procurement patterns across commercial constellation and national security segments.
| Leading Market Players |
|---|
| Space Exploration Technologies Corp. |
| United Launch Alliance |
| Blue Origin |
| Northrop Grumman Corporation |
| Rocket Lab |
| Boeing |
| Lockheed Martin Corporation |
| L3Harris Technologies |
| Raytheon Technologies Corporation |
| Others |
Pricing and Supply Chain Analysis
Range capacity underutilization in Mexico and the Canadian Arctic compresses supplier pricing power while concentrating procurement leverage with Texas and Florida launch operators. FAA Part 450 licensing acceleration tightens turnaround economics, forcing expendable vehicle providers toward cost absorption or market exit.
Pricing Analysis
Long-term offtake agreements dominate procurement between constellation operators and reusable launch providers, locking in multi-mission pricing schedules that amortize booster development costs across manifest density. Price differentiation hinges on mission assurance certification tiers and payload integration complexity, with government payloads commanding reliability premiums over commercial rideshare slots. Cost compression in the expendable segment intensifies as reusable systems capture high-cadence commercial demand. Private constellation operators exhibit acute price sensitivity, while national security missions prioritize mission assurance over per-kilogram economics.
Supply Chain Analysis
Extended payment terms from prime contractors strain specialty metal suppliers, with aerospace-grade titanium billet producers in the United States and Japan demanding supply-chain finance facilities to bridge fabrication-to-delivery gaps. Propulsion system manufacturing draws from Alabama and Florida production clusters, with Inconel superalloy combustion chambers resting on limited ASME-certified welding capacity. Single-source vulnerability concentrates in domestic titanium forging for pressure vessels and turbopump housings. Distribution runs through vertically integrated launch providers controlling engine manufacturing and vehicle integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent launch vehicle manufacturers face substitution pressure from reusable architecture penetration, requiring defensive repositioning to preserve mission-assurance premiums in national security procurement.
For Market Incumbents: Insulate national security revenue streams through vertical integration of Atlas and Delta heritage systems, deepening mission assurance certification investments to defend against SpaceX and Blue Origin reusable platform capture. Accelerate RP-1/LOX engine manufacturing scale in Alabama to match batch fabrication cost structures of commercial entrants. For New Entrants and Emerging Players: Establish a beachhead in Canadian Arctic polar orbit missions, where sun-synchronous launch demand from Nunavut ground station expansion outpaces incumbent provider attention. Pursue regulatory harmonization with FAA safety standards to unlock Baja California launch corridors for equatorial-adjacent missions with reduced plane-change delta-v requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid reusable-expendable operators serving constellation deployment schedules with dedicated rideshare missions. Five-to-ten-year viability favors mid-tier providers with engine manufacturing backward integration and FAA Part 450 licensing infrastructure. Monitor FCC spectrum allocation velocity for Ka-band downlink services as the inflection indicator for launch manifest density acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable First-Stage Certification | FAA Part 450 performance-based criteria enable novel recovery methods without prescriptive waivers. |
| Engine Manufacturing Scale-Up | Alabama and Florida RP-1/LOX production clusters reduce unit costs through batch fabrication methods. |
| Arctic Ground Station Partnership | CSA technology collaborations in Nunavut create dedicated demand for polar orbit insertion capacity. |
| Mexico Regulatory Harmonization | FAA safety standard alignment unlocks southern launch azimuths for reduced plane-change missions. |
| On-Orbit Servicing Integration | Satellite life extension robotics paired with precision deployment reduce replacement launch frequency. |
Research Methodology
A spread of perspectives from launch vehicle program managers, FAA licensing officials, constellation procurement leads, and propulsion system engineers converged on the working assumptions driving demand projections. Primary fieldwork combined structured interviews with secondary validation through FAA launch license databases, FCC spectrum allocation filings, NASA contract award records, and CSA technology partnership disclosures. Bottom-up manifest density modeling triangulated against top-down national security budget appropriation analysis.
Demand-supply balance across the projection horizon integrated orbital insertion capacity expansion against constellation deployment schedules and government mission procurement timelines. Segmentation dimensions modeled include technology tier, payload scale class, end-user type, and orbital inclination requirement. CAGRs derived from manifest density trajectories weighted by FCC spectrum allocation velocity and FAA licensing approval cadence. Industry-specific inputs incorporated Eastern Range and Western Range scheduling constraints and titanium billet lead time volatility.
Stress conditions across range capacity bottlenecks, debris mitigation rule evolution, and EPA NEPA compliance timeline variability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reusable technology adoption curves and regulatory harmonization progress. Macroeconomic contraction, abrupt licensing framework reversal, or breakthrough propulsion technology emergence would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Mobile Satellite Services Market
Satellite
Argentina Satellite Imagery Services Market
Satellite
India Satellite-Based Earth Observation Market
Satellite
GEO Satellite Market
Satellite
Spain Satellite Imagery Services Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
Global Remote Sensing Services Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
Commercial LEO Satellite Market
Satellite
Russia Satellite Communications Market
Satellite
Satellite Manufacturing Market
Satellite
Italy Satellite Imagery Services Market
Satellite
Global Commercial Satellite Imagery Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
Africa Satellite Connectivity Market
Satellite
Germany Satellite Imagery Services Market