
 Polyethylene Naphthalate Market | 2026-2036
Polyethylene Naphthalate Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Naphthalate Market Analysis
Modular film-to-resin bundling is broadening procurement options for electronics converters seeking integrated substrate solutions. Teijin Limited leverages captive dimethyl naphthalene capacity to sustain cost discipline across its PEN film operations. Toray Industries, Inc. anchors high-barrier packaging demand in Japan through proprietary biaxial stretching technology. SKC Co., Ltd. competes aggressively in optical-grade films by controlling downstream coating processes in-house.
Polyethylene naphthalate is a high-performance polyester synthesized from naphthalene-2,6-dicarboxylic acid and ethylene glycol, distinguished by a glass transition temperature near 120°C that enables thermal stability beyond standard PET. Films dominate current value capture owing to their penetration in flexible printed circuit boards and solar backsheet laminates, while resins represent the fastest-expanding category as blow-molding applications for hot-fill beverage bottles gain commercial traction. Fibers remain a specialized margin pool serving industrial tire cord and high-temperature filtration media where aramid cost barriers create a mid-tier opening.
The US FDA maintains stringent migration limits for PEN in food-contact layers, compelling resin producers to validate oligomer control through batch certification. Japan's METI and South Korea's MFDS enforce divergent electrical insulation fire-rating standards that fragment film qualification protocols across Northeast Asian supply chains. REACH registration requirements in Europe constrain naphthalene feedstock sourcing for non-integrated compounders, elevating compliance costs relative to Asian integrated producers. Stakeholders must monitor regulatory divergence on recycled-content mandates as mechanical recycling of PEN multilayer structures remains technically immature.
Market Dynamics
Japan's METI energy-efficiency mandates for display components are accelerating substitution from conventional polyester to PEN film, while captive dimethyl naphthalene supply at integrated producers is compressing cost structures for non-integrated compounders.
Growth Catalysts
- Semiconductor packaging demand:South Korea's Pyeongtaek-Yongin corridor is absorbing optical-grade PEN films for advanced chip substrates. Electronics manufacturers are qualifying PEN for flexible circuit layers.
- Hot-fill beverage bottle adoption:Blow-molding resins are penetrating carbonated and aseptic beverage segments where thermal stability above 85°C is required. PEN's glass transition temperature near 120°C enables hot-fill processing without deformation.
- Solar backsheet laminate penetration:Photovoltaic module assemblers are specifying PEN films for barrier layers in dual-glass and frameless designs. UV resistance and hydrolytic stability extend module warranty coverage.
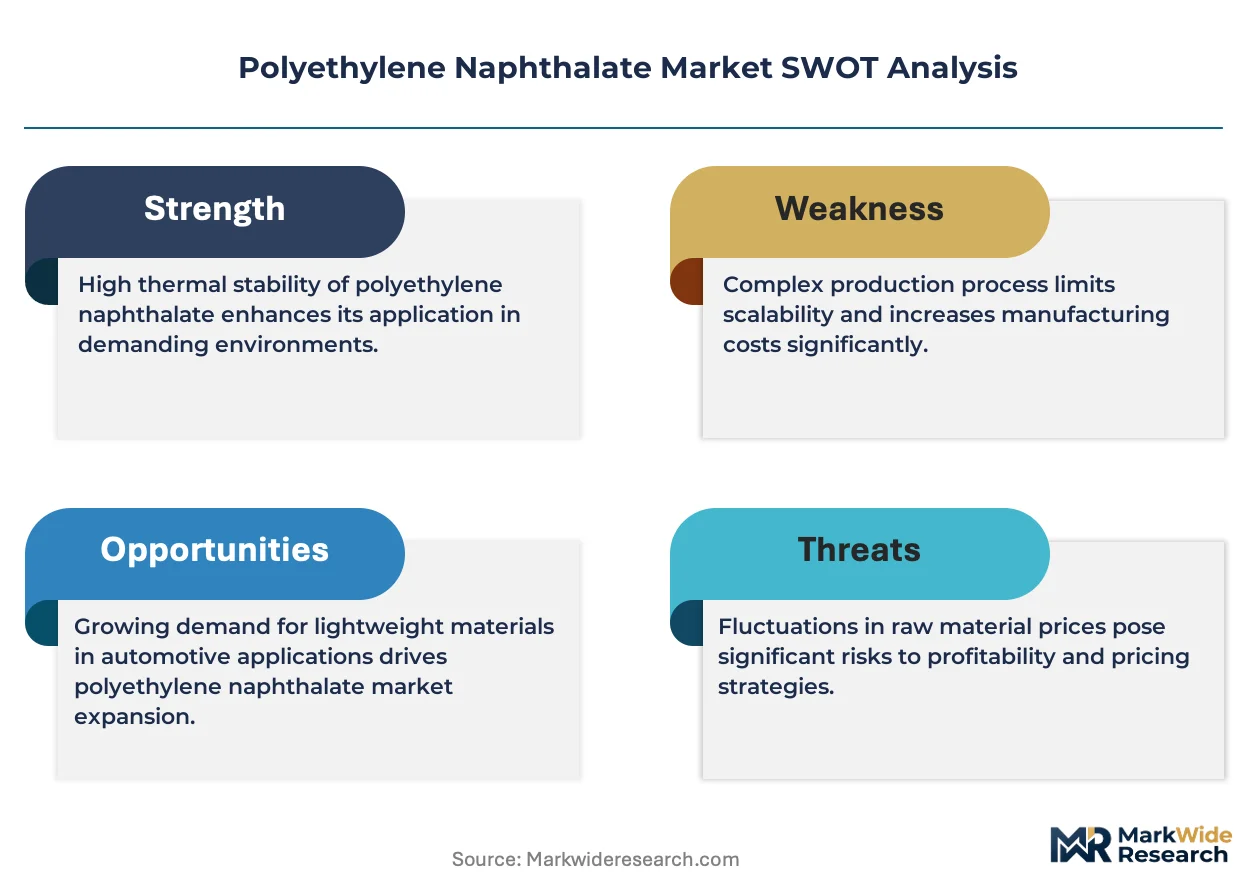
Market Restraints
- Naphthalene feedstock concentration:Non-integrated compounders face elevated compliance costs under REACH registration requirements in Europe. Integrated Asian producers with captive naphthalene supply maintain structural cost advantages.
- Mechanical recycling immaturity:Multilayer PEN structures lack viable mechanical recycling pathways. Recycled-content mandates in packaging applications create technical compliance gaps for converters.
- Aramid substitution ceiling:Industrial tire cord and high-temperature filtration applications face price-performance trade-offs against aramid fibers. PEN fibers occupy a mid-tier position with limited premium capture.
Strategic Opportunities
- Optical coating integration:Downstream in-house coating capabilities enable specification of value-added film grades. Hardcoat and anti-reflective layers command price premiums in display applications.
- Food-contact layer validation:US FDA migration limits for oligomers create certification barriers that validated producers can leverage. Batch certification protocols favor established resin suppliers with analytical infrastructure.
- Flexible electronics substrate expansion:East Asian electronics manufacturers are expanding PEN film qualification for roll-to-roll processing. Thermal dimensional stability enables fine-pitch circuit patterning.
Industry Challenges
- Fire-rating standard fragmentation:Japan's METI and South Korea's MFDS enforce divergent electrical insulation classifications. Film producers must maintain parallel qualification protocols for Northeast Asian supply chains.
- Oligomer control certification:US FDA batch certification for food-contact layers requires analytical chemistry capabilities and documentation systems. Smaller compounders face capability gaps in regulatory compliance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Naphthalate Market |
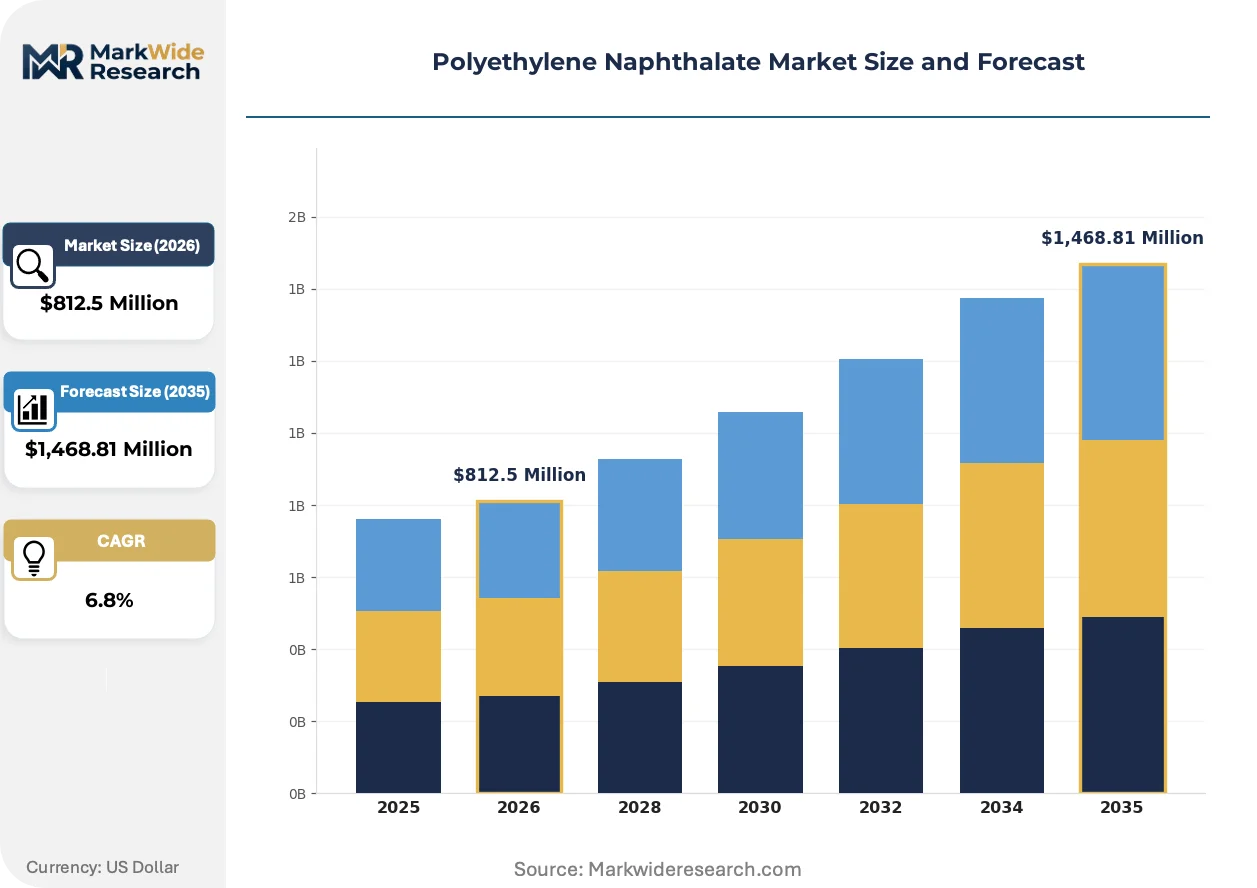
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,468.81 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Fibers, Resins, Preforms End Use Industry: Textiles, Packaging, Electronics, Automotive Application: Food Packaging, Electrical Insulation, Bottles, Coatings Sales Channel: Direct Sales, Distributors, Online Retail, Trade Shows |
| Companies Covered | Indorama Ventures Public Company Limited, Sumitomo Chemical Co., Ltd., Teijin Limited, DuPont Teijin Films, Kolon Industries, Toyobo Co., Ltd., SASA Polyester Sanayi A.S., Toray Industries, Inc., SKC Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Naphthalate Market Emerging Trajectories
Process integration and material specification are reshaping competitive positioning in PEN film and resin supply. Technology convergence with adjacent polyester platforms is compressing development cycles.
Biaxial stretching process refinements are overtaking conventional sequential stretching for high-barrier packaging grades. Japanese packaging converters are adopting simultaneous biaxial lines for improved thickness uniformity. This technology is overtaking legacy sequential equipment in premium film specifications.
REACH registration requirements for naphthalene feedstocks are constraining European compounder sourcing flexibility. ECHA substance evaluation protocols extend lead times for non-integrated producers. Resin qualification timelines in automotive and electrical applications are lengthening as a result.
Integrated film-to-resin bundling is compressing procurement decision cycles for electronics converters. Specifications increasingly combine substrate and coating requirements in single-source arrangements. South Korean display panel assemblers are driving this consolidation in optical-grade supply agreements.
Polyethylene Naphthalate Market Segmentation
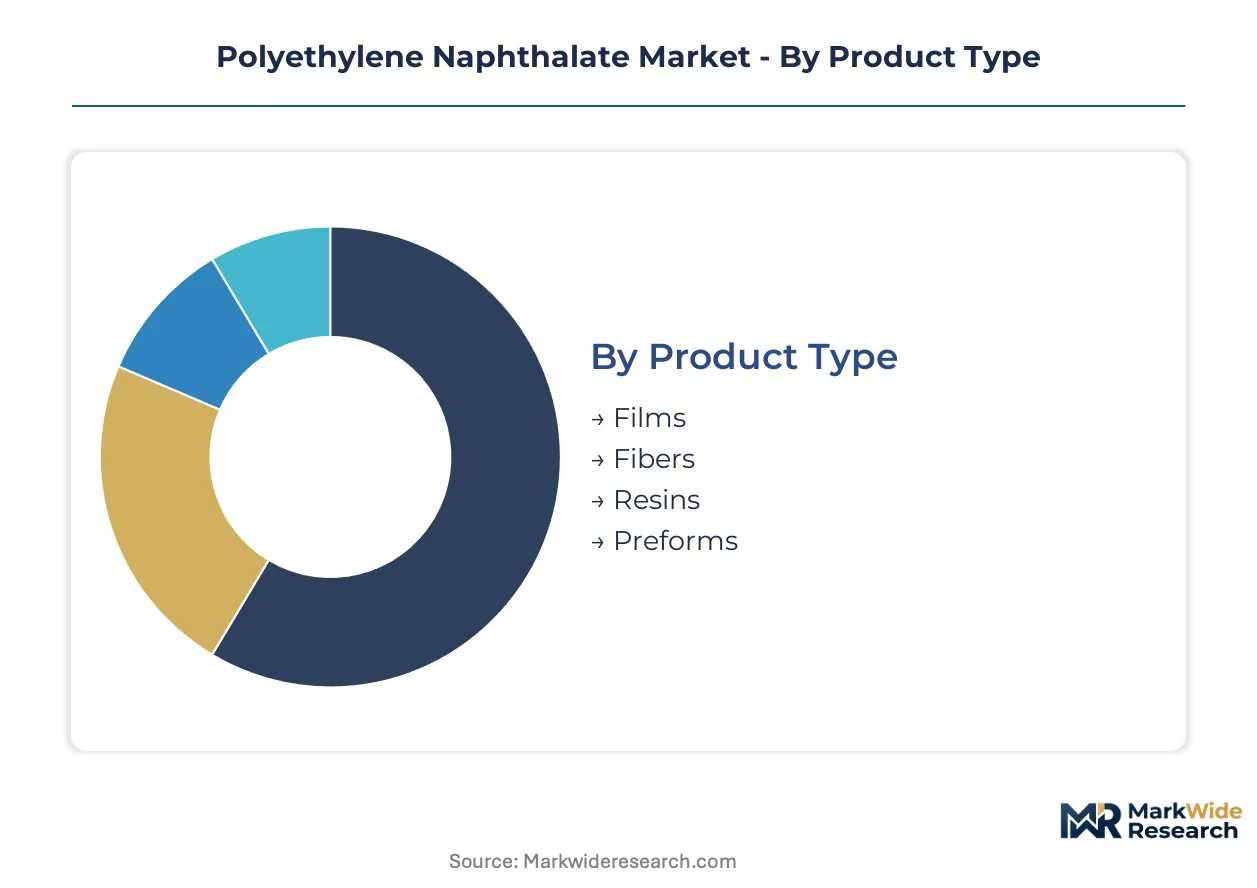
PEN's thermal and barrier properties create distinct value propositions across product forms, driving divergent buyer priorities. End-use concentration in electronics and packaging segments shapes specification requirements and procurement patterns.
Product Type:
Buyers differentiate primarily by thermal performance thresholds and downstream processing compatibility.
- Films:Biaxially oriented PEN films deliver dimensional stability above 120°C for flexible circuit substrates and solar backsheet laminates. Electronics manufacturers in South Korea's Pyeongtaek-Yongin corridor specify optical-grade variants for semiconductor packaging layers.
- Resins:Blow-molding grade resins target hot-fill beverage bottles requiring thermal resistance above 85°C without deformation. PEN's glass transition temperature enables carbonated and aseptic beverage processing where standard PET fails.
- Fibers:Industrial tire cord and high-temperature filtration media serve mid-tier applications between standard polyester and aramid performance.
- Preforms:Injection-molded preforms for stretch-blow molding of high-barrier beverage containers.
Films lead volumes today; resins are climbing the fastest as hot-fill beverage adoption accelerates.
End Use Industry:
Specification intensity varies sharply between regulated food-contact layers and performance-driven electronics substrates.
- Electronics:Flexible printed circuit boards and display components demand ultra-low thermal expansion coefficients. Japan's METI energy-efficiency mandates accelerate substitution from conventional polyester in display laminates.
- Packaging:High-barrier food and beverage containers leverage PEN's oligomer control and migration compliance. US FDA batch certification requirements favor established resin suppliers with analytical infrastructure.
- Automotive:Under-hood electrical insulation and sensor housings utilize PEN's hydrolytic stability.
- Textiles:Industrial applications including tire cord and filtration media where thermal resistance exceeds PET capabilities.
Electronics commands premium pricing; packaging is expanding most quickly through beverage bottle conversions.
Application:
Processing method and regulatory exposure determine material grade selection and supplier qualification pathways.
- Electrical Insulation:Film and resin grades for wire coatings and capacitor dielectrics require compliance with divergent fire-rating standards. Japan's METI and South Korea's MFDS enforce separate classification protocols that fragment film qualification.
- Food Packaging:Multilayer structures with PEN barrier layers face mechanical recycling immaturity constraints. REACH registration requirements for naphthalene feedstocks constrain European compounder sourcing flexibility.
- Bottles:Hot-fill and aseptic beverage containers utilize blow-molding resins with validated oligomer control.
- Coatings:Hardcoat and anti-reflective layers applied to optical-grade films for display applications.
Electrical insulation dominates technical specifications; bottles show steepest expansion trajectory.
Sales Channel:
Transaction complexity and technical support requirements shape channel preference across buyer segments.
- Direct Sales:Integrated film-to-resin bundling agreements serve high-volume electronics converters. South Korean display panel assemblers consolidate optical-grade supply through single-source substrate and coating arrangements.
- Distributors:Regional stocking points support smaller packaging converters with fragmented order patterns and just-in-time requirements.
- Online Retail:Sample quantities and technical documentation access for R&D and qualification purposes.
- Trade Shows:Specification development and supplier qualification for new application development.
Direct sales captures the largest transaction values; distributor relationships are gaining share among mid-tier converters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene naphthalate commercialization traces to Japanese chemical conglomerates scaling dimethyl naphthalene chemistry during the 1990s display boom. Teijin and Toray pioneered biaxial film lines serving domestic electronics assemblers. This heritage established East Asian supply chains that now feed semiconductor packaging corridors worldwide.
Japan
METI energy-efficiency mandates for display components accelerate substitution from conventional polyester to PEN film in panel laminates. JIS standards govern electrical insulation classifications that diverge from South Korean protocols. The Kanto region around Tokyo anchors optical-grade film production serving domestic display manufacturers.
South Korea
Semiconductor packaging demand concentrates in the Pyeongtaek-Yongin corridor absorbing optical-grade PEN films for advanced chip substrates. MFDS electrical insulation fire-rating standards create qualification barriers distinct from Japanese METI classifications. Seoul-based display panel assemblers consolidate substrate and coating procurement through integrated supply agreements.
United States
FDA migration limits for food-contact layers compel resin producers to validate oligomer control through batch certification protocols. Hot-fill beverage bottle adoption drives blow-molding resin qualification among carbonated and aseptic processors. The Southeast manufacturing belt hosts compounders serving packaging converters with validated analytical infrastructure.
Germany
ECHA REACH registration requirements for naphthalene feedstocks constrain sourcing flexibility for non-integrated European compounders. Resin qualification timelines lengthen as substance evaluation protocols extend lead times. The Rhine-Ruhr industrial corridor maintains specialty polyester compounding capacity despite feedstock cost disadvantages versus Asian integrated producers.
China
MIIT industrial policy supports domestic high-performance polyester capacity expansion targeting electronics substrate import substitution. GB standards for electrical insulation materials create parallel certification pathways distinct from IEC frameworks. The Yangtze River Delta around Shanghai concentrates film conversion operations serving regional display module assemblers.
Polyethylene Naphthalate Market Vendor Landscape
Premium-margin players sit above commodity-margin players across captive feedstock access and downstream coating integration. The vendor base clusters around three strategic archetypes: integrated chemical conglomerates with naphthalene supply control, specialized film converters with proprietary biaxial stretching assets, and regional resin compounders serving qualified packaging applications. Dominant competitive moves include backward integration into dimethyl naphthalene production and in-house optical coating capability expansion.
Within the integrated chemical tier, Teijin Limited and Toray Industries exemplify archetypes combining captive feedstock with film manufacturing scale. SKC Co., Ltd. occupies a position among Korean specialists competing through downstream process control. These three anchors represent divergent strategic postures: Japanese conglomerate breadth, Korean coating specialization, and regional supply chain density serving Pyeongtaek-Yongin semiconductor demand.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| Sumitomo Chemical Co., Ltd. |
| Teijin Limited |
| DuPont Teijin Films |
| Kolon Industries |
| Toyobo Co., Ltd. |
| SASA Polyester Sanayi A.S. |
| Toray Industries, Inc. |
| SKC Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Japan's METI energy-efficiency mandates for display components gate qualified supply access and premium-tier pricing power for PEN film producers with validated fire-rating certifications. Buyers without oligomer control infrastructure face exclusion from food-contact resin tiers where FDA batch certification commands structural premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates optical-grade film with in-house coating capabilities from commodity resin grades and unqualified fiber tiers. Price differentiation rests on FDA certification tier and captive dimethyl naphthalene supply status. Cost compression in standard-grade resins is intensifying because non-integrated compounders absorb REACH registration burdens. Packaging converters show highest price sensitivity; semiconductor substrate assemblers accept premiums for thermal dimensional stability.
Supply Chain Analysis
Regional distribution centers in Japan, South Korea, and Germany anchor hub-and-spoke patterns serving electronics and packaging corridors. Naphthalene feedstock sourcing draws from integrated Asian producers with captive supply, while European compounders face ECHA substance evaluation delays. Single-source vulnerability concentrates in dimethyl naphthalene production. Distribution runs through direct sales agreements for high-volume electronics converters and regional stocking points for fragmented packaging orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Japan's METI display mandates and FDA oligomer controls create demand for certified supply. Compliance infrastructure separates viable participants from margin-compressed tiers.
For Market Incumbents: Anchor backward integration into dimethyl naphthalene production to defend against non-integrated compounders facing REACH cost disadvantages. Expand in-house optical coating capabilities to capture hardcoat and anti-reflective premiums in display applications. Threat: Korean specialists with Pyeongtaek-Yongin corridor density erode optical-grade share through integrated substrate-coating bundling. For New Entrants and Emerging Players: E-commerce sample channels enable qualification-stage access to R&D buyers seeking PEN film alternatives for flexible circuit prototyping. Target blow-molding resin tiers for hot-fill beverage bottles where FDA certification barriers favor analytical infrastructure investments over scale. White-space: European packaging converters underserved by REACH-constrained local supply. For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated compounders with validated oligomer control but lacking captive feedstock. Long-term viability hinges on regulatory divergence persistence across METI, MFDS, and FDA jurisdictions. Signal to watch: mechanical recycling breakthroughs for multilayer structures that would erode virgin resin demand under recycled-content mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dimethyl Naphthalene | Captive feedstock supply neutralizes REACH cost disadvantages for European compounders. |
| In-House Optical Coating Expansion | Hardcoat and anti-reflective capabilities command price premiums from Seoul display panel assemblers. |
| FDA Batch Certification Investment | Analytical infrastructure validates oligomer control for food-contact resin tiers with structural pricing power. |
| Simultaneous Biaxial Stretching Line Adoption | Thickness uniformity improvements displace legacy sequential equipment in Japanese packaging converter specifications. |
| Flexible Electronics Substrate Qualification | Thermal dimensional stability enables fine-pitch circuit patterning for East Asian roll-to-roll processing. |
Methodological Framework
Direct dialogue with polymer plant managers, procurement leads at display panel OEMs, distribution channel partners, and technical R&D directors grounded the qualitative foundation. Secondary validation drew from customs trade data, Japan Chemical Industry Association reports, SEC 10-K filings, and ECHA substance evaluation records. Bottom-up segment sizing and top-down macro anchoring triangulated volume estimates.
Output projections across the analysis window reflect modeled interactions between product form, end-use industry, application method, and regional regulatory cluster. CAGRs emerged from segment-level trajectory blending anchored to electronics packaging demand and beverage bottle conversion rates. Forecast inputs included METI mandate implementation pace and FDA certification timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for mechanical recycling of multilayer PEN structures would alter the outlook for virgin resin demand. Forecasts reflect documented assumptions around regulatory divergence persistence and feedstock concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Formaldehyde-Free Resin Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Europe Fluoropolymer Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market
Polymers & Resins
Global Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Poly (1-Decene) Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
South America Epoxy Resins Market
Polymers & Resins
Calendering Resins Market