
 Medical Grade Paper Market | 2026-2036
Medical Grade Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Grade Paper Market Outlook
The gap between premium sterilization-grade papers and commodity medical papers is expanding as hospitals demand higher barrier performance and pharmaceutical packagers face stricter validation protocols. BillerudKorsnäs AB leverages its Nordic pulp integration to control fiber purity from source to finished sheet. WestRock anchors North American supply through extensive converting infrastructure and direct hospital system contracts. Amcor Limited differentiates via multilayer composite structures that merge paper substrates with polymer barriers.
Medical grade paper denotes cellulose-based sheets engineered to meet biocompatibility, sterility maintenance, and particulate limits specified under ISO 11607 and EN 868 standards, typically manufactured from controlled alpha-cellulose content with wet-strength resin additives for steam and ethylene oxide penetration. Uncoated paper dominates surgical wrap volumes where porosity governs sterilization efficacy, while specialty paper captures margin concentration in diagnostic kit lamination where custom caliper and coefficient of friction parameters command technical premiums. Composite grades are displacing pure cellulose in implantable device packaging as manufacturers seek puncture resistance without sacrificing sterilization access.
FDA 21 CFR Part 820 quality system regulations and EU MDR technical documentation requirements compel paper converters to maintain batch-level traceability and endotoxin testing protocols that commodity suppliers cannot satisfy. Health Canada's PMRA and TGA Australia impose parallel sterilization validation frameworks that restrict market access to certified manufacturers. Stakeholders must monitor evolving EPA sterilization gas emissions rules and the EU F-Gas Regulation's impact on ethylene oxide availability, as these will determine which paper barrier technologies achieve cost-competitive scale.
Market Dynamics
FDA 21 CFR Part 820 quality system regulations and EU MDR technical documentation requirements are compressing the supplier base by mandating batch-level traceability and endotoxin testing protocols that commodity paper converters cannot satisfy. This regulatory tightening is accelerating consolidation among certified manufacturers while raising barriers for new entrants.
Growth Catalysts
- Hospital sterilization wrap demand:Healthcare systems in Germany, France, and the United States are prioritizing infection control protocols that require validated barrier papers with documented steam and ethylene oxide penetration performance.
- ISO 11607 standardization:Global alignment around sterilization validation frameworks is creating cross-border procurement efficiencies for medical device manufacturers sourcing packaging materials.
- Ethylene oxide sterilization persistence:Despite EPA emissions scrutiny, EtO remains the dominant method for heat-sensitive devices, sustaining demand for porous cellulose substrates engineered to specific porosity thresholds.
Market Restraints
- Nordic pulp supply concentration:Premium alpha-cellulose fiber sourcing depends on Scandinavian kraft pulp mills, exposing converters to regional logistics disruptions and energy cost volatility.
- Polymer barrier substitution:Multilayer plastic films and Tyvek alternatives are capturing share in implantable device packaging where puncture resistance exceeds paper's mechanical limits.
- EU F-Gas Regulation constraints:Restrictions on ethylene oxide availability under the F-Gas framework are forcing sterilization providers toward alternative methods that may not validate with existing paper formulations.
Strategic Opportunities
- India medical device manufacturing expansion:CDSCO regulatory harmonization with ISO standards is attracting contract packaging operations that require certified sterilization-grade paper supply.
- Diagnostic kit lamination:Custom caliper and coefficient of friction specifications for lateral flow assays command technical premiums beyond commodity surgical wrap margins.
- Composite substrate convergence:Paper-polymer hybrid structures that merge cellulose porosity with synthetic puncture resistance are opening implantable device segments previously closed to pure paper.
Industry Challenges
- Wet-strength resin formulation expertise:The specialized chemistry knowledge required for steam-sterilizable paper additives is concentrated among aging technical workforces in European and North American mills.
- Endotoxin testing infrastructure:LAL assay capabilities and cleanroom converting environments demand capital investment that mid-tier suppliers struggle to justify at current volume thresholds.
- Legacy sterilization validation cycles:Medical device manufacturers face 18-24 month requalification timelines when switching paper suppliers, freezing procurement relationships and delaying new entrant market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Grade Paper Market |
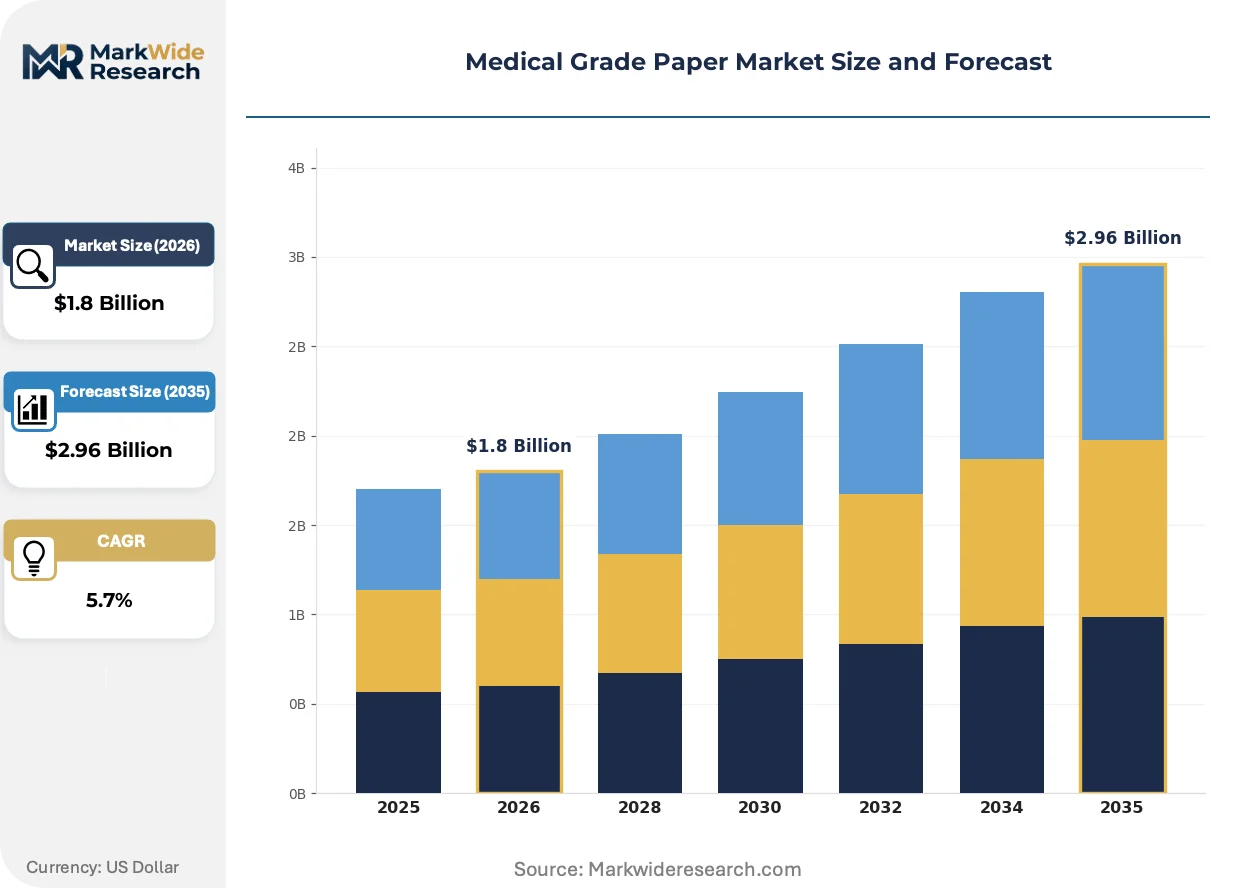
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Specialty Paper, Absorbent Paper End Use Industry: Pharmaceuticals, Medical Devices, Diagnostics, Packaging Grade: Bleached, Unbleached, Synthetic, Composite Application: Surgical Supplies, Lab Consumables, Patient Records, Packaging Materials |
| Companies Covered | KJ Specialty Paper Co., Ltd., Arctic Paper SA, BillerudKorsnäs AB, Navkar International, PMS, Amcor Limited, Efelab, WestRock, Anqing Tianrun Paper Packaging Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Grade Paper Market Strategic Shifts
Material science advances and regulatory stringency are converging to redefine performance benchmarks for sterilization-grade substrates. Manufacturers are racing to develop barrier solutions that satisfy both biological safety requirements and mechanical durability demands.
Multilayer composite structures that bond cellulose substrates with microporous polymer films are overtaking pure paper in implantable device packaging. Cardiovascular and orthopedic device manufacturers in Switzerland and Germany are specifying these hybrids for tray lidding applications. The technology is overtaking conventional uncoated grades by delivering puncture resistance without sacrificing EtO penetration rates.
The EU MDR's expanded technical documentation requirements are forcing paper converters to implement electronic batch records and supplier quality agreements that exceed ISO 9001 baselines. Device manufacturers now demand certificate of conformance data with every lot. Sterilization wrap suppliers serving the European market are responding by investing in automated inspection systems and blockchain-traceability pilots.
Hospital procurement departments are consolidating vendor lists and mandating long-term supply agreements with penalty clauses for sterilization validation failures. Group purchasing organizations in the United States are replacing spot-buying relationships with multi-year contracts that lock in paper specifications. This concentration is most visible among integrated delivery networks in Texas and California, where supply chain resilience has displaced unit cost as the primary selection criterion.
Medical Grade Paper Market Segmentation
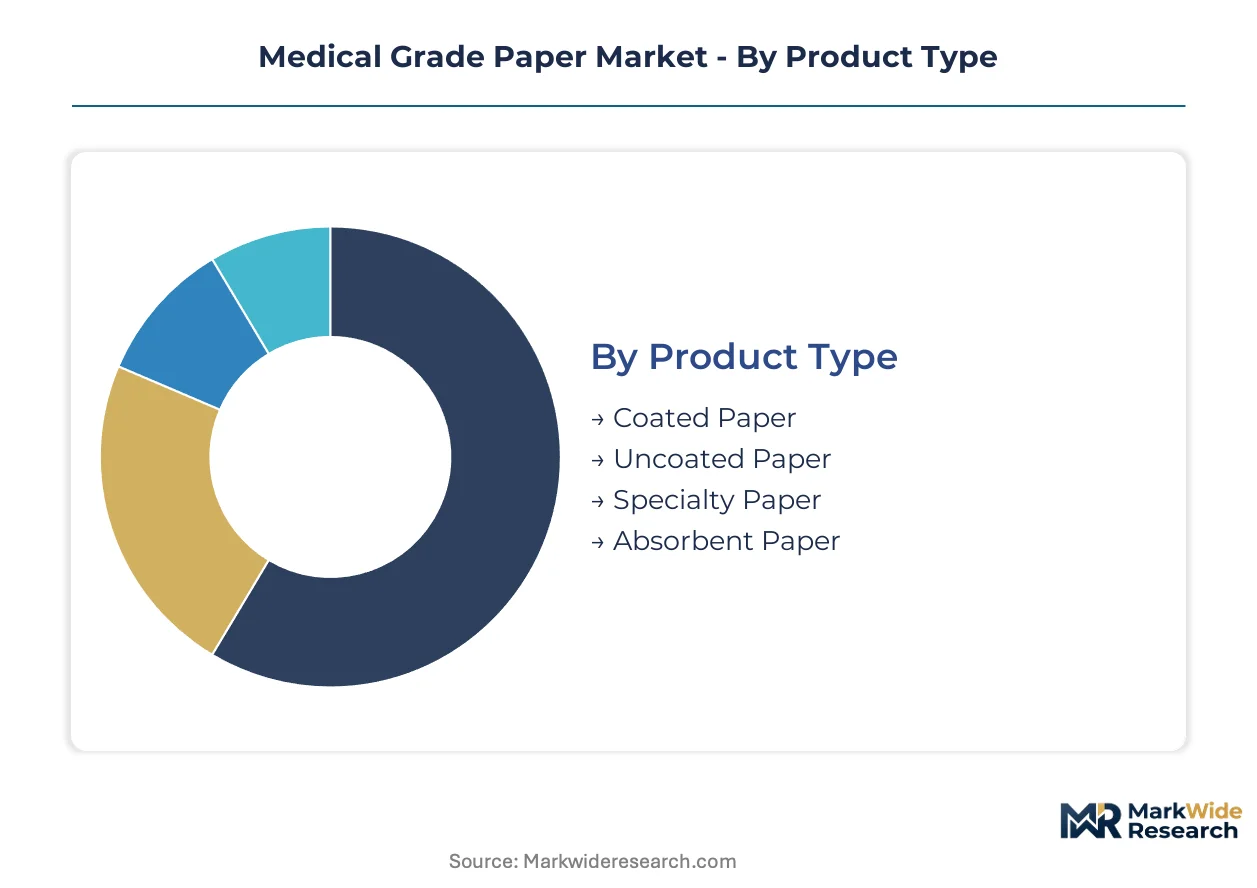
Segmentation in medical grade paper tracks how cellulose substrates align with sterilization protocols, device risk classes, and regulatory validation tiers. Each dimension reveals distinct margin structures and supplier capability requirements that shape procurement decisions across healthcare systems.
Product Type:
Uncoated grades serve standalone sterilization applications where porosity governs steam and ethylene oxide penetration, while coated and composite variants embed into multilayer barrier systems for implantable devices.
- Coated Paper:Polymer-treated surfaces provide moisture barriers for pharmaceutical blister packs and diagnostic kit lamination. Swiss orthopedic device manufacturers specify coated grades for tray lidding where puncture resistance intersects with sterilization access requirements.
- Uncoated Paper:Pure alpha-cellulose sheets engineered to controlled porosity thresholds dominate hospital sterilization wrap volumes. German hospital systems prioritize uncoated grades for surgical kit packaging where steam penetration rates must validate within narrow tolerance bands.
- Specialty Paper:Custom caliper and coefficient of friction parameters serve lateral flow diagnostic assays in California and Massachusetts manufacturing clusters.
- Absorbent Paper:Capillary-structured cellulose supports fluid collection in point-of-care testing devices regulated by FDA Class II protocols.
Uncoated paper leads volumes today; composite formulations are gaining share fastest.
End Use Industry:
Cost tiers separate commodity surgical wrap demand from premium diagnostic and implantable device applications where validation documentation commands price premiums.
- Pharmaceuticals:Sterile barrier papers for vial and ampoule packaging must satisfy FDA 21 CFR Part 820 batch traceability and endotoxin testing protocols that commodity converters cannot satisfy.
- Medical Devices:Cardiovascular and orthopedic implant packaging in Germany and Switzerland drives specification of multilayer composites combining cellulose porosity with synthetic puncture resistance.
- Diagnostics:Lateral flow assay manufacturers in California demand precise coefficient of friction control for automated kit assembly lines.
- Packaging:Contract sterilization providers serving US integrated delivery networks source validated wrap materials under multi-year supply agreements with penalty clauses for validation failures.
Medical Devices captures the steepest expansion trajectory; Packaging maintains the largest absolute volume position.
Grade:
Supply concentration in Nordic pulp regions favors bleached alpha-cellulose production, while synthetic and composite grades depend on polymer integration capabilities concentrated among North American and European converters.
- Bleached:High-purity alpha-cellulose from Scandinavian kraft pulp mills supplies surgical wrap and pharmaceutical packaging where fiber cleanliness governs biocompatibility outcomes.
- Unbleached:Lower-cost cellulose serves non-sterile medical documentation and secondary packaging applications with reduced regulatory validation burdens.
- Synthetic:Cellulose-derivative substrates engineered for specific gas permeability rates support ethylene oxide sterilization of heat-sensitive devices under EPA emissions scrutiny.
- Composite:Paper-polymer hybrid structures merge cellulose porosity with Tyvek-grade puncture resistance for implantable device segments previously closed to pure paper.
Bleached grade dominates procurement volumes today; Composite formulations are climbing the fastest.
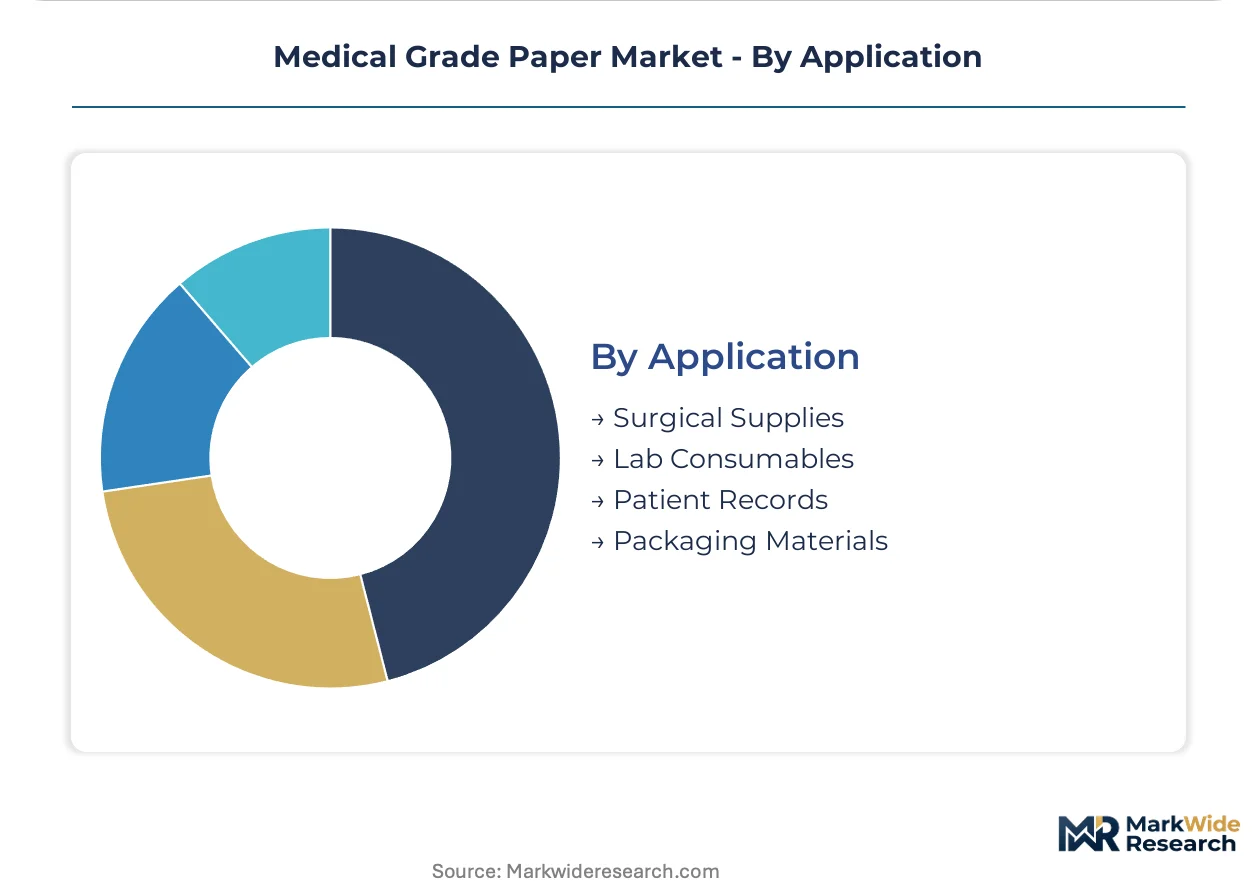
Application:
Application segmentation tracks how paper substrates integrate into sterile workflow hierarchies, from immediate patient contact through downstream documentation and logistics.
- Surgical Supplies:Sterilization wrap for instrument trays demands documented steam and ethylene oxide penetration performance that German hospital systems validate through ISO 11607 protocols.
- Lab Consumables:Absorbent and specialty papers for cell culture and diagnostic workflows require low-extractable profiles that California biotech clusters specify in supplier quality agreements.
- Patient Records:Archival-grade papers for medical documentation face digitization pressure but persist in jurisdictions with mandatory physical record retention under HIPAA and EU GDPR frameworks.
- Packaging Materials:Tray liners, lidding substrates, and secondary barriers for device distribution absorb the largest volume share across North American and European supply chains.
Packaging Materials leads volumes today; Lab Consumables is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulp chemistry expertise concentrates in Scandinavian mill towns and German technical universities, anchoring premium-grade cellulose production for sterile barrier applications.
United States
Integrated delivery networks in Texas and California mandate multi-year sterilization wrap contracts with penalty clauses for validation failures. FDA 21 CFR Part 820 quality system regulations compel batch-level traceability that commodity converters cannot satisfy. Boston and San Diego biotech clusters drive specification of low-extractable papers for diagnostic workflows.
Germany
Cardiovascular and orthopedic device manufacturers in Baden-Württemberg specify multilayer composites for tray lidding applications. EU MDR technical documentation requirements force paper converters to implement electronic batch records exceeding ISO 9001 baselines. The Rhine-Main manufacturing corridor hosts sterilization validation laboratories serving continental European supply chains.
Sweden
Nordic kraft pulp mills supply alpha-cellulose fiber with controlled purity from source to finished sheet. REACH chemical registration frameworks govern wet-strength resin additives used in steam-sterilizable grades. Stockholm and Gothenburg technical institutes retain specialized knowledge of medical paper chemistry.
India
CDSCO regulatory harmonization with ISO standards attracts contract packaging operations requiring certified sterilization-grade paper. Maharashtra and Gujarat medical device manufacturing zones source barrier substrates for export-oriented production. Mumbai pharmaceutical packagers face escalating validation protocol demands from European and North American customers.
Switzerland
Implantable device manufacturers in Basel and Zurich specify paper-polymer hybrids combining cellulose porosity with synthetic puncture resistance. Swissmedic technical documentation requirements exceed baseline EU thresholds for sterile barrier systems. The country's precision engineering culture extends to custom caliper specifications for diagnostic kit lamination.
Medical Grade Paper Market Competitive Environment
Capital-heavy pulp producers compete with asset-light converting specialists for control of sterilization-grade paper value chains. The supplier base compresses around certified manufacturers capable of endotoxin testing and batch traceability, while commodity players exit under regulatory pressure. Nordic integrated pulp-to-paper operators and North American packaging converters represent distinct strategic archetypes. Consolidation accelerates through selective acquisition of cleanroom converting assets and strategic partnerships with sterilization service providers.
Among Nordic integrated producers, BillerudKorsnäs AB anchors the premium-grade segment through captive pulp supply. North American packaging specialist WestRock occupies a position serving hospital systems through extensive converting infrastructure. Amcor Limited exemplifies the multilayer composite approach, merging paper substrates with polymer barriers for implantable device applications. These three represent contrasting responses to FDA and EU MDR validation requirements reshaping procurement criteria.
| Leading Market Players |
|---|
| KJ Specialty Paper Co., Ltd. |
| Arctic Paper SA |
| BillerudKorsnäs AB |
| Navkar International |
| PMS |
| Amcor Limited |
| Efelab |
| WestRock |
| Anqing Tianrun Paper Packaging Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Hospital group purchasing organizations in Texas and California concentrate procurement volume under multi-year sterilization wrap contracts, anchoring a contract-based long-term offtake model that locks in paper specifications and penalty structures for validation failures.
Pricing Analysis
Bundled sterilization validation services command premiums over unbundled commodity paper sales. Three-tier pricing structure across premium, standard, and economy levels separates ISO 11607-certified surgical wrap from diagnostic-grade specialty papers and unbleached documentation grades. Price differentiation rests on certification tier and wet-strength resin formulation expertise. Pricing pressure stems from polymer barrier substitution in implantable device segments where Tyvek alternatives capture share. Contract sterilization providers show least price sensitivity due to requalification timeline constraints, while commodity converters face intense cost compression.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO regulatory framework are reshaping sourcing patterns for export-oriented medical device manufacturers in Maharashtra and Gujarat. Geographic supply concentrates in Sweden, Finland, and Germany where Nordic kraft pulp mills and Baden-Württemberg converting infrastructure anchor alpha-cellulose fiber production. Raw material dependencies center on bleached alpha-cellulose pulp, wet-strength resin additives, and microporous polymer films for composite grades. Single-source vulnerability runs through Scandinavian pulp concentration exposed to regional energy cost volatility. Distribution runs through sterilization service providers and hospital system GPOs rather than spot commodity channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical grade paper market functions as a regulatory compounder where EU MDR technical documentation requirements and FDA 21 CFR Part 820 quality system mandates continuously elevate entry barriers and consolidate procurement around certified manufacturers.
For Market Incumbents: To counter polymer barrier substitution in implantable device packaging, BillerudKorsnäs and WestRock should deepen captive pulp integration and accelerate composite substrate R&D partnerships with cardiovascular device manufacturers in Switzerland and Germany. Certification investment in endotoxin testing infrastructure and blockchain-traceability systems will defend hospital system contract renewals against mid-tier challengers. For New Entrants and Emerging Players: Direct-to-sterilization-service-provider digital platforms offer the most penetrable route around legacy 18-24 month requalification cycles that freeze incumbent relationships. Target India's CDSCO-harmonized contract packaging operations in Maharashtra and Gujarat where ISO 11607 validation demand outpaces certified domestic supply. Specialty diagnostic kit lamination for California lateral flow assay manufacturers commands technical premiums beyond commodity wrap margins. For Investors and Strategic Acquirers: Packaging converters with hospital system GPO relationships are the most active acquirer in this space, seeking cleanroom converting assets and sterilization validation capabilities. Mid-tier European mills with wet-strength chemistry expertise but lacking endotoxin testing infrastructure represent the optimal acquisition target archetype. The signal to watch is EPA ethylene oxide emissions rulemaking, which would accelerate paper-polymer hybrid adoption or force sterilization method shifts invalidating existing paper formulations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR Part 820 Compliance Investment | Batch-level traceability systems satisfy quality system regulations that commodity converters cannot meet. |
| EU MDR Technical Documentation Pathway | Electronic batch records and supplier quality agreements exceed ISO 9001 baselines for European market access. |
| Hospital System Partnership | Multi-year supply agreements with Texas and California integrated delivery networks lock in sterilization wrap volumes. |
| Composite Substrate Development | Paper-polymer hybrids merge cellulose porosity with synthetic puncture resistance for implantable device segments. |
| CDSCO Regulatory Harmonization | ISO 11607-aligned validation protocols attract contract packaging operations to Maharashtra and Gujarat manufacturing zones. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with paper mill technical directors, hospital GPO procurement managers, sterilization service providers, biomedical engineers, and regulatory affairs specialists at cardiovascular device manufacturers with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, ISO 11607 certification registries, and Scandinavian pulp industry production disclosures. Bottom-up demand modeling from surgical wrap volumes and diagnostic kit lamination requirements triangulated against top-down market sizing from certified manufacturer capacity declarations.
Segment-weighting across product type, end use industry, grade, and application dimensions structured the analytical framework over the projection horizon. Uncoated sterilization wrap, coated pharmaceutical packaging, specialty diagnostic substrates, and composite implantable device barriers each carried distinct volume and margin assumptions. CAGRs derived from sterilization protocol persistence rates, regulatory validation timeline compression, and polymer substitution elasticity in high-barrier applications. Nordic pulp supply concentration and EPA ethylene oxide emissions pathways entered as scenario variables.
The model assumes a particular technology adoption path; alternative pathways for ethylene oxide sterilization phase-out or rapid Tyvek displacement would alter the outlook. Forecasts reflect documented assumptions regarding CDSCO harmonization pace, EU MDR enforcement stringency, and hospital procurement consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Canada Honeycomb Paper Market
Paper Products
Clay Coated Paper Market
Paper Products
Global Paperboard Market
Paper Products
Glassine Paper Market
Paper Products
Paper Based Laminates Market
Paper Products
Stone Paper Market
Paper Products
Semi Chemical Wood Pulp Market
Paper Products
Abaca Pulp Market
Paper Products
Pulp and Paper Chemicals Market
Paper Products
Digital Printing Paper Market
Paper Products
Carbonless Paper Market
Paper Products
Specialty Paper Market
Paper Products
Europe Decor Paper Market
Paper Products
Global Wood Pulp Market
Paper Products
Wood-Based Panel Market
Paper Products
Reprographic Paper Market