
 North America Polycarbonate (PC) Market | 2026-2036
North America Polycarbonate (PC) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polycarbonate (PC) Market Insights
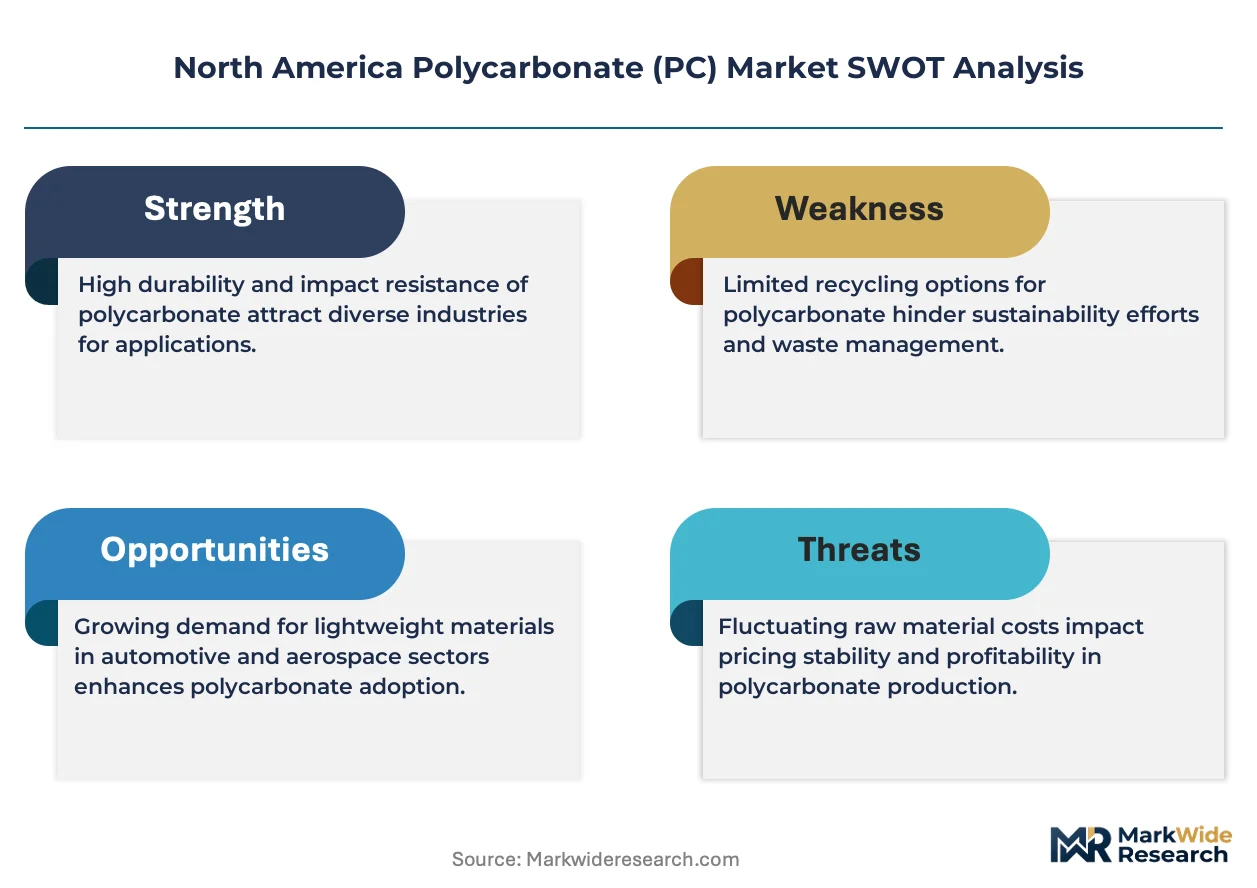
The EPA's Safer Choice program is hardening material selection criteria across durable goods supply chains. Covestro AG leverages its Baytown, Texas integrated production complex to sustain cost-competitive resin supply for North American automotive OEMs. SABIC anchors its position through high-heat PC formulations serving Tier-1 electronics suppliers. Trinseo competes on specialized optical-grade sheet output for LED lighting and display manufacturers.
Polycarbonate is a thermoplastic polymer synthesized from bisphenol A and phosgene, distinguished by optical clarity, impact resistance exceeding 200 times that of glass, and service temperatures up to 135°C. It serves primarily as a lightweight, shatter-resistant substitute for glass and metal in safety-critical and optical applications. Film and sheet categories dominate current volume flows, with resin grades capturing margin pools in medical device and aerospace qualification tiers. Automotive applications are expanding fastest as electrification drives battery enclosure and thermal management demand, while construction remains mature with replacement-cycle dependency.
US EPA regulations on bisphenol A exposure limits, California's Proposition 65 labeling requirements, and OSHA workplace chemical exposure standards collectively shape formulation choices and market access thresholds for PC producers. Health Canada maintains aligned but independently enforced food-contact material restrictions affecting cross-border sheet and film trade. Stakeholders must monitor evolving state-level extended producer responsibility legislation and its potential to restructure recycling infrastructure economics for engineering thermoplastics.
Market Dynamics
Electric vehicle battery enclosure specifications are concentrating polycarbonate demand along the US Gulf Coast petrochemical corridor, while EPA Safer Choice program criteria harden material selection thresholds across durable goods supply chains.
Growth Catalysts
- Battery Enclosure Specifications:EV thermal management requirements are expanding high-heat polycarbonate grades into battery housing assemblies, displacing metal substrates in North American automotive platforms.
- Extended Producer Responsibility:California and New York state-level EPR frameworks are mandating recycled content thresholds, creating pull-through demand for post-industrial PC regrind streams.
- Optical Sheet Applications:LED diffusion panel and display backlighting specifications are concentrating volume in specialized optical-grade sheet production.
Market Restraints
- Bisphenol A Feedstock Volatility:BPA price swings and EPA exposure limit enforcement compress formulation flexibility for food-contact and medical device grades.
- Gulf Coast Supply Concentration:Integrated production clusters in Texas and Louisiana create hurricane and freeze-risk exposure for North American resin availability.
- Glass-Metal Substitution Ceiling:Acrylic and tempered glass advances in architectural glazing limit PC penetration in premium construction segments.
Strategic Opportunities
- Canadian Recycling Infrastructure:Ontario and Quebec EPR implementation lags create first-mover positioning for closed-loop PC collection and reprocessing systems.
- Medical Device Qualification Tiers:US FDA 510(k) and Health Canada MDEL pathways for sterilizable PC grades open margin pools in surgical instrument housings.
- Lightweighting Mandates:NHTSA CAFE standards and EPA vehicle emissions rules are accelerating PC composite adoption in interior and exterior automotive panels.
Industry Challenges
- Phosgene Handling Certification:OSHA Process Safety Management compliance and specialized operator training requirements constrain workforce scalability for integrated producers.
- Cross-Border Regulatory Misalignment:Divergent Health Canada and FDA food-contact material approvals create SKU proliferation and inventory segmentation costs for sheet and film distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polycarbonate (PC) Market |
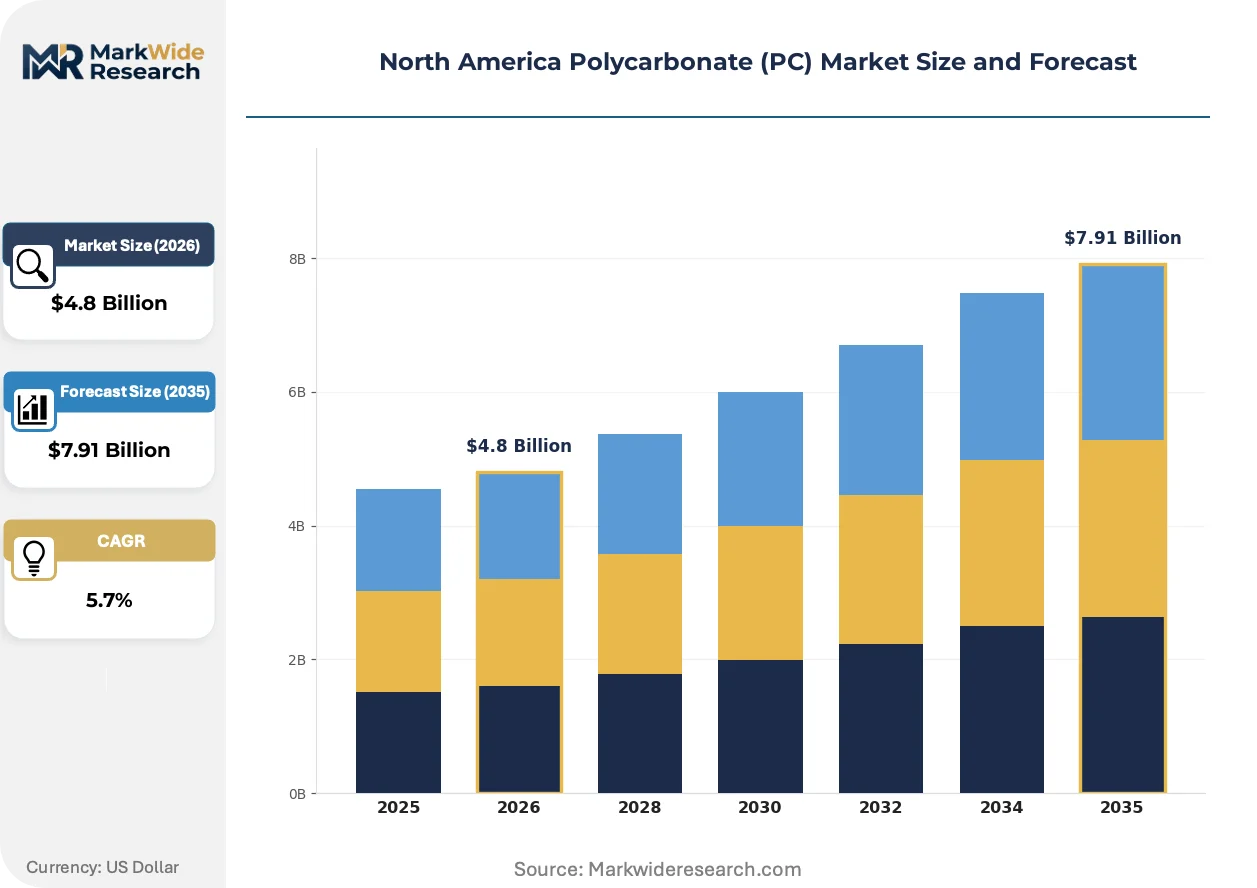
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film, Sheet, Resin, Blends Application: Aerospace, Automotive, Electronics, Construction End User: OEMs, Tier-1 Suppliers, Retail, Manufacturing Distribution Channel: Direct Sales, Online, Distributors, Wholesalers |
| Companies Covered | Covestro AG, SABIC, Teijin Limited, Mitsubishi Chemical Corporation, DuPont, LG Chem, Trinseo, Evonik Industries AG, AGC Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polycarbonate (PC) Market Trends and Innovations
Bio-based feedstock development, regulatory chemistry restrictions, and buyer consolidation in automotive Tier-1 supply chains are restructuring competitive positioning across polycarbonate value streams.
Non-phosgene melt transesterification routes are rewriting process economics for specialty-grade production. Covestro and SABIC pilot facilities in Texas are validating commercial-scale output without chlorine-based intermediates. This technology is rewriting environmental compliance cost structures for producers serving EPA-regulated durable goods markets.
EPA Safer Choice program criteria expansion is tightening bisphenol A exposure thresholds in consumer-facing applications. Industrial consequence includes accelerated reformulation toward BPA-free copolycarbonate grades for food-contact and pediatric product segments. Medical device and infant care product categories are most affected, with suppliers pursuing Health Canada aligned certifications to maintain cross-border market access.
Automotive OEM direct material qualification is compressing distributor roles in battery enclosure supply chains. Tier-1 electronics suppliers are consolidating procurement through approved vendor lists with captive resin specifications. This pattern is most visible in Michigan and Ohio assembly corridors, where Ford and GM platforms specify PC grades at the vehicle program level rather than component level.
North America Polycarbonate (PC) Market Segmentation
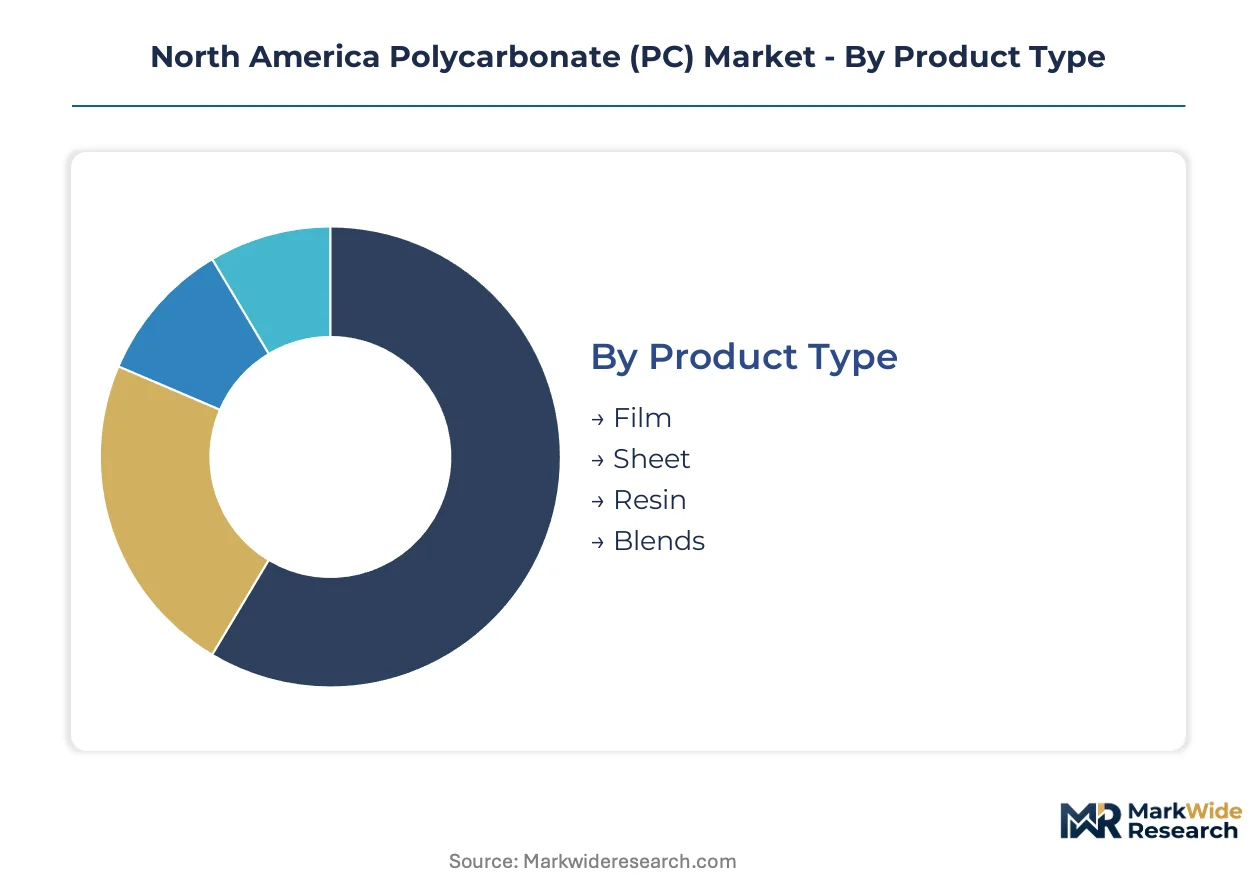
Polycarbonate market segmentation reveals how material specifications align with performance requirements across safety-critical and optical applications. Upgrade cycles in automotive electrification and LED lighting are restructuring volume flows between commodity and specialty grades.
Product Type:
Replacement cycles vary sharply across product categories, with film and sheet demanding annual restocking while resin qualifications lock in multi-year supply agreements.
- Film:Thin-gauge extruded products serve graphic overlay and membrane switch applications. Demand clusters in Michigan automotive electronics corridors where Ford and GM specify PC film for instrument panel interfaces.
- Sheet:Thick-gauge extruded and cast products dominate architectural glazing and LED diffusion panels. Texas and Ohio manufacturing hubs concentrate optical-grade sheet output for display backlighting specifications.
- Resin:Virgin and compounded pellets feed injection molding operations across medical device and aerospace tiers.
- Blends:PC-ABS and PC-PBT alloys deliver tailored impact and heat resistance for consumer electronics housings.
Volume placements concentrate in Sheet; the faster expansion belongs to Resin.
Application:
Cost tiers separate qualification-intensive aerospace and medical segments from price-sensitive construction applications.
- Aerospace:FAA-certified flame-retardant grades meet strict smoke and toxicity specifications for aircraft interior components. Texas Gulf Coast producers anchor supply for Boeing and Airbus Tier-1 fabricators.
- Automotive:Battery enclosure and thermal management assemblies are displacing metal substrates in EV platforms. Michigan and Ohio assembly corridors specify high-heat PC grades at vehicle program level.
- Electronics:LED lighting and display backlighting concentrate demand in optical-grade formulations.
- Construction:Mature replacement-cycle dependency limits growth in architectural glazing and sound barrier applications.
Construction captures the largest volume base; automotive delivers the steepest expansion trajectory.
End User:
Customer type determines specification control, with OEMs dictating material grades and Tier-1 suppliers managing procurement execution.
- OEMs:Ford, GM, and Tesla direct-qualify PC grades for battery housings and interior panels, compressing distributor influence in automotive supply chains.
- Tier-1 Suppliers:Delphi, Magna, and Lear consolidate procurement through approved vendor lists with captive resin specifications.
- Retail:Hardware chains and building material outlets stock standard sheet and film gauges for contractor pickup.
- Manufacturing:Custom fabricators and thermoformers source resin and sheet for secondary conversion into finished components.
Procurement authority rests with OEMs; margin capture favors Tier-1 Suppliers.
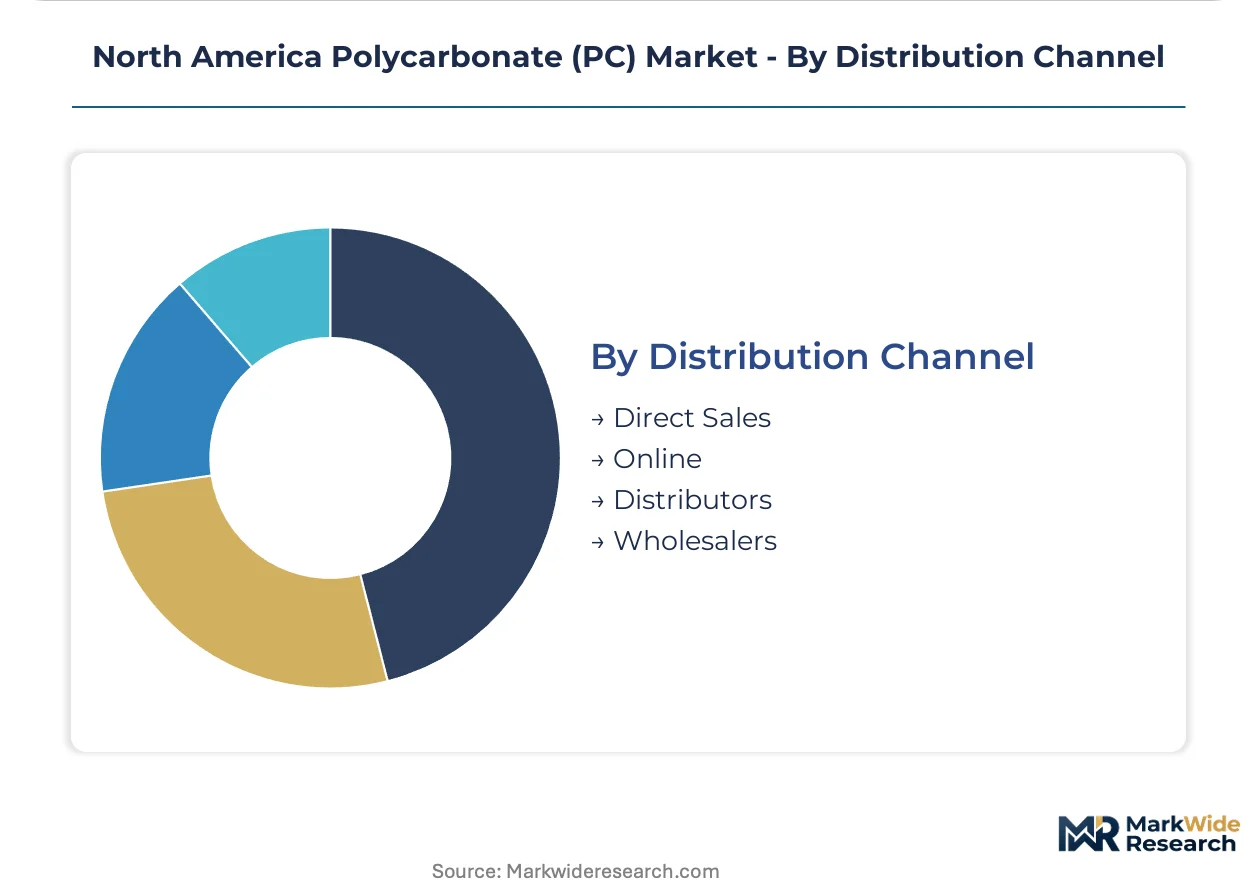
Distribution Channel:
Supply concentration along the Gulf Coast petrochemical corridor shapes channel economics and lead time structures.
- Direct Sales:Covestro and SABIC maintain mill-direct relationships with automotive OEMs and aerospace Tier-1s, bypassing distributor margins on high-volume contracts.
- Distributors:Nexeo Solutions and Univar Solutions stock standard resin grades and sheet products for mid-volume manufacturers without direct mill qualification.
- Online:Specialized optical sheet and small-lot resin sales through industry-specific platforms serve prototype and R&D demand.
- Wholesalers:Regional building material wholesalers handle construction-grade sheet for architectural glazing contractors.
Direct Sales commands the highest volume share; Distributors retain the broadest SKU breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters along the US Gulf Coast while consumption spreads across automotive corridors and electronics manufacturing hubs. Canada and Mexico operate as integrated supply chain extensions with distinct regulatory frameworks. Regional dynamics hinge on EPA enforcement intensity, state-level extended producer responsibility legislation, and cross-border material certification alignment.
United States
EV battery enclosure demand concentrates in Michigan and Ohio assembly corridors where Ford and GM specify PC grades at the vehicle program level. EPA Safer Choice program criteria harden material selection thresholds across durable goods supply chains. Texas Gulf Coast petrochemical complexes anchor resin production for North American automotive OEMs.
Canada
Ontario and Quebec EPR implementation lags create first-mover positioning for closed-loop PC collection and reprocessing systems. Health Canada maintains independently enforced food-contact material restrictions affecting cross-border sheet and film trade. Automotive parts manufacturing in Windsor and Oshawa corridors sustains resin demand from US suppliers.
Mexico
Nearshoring of automotive electronics assembly expands optical-grade sheet consumption in Baja California and Chihuahua manufacturing zones. Mexican environmental regulations lack equivalent EPA exposure limit enforcement, creating formulation flexibility for non-food-contact applications. Monterrey industrial corridor hosts thermoforming operations serving US construction markets.
North America Polycarbonate (PC) Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical producers with captive phosgene handling capabilities and specialized compounders serving qualification-intensive tiers. Three archetypes dominate: Gulf Coast resin producers with backward integration into BPA feedstock, optical-grade sheet specialists with display industry certifications, and medical-device-grade compounders with FDA and Health Canada alignment. Capacity expansion and portfolio diversification toward BPA-free copolycarbonate grades represent the dominant competitive moves.
Among integrated resin producers, Covestro AG anchors the Gulf Coast production corridor through its Baytown, Texas complex. SABIC occupies a position serving high-heat formulation demand from Tier-1 electronics suppliers. Trinseo exemplifies the specialized compounder archetype with optical-grade sheet output for LED lighting manufacturers.
| Leading Market Players |
|---|
| Covestro AG |
| SABIC |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| DuPont |
| LG Chem |
| Trinseo |
| Evonik Industries AG |
| AGC Group |
| Others |
Pricing and Supply Chain Analysis
Bisphenol A spot price indices cascade through polycarbonate value chains into three-tier pricing structures across premium, standard, and economy levels. Gulf Coast resin producers translate feedstock volatility into contract renegotiation leverage with automotive OEMs, while optical-grade sheet specialists command fixed-price premiums through display industry qualification lock-ins.
Pricing Analysis
Yield-based pricing anchors optical-grade sheet contracts to LED panel throughput guarantees, separating premium certified grades from standard architectural tiers. Price differentiation rests on FDA 510(k) certification status and volume scale, with medical-device compounders capturing 40% premiums over construction-grade resin. Cost compression in commodity sheet intensifies as acrylic substitution accelerates in architectural glazing. Tier-1 automotive suppliers exhibit lowest price sensitivity due to program-level qualification requirements, while retail hardware channels face margin erosion from spot-market resin volatility.
Supply Chain Analysis
Dual-sourcing mandates from Ford and GM platform engineers require qualified resin supply from both Texas and Louisiana production corridors simultaneously. Geographic supply concentration centers on the US Gulf Coast, with Ontario reprocessing emerging as secondary feedstock source. Raw material dependencies draw from BPA monomer, phosgene intermediates, and optical-grade additive packages. Single-source vulnerability intensifies around hurricane-season production interruptions. Distribution runs through mill-direct contracts for automotive OEMs, with Nexeo Solutions and Univar Solutions handling mid-volume resin and sheet fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-phosgene melt transesterification technology is displacing legacy chlorine-based polycarbonate synthesis, compressing environmental compliance cost structures and rewriting qualification requirements for EPA-regulated durable goods supply chains.
For Market Incumbents: Acquire closed-loop recycling assets in Ontario and Quebec before EPR mandates harden post-industrial regrind specifications. Backward integration into BPA feedstock buffers margin compression from spot price volatility. Covestro and SABIC must defend optical-grade certification positions against emerging copolycarbonate entrants targeting pediatric product segments.
For New Entrants and Emerging Players: Enter via Canadian EPR implementation gaps with localized collection and reprocessing infrastructure serving US automotive OEMs seeking recycled content compliance. Target medical-device-grade compounding in Windsor corridor leveraging Health Canada MDEL pathway alignment with FDA 510(k) standards. Pursue direct qualification with Tier-1 electronics suppliers rather than distributor channel penetration.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized optical-grade sheet producers with captive display industry certifications in Texas and Ohio manufacturing hubs. Five-to-ten year viability hinges on BPA-free copolycarbonate formulation pivots and automotive lightweighting mandate acceleration. Monitor EPA Safer Choice program criteria expansion as inflection signal for reformulation capex requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Non-phosgene Process Scale-up | Covestro and SABIC pilot facilities in Texas validate chlorine-free production economics for EPA compliance. |
| Backward Integration into BPA Feedstock | Captive monomer supply secures margin stability against spot price volatility in Gulf Coast corridors. |
| Canadian Recycling Infrastructure Buildout | Ontario and Quebec EPR lags create first-mover positioning for closed-loop PC collection systems. |
| Medical Device Certification Investment | FDA 510(k) and Health Canada MDEL alignment opens surgical instrument housing margin pools. |
| Automotive OEM Direct Qualification | Ford and GM platform-level specification bypasses distributor influence in battery enclosure supply chains. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this polycarbonate market assessment. Primary interviews with plant managers at Gulf Coast resin complexes, procurement leads at Michigan automotive Tier-1s, distribution channel partners stocking optical-grade sheet, and technical R&D directors developing BPA-free formulations combined with secondary validation from EPA Safer Choice program databases, ACC industry reports, SEC 10-K disclosures, and Health Canada MDEL registration files. Bottom-up volume modeling across product categories triangulated against top-down petrochemical capacity assessments.
Segment-level granularity modeled resin grade tiers, end-use industries spanning automotive electrification and LED lighting, regional production hub economics, and qualification-intensive versus commodity volume splits. CAGRs derived from demand elasticity analysis against EV battery enclosure specifications and construction replacement cycles. Industry-specific forecast inputs incorporated NHTSA CAFE standard stringency trajectories and state-level EPR implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under hurricane-induced Gulf Coast production interruptions and accelerated EPA bisphenol A exposure limit enforcement. Deviation in automotive OEM lightweighting mandate adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle-East and Africa Fluoropolymers Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Polymers for Electric Vehicle (EV) Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Asia-Pacific Polycarbonate (PC) Market
Polymers & Resins
Polymer Plastic Plain Bearings Market
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
Semi-Rigid Spray Polyurethane Foam Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market