
 Specialty and High Performance Films Market | 2026-2036
Specialty and High Performance Films Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty and High Performance Films Market Outlook
Software-defined optical tuning is consolidating what specialty film suppliers monetize, shifting revenue from static material sales to programmable performance layers. 3M leverages its patent portfolio in multilayer optical film to command premium positioning in display brightness enhancement. Toray Industries anchors Asian supply chains through captive resin production and downstream film extrusion. Evonik Industries AG differentiates via high-purity cyclo-olefin polymer grades for pharmaceutical blister packaging.
Specialty and high performance films comprise engineered polymer substrates with controlled thickness tolerances, typically ranging from sub-micron to several hundred microns, manufactured through precision extrusion, biaxial orientation, or solution casting to deliver specific optical, barrier, thermal, or mechanical functions across demanding industrial environments. Polyester films dominate optical and electronic applications due to superior dimensional stability and clarity, while polyethylene variants sustain volume leadership in food packaging where moisture barrier and sealability matter most. Polypropylene films occupy the fastest-growing niche in capacitor-grade metallization for electric vehicle power electronics, where dielectric strength and thermal endurance command margin premiums.
The EPA regulates volatile organic compound emissions from solvent-based coating processes used in specialty film manufacturing, pushing converters toward aqueous and UV-cured alternatives. FDA material contact notifications govern healthcare film compositions for pharmaceutical and medical device packaging, creating compliance moats for qualified suppliers. The EU REACH framework restricts phthalate plasticizers and perfluorinated substances in consumer-facing film applications, reshaping formulation roadmaps. Stakeholders must monitor how evolving semiconductor packaging standards and automotive electrification targets redefine thickness and thermal performance specifications before committing capacity expansions.
Market Dynamics
Barrier film specifications for foldable electronics are forcing resin suppliers to co-develop optical-grade substrates with display stack integrators, collapsing the traditional specification gap between material science and end-device engineering.
Growth Catalysts
- Semiconductor packaging films:Advanced substrate materials for chiplet architectures are pulling ultra-thin polyimide and cyclo-olefin polymers into high-volume production.
- REACH substance restrictions:The EU framework's phasing of perfluorinated compounds is accelerating reformulation investment toward bio-based barrier coatings.
- China display cluster:Panel fabs in Hefei and Shenzhen are consolidating procurement of locally-extruded optical polyester to reduce import dependency.
Market Restraints
- Capacitor-grade resin concentration:Polypropylene homopolymer supply for EV power electronics concentrates among three Asian petrochemical complexes, creating single-source vulnerability.
- Optical film thickness tolerance:Sub-micron uniformity requirements for polarizer substrates limit qualified machine-direction orientation lines to under twelve facilities worldwide.
- Fluorinated process chemistry:EPA emission controls on solvent recovery systems add capital intensity to anti-reflective coating operations without mature aqueous alternatives.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO's tightening blister-pack integrity standards are opening qualification windows for cyclo-olefin polymer films previously excluded by incumbent suppliers.
- UV-cured barrier deposition:Electron-beam crosslinking of silicon oxide layers onto flexible substrates is converging with roll-to-roll atomic layer deposition for hybrid coating architectures.
- Direct-to-fab distribution:Display manufacturers in Gyeonggi Province are bypassing regional distributors to contract extrusion capacity directly, compressing channel margins.
Industry Challenges
- Multi-layer coextrusion expertise:The shortage of process engineers capable of tuning 200+ layer optical stacks is extending commissioning timelines for new barrier film lines.
- Automotive qualification cycles:AEC-Q200 certification for capacitor films used in traction inverters requires 18-24 month validation protocols that mismatch semiconductor roadmaps.
- Legacy solvent coating integration:Converters with installed aqueous coating capacity face retrofit costs exceeding greenfield investment when adding high-barrier metallization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty and High Performance Films Market |
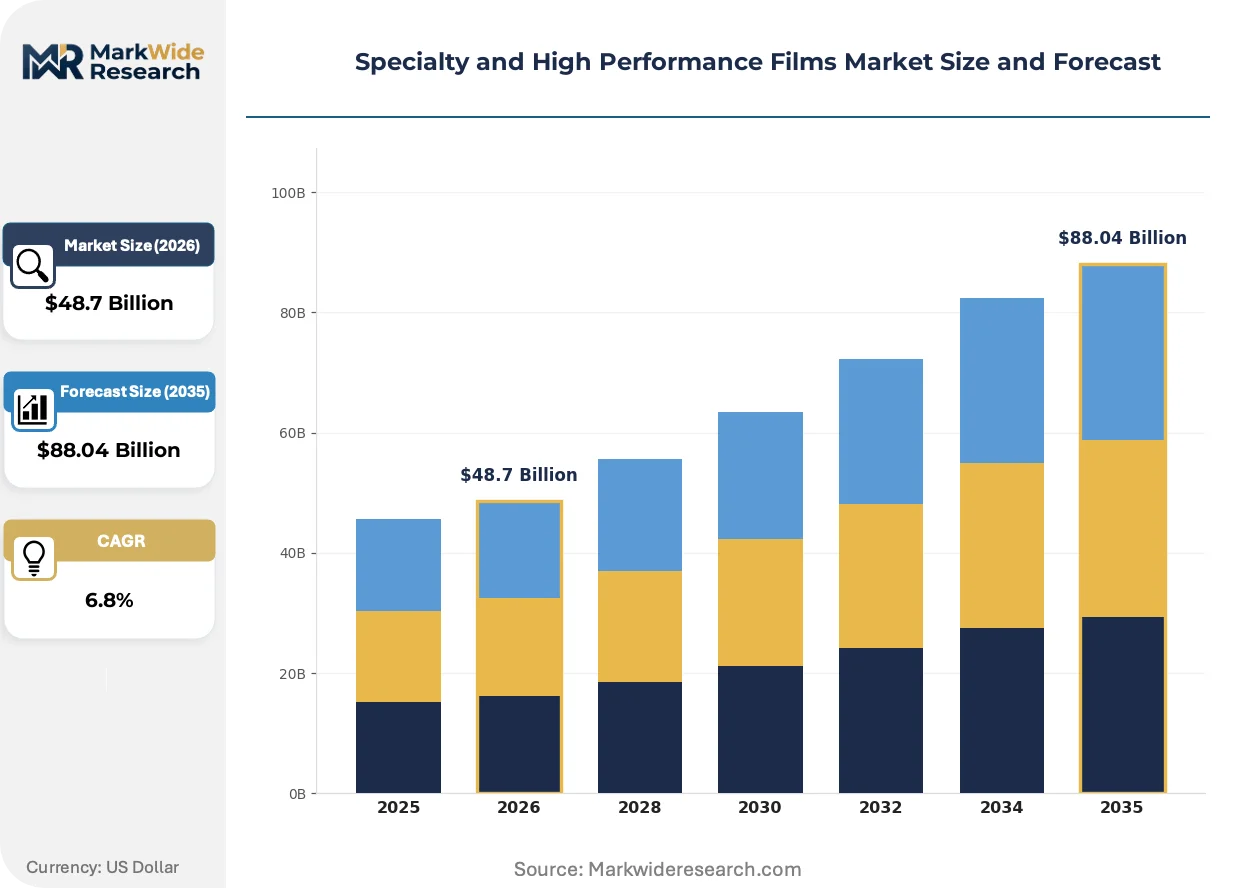
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester Application: Packaging, Automotive, Electronics, Construction End User: Food & Beverage, Healthcare, Retail, Consumer Goods Thickness: Thin, Medium, Thick, Ultra-thin |
| Companies Covered | 3M, BASF SE, Evonik Industries AG, The Dow Chemical Company, Saint-Gobain, Covestro AG, Solvay, DuPont Teijin Films, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty and High Performance Films Market Strategic Shifts
Programmable optical performance is displacing static material specifications across display and semiconductor packaging applications, with software-defined tuning layers becoming the primary value capture mechanism rather than substrate commodity supply.
Solution-cast polyimide films with embedded quantum dot color conversion layers are decentralizing the traditional supply chain separation between emitter materials and display substrates. Panel manufacturers in South Korea and China are integrating these films directly into mini-LED backlight units, compressing the number of discrete optical components by half while shifting margin capture upstream from assembly houses to material suppliers.
REACH authorization requirements for di(2-ethylhexyl) phthalate in medical device films are forcing compounders toward citrate and trimellitate alternatives with inferior low-temperature flexibility. German packaging converters serving pharmaceutical blister markets are absorbing 15-20% formulation cost premiums to maintain EU market access, while their North American counterparts face divergent FDA material contact notification pathways that delay product harmonization.
Consolidated procurement by display stack integrators is compressing specification autonomy previously held by individual brand OEMs. Samsung Display and BOE Technology now dictate optical film thickness, haze, and birefringence tolerances directly to Toray Industries and SKC, bypassing the historical role of panel assembly houses as specification intermediaries and compressing supplier margins through volume-commitment contracting.
Specialty and High Performance Films Market Segmentation
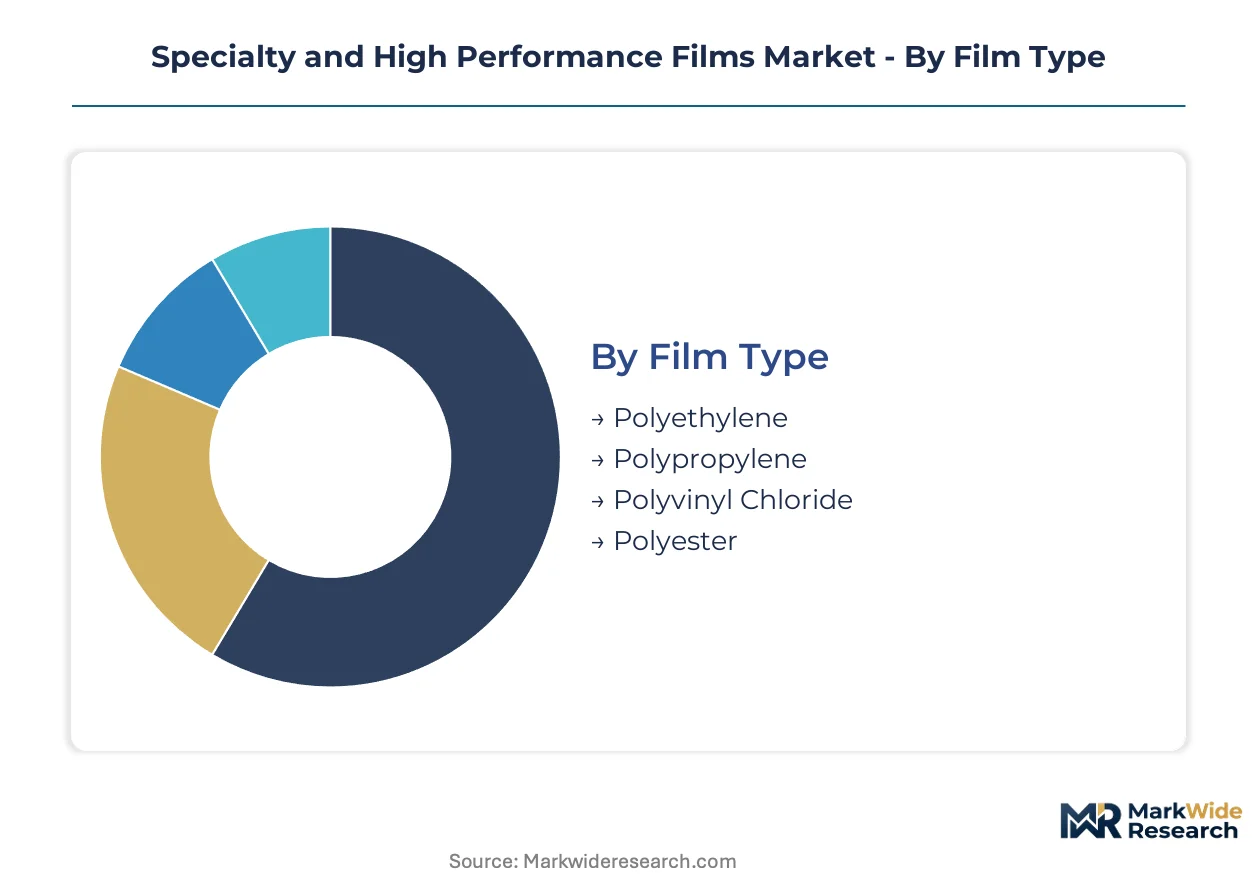
Specialty and high performance films serve radically different performance requirements across film type, application, and end-user specifications. Upgrade cycles in semiconductor packaging and automotive electrification are collapsing legacy segmentation boundaries as material suppliers co-develop substrates with downstream integrators.
Film Type:
Replacement cycles for optical-grade substrates are shortening as display manufacturers demand programmable performance layers rather than static material supply.
- Polyester:Biaxially oriented polyethylene terephthalate delivers superior dimensional stability and optical clarity for polarizer substrates and flexible display backplanes. Panel fabs in Hefei and Shenzhen are consolidating procurement of locally-extruded optical polyester to reduce import dependency from Japanese suppliers.
- Polypropylene:Metallized biaxially oriented polypropylene films provide dielectric strength and thermal endurance for EV power electronics capacitors. Three Asian petrochemical complexes concentrate homopolymer supply, creating single-source vulnerability for traction inverter manufacturers.
- Polyethylene:Low-density and linear low-density variants dominate moisture barrier applications in food packaging where sealability and cost efficiency matter most.
- Polyvinyl Chloride:Plasticized and unplasticized grades serve pharmaceutical blister packaging with established regulatory pathways through FDA material contact notifications.
Polyethylene sits at the top of the volume ranking, with polypropylene climbing the fastest.
Application:
Cost tier differentiation separates commodity packaging films from premium grades commanding margin premiums in semiconductor and automotive qualification cycles.
- Electronics:Barrier films for foldable displays and chiplet packaging substrates require sub-micron thickness tolerances and anti-reflective coatings. REACH substance restrictions on perfluorinated compounds are accelerating reformulation toward silicon oxide barrier layers deposited via roll-to-roll atomic layer deposition.
- Automotive:Capacitor-grade films for traction inverters must survive AEC-Q200 certification protocols spanning 18-24 months. German and South Korean automakers are pulling polypropylene dielectrics into high-voltage power electronics faster than validation timelines can accommodate.
- Packaging:High-barrier metallization and transparent oxide coatings preserve shelf stability for oxygen-sensitive pharmaceuticals and perishable foods.
- Construction:Weatherable fluoropolymer and acrylic films protect photovoltaic backsheet laminates from UV degradation and moisture ingress.
Packaging maintains volume leadership, while electronics gains share fastest on semiconductor packaging film demand.
End User:
Customer type concentration in healthcare and food sectors creates divergent compliance moats around FDA, EMA, and CDSCO qualification pathways.
- Healthcare:Cyclo-olefin polymer films for pharmaceutical blister packaging must satisfy FDA material contact notifications and EU MDR requirements. CDSCO's tightening integrity standards in India are opening qualification windows for suppliers previously excluded by incumbents.
- Food & Beverage:Oxygen and moisture barrier specifications vary sharply between ambient shelf-stable products and modified-atmosphere packaging for fresh proteins.
- Consumer Goods:Cosmetic and personal care applications demand aesthetic clarity and chemical resistance for premium positioning.
- Retail:Point-of-purchase display films and tamper-evident packaging balance printability with mechanical durability.
Food & Beverage anchors volume demand, with healthcare expanding most quickly on pharmaceutical packaging compliance requirements.
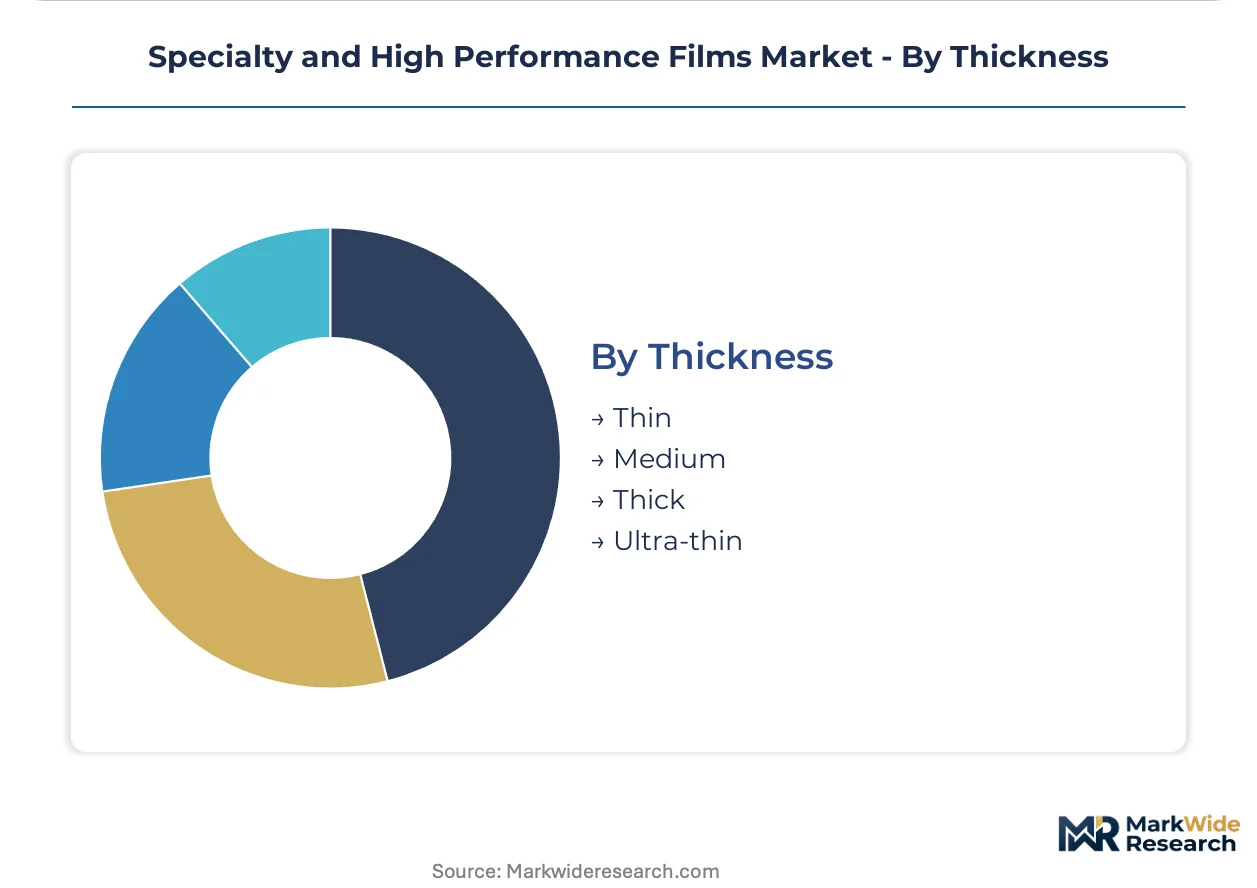
Thickness:
Supply concentration in ultra-thin and thin categories limits qualified machine-direction orientation lines to under twelve facilities worldwide.
- Ultra-thin:Sub-micron films for polarizer substrates and semiconductor packaging require precision extrusion and biaxial orientation capabilities possessed by Toray Industries, SKC, and a handful of specialized converters.
- Thin:One- to twelve-micron films serve capacitor dielectrics and flexible display substrates where dielectric strength must coexist with mechanical flexibility.
- Medium:Twelve- to fifty-micron grades balance barrier performance with handling characteristics for food packaging and industrial lamination.
- Thick:Fifty- to several-hundred-micron films provide structural rigidity for photovoltaic backsheets and architectural glazing interlayers.
Medium thickness grades dominate current volume, though ultra-thin films follow the steepest expansion trajectory on foldable electronics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's display manufacturing clusters consume optical-grade polyester at volumes that dwarf Germany's pharmaceutical packaging demand, yet both markets command equivalent supplier attention through divergent qualification pathways.
United States
Semiconductor packaging films for chiplet architectures pull ultra-thin polyimide substrates into high-volume production. EPA emission controls on solvent recovery systems add capital intensity to anti-reflective coating operations. Austin and Phoenix semiconductor corridors are consolidating procurement of locally-extruded barrier films to reduce import dependency from Asian suppliers.
Germany
Pharmaceutical blister packaging converters absorb formulation cost premiums to maintain EU market access under REACH authorization requirements. ECHA substance restrictions on phthalate plasticizers are forcing compounders toward citrate alternatives with inferior low-temperature flexibility. Bavarian packaging clusters serving medical device markets face divergent FDA notification pathways that delay product harmonization with North American operations.
China
Panel fabs in Hefei and Shenzhen are consolidating procurement of locally-extruded optical polyester to reduce import dependency from Japanese suppliers. NMPA regulations govern pharmaceutical film compositions while MIIT standards shape display substrate specifications. Yangtze River Delta manufacturing corridors are bypassing regional distributors to contract extrusion capacity directly from resin suppliers.
Japan
Optical-grade polyester films for polarizer substrates require sub-micron thickness tolerances that limit qualified machine-direction orientation lines. METI industrial standards coordinate with JIS specifications for capacitor-grade polypropylene dielectrics. Kanto and Kansai manufacturing belts anchor Asian supply chains through captive resin production and downstream film extrusion.
South Korea
Display stack integrators in Gyeonggi Province dictate optical film specifications directly to material suppliers, bypassing historical panel assembly intermediaries. MFDS pharmaceutical packaging regulations create compliance moats for qualified suppliers serving blister-pack markets. Busan-Ulsan petrochemical corridors concentrate polypropylene homopolymer supply for EV power electronics capacitors.
Specialty and High Performance Films Market Competitive Environment
Top-tier vendors anchor premium optical and barrier film segments, while mid-scale converters occupy commoditized packaging tiers. The vendor base stratifies across three functional layers: integrated resin-to-film producers, specialized coating converters, and regional distribution-assemblers. Two dominant competitive moves define current positioning: backward integration into captive resin production to secure polypropylene homopolymer supply, and direct-to-fab distribution contracts that compress channel margins.
Within the integrated producer archetype, Toray Industries and DuPont Teijin Films occupy positions exemplifying captive supply chain control from polymer synthesis through precision extrusion. Evonik Industries AG represents the specialty chemical pathway, differentiating through high-purity cyclo-olefin polymer grades. These three entities illustrate how qualification moats around FDA material contact notifications and REACH compliance create defensible positioning against unqualified regional competitors.
| Leading Market Players |
|---|
| 3M |
| BASF SE |
| Evonik Industries AG |
| The Dow Chemical Company |
| Saint-Gobain |
| Covestro AG |
| Solvay |
| DuPont Teijin Films |
| Toray Industries |
| Others |
Value Chain & Pricing Dynamics
Roll-to-roll atomic layer deposition adoption is compressing coating costs for barrier films while simultaneously concentrating qualified equipment supply among German and Japanese toolmakers. This process transition rewards converters with installed aqueous coating capacity, while legacy solvent-based operators absorb retrofit premiums or exit high-barrier segments entirely.
Pricing Analysis
Capacity additions in China are reshaping price floors for optical-grade polyester films, forcing Japanese incumbents to defend premium positioning through tighter thickness tolerances. Contract-based long-term offtake dominates display stack procurement, with FDA and REACH certification tiers commanding 15-20% premiums over standard grades. Cost compression in commodity packaging films is intensifying because Chinese panel fabs are consolidating procurement of locally-extruded substrates. Food and beverage packaging buyers exhibit highest price sensitivity, while semiconductor packaging integrators prioritize qualification reliability over unit cost.
Supply Chain Analysis
AEC-Q200 and FDA material contact notifications gate qualified supply for capacitor and pharmaceutical films, limiting certified production to facilities in Japan, Germany, and South Korea. Polypropylene homopolymer feedstock draws from three Asian petrochemical complexes, while optical-grade polyester resin sources from captive operations at Toray Industries and SKC. Single-source vulnerability in EV-grade capacitor resins exposes traction inverter manufacturers to allocation risk. Distribution runs through direct-to-fab contracts in Gyeonggi Province and Hefei, compressing regional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as semiconductor packaging and automotive electrification pull ultra-thin films into high-volume production. Material suppliers co-developing substrates with downstream integrators capture margin expansion unavailable to static commodity producers.
For Market Incumbents: Deploy captive resin production to secure polypropylene homopolymer supply against single-source concentration risk. Expand aqueous coating capacity to preempt EPA emission control retrofit costs. Reinforce qualification moats through accelerated FDA material contact notification submissions for cyclo-olefin polymer grades.
For New Entrants and Emerging Players: UV-cured barrier deposition technology offers entry into foldable electronics without legacy solvent coating infrastructure. Target CDSCO qualification pathways in India where tightening blister-pack integrity standards exclude incumbent suppliers. Pursue electron-beam crosslinking partnerships with display stack integrators seeking hybrid coating architectures.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale converters lacking certification depth but possessing installed precision extrusion capacity. Five-to-ten-year viability hinges on REACH compliance positioning and direct-to-fab contract penetration. Watch for AEC-Q200 certification timeline compression as German and South Korean automakers accelerate EV power electronics roadmaps.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Production | Secures polypropylene homopolymer supply for EV capacitor films against Asian petrochemical concentration. |
| Direct-to-Fab Distribution Contracts | Bypasses regional distributors in Gyeonggi Province and Hefei, compressing channel margins for qualified suppliers. |
| UV-Cured Barrier Deposition Scale-Up | Replaces solvent-based coatings under EPA emission controls while enabling roll-to-roll atomic layer deposition hybridization. |
| CDSCO Qualification Investment | Opens pharmaceutical blister packaging access in India where tightening integrity standards reshape supplier eligibility. |
| Multi-Layer Coextrusion Talent Acquisition | Addresses process engineer scarcity for 200+ layer optical stacks, shortening commissioning timelines for new barrier film lines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged resin synthesis directors, precision extrusion plant managers, display stack procurement leads at panel fabs, pharmaceutical packaging converters, and capacitor film specification engineers. Secondary validation drew from customs and trade data, EPA emission filings, FDA material contact notification databases, ECHA REACH authorization registers, and SEC disclosures from integrated chemical producers. Bottom-up capacity modeling triangulated against top-down end-use demand estimates across semiconductor packaging, automotive power electronics, and pharmaceutical blister applications.
Segment-weighting applied film type, application, end-user industry, and thickness grade dimensions across the analysis window. CAGRs derived from elasticity-adjusted demand curves for each segment, calibrated against historical capacity utilization and announced extrusion line additions. Forecast inputs incorporated AEC-Q200 certification timeline assumptions, REACH substance restriction phase-out schedules, and display manufacturer procurement consolidation patterns.
The model holds under stable regulatory enforcement and continued semiconductor packaging film demand growth; deviation in EPA emission control stringency or REACH perfluorinated compound phase-out acceleration would shift capacity investment returns. A model refresh is warranted upon material change in automotive electrification targets or foldable display adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Halloysite Market
Specialty Materials
Nitrocellulose Market
Specialty Materials
Alginate Films Market
Specialty Materials
Asia-Pacific Green Sic Market
Specialty Materials
North America Microspheres Market
Specialty Materials
North America Solar Control Window Films Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
PCB Prepreg Material Market
Specialty Materials
Mica Sheet Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Carrageenan Film Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Sheath Materials Market
Specialty Materials
Global Cellulose Esters Market