
 Europe Ambulance Services Market | 2026-2036
Europe Ambulance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ambulance Services Market Insights
Modular fleet configurations—combining basic transport vans with interchangeable advanced life support modules—is rebalancing procurement economics for municipal buyers. Babcock International Group PLC leverages its defense-sector logistics expertise to anchor large-scale government contracts across the United Kingdom. Falck specializes in integrated fire-rescue-ambulance bundles that dominate Nordic municipal outsourcing. European Air Ambulance competes on cross-border aeromedical reach, sustaining premium positioning for inter-country patient transfers.
Ambulance services encompass pre-hospital emergency medical response, patient transport, and inter-facility transfer operations utilizing specially equipped ground vehicles, rotorcraft, and fixed-wing aircraft configured with life-support apparatus, patient monitoring systems, and communication links to receiving hospitals. These services function as the critical interface between incident scenes and definitive care, with response-time mandates and clinical outcome metrics defining operational performance. Emergency Medical Services generates the dominant revenue share given statutory obligations and population coverage requirements, while Air Ambulance Services captures disproportionate margin pools due to specialized crew certification and aircraft amortization structures. Non-Emergency Transport represents a maturing segment where price competition intensifies among regional operators serving dialysis and elective discharge circuits.
EMA's clinical trial coordination standards and the EU Green Deal's commercial vehicle emission thresholds shape fleet renewal timelines and equipment certification pathways across member states. REACH compliance for disinfectants and onboard medical consumables adds procurement complexity for operators managing multi-country vehicle pools. Stakeholders must monitor how CSRD disclosure requirements alter capital access for mid-sized regional ambulance fleets.
Market Dynamics
EU Green Deal emission mandates are compressing diesel fleet replacement cycles across municipal ambulance operators, forcing capital reallocation toward zero-emission vehicle platforms and charging infrastructure before full TCO parity is achieved.
Growth Catalysts
- EMA clinical trial coordination standards:These protocols expand specialized patient transport contracts for pharmaceutical logistics operators serving multi-site studies across member states.
- Spain's coastal medical tourism corridors:Private hospital clusters in Barcelona and Málaga are outsourcing dedicated ambulance fleets to secure international patient transfer accreditation.
- Modular ALS van configurations:Interchangeable life-support modules allow municipal buyers to scale emergency capacity without full vehicle replacement.
Market Restraints
- Lithium-ion battery supply concentration:European ambulance OEMs depend on Asian cell manufacturers for electric powertrains, exposing procurement to mineral price volatility.
- REACH compliance complexity:Disinfectant and onboard consumable certification requirements fragment procurement for operators managing multi-country vehicle pools.
- Specialized aeromedical crew scarcity:Fixed-wing and rotorcraft services face structural bottlenecks in ICU-trained flight physician certification pipelines.
Strategic Opportunities
- Poland's underpenetrated emergency networks:Regional hospital consolidation is creating first-mover openings for integrated ground-air ambulance operators.
- CSRD disclosure requirements:Sustainability reporting mandates are redirecting institutional capital toward fleet operators with verified electrification roadmaps.
- Telemedicine-ambulance convergence:Real-time specialist consultation during transport is opening subscription revenue streams for technology-enabled operators.
Industry Challenges
- Paramedic workforce attrition:Burnout and compensation gaps in France and Italy are degrading response-time performance in high-density urban corridors.
- Multi-jurisdiction licensing friction:Cross-border aeromedical crews must maintain separate certifications under ANSM, Swissmedic, and TGA equivalency frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ambulance Services Market |
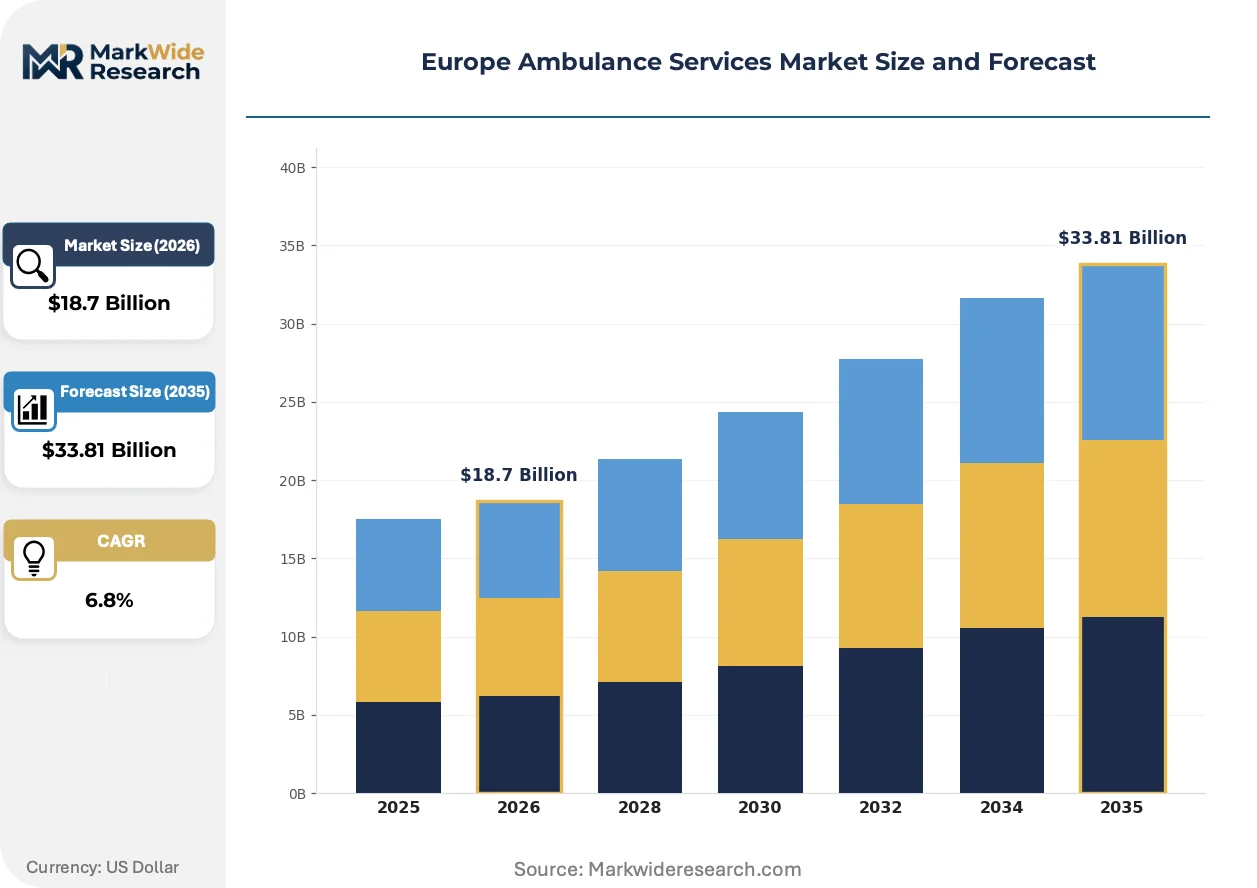
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency Medical Services, Non-Emergency Transport, Inter-Facility Transfers, Air Ambulance Services Vehicle Type: Ambulance Vans, Helicopters, Motorcycles, Mobile Intensive Care Units End User: Hospitals, Private Clinics, Government Agencies, Insurance Companies Technology: Telemedicine Integration, GPS Tracking Systems, Advanced Life Support Equipment, Patient Monitoring Systems |
| Companies Covered | BVG Group, Acadian Ambulance Service, Babcock International Group PLC, Air Methods, Global Medical Response, Falck, European Air Ambulance, Assistiamo Te, London Ambulance Service, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ambulance Services Market Trends and Innovations
Fleet transformation is accelerating through three interconnected vectors: powertrain electrification, regulatory disclosure mandates, and procurement model restructuring that shifts capital burden from municipalities to contracted operators.
Battery-electric ambulance platforms are electrifying last-mile emergency response in German and Dutch urban networks. Municipal buyers in Rotterdam and Hamburg are piloting 150kW fast-charging depot configurations to sustain sub-8-minute dispatch readiness. This transition is compressing diesel resale values and stranding mid-life vehicle assets before planned replacement cycles.
EU Green Deal commercial vehicle emission thresholds are forcing accelerated fleet renewal timelines. Operators must certify zero-emission procurement shares to maintain government contract eligibility under national transposition rules. Nordic municipal consortiums are consolidating purchasing power to secure volume pricing on electric chassis from specialized commercial vehicle OEMs.
Outcome-based contracting is displacing per-mile reimbursement models in United Kingdom NHS framework agreements. Integrated operators now assume clinical outcome accountability, with payment tied to stroke and cardiac intervention time targets. This restructuring concentrates contract awards among operators with dedicated dispatch optimization platforms and hospital network integration capabilities.
Europe Ambulance Services Market Segmentation
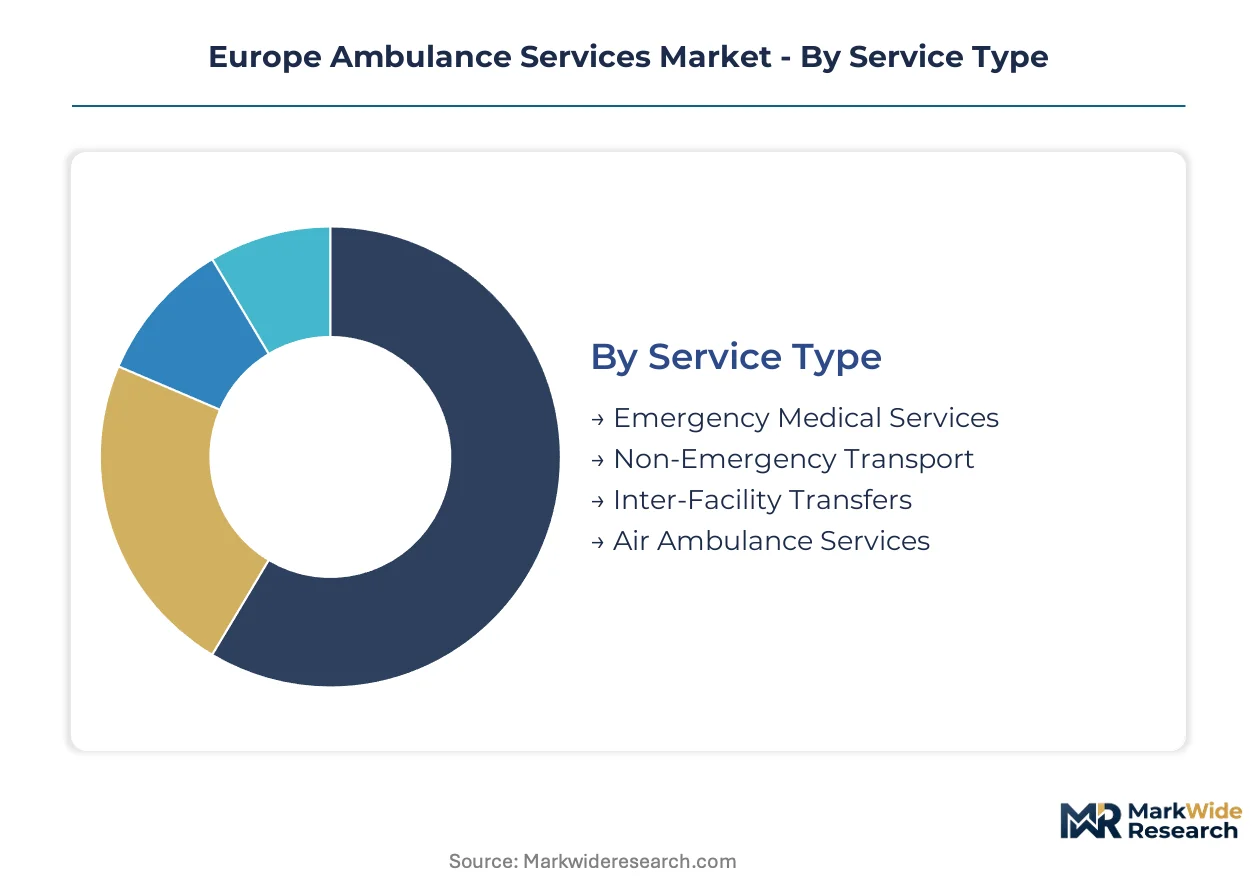
Segmentation in Europe's ambulance services market reveals how regulatory certification burdens, vehicle procurement economics, and care delivery models fragment competitive positioning across member states. Each dimension carries distinct margin profiles and capital intensity requirements that shape operator specialization strategies.
Service Type:
Emergency Medical Services demands full EMA clinical trial coordination compliance for pharmaceutical transport contracts, while Air Ambulance Services requires separate aeromedical crew certifications under national aviation medical frameworks.
- Emergency Medical Services:Statutorily mandated pre-hospital response with population coverage obligations driving municipal procurement. Demand concentrates in Germany's urban corridors where response-time mandates tighten clinical outcome accountability.
- Air Ambulance Services:Fixed-wing and rotorcraft operations requiring ICU-trained flight physicians and specialized aircraft amortization structures. Cross-border patient transfers between France, Germany, and Switzerland sustain premium positioning despite crew certification bottlenecks.
- Non-Emergency Transport:Maturing segment serving dialysis and elective discharge circuits with intensifying price competition among regional operators.
- Inter-Facility Transfers:Hospital network consolidation is expanding outsourced contracts for specialized patient movements between tertiary care centers.
Emergency Medical Services sits at the top of the volume ranking, with Air Ambulance Services climbing the fastest.
Vehicle Type:
Procurement economics diverge sharply between ground fleet standardization and aerial platform specialization, with EU Green Deal emission thresholds compressing diesel replacement cycles unevenly across categories.
- Ambulance Vans:Modular ALS configurations with interchangeable life-support modules allow municipal buyers to scale emergency capacity without full vehicle replacement. Nordic consortiums are consolidating purchasing power for electric chassis volume pricing.
- Mobile Intensive Care Units:High-acuity ground transport requiring advanced patient monitoring systems and dedicated crew certification. Spain's coastal medical tourism clusters in Barcelona and Málaga are outsourcing dedicated fleets to secure international patient transfer accreditation.
- Helicopters:Rotorcraft platforms for rapid response in terrain-constrained regions, facing structural bottlenecks in flight physician certification pipelines.
- Motorcycles:First-response units in dense urban networks where sub-8-minute dispatch mandates exceed conventional vehicle feasibility.
Ambulance Vans dominate procurement volumes, while Mobile Intensive Care Units are gaining share fastest among premium service tiers.
End User:
Contracting authority fragmentation across public health systems, private hospital clusters, and insurance reimbursement frameworks creates divergent procurement timelines and performance metrics.
- Hospitals:Tertiary care networks expanding outsourced ambulance contracts as emergency department consolidation accelerates across Germany, France, and Italy.
- Government Agencies:Municipal and regional authorities mandating zero-emission procurement shares under national EU Green Deal transposition rules.
- Private Clinics:Medical tourism destinations requiring dedicated fleet accreditation for international patient transfers.
- Insurance Companies:Outcome-based contracting pilots in United Kingdom NHS frameworks tying reimbursement to stroke and cardiac intervention time targets.
Government Agencies anchor the volume ranking, with Insurance Companies expanding most quickly through outcome-based reimbursement restructuring.
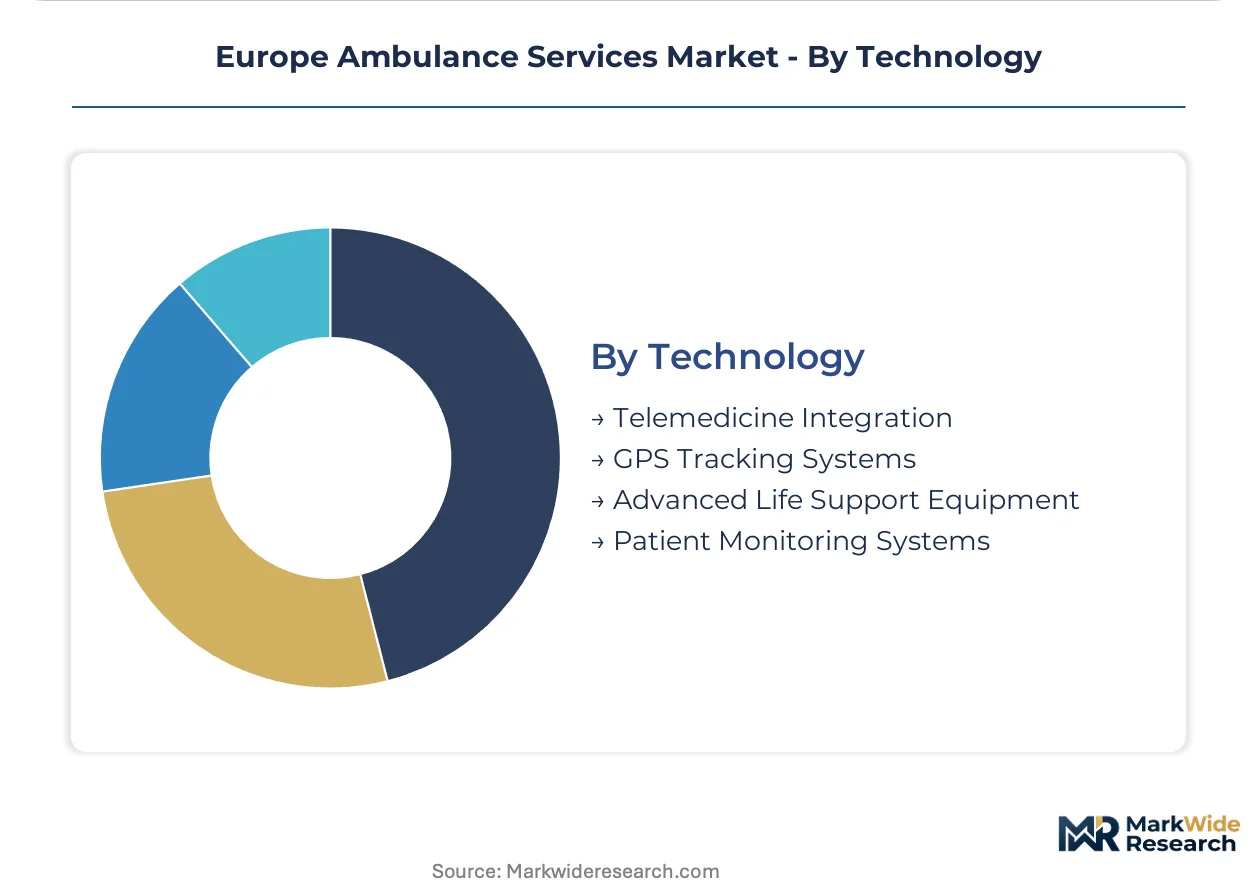
Technology:
Equipment certification pathways under REACH compliance for disinfectants and onboard consumables add procurement complexity for operators managing multi-country vehicle pools.
- Advanced Life Support Equipment:Defibrillators, ventilators, and medication delivery systems requiring CE marking and national medical device registration. Rotterdam and Hamburg are piloting 150kW fast-charging depot configurations to sustain dispatch readiness for electric ALS platforms.
- Telemedicine Integration:Real-time specialist consultation during transport opening subscription revenue streams for technology-enabled operators. CSRD disclosure requirements are redirecting institutional capital toward fleet operators with verified digital transformation roadmaps.
- Patient Monitoring Systems:Continuous vital sign transmission to receiving hospitals enabling pre-arrival intervention preparation.
- GPS Tracking Systems:Dispatch optimization platforms integrated with hospital network systems for outcome-based contract compliance.
Advanced Life Support Equipment holds the top volume position, with Telemedicine Integration showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern ambulance services trace their organized structure to military medical evacuation systems pioneered in Germany and France during the early twentieth century. These foundations established the tiered response protocols and vehicle specifications now standardized across European Union member states. Contemporary market development reflects divergent national health system architectures and regulatory implementation timelines.
Germany
Emergency hospital networks in North Rhine-Westphalia and Bavaria are expanding outsourced ambulance contracts as regional consolidation accelerates. The KBA enforces stringent vehicle certification standards under national EU Green Deal transposition rules, mandating zero-emission procurement shares for municipal contract eligibility. Hamburg's pilot 150kW fast-charging depot configurations sustain sub-8-minute dispatch readiness for electric ALS platforms.
United Kingdom
Outcome-based contracting pilots within NHS framework agreements tie reimbursement to stroke and cardiac intervention time targets. Babcock International Group PLC leverages defense-sector logistics expertise to anchor large-scale government contracts across England and Scotland. London's integrated dispatch optimization platforms concentrate contract awards among operators with dedicated hospital network integration capabilities.
France
ANSM maintains separate certification frameworks for cross-border aeromedical crews operating between France, Germany, and Switzerland. Paramedic workforce attrition in high-density urban corridors degrades response-time performance in Paris and Lyon. Île-de-France tertiary care networks are expanding outsourced contracts as emergency department consolidation accelerates.
Spain
Private hospital clusters in Barcelona and Málaga are outsourcing dedicated ambulance fleets to secure international patient transfer accreditation. Coastal medical tourism corridors generate concentrated demand for specialized transport serving dialysis and elective discharge circuits. Andalusia's regional health authorities are consolidating purchasing power for modular ALS van configurations.
Poland
Regional hospital consolidation creates first-mover openings for integrated ground-air ambulance operators in underpenetrated emergency networks. EMA clinical trial coordination standards expand specialized patient transport contracts for pharmaceutical logistics operators serving multi-site studies. Warsaw and Kraków municipal authorities are piloting telemedicine-ambulance convergence for real-time specialist consultation during transport.
Europe Ambulance Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service specialization tiers, with aeromedical operators capturing disproportionate returns against ground transport commoditization. The market exhibits moderate consolidation among integrated emergency services providers while fragmenting across regional non-emergency transport specialists. Three archetypes dominate: defense-logistics converters, integrated fire-rescue-ambulance bundlers, and cross-border aeromedical specialists. Competitive dynamics center on government contract anchoring and fleet electrification roadmaps that satisfy CSRD disclosure requirements for institutional capital access.
Within the integrated emergency services tier, Babcock International Group PLC and Falck occupy positions reflecting divergent national contracting traditions. Babcock exemplifies the defense-logistics conversion archetype through United Kingdom government contract anchoring. Falck represents Nordic municipal outsourcing specialization through integrated fire-rescue-ambulance bundling. European Air Ambulance sits within the cross-border aeromedical segment, sustaining premium positioning for inter-country patient transfers despite crew certification bottlenecks.
| Leading Market Players |
|---|
| BVG Group |
| Acadian Ambulance Service |
| Babcock International Group PLC |
| Air Methods |
| Global Medical Response |
| Falck |
| European Air Ambulance |
| Assistiamo Te |
| London Ambulance Service |
| Others |
Pricing and Supply Chain Analysis
Horizontal integration of municipal ambulance contracts across Nordic consortiums anchors procurement leverage for fleet operators, compressing supplier margins while elevating volume-scale pricing power for integrated service providers bidding on multi-year government frameworks.
Pricing Analysis
Outcome-based reimbursement structures tie municipal payments to stroke and cardiac intervention time targets, displacing per-mile transactional models across United Kingdom NHS frameworks. Price differentiation rests on clinical outcome accountability tiers and dedicated dispatch optimization platform integration, with government agencies exhibiting lowest sensitivity due to statutory coverage mandates while private clinics face acute pressure from medical tourism accreditation costs. Cost compression in non-emergency transport intensifies as regional operators compete on dialysis circuit contracts.
Supply Chain Analysis
Single-source vulnerability sits with Asian cell manufacturers supplying lithium-ion powertrains to European ambulance OEMs, exposing procurement to mineral price volatility and geopolitical disruption. Component sourcing draws from Germany for specialized chassis, South Korea for battery cells, and China for onboard monitoring electronics. Tariff exposure on medical device imports from non-EU jurisdictions compounds REACH compliance costs for multi-country fleet operators. Distribution runs through municipal procurement consortia and hospital network direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's ambulance services market functions as a stable compounder, with EU Green Deal fleet electrification mandates driving predictable capital redeployment cycles across municipal operators.
For Market Incumbents: Anchor defense-sector logistics capabilities to secure large-scale government contract renewals as outcome-based accountability tightens. Invest in captive charging infrastructure to preempt municipal zero-emission procurement thresholds. Consolidate dispatch optimization platforms to maintain stroke and cardiac intervention time target compliance against emerging technology-enabled entrants. For New Entrants and Emerging Players: Telemedicine-ambulance convergence platforms offer a technology-first wedge into Poland's underpenetrated emergency networks and Spain's coastal medical tourism corridors. Target first-mover positioning in Warsaw and Kraków municipal pilot programs. Pursue subscription revenue models for real-time specialist consultation during transport rather than competing on commoditized non-emergency dialysis circuits. For Investors and Strategic Acquirers: Roll-up economics work for integrated ground-air ambulance operators because regional hospital consolidation in Poland and Italy fragments competitive landscapes into acquirable mid-scale assets. Five-to-ten year viability hinges on verified electrification roadmaps satisfying CSRD disclosure requirements. Monitor lithium-ion supply contract renegotiation cycles as inflection indicators for fleet transformation capital intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Roadmap | CSRD disclosure mandates redirect institutional capital toward verified zero-emission procurement plans. |
| Modular ALS Platform Standardization | Interchangeable life-support modules allow municipal buyers to scale emergency capacity without full vehicle replacement. |
| Telemedicine Integration Partnership | Real-time specialist consultation during transport opens subscription revenue streams for technology-enabled operators. |
| Cross-Border Aeromedical Certification | ANSM and Swissmedic equivalency frameworks sustain premium positioning for inter-country patient transfers. |
| Outcome-Based Contracting Capability | NHS framework agreements tie reimbursement to stroke and cardiac intervention time targets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal procurement officers, ambulance fleet managers, aeromedical crew certification directors, and hospital network integration specialists with secondary validation through KBA vehicle certification records, EMA clinical trial coordination protocols, NHS framework agreement disclosures, and EU Green Deal national transposition filings. Bottom-up service demand modeling and top-down health expenditure allocation triangulated market sizing.
Segment-weighting approaches distributed value across emergency medical services, air ambulance services, non-emergency transport, and inter-facility transfers, with vehicle type stratification between ambulance vans, mobile intensive care units, helicopters, and motorcycles. Technology segmentation captured advanced life support equipment, telemedicine integration, patient monitoring systems, and GPS tracking platforms. CAGRs derived from contracted fleet renewal timelines, electrification mandate phase-in schedules, and municipal outsourcing penetration curves across the analysis window.
The model holds under stable EU regulatory implementation and lithium-ion supply continuity; deviation in mineral price volatility or REACH compliance enforcement would shift fleet transformation economics. Forecasts reflect documented assumptions on municipal contract renewal rates and zero-emission procurement share thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
Global Ambulance Stretchers Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
Adrenal Crisis Management Market
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
Cardiopulmonary Resuscitation Market
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
Global Emergency Medical Apps Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
US Urgent Care Centers Market
Emergency Medical Services
Europe Air Ambulance Services Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
First Aid Market