
 Global Mechanical Ventilators Market | 2026-2036
Global Mechanical Ventilators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mechanical Ventilators Market Foresight
Adaptive servo-ventilation and closed-loop oxygen control is tilting the engineering stack toward algorithm-driven respiratory support. Medtronic plc leverages its integrated critical care portfolio to sustain installed-base loyalty across North American health systems. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. anchors its competitive stance on manufacturing scale and cost-optimized platform designs for emerging markets.
Mechanical ventilators are electromechanical life-support systems that generate controlled breathing patterns through positive pressure delivery, typically operating across tidal volumes of 50-2000 mL and respiratory rates of 1-150 breaths per minute to sustain gas exchange in patients with compromised pulmonary function. Invasive ventilators dominate acute care revenue pools where prolonged intubation drives premium pricing, while portable ventilators represent the fastest-expanding application as home healthcare providers seek to decouple respiratory support from hospital infrastructure. Dual-mode technology commands outsized R&D investment because it reconciles patient comfort with clinical precision across pressure and volume targets.
FDA premarket clearance under 21 CFR 868.5895 and the EU Medical Device Regulation (MDR) establish divergent compliance burdens that fragment product development roadmaps for manufacturers serving both jurisdictions. The WHO's emergency use listing pathway and ISO 80601-2-80 standards for home healthcare ventilators further stratify market access requirements across clinical and non-clinical settings. Stakeholders must weigh regulatory capital intensity against the margin compression risk of commoditized acute-care platforms.
Market Dynamics
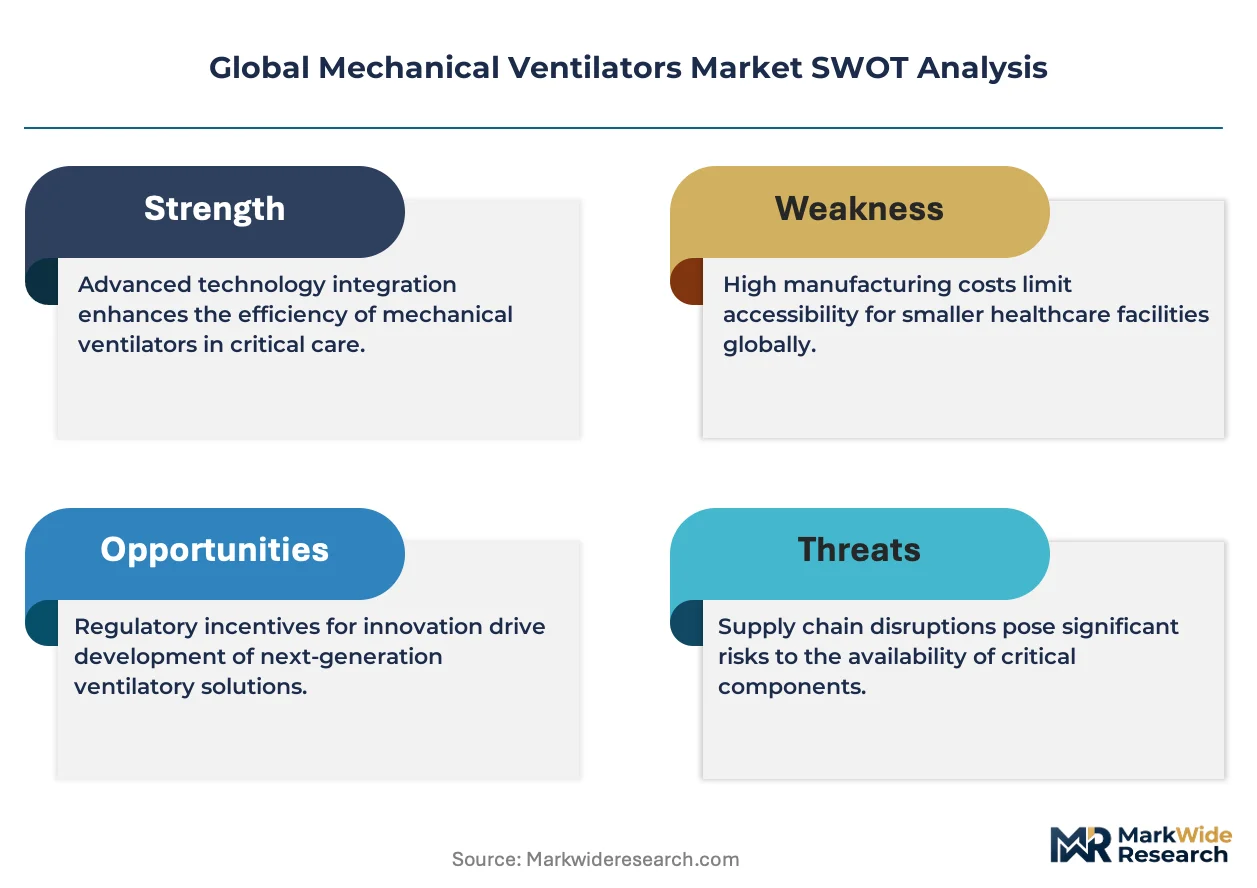
Algorithm-driven respiratory support is compressing hardware differentiation and forcing manufacturers to compete on software ecosystems and clinical data integration rather than electromechanical specifications alone.
Growth Catalysts
- ICU Infrastructure Expansion:Brazil's federal critical care investment programs are accelerating procurement of invasive ventilators for tertiary facilities. State-level health secretariats are standardizing equipment specifications to enable bulk purchasing.
- Home Healthcare Decoupling:Portable ventilator demand from long-term care providers is severing respiratory support from hospital infrastructure. Medicare reimbursement shifts in the United States are validating non-acute settings.
- ISO 80601-2-80 Harmonization:The home healthcare ventilator standard is reducing technical barriers for multi-setting device platforms. Manufacturers are converging development roadmaps around this framework.
Market Restraints
- Semiconductor Input Volatility:MEMS pressure sensors and flow controllers face allocation constraints from automotive and consumer electronics demand. Foundry capacity concentration in Taiwan creates supply vulnerability.
- EU MDR Compliance Burden:The Medical Device Regulation's clinical evidence requirements and notified body bottlenecks are extending certification timelines. Small and mid-tier manufacturers face capital intensity barriers.
- Non-Invasive Ventilation Substitution:High-flow nasal cannula systems and CPAP devices are capturing respiratory support cases previously requiring mechanical ventilation. Pulmonologists are revising intubation thresholds.
Strategic Opportunities
- India Tertiary Sector Penetration:Ayushman Bharat health scheme expansion is broadening critical care access beyond metropolitan centers. District hospital upgrades represent underpenetrated procurement volume.
- Closed-Loop Oxygen Convergence:Integration of pulse oximetry feedback with ventilator control algorithms is enabling automated FiO2 titration. This technology pairing reduces nursing workload and hypoxia events.
- Direct-to-Provider Distribution:Group purchasing organization bypass strategies are emerging through manufacturer-owned service networks. Hospital system consolidation is enabling account-based sales models.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Ventilator-specific clinical engineering expertise is concentrated among aging specialists. Training pipeline gaps in respiratory therapy and device maintenance are extending service response times.
- Legacy Health Record Integration:Proprietary data protocols from established EMR vendors are complicating ventilator-to-cloud connectivity. Interoperability certification delays are freezing procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mechanical Ventilators Market |
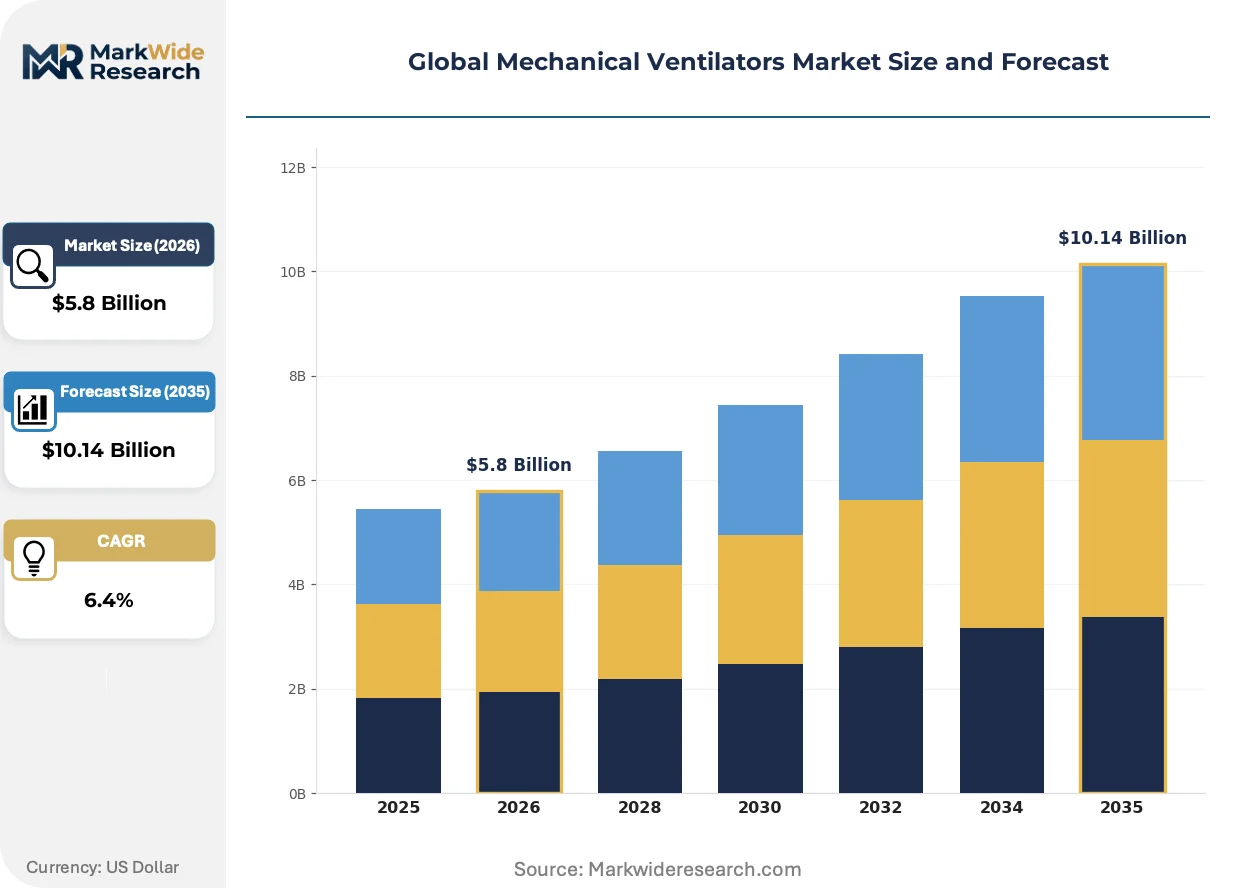
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Ventilators, Non-Invasive Ventilators, Portable Ventilators, Emergency Ventilators Technology: Pressure Controlled, Volume Controlled, Dual Mode, High-Frequency Oscillatory, Non-Invasive Positive Pressure Application: Adult Respiratory Support, Neonatal Care, Pediatric Therapy, Surgery Assistance, Home Care End User: Hospitals, Ambulatory Surgical Centers, Home Healthcare Providers, Long-Term Care Facilities, Emergency Medical Services |
| Companies Covered | Medtronic plc, Getinge AB, Koninklijke Philips N.V., Drägerwerk AG & Co. KGaA, GE Healthcare, Hamilton Medical, ResMed Inc., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Smiths Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mechanical Ventilators Market Shifts & Advancements
Digital twin architectures and edge computing are redefining how respiratory support systems generate, process, and act upon patient data in real time.
Digital twin technology is virtualizing patient-specific respiratory modeling by creating dynamic simulations of lung mechanics and gas exchange. Academic medical centers in Germany and the Netherlands are piloting these systems for predictive weaning protocols. This virtualization is compressing the clinical trial burden for new ventilation modes by enabling in-silico validation.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up and periodic safety update reports. Manufacturers serving European markets are restructuring quality management systems to capture real-world performance data. Class II respiratory devices face heightened notified body scrutiny, pushing development timelines toward conservative planning assumptions.
Hospital system procurement consolidation is concentrating buying power among integrated delivery networks and national health services. Single-source contracting for ventilator fleets is displacing multi-vendor environments in the United Kingdom's NHS trusts and large United States health systems. This concentration is most visible in academic medical centers where standardization reduces training complexity and spare parts inventory.
Global Mechanical Ventilators Market Segmentation
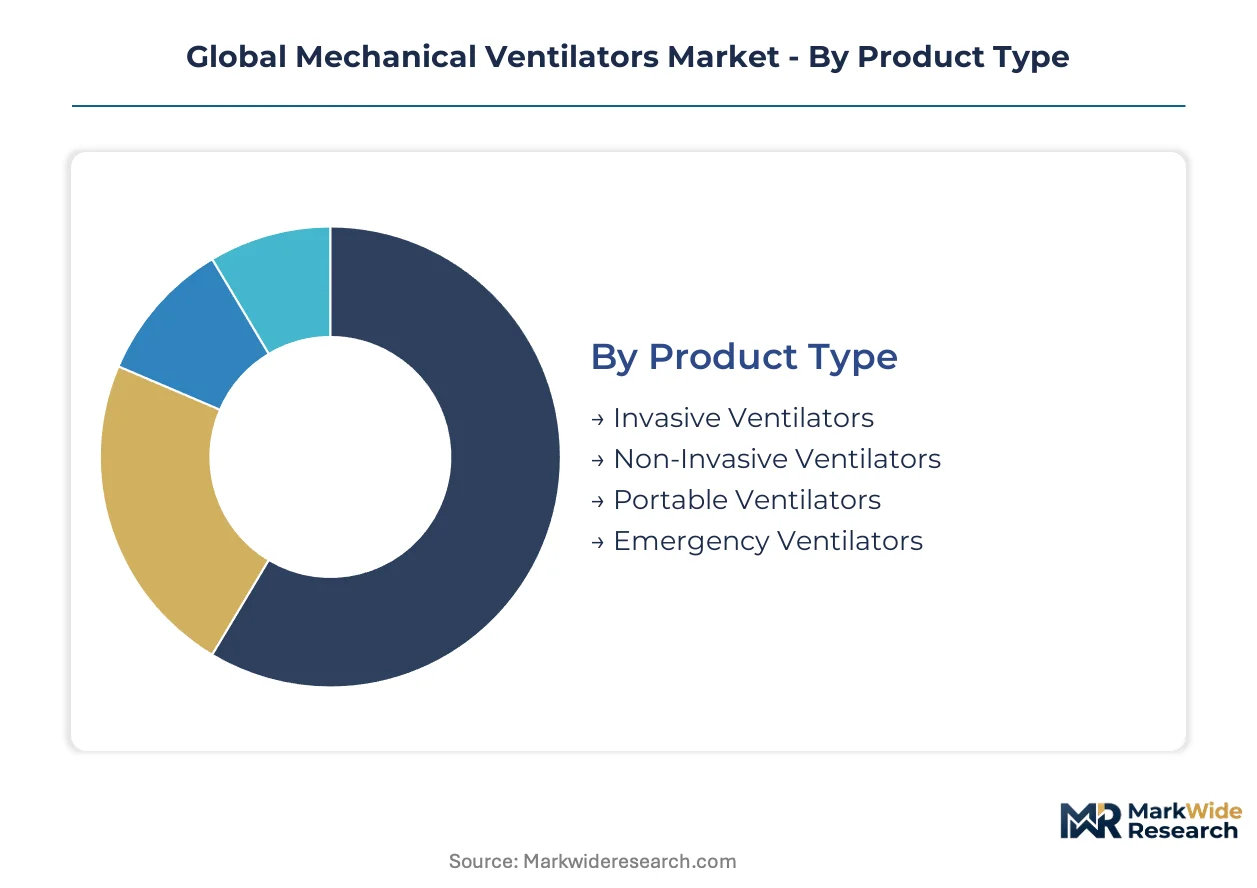
Mechanical ventilator procurement patterns diverge sharply across clinical settings, with replacement cycles spanning 7-10 years in tertiary hospitals versus 3-5 years in transport and emergency applications. Understanding these temporal rhythms helps manufacturers align service contracts and upgrade pathways with actual capital deployment.
Product Type:
Replacement velocity separates acute-care platforms with decade-long depreciation schedules from portable units subject to field wear and technology obsolescence.
- Invasive Ventilators:These systems deliver positive pressure through endotracheal or tracheostomy tubes, supporting tidal volumes from 50-2000 mL with precision waveform control. Demand concentrates in Brazil's expanding federal ICU infrastructure, where state-level bulk purchasing standardizes specifications across tertiary facilities.
- Portable Ventilators:Battery-powered units weighing under 5 kg enable inter-hospital transport and home-based respiratory support. Medicare reimbursement validation in the United States is accelerating procurement from long-term care providers seeking to decouple respiratory support from hospital infrastructure.
- Non-Invasive Ventilators:Mask-delivered pressure support systems for conscious patients with intact airway reflexes.
- Emergency Ventilators:Simplified pneumatic or electromechanical designs for field deployment and mass casualty scenarios.
Invasive ventilators dominate installed base. Portable ventilators are where expansion concentrates most steeply.
Technology:
Engineering complexity stratifies pricing tiers, with algorithm-intensive platforms commanding premium positioning against commoditized pneumatic designs.
- Dual Mode:These systems automatically alternate between pressure and volume targeting based on patient compliance and lung mechanics. India's Ayushman Bharat district hospital upgrades are driving procurement of these flexible platforms where specialist coverage is thin.
- Pressure Controlled:Constant inspiratory pressure delivery with variable tidal volume based on lung compliance.
- Volume Controlled:Fixed tidal volume delivery with variable pressure based on airway resistance and compliance.
- High-Frequency Oscillatory:Ultra-rapid small-volume ventilation for neonatal and severe ARDS applications.
- Non-Invasive Positive Pressure:Bi-level pressure support algorithms optimized for mask ventilation interfaces.
Volume controlled retains the largest legacy footprint. Dual mode is gaining share fastest among new installations.
Application:
Patient physiology dictates specification requirements, with neonatal and adult segments demanding incompatible flow ranges and monitoring sensitivity.
- Adult Respiratory Support:Full-featured platforms supporting 50-2000 mL tidal volumes with advanced weaning protocols. Academic medical centers in Germany and the Netherlands are piloting digital twin integration for predictive liberation from mechanical support.
- Home Care:Simplified interfaces and remote monitoring capabilities for non-acute settings. United States Medicare reimbursement shifts are validating this segment's expansion beyond traditional hospital boundaries.
- Neonatal Care:Precision micro-volume delivery and thermal management for patients under 10 kg.
- Pediatric Therapy:Intermediate flow ranges and alarm systems adapted for developing physiology.
- Surgery Assistance:Anesthesia-integrated ventilation with rapid emergence protocols.
Adult respiratory support commands the revenue base. Home care represents the steepest expansion trajectory.
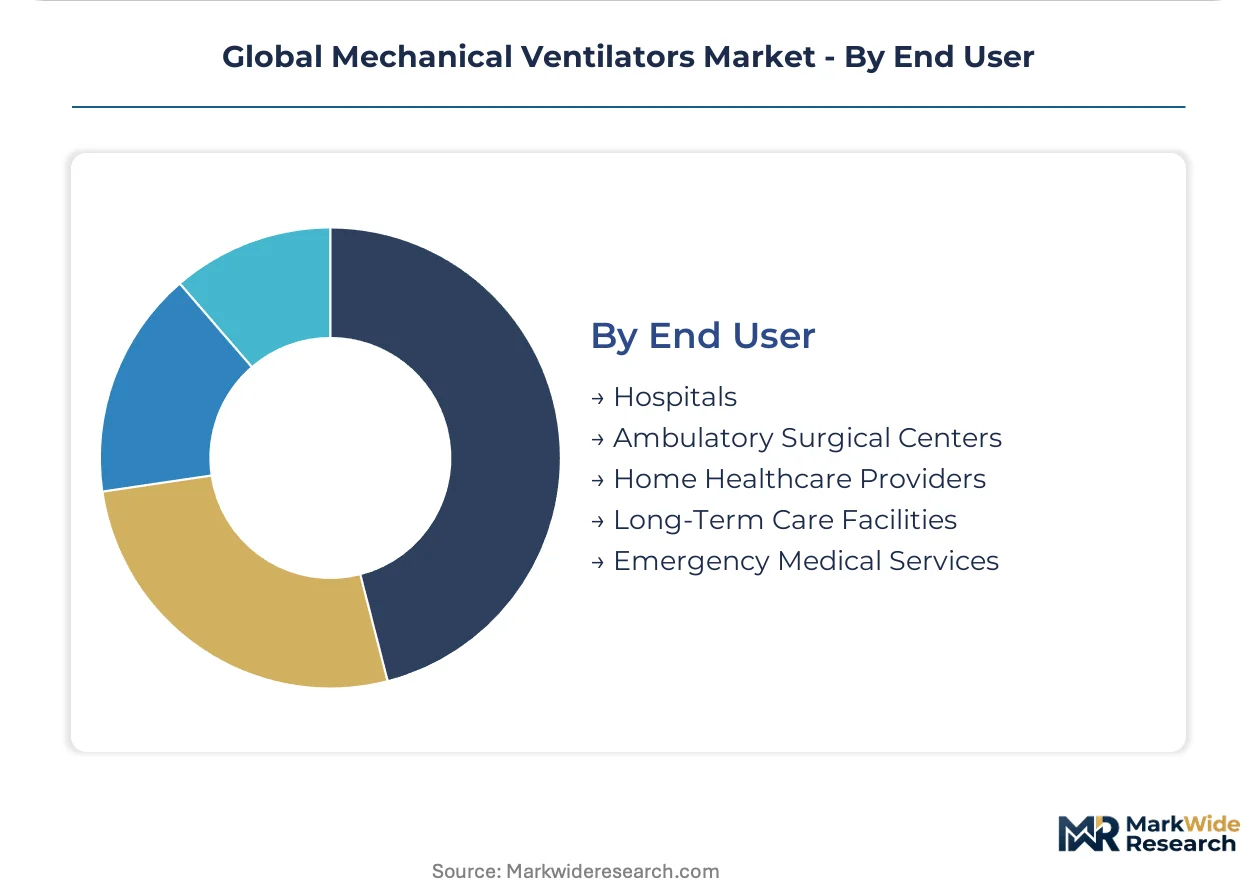
End User:
Capital intensity and clinical autonomy vary dramatically across settings, from consolidated health system procurement to fragmented home healthcare purchasing.
- Hospitals:Integrated delivery networks in the United Kingdom's NHS trusts and large United States health systems are consolidating to single-source ventilator fleets. Standardization reduces training complexity and spare parts inventory across multi-facility deployments.
- Home Healthcare Providers:Distributed service organizations with limited biomedical engineering capacity. ISO 80601-2-80 harmonization is reducing technical barriers for multi-setting device platforms serving this channel.
- Ambulatory Surgical Centers:Short-procedure facilities with anesthesia-integrated ventilation needs.
- Long-Term Care Facilities:Extended-stay environments with weaning and chronic support requirements.
- Emergency Medical Services:Pre-hospital transport with ruggedized, battery-dependent specifications.
Hospitals anchor the installed base. Home healthcare providers are where procurement volume is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision ventilation platforms to tertiary hospitals across Brazil and India, establishing the primary trade-flow corridor for high-acuity respiratory equipment.
United States
Medicare reimbursement shifts validate home healthcare ventilator procurement outside hospital infrastructure. FDA premarket clearance under 21 CFR 868.5895 shapes product entry timelines for Class II respiratory devices. Academic medical centers in Boston and the Research Triangle pilot digital twin integration for predictive weaning protocols.
Germany
EU MDR clinical evidence requirements extend certification timelines for multi-jurisdiction manufacturers. The Medical Device Regulation's post-market surveillance mandates systematic safety update reports. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia concentrate notified body expertise and testing infrastructure.
Brazil
Federal critical care investment programs accelerate invasive ventilator procurement for tertiary facilities. ANVISA registration requirements govern import authorization for respiratory devices. State-level health secretariats in São Paulo and Minas Gerais standardize equipment specifications to enable bulk purchasing.
India
Ayushman Bharat health scheme expansion broadens critical care access beyond metropolitan centers. CDSCO medical device rules classify ventilators under regulated import categories. District hospital upgrades in Maharashtra and Karnataka represent underpenetrated procurement volume for dual-mode platforms.
China
NMPA medical device registration drives compliance timelines for domestic and imported respiratory equipment. Manufacturing scale advantages in Shenzhen and Guangzhou anchor cost-optimized platform designs for emerging market export. GB standards harmonization with ISO frameworks reduces technical barriers for multi-setting devices.
Global Mechanical Ventilators Market Competitive Landscape
On the supply side, the industry is consolidating around integrated critical care portfolios and manufacturing scale advantages. Three archetypes dominate: diversified medtech conglomerates with installed-base loyalty programs, specialized respiratory device manufacturers with algorithm-intensive platforms, and emerging market fabricators with cost-optimized designs. Competitive moves concentrate on strategic partnerships for software ecosystem integration and geographic expansion through direct-to-provider distribution networks.
Among diversified medtech conglomerates, Medtronic plc and Koninklijke Philips N.V. occupy positions defined by integrated hospital system relationships and broad critical care portfolios. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. exemplifies the scale-driven archetype, leveraging manufacturing concentration in southern China to serve price-sensitive procurement channels across emerging markets.
| Leading Market Players |
|---|
| Medtronic plc |
| Getinge AB |
| Koninklijke Philips N.V. |
| Drägerwerk AG & Co. KGaA |
| GE Healthcare |
| Hamilton Medical |
| ResMed Inc. |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Smiths Group plc |
| Others |
Supply & Pricing Matrix
Shenzhen's manufacturing cluster concentration in southern China anchors cost-optimized platform production for emerging market export, compressing margin structures for premium European manufacturers competing on algorithmic differentiation rather than scale economics.
Pricing Analysis
Next-generation dual-mode ventilators command 40-60% premiums over volume-controlled legacy platforms, while prior-generation pneumatic designs face accelerating price erosion in bulk procurement channels. Three-tier pricing structure across premium algorithm-intensive, standard multi-mode, and economy basic ventilation levels stratifies the acute-care segment, with FDA 510(k) clearance tier and ISO 80601-2-80 certification status serving as primary differentiation drivers. Pricing pressure stems from high-flow nasal cannula systems capturing respiratory support cases previously requiring mechanical intubation. Home healthcare providers exhibit highest price sensitivity due to Medicare reimbursement constraints, while academic medical centers prioritize clinical performance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for MEMS pressure sensors and precision flow controllers. Manufacturing capacity concentrates in China, Germany, and the United States, with semiconductor foundry output in Taiwan feeding critical sensor components. Raw material dependencies span medical-grade aluminum alloys, silicone elastomers for patient circuits, and specialized polymers for disposable breathing sets. Single-source vulnerability in Taiwan-based foundry capacity for pressure transducers creates allocation bottlenecks when automotive and consumer electronics demand surges. Distribution runs through group purchasing organizations and manufacturer-owned service networks, with direct-to-hospital contracting displacing traditional distributor channels in consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical ventilator incumbents must defend against high-flow nasal cannula and CPAP substitution eroding acute-care case volumes, while algorithm-driven respiratory support commoditizes hardware differentiation across price tiers.
For Market Incumbents: Pre-empt software ecosystem lock-in by integrating closed-loop oxygen control with proprietary clinical data platforms before open-architecture standards consolidate. Deepen backward integration into MEMS sensor supply through captive Taiwan foundry partnerships or alternative German precision engineering sources. Defend installed-base loyalty through predictive maintenance contracts tied to digital twin remote monitoring capabilities. For New Entrants and Emerging Players: Build out ISO 80601-2-80 certified multi-setting platforms targeting India's Ayushman Bharat district hospital upgrades, where specialist coverage scarcity favors flexible dual-mode specifications over premium single-purpose designs. Penetrate Brazil's state-level bulk purchasing programs through ANVISA-registered cost-optimized invasive ventilators. Pursue direct-to-provider distribution bypassing GPO intermediaries in consolidated United States health systems. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm-intensive platform specialists with FDA 510(k) predicate libraries and EU MDR technical documentation ready for notified body submission. Long-term viability hinges on software recurring revenue attachment rates exceeding hardware depreciation cycles. Target acquisition archetype: respiratory device manufacturers with installed base in academic medical centers and pending digital twin validation studies. Monitor FDA premarket notification backlog duration as inflection indicator for new entrant window timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Submission | Accelerates product entry timelines under 21 CFR 868.5895 for Class II respiratory devices. |
| CE Marking Pathway Completion | Enables EU MDR compliance for algorithm-driven platforms targeting German hospital procurement. |
| Hospital System Partnership | Secures single-source fleet standardization contracts with United Kingdom NHS trusts. |
| Software Companion Development | Integrates closed-loop oxygen control with pulse oximetry feedback for automated FiO2 titration. |
| Reimbursement Strategy | Validates home healthcare ventilator procurement through Medicare coverage determination shifts. |
Research Methodology
A standing panel of critical care physicians, hospital biomedical engineers, GPO contracts managers, and respiratory therapy directors provided ongoing calibration across primary fieldwork and secondary source validation. Intensive care unit procurement committees at tertiary facilities in São Paulo, Mumbai, and Boston contributed operational data on replacement cycles and specification requirements. Secondary sources encompassed FDA 510(k) premarket notification databases, ANVISA import registration records, EU MDR notified body technical documentation, and CMS Medicare reimbursement coding updates. Bottom-up unit economics triangulated against top-down health system capital expenditure surveys.
Scenario-bracketing around semiconductor supply disruption severity and EU MDR certification timeline compression framed sensitivity analysis across the projection horizon. Segmentation modeling spanned product type, technology generation, patient application, and end-user setting dimensions. CAGRs derived from installed base turnover velocity and penetration rate assumptions in underpenetrated district hospital tiers. Industry-specific inputs incorporated WHO emergency use listing pathway adoption and ISO 80601-2-80 harmonization progress for home healthcare platforms.
Practitioners should monitor FDA premarket notification backlog duration, Taiwan foundry allocation announcements, and high-flow nasal cannula clinical guideline revisions for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Global Smart Contact Lenses Market
Medical Devices
Enteral Stents Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Global Centesis Catheters Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
Global Vagus Nerve Stimulation Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Global Angiography Catheters Market