
 Kidney Transplant Medicine Market | 2026-2036
Kidney Transplant Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Kidney Transplant Medicine Market Insights
Hospital-based transplant centers are unwinding their historical reliance on small independent dialysis clinics for post-surgical pharmaceutical procurement. Astellas Pharma Inc. anchors the calcineurin inhibitor segment through its entrenched tacrolimus franchise. Novartis AG competes via mTOR inhibitor specialization, while Bristol-Myers Squibb Company extends its position in co-stimulation blockade with belatacept.
Kidney transplant medicine encompasses pharmaceutical agents and diagnostic tools designed to prevent allograft rejection, manage post-operative infections, and preserve renal function following transplantation. These products operate through precise immunomodulatory mechanisms, with calcineurin inhibitors requiring therapeutic drug monitoring via LC-MS/MS assays to maintain narrow 5-15 ng/mL trough windows. Immunosuppressants command the dominant value pool due to lifelong therapy requirements, while biologicals represent the fastest-expanding category as monoclonal antibodies displace chronic corticosteroid exposure. Sustained-release delivery modes are gaining share as adherence economics reshape payer reimbursement calculations.
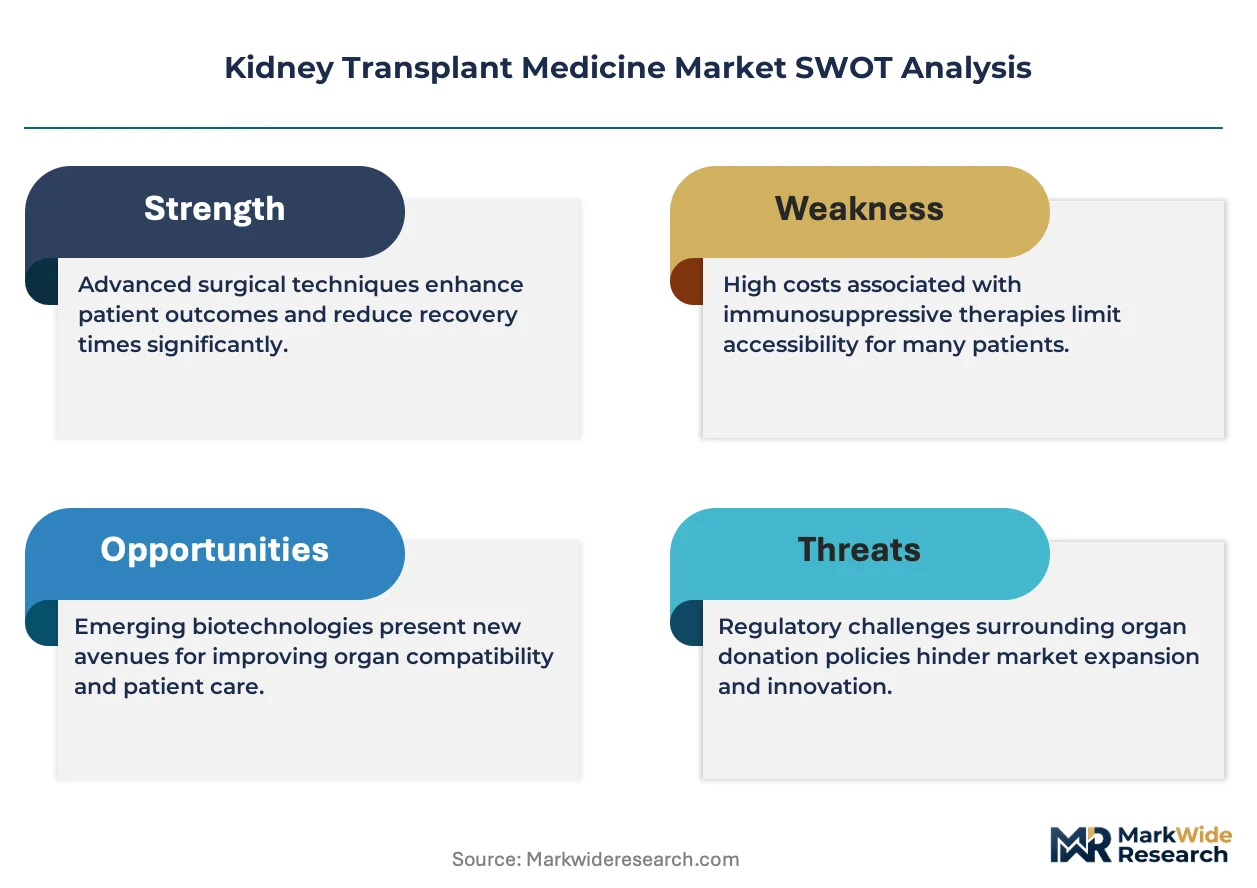
The FDA, EMA, and WHO set divergent bioequivalence thresholds for narrow-therapeutic-index immunosuppressants, fragmenting generic substitution rules across jurisdictions. REACH and the EU MDR impose escalating purity and traceability mandates on biological immunosuppressant manufacturing, raising compliance costs for plasma-derived agents. Stakeholders must monitor evolving payer policies on therapeutic drug monitoring reimbursement, as value-based contracts tie immunosuppressant coverage to graft survival metrics rather than prescription volume alone.
Market Dynamics
Hospital-based transplant centers are consolidating pharmaceutical procurement under centralized pharmacy and therapeutics committees, eroding the autonomy of individual nephrologists in immunosuppressant selection. This shift concentrates purchasing power and tightens adherence to institutional formularies.
Growth Catalysts
- Medicare Coverage Extension:The removal of the 36-month cap on immunosuppressive drug coverage in the United States eliminates cost barriers that previously drove graft loss among non-adherent patients.
- Therapeutic Drug Monitoring:LC-MS/MS assay standardization is expanding across transplant centers, enabling precision dosing that reduces rejection episodes and hospital readmissions.
- Living-Donor Program Expansion:Preemptive transplantation protocols are multiplying across academic medical centers, shortening wait times and expanding the addressable patient pool for maintenance immunosuppression.
Market Restraints
- Narrow-Therapeutic-Index Complexity:Tacrolimus and cyclosporine require trough level maintenance within 5-15 ng/mL windows, creating liability exposure for generic substitution and therapeutic substitution programs.
- Biological Manufacturing Concentration:Plasma-derived immunosuppressant production clusters among a limited set of fractionation facilities, concentrating supply risk for polyclonal antibody products.
- REACH Compliance Escalation:The European Union's escalating purity and traceability mandates for biological manufacturing raise fixed costs for market entry and sustained operations.
Strategic Opportunities
- Sustained-Release Formulations:Once-daily tacrolimus extended-release tablets are capturing share from immediate-release versions as adherence economics reshape payer reimbursement calculations.
- Value-Based Contracting:Payers in the United States are piloting contracts that tie immunosuppressant coverage to graft survival metrics rather than prescription volume alone.
- Monoclonal Antibody Expansion:IL-2 receptor antagonists and co-stimulation blockade agents are penetrating steroid-minimization protocols, expanding the biologicals category.
Industry Challenges
- Therapeutic Drug Monitoring Reimbursement:Payer policies on LC-MS/MS assay coverage remain inconsistent across Medicare Advantage plans and commercial insurers, creating revenue uncertainty for hospital laboratories.
- Generic Bioequivalence Standards:The FDA's tightened bioequivalence requirements for narrow-therapeutic-index drugs are extending ANDA review timelines and complicating formulary management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kidney Transplant Medicine Market |
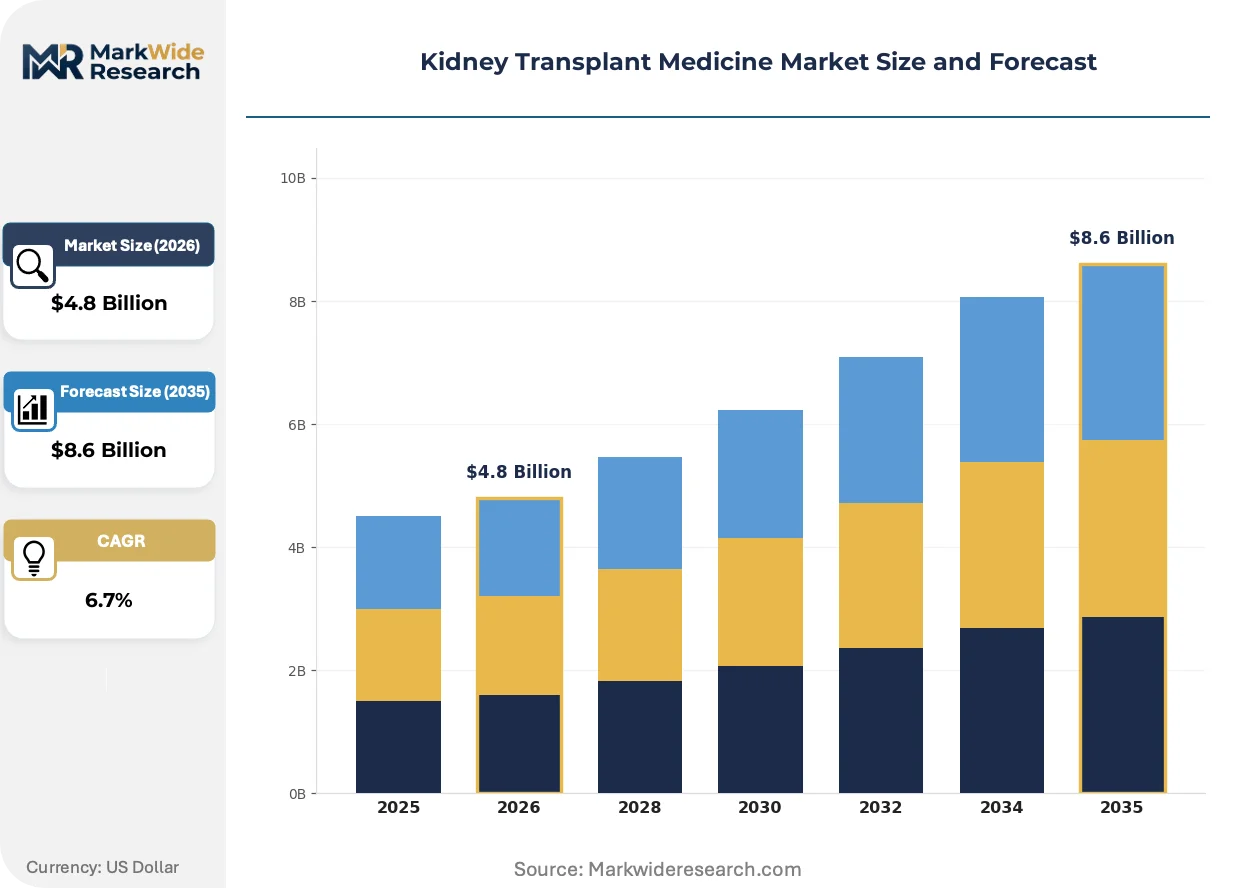
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Anti-viral Agents, Biologicals, Diagnostics Indication: Prevent Rejection, Post-transplant Infection, Renal Dysfunction, Graft Failure Delivery Mode: Oral Administration, Injectable, Intravenous, Sustained Release End User: Hospitals, Clinics, Home Healthcare, Specialty Pharmacies |
| Companies Covered | Astellas Pharma Inc., Novartis AG, Sanofi, Bristol-Myers Squibb Company, GSK plc, AbbVie Inc., Pfizer Inc., Roche, Veloxis Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kidney Transplant Medicine Market Trends and Innovations
Immunosuppression protocols are pivoting from chronic corticosteroid exposure toward targeted biological agents, reshaping both clinical practice and pharmaceutical procurement patterns across transplant centers.
Monoclonal antibodies targeting the IL-2 receptor and co-stimulation pathways are supplanting long-term corticosteroid maintenance in steroid-minimization protocols. Academic transplant centers in the United States and Germany are adopting these regimens at accelerating pace. The shift is compressing the chronic corticosteroid market while expanding biologicals manufacturing capacity requirements.
The FDA's tightened bioequivalence standards for narrow-therapeutic-index immunosuppressants are extending generic substitution review timelines. Hospital formularies are responding by narrowing approved generic tacrolimus suppliers and requiring therapeutic drug monitoring confirmation post-switch. The calcineurin inhibitor segment bears the greatest compliance burden from this regulatory recalibration.
Post-surgical pharmaceutical procurement is migrating from nephrology clinic autonomy toward centralized pharmacy and therapeutics committee oversight. Transplant centers are replacing individual physician preference with institutional formularies and restricted drug lists. This concentration is most visible in United States hospital systems with multiple transplant sites seeking procurement economies.
Kidney Transplant Medicine Market Segmentation
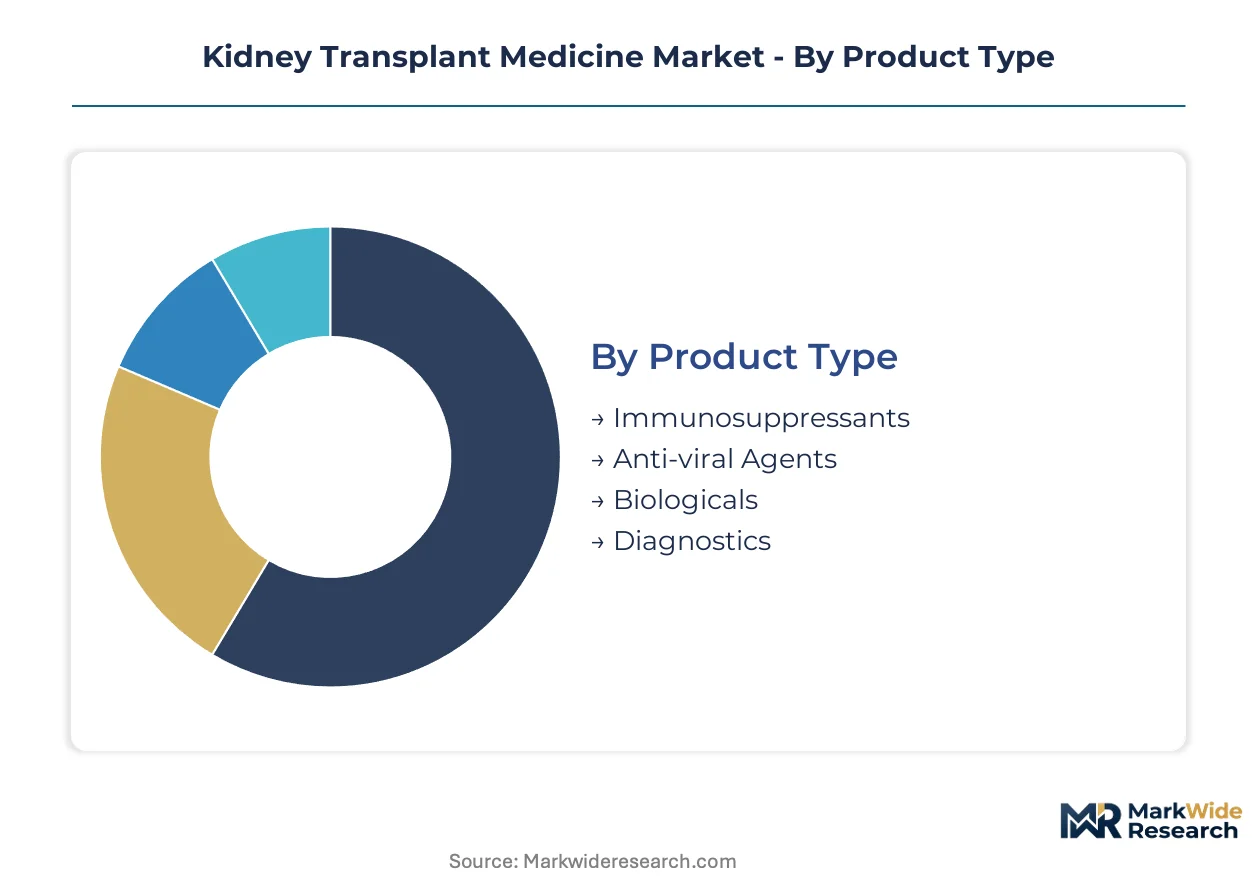
Kidney transplant medicine segmentation reflects divergent regulatory pathways across product categories. FDA bioequivalence standards for narrow-therapeutic-index drugs reshape procurement decisions differently than EMA MDR requirements for biological manufacturing.
Product Type:
FDA and EMA impose distinct purity thresholds on plasma-derived versus chemically synthesized agents, fragmenting compliance architectures.
- Immunosuppressants:Calcineurin inhibitors and antiproliferative agents constitute the foundational pharmaceutical backbone. Demand concentrates in United States hospital systems where Medicare's coverage extension eliminated the 36-month cap, though narrow-therapeutic-index complexity creates liability exposure for generic substitution programs.
- Biologicals:Monoclonal antibodies and polyclonal antibody preparations target specific immune pathways with precision. Academic medical centers in Germany and the United States are adopting IL-2 receptor antagonists and co-stimulation blockade agents at accelerating pace as steroid-minimization protocols expand.
- Anti-viral Agents:Prophylactic and therapeutic antivirals address cytomegalovirus and BK polyomavirus threats.
- Diagnostics:LC-MS/MS therapeutic drug monitoring assays and molecular diagnostics enable precision dosing.
Established volume favors immunosuppressants; emerging adoption favors biologicals.
Indication:
Clinical application determines reimbursement coding and payer contract structures across jurisdictions.
- Prevent Rejection:Maintenance immunosuppression protocols require lifelong pharmaceutical intervention. United States transplant centers are consolidating procurement under centralized pharmacy committees, tightening adherence to institutional formularies for rejection prophylaxis.
- Post-transplant Infection:Prophylactic antimicrobial regimens target opportunistic pathogens in the immediate post-operative window. Demand clusters in hospital-based transplant centers where bundled payment models incentivize readmission reduction through aggressive infection prevention.
- Renal Dysfunction:Nephroprotective agents and dose-adjustment protocols preserve allograft function.
- Graft Failure:Salvage immunosuppression and re-transplant preparation protocols address late complications.
Prevention commands the dominant spend; infection management shows steepest expansion trajectory.
Delivery Mode:
Adherence economics reshape reimbursement calculations differently across administration routes.
- Sustained Release:Extended-release tacrolimus formulations reduce dosing frequency and improve pharmacokinetic stability. Payers in the United States are recalibrating reimbursement to favor once-daily regimens that demonstrate measurable adherence improvements.
- Oral Administration:Immediate-release tablets and capsules remain the default for maintenance therapy. Volume concentrates in specialty pharmacy channels where 90-day dispensing and adherence packaging programs target Medicare Part D populations.
- Injectable:Subcutaneous and intramuscular formulations serve induction protocols.
- Intravenous:Hospital-administered formulations dominate perioperative and acute rejection episodes.
Immediate-release oral formulations anchor current volume; sustained-release versions are gaining share fastest.
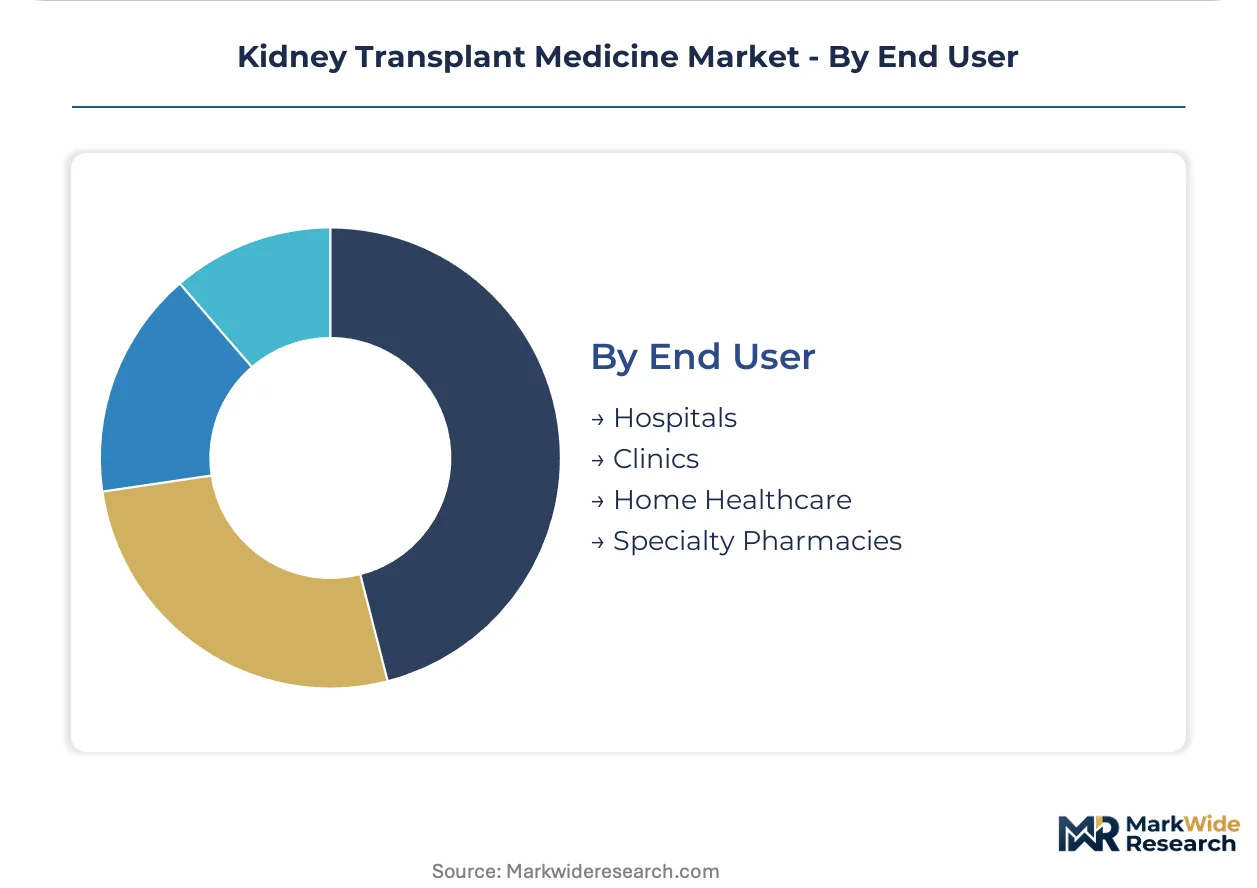
End User:
Procurement autonomy varies sharply across care settings, concentrating purchasing power in institutional channels.
- Hospitals:Academic medical centers and transplant-specialized hospital systems command the dominant procurement volume. Centralized pharmacy and therapeutics committees are eroding individual nephrologist autonomy in immunosuppressant selection across United States health systems.
- Specialty Pharmacies:Limited-distribution networks manage high-cost biologicals and narrow-therapeutic-index generics. These channels are capturing share from hospital outpatient departments as value-based contracts tie reimbursement to graft survival metrics.
- Clinics:Independent nephrology practices and dialysis centers handle stable maintenance patients.
- Home Healthcare:Infusion services and remote monitoring support early discharge protocols.
Hospital systems concentrate procurement power; specialty pharmacies are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites European distribution of narrow-therapeutic-index immunosuppressants, while the US Interstate Highway System enables just-in-time delivery to transplant centers across the continental United States.
United States
Medicare's removal of the 36-month immunosuppressive drug coverage cap eliminates cost barriers that previously drove graft loss among non-adherent patients. The FDA tightened bioequivalence standards for tacrolimus and cyclosporine, extending ANDA review timelines. The Mayo Clinic transplant network in Rochester, Minnesota anchors multi-site procurement standardization across academic medical centers.
Germany
Academic transplant centers in Berlin and Heidelberg are accelerating adoption of IL-2 receptor antagonists and co-stimulation blockade agents within steroid-minimization protocols. REACH and the EU MDR impose escalating purity mandates on biological immunosuppressant manufacturing, raising compliance costs for plasma-derived agents. The Rhine-Ruhr metropolitan region concentrates fractionation capacity for polyclonal antibody production.
Japan
PMDA's therapeutic drug monitoring guidelines for calcineurin inhibitors drive LC-MS/MS assay standardization across university hospitals. METI incentives support domestic manufacturing of sustained-release tacrolimus formulations. The Keihin industrial corridor spanning Tokyo and Kawasaki hosts specialized pharmaceutical packaging operations for narrow-therapeutic-index generics.
India
CDSCO's bioequivalence requirements for generic immunosuppressants are converging toward FDA standards, though review timelines remain shorter than Western regulators. The country's national pharmaceutical regulator maintains distinct purity thresholds for plasma-derived versus chemically synthesized agents. Hyderabad's Genome Valley anchors contract manufacturing for monoclonal antibody intermediates serving export markets.
United Kingdom
NHS England's value-based procurement pilots tie immunosuppressant reimbursement to graft survival metrics rather than prescription volume alone. The MHRA post-Brexit regulatory framework maintains alignment with EMA standards for biological manufacturing. The Cambridge-London life sciences corridor concentrates therapeutic drug monitoring assay development and precision diagnostics commercialization.
Kidney Transplant Medicine Market Competitive Landscape
Concentration sits with calcineurin inhibitor specialists and mTOR inhibitor developers, though biologicals manufacturing is fragmenting as monoclonal antibody platforms proliferate. Three archetypes dominate: entrenched small-molecule incumbents with tacrolimus franchises, plasma-derived biologicals specialists with fractionation assets, and precision diagnostics developers with LC-MS/MS capabilities. Competitive moves center on sustained-release formulation patent extensions and value-based contract pilots with Medicare Advantage plans.
Within the calcineurin inhibitor tier, Astellas Pharma Inc. and Veloxis Pharmaceuticals, Inc. exemplify contrasting strategic positions—one anchored in immediate-release market presence, the other in extended-release specialization. Among Swiss-based diversified pharmaceutical developers, Novartis AG and Roche occupy positions spanning mTOR inhibition and diagnostic platforms respectively. Bristol-Myers Squibb Company represents the co-stimulation blockade vector as belatacept penetration accelerates in steroid-minimization protocols.
| Leading Market Players |
|---|
| Astellas Pharma Inc. |
| Novartis AG |
| Sanofi |
| Bristol-Myers Squibb Company |
| GSK plc |
| AbbVie Inc. |
| Pfizer Inc. |
| Roche |
| Veloxis Pharmaceuticals, Inc. |
| Others |
Pricing and Supply Chain Analysis
Monoclonal antibody substitution for chronic corticosteroid exposure simultaneously reshapes manufacturing geography toward plasma fractionation clusters and compresses pricing economics for small-molecule immunosuppressants. Hospital procurement committees exploit this shift to consolidate volume discounts across biological and chemical agent categories.
Pricing Analysis
Volume-discount tiering structures dominate immunosuppressant procurement, with hospital systems leveraging multi-site transplant center networks to extract preferential terms from calcineurin inhibitor suppliers. Price differentiation hinges on therapeutic drug monitoring bundling and generic bioequivalence certification tier—FDA-approved narrow-therapeutic-index generics command premiums over standard ANDA pathways. Cost compression in immediate-release tacrolimus intensifies as extended-release formulations capture adherence-linked reimbursement bonuses. Medicare Advantage plans exhibit highest price sensitivity; academic medical centers with captive pharmacy operations show lowest.
Supply Chain Analysis
Inventory lead times for polyclonal antibody products extend due to plasma collection seasonality and fractionation batch complexity. Supply concentrates in the United States, Germany, and Switzerland for plasma-derived biologicals; India and China anchor active pharmaceutical ingredient synthesis for generic calcineurin inhibitors. Manufacturing rests on porcine-derived surfactant supplies, chromatography resin availability, and cold-chain logistics capacity. Single-source vulnerability permeates anti-thymocyte globulin production. Distribution runs through hospital-centric specialty pharmacy networks with limited-distribution biologicals protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kidney transplant medicine market exhibits cyclical recovery characteristics as Medicare coverage extension removes prior cost barriers and living-donor program expansion replenishes addressable patient pools.
For Market Incumbents: Consolidate procurement relationships through multi-year value-based contracts tying reimbursement to graft survival metrics rather than prescription volume. Deepen backward integration into therapeutic drug monitoring assay development to capture laboratory revenue streams threatened by centralized hospital committee purchasing. For New Entrants and Emerging Players: FDA fast-track designation for sustained-release tacrolimus formulations offers the most penetrable regulatory pathway, given bioequivalence complexity that deters immediate-release generic competition. Target United States specialty pharmacy channels with adherence-monitoring service bundling as differentiated go-to-market positioning against entrenched hospital formulary incumbents. For Investors and Strategic Acquirers: The FDA's tightened narrow-therapeutic-index bioequivalence standards reshape the acquisition landscape toward extended-release formulation specialists with validated pharmacokinetic profiles. Long-term viability centers on biologicals manufacturing assets with plasma fractionation infrastructure. Monitor Medicare Advantage plan value-based contract adoption rates as inflection signal for pricing power migration from manufacturers to payers.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Once-daily tacrolimus dosing captures adherence-linked reimbursement bonuses from Medicare Advantage plans. |
| Therapeutic Drug Monitoring Integration | LC-MS/MS assay bundling with immunosuppressant supply secures laboratory revenue against hospital committee consolidation. |
| Value-Based Contract Piloting | Graft survival metric linkage differentiates suppliers in United States hospital system procurement competitions. |
| Plasma Fractionation Capacity Expansion | Anti-thymocyte globulin supply security addresses single-source vulnerability in polyclonal antibody production. |
| Steroid-Minimization Protocol Partnerships | IL-2 receptor antagonist co-development with academic medical centers accelerates biologicals category penetration. |
Research Methodology
Operator-level perspectives from transplant pharmacy directors, nephrology procurement committee members, payer formulary managers, and LC-MS/MS assay laboratory directors anchored the qualitative base. Secondary validation drew from FDA ANDA filings, EMA MDR submission databases, CMS Medicare Part D claims extracts, and hospital GPO contract repositories. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure triangulation produced convergent volume estimates.
Sensitivity analysis tested forecast robustness across alternative immunosuppression protocol adoption curves and generic substitution rate scenarios over the projection horizon. Segmentation dimensions spanned product type, indication severity, delivery mode pharmacokinetics, and end-user procurement autonomy. CAGRs derived from logistic diffusion modeling of sustained-release formulation uptake and linear extrapolation of living-donor program expansion trajectories. Medicare policy continuity and FDA bioequivalence enforcement intensity served as scenario-dependent inputs.
Decision-makers should treat outputs as directional under assumptions of stable Medicare immunosuppressive coverage extension and unaltered narrow-therapeutic-index regulatory thresholds; material deviation in reimbursement policy or bioequivalence standards would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
Global Nephroblastoma Treatment Market
Nephrology
Global Dialysis Market
Nephrology
Renal Stent Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
Renal Cell Carcinoma Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Complement 3 Glomerulopathy (C3G) Treatment Market
Nephrology
Renal Insufficiency Treatment Market
Nephrology
Global Continuous Renal Replacement Therapy (CRRT) Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Renal Denervation Market
Nephrology
Dialysis Centers Market
Nephrology
Nephrotic Syndrome Market
Nephrology
Ketoanalogue for Kidney Disease Market
Nephrology
Kidney Transplant Market