
 Global Ambulance Market | 2026-2036
Global Ambulance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ambulance Market Intelligence
The capability gap between custom, high-spec vehicle manufacturing and standardized, high-volume production is reorganizing the competitive landscape. REV Group leverages its large-scale manufacturing footprint to serve diverse price points and fleet requirements. In contrast, specialists like Braun Industries and Demers Ambulances differentiate through custom engineering and advanced life support integration. NAFFCO focuses on serving the specific needs of markets in the Middle East and Africa with ruggedized vehicle options.
An ambulance is a medically equipped vehicle designed for transporting patients to healthcare facilities. These vehicles must meet specific chassis-based structural integrity standards, such as the KKK-A-1822 federal specification in the United States, to ensure occupant safety during transit. Advanced Life Support (ALS) units represent the highest value segment due to complex onboard medical systems. Demand from Private Healthcare Providers is growing faster than from traditional Public Emergency Services, especially for non-emergency patient transport applications.
Regulatory compliance is a critical barrier to entry, with standards set by bodies like the U.S. National Highway Traffic Safety Administration (NHTSA) for vehicle safety and the European Union's CE marking for onboard medical devices. The WHO's Essential Emergency and Critical Care guidelines also influence design specifications in many countries. Vehicle manufacturers must now decide whether to invest in all-electric powertrain development or focus on optimizing internal combustion engine platforms for the near term.
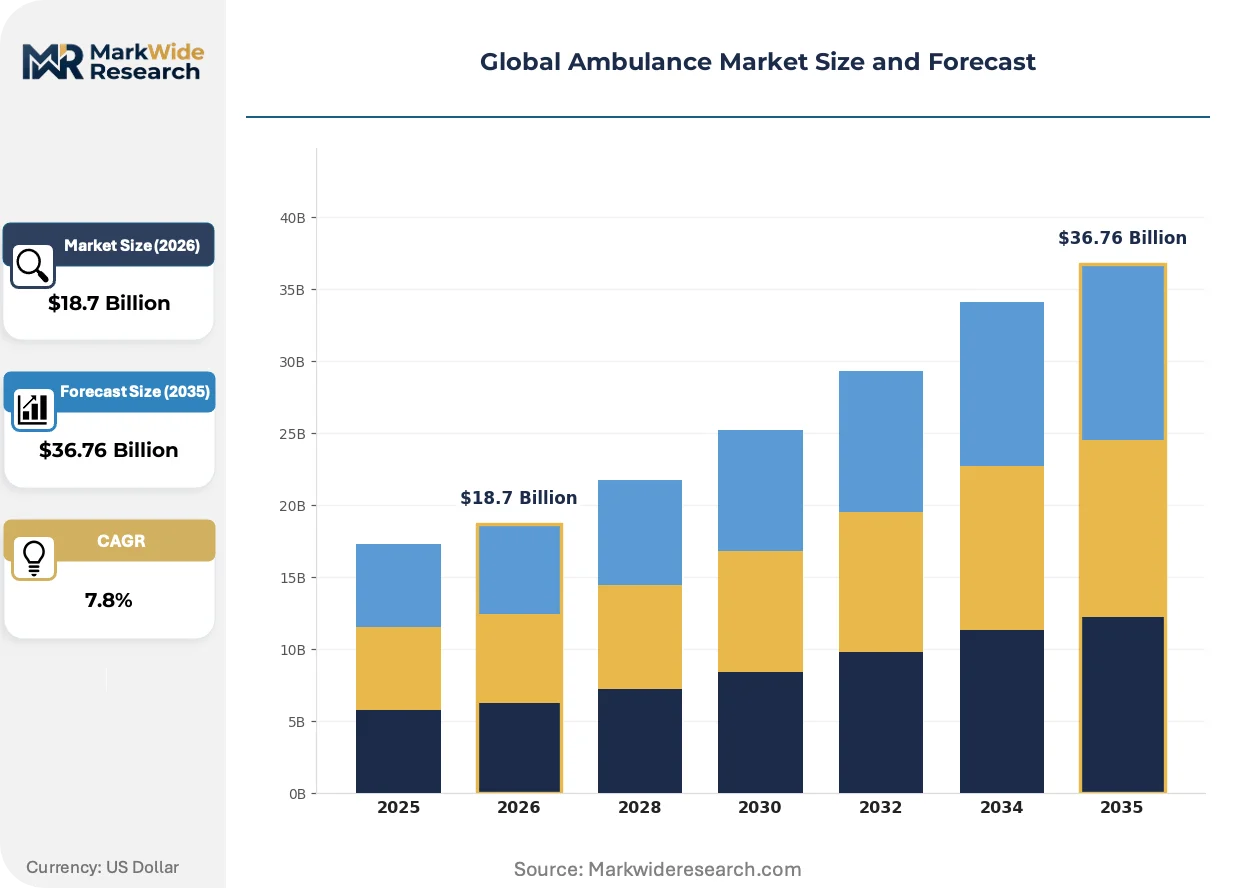
Market Dynamics
The ambulance market's competitive structure is being redefined by the divergence between high-volume, standardized production and low-volume, custom-engineered vehicles. This dynamic creates distinct pathways for market participants, with fleet standardization driving scale economies while advanced life support requirements demand specialized manufacturing capabilities.
Growth Catalysts
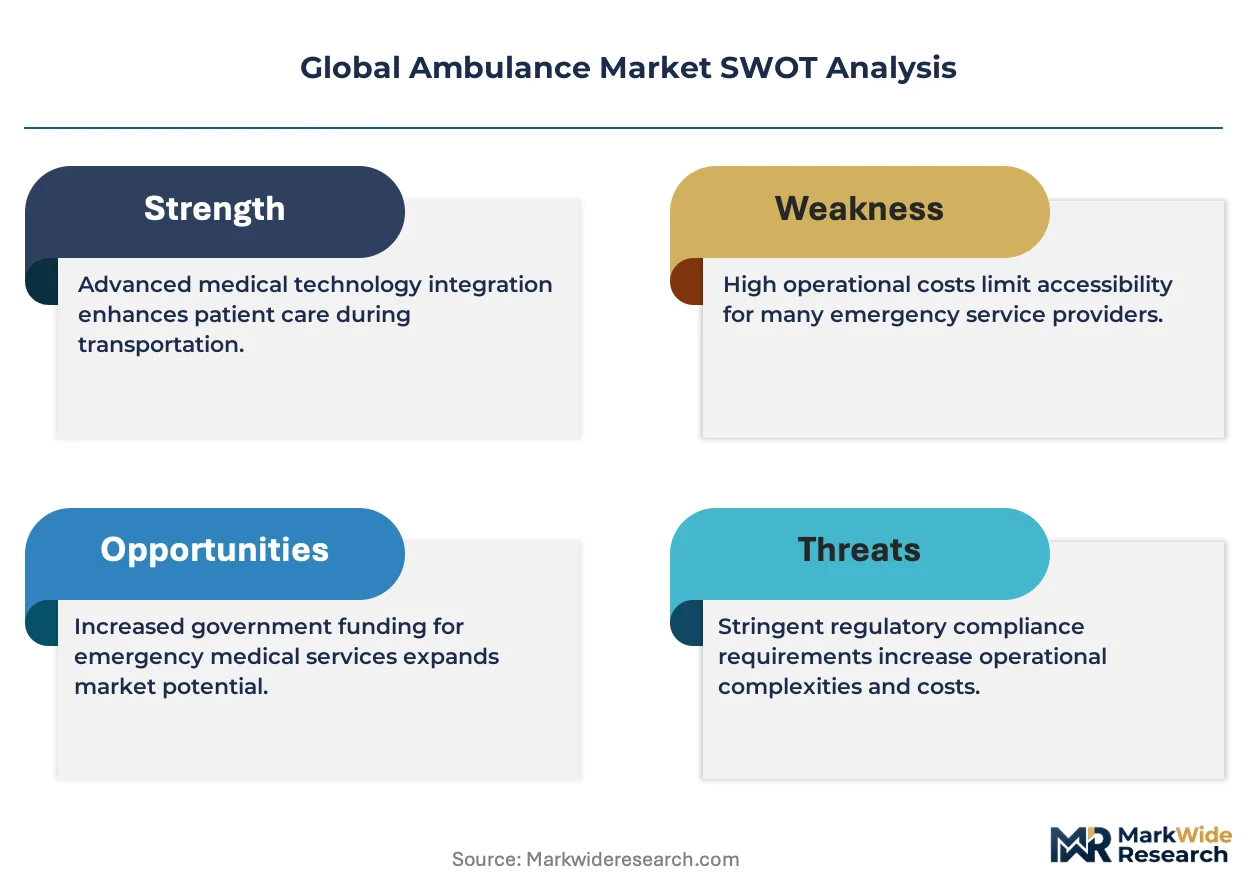
- Stricter Emissions Standards:Regulations like Europe's Euro 6 and comparable rules in other regions are compelling public and private fleet operators to upgrade older vehicles, creating a consistent replacement cycle.
- Infrastructure Development:The expansion of emergency medical services infrastructure, particularly in countries like India, is creating foundational demand for new ambulance fleets to improve national response times and healthcare access.
- Onboard Telemedicine Integration:The incorporation of advanced telemedicine systems allows for real-time patient data transmission to hospitals, improving outcomes and justifying investment in higher-specification Advanced Life Support (ALS) vehicles.
Market Restraints
- High Certification Costs:Meeting structural integrity and safety standards, such as the KKK-A-1822 federal specification in the United States, involves significant testing and engineering investment, acting as a barrier to new entrants.
- Complex Medical Device Integration:The integration and certification of onboard medical equipment, which must comply with regulations like the European Union's CE marking, adds significant cost and complexity to vehicle manufacturing.
- Electric Powertrain Viability:The high initial cost and unresolved technical challenges related to range, charging infrastructure, and power for onboard systems limit the immediate, large-scale adoption of all-electric ambulance platforms.
Strategic Opportunities
- Ruggedized Vehicle Platforms:Developing specialized, durable ambulances for markets with challenging terrain and climate conditions, particularly in parts of Africa and the Middle East, addresses an underserved need.
- Non-Emergency Patient Transport:The growing private healthcare sector is creating a distinct market for vehicles optimized for non-emergency patient transport, which have different design and cost requirements than traditional emergency ambulances.
- Modular Interior Systems:Designing ambulances with modular and reconfigurable interiors allows manufacturers to offer greater customization and serve multiple mission profiles, from basic transport to mobile critical care, with a single platform.
Industry Challenges
- Specialized Technician Scarcity:A shortage of technicians with the dual expertise in automotive mechanics and sophisticated medical electronics poses a significant challenge for fleet maintenance and ensuring vehicle uptime.
- Legacy System Interoperability:Integrating modern, digitally-native ambulance communication systems with the often-outdated radio and dispatch infrastructure of public emergency services creates significant operational friction and delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ambulance Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Life Support, Advanced Life Support, Patient Transport, Neonatal Ambulance, Mortuary Vehicle Application: Emergency Response, Non-Emergency Transport, Disaster Management, Event Medical Services, Patient Transfer End User: Public Emergency Services, Private Healthcare Providers, Military Medical Units, Non-Profit Organizations, Corporate Health Facilities Deployment: Road Ambulance, Air Ambulance, Water Ambulance, Motorcycle Ambulance |
| Companies Covered | REV Group, Demers Ambulances, Braun Industries, NAFFCO, Crestline Ambulance, Life Line Emergency Vehicles, Medix Specialty Vehicles, Frazer Ltd, WAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ambulance Market Strategic Shifts & Innovations
The convergence of advanced medical technology and stringent automotive regulations is reshaping vehicle design and function. Manufacturers must navigate the dual pressures of integrating complex life-support systems while meeting new mandates for vehicle safety and environmental performance.
Technology and Product Evolution
Onboard telemedicine platforms integrate real-time biometric monitoring, diagnostics, and secure video links to hospitals. Private healthcare providers are the most rapid adopters, aiming to initiate critical care protocols before a patient reaches the emergency department. This capability is fragmenting the traditional response model by creating distinct tiers of pre-hospital intervention and specialized transport services.
Regulatory and Policy Shifts
Stricter vehicle emission standards, including Europe's Euro 6 framework and parallel clean air regulations from the U.S. Environmental Protection Agency, are a primary influence on chassis development. This pressure is forcing manufacturers to invest in either optimizing internal combustion engine platforms or developing costly all-electric powertrains. The Type II van-based ambulance segment is most affected, prompting a re-evaluation of platform choices for urban fleets.
Demand-Side and Behavioral Shifts
A move toward full-service fleet leasing and comprehensive maintenance contracts is altering acquisition models, especially for large private operators. This operational expenditure model displaces the traditional one-time capital purchase, allowing organizations to manage costs and ensure fleet modernity. The pattern is most visible in North American and European markets where private patient transport companies command significant purchasing volume.
Global Ambulance Market Segmentation
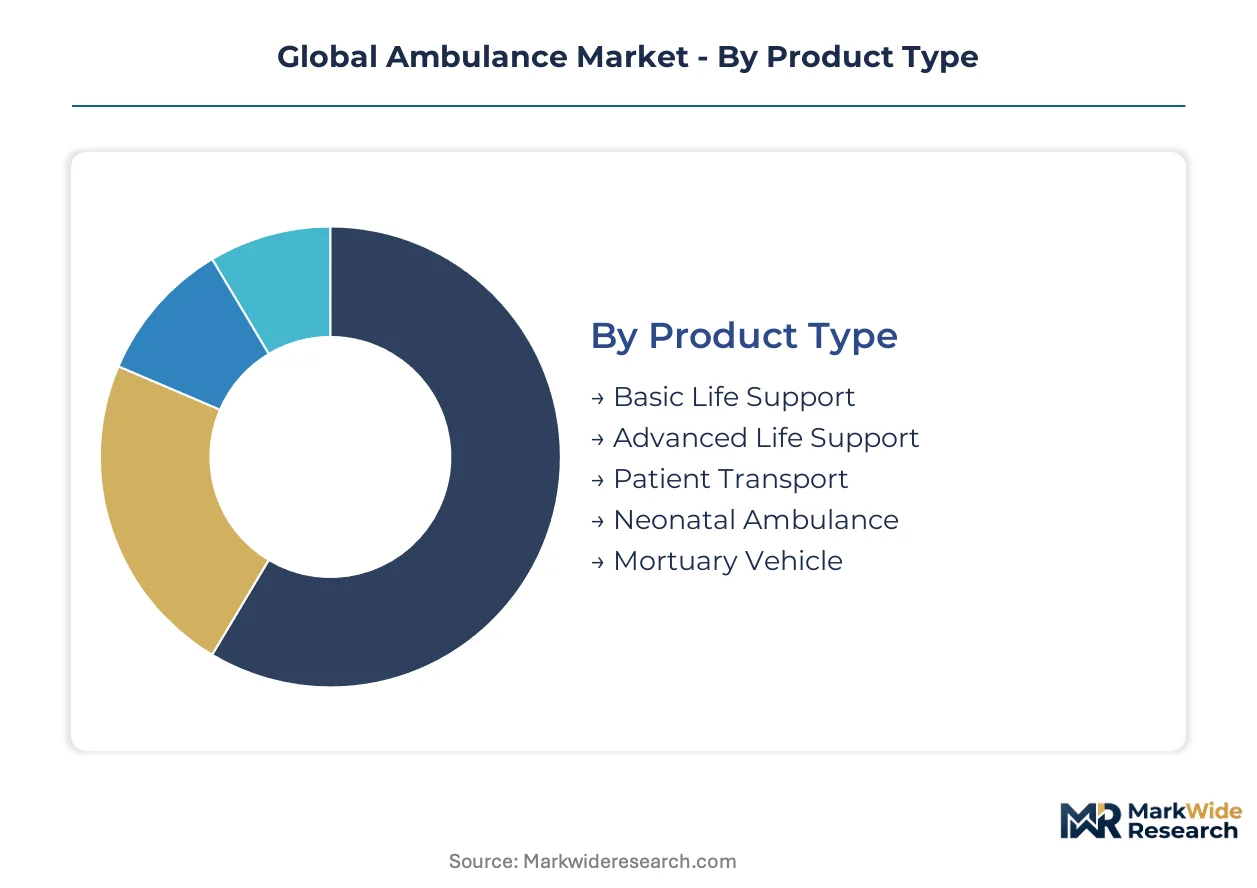
Segmentation provides a granular understanding of the diverse requirements driving the global ambulance market, highlighting specialized demands across different operational contexts and patient needs. Analyzing these segments reveals varying growth trajectories and technological adoption rates, informing strategic investments for manufacturers.
Product Type:
Product type segmentation highlights how certain ambulance configurations are tailored for specific national healthcare systems, while others serve broader international demand.
- Advanced Life Support:These units integrate complex medical systems for critical interventions, including cardiac monitoring and ventilation. Demand concentrates in developed economies like the United States and Germany, driven by private healthcare providers seeking to improve pre-hospital patient outcomes.
- Patient Transport:Vehicles optimized for non-emergency transfers of stable patients between facilities, often with less intensive medical equipment. North American and European private healthcare providers increasingly adopt these platforms to manage operational costs and improve patient flow.
- Basic Life Support:Ambulances equipped for fundamental medical care and patient stabilization during transport.
- Neonatal Ambulance:Specialized vehicles designed with incubators and life support for transporting critically ill newborns between hospitals.
- Mortuary Vehicle:Dedicated vehicles for the dignified transport of deceased individuals, adhering to specific public health regulations.
Basic Life Support commands the established base. The steepest expansion runs through Advanced Life Support.
Application:
Application segmentation differentiates ambulance usage based on the urgency and nature of patient needs, influencing vehicle design and onboard equipment.
- Emergency Response:These services involve rapid deployment to critical incidents, providing immediate medical intervention and transport to hospitals. Public emergency services and private operators in France and the United Kingdom prioritize these high-spec vehicles to meet strict response time mandates.
- Non-Emergency Transport:Scheduled patient transfers for appointments, discharges, or inter-facility moves where immediate life support is not required. Private healthcare networks in India and Brazil increasingly utilize these services to optimize resource allocation and patient convenience.
- Disaster Management:Specialized ambulance fleets deployed in large-scale emergencies, requiring robust communication and extended operational capabilities.
- Event Medical Services:Ambulances providing on-site medical coverage for public gatherings, ensuring immediate care for attendees.
- Patient Transfer:General purpose transport of patients between medical facilities or from home to hospital, often for non-critical conditions.
Emergency Response applications represent the most mature segment. Non-Emergency Transport applications are expanding significantly as healthcare systems evolve.
End User:
End user segmentation reveals distinct procurement patterns, reflecting varying budget constraints, regulatory environments, and service mandates across different organizations.
- Private Healthcare Providers:These entities acquire ambulances for both emergency and non-emergency transport, often prioritizing advanced telemedicine and fleet leasing models. Demand from these providers in the United States and Germany is growing faster than traditional public services due to expanding service offerings.
- Public Emergency Services:Government-funded agencies responsible for initial emergency medical response and transport, adhering to strict national standards like KKK-A-1822 in the US. These services represent the largest installed base, with replacement cycles driven by stricter emissions standards such as Europe's Euro 6.
- Military Medical Units:Specialized ambulance vehicles designed for rugged operational environments and battlefield casualty evacuation, often with enhanced armor and off-road capability.
- Non-Profit Organizations:Charities and humanitarian groups operating ambulances in underserved regions or during disaster relief efforts, frequently relying on donated or refurbished vehicles.
- Corporate Health Facilities:On-site medical units at large industrial complexes or remote project sites, providing immediate care and transport for employees.
Public Emergency Services drive consistent foundational demand for ambulances. Private Healthcare Providers are increasingly influencing market specifications and volume.
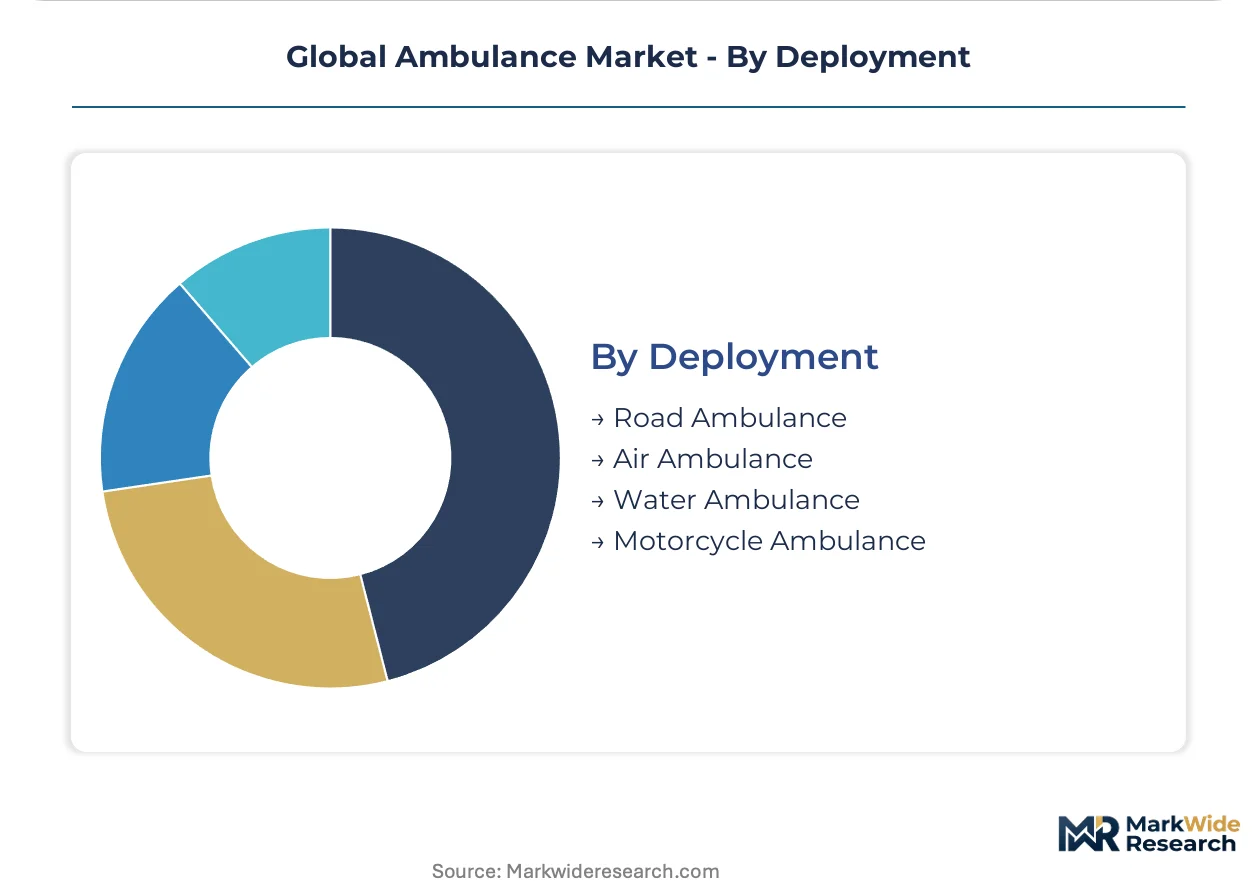
Deployment:
Deployment segmentation highlights the critical dependency on specific infrastructure, from extensive road networks to specialized airfields and waterways, influencing operational reach and speed.
- Road Ambulance:The most common form of patient transport, these vehicles utilize standard chassis platforms adapted for medical use, navigating urban and rural road networks. Their widespread use across India and the United Kingdom underpins national emergency medical services infrastructure.
- Air Ambulance:Helicopters or fixed-wing aircraft equipped for rapid patient transport over long distances or challenging terrain, offering critical time savings for severe trauma cases. Services in Australia and Canada rely heavily on these platforms for remote area access and inter-hospital transfers.
- Water Ambulance:Boats or other marine vessels equipped to transport patients across waterways, lakes, or coastal areas where road access is limited.
- Motorcycle Ambulance:Agile two-wheeled vehicles used for rapid first response in congested urban areas, carrying basic medical equipment and personnel.
Road Ambulance dominates the market in terms of volume and accessibility. Air and Water Ambulances serve critical, high-value niche applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across the global ambulance market. Developed economies prioritize high-spec Advanced Life Support vehicles, reflecting lower price sensitivity for critical care. Conversely, emerging markets often seek cost-effective Basic Life Support units for foundational emergency medical services infrastructure. This divergence shapes regional procurement and manufacturing strategies.
United States
Private healthcare providers drive demand for advanced telemedicine integration in US ambulances. The KKK-A-1822 federal specification mandates stringent structural integrity standards for all vehicles. Manufacturers in states like Ohio and Indiana specialize in custom ambulance body fabrication and complex medical system integration.
Germany
German healthcare systems require high-value ALS units, supported by robust private healthcare investment. European Union's CE marking is essential for onboard medical devices, ensuring compliance across the continent. Production clusters near cities like Wietmarschen focus on high-quality, technically advanced emergency vehicles.
India
India's expanding emergency medical services infrastructure generates foundational demand for new ambulance fleets. The country's national health policies encourage investment in improving response times and healthcare access. Manufacturers in regions like Maharashtra are scaling up production for both basic and advanced life support vehicles.
United Kingdom
Public emergency services in the United Kingdom prioritize high-spec vehicles to meet strict response time mandates. Stricter vehicle emission standards, including Europe's Euro 6 framework, compel fleet operators to upgrade. Specialist vehicle builders in areas around the Midlands develop innovative designs for urban and rural operations.
United Arab Emirates
NAFFCO focuses on serving the specific needs of markets in the Middle East and Africa with ruggedized vehicle options. The UAE's Ministry of Health and Prevention (MOHAP) sets standards for emergency medical services and vehicle specifications. Dubai's strategic location supports logistics and distribution for specialized ambulance platforms across the region.
Global Ambulance Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the ambulance market. The competitive structure is reorganizing around the divergence between custom, high-spec vehicle manufacturing and standardized, high-volume production. This creates distinct pathways for market participants, with global conglomerates leveraging scale economies and specialist manufacturers focusing on advanced life support integration. Strategic partnerships and portfolio diversification are common competitive moves.
The market features a mix of global manufacturers and specialized producers. Companies such as REV Group exemplify the strategy of leveraging large-scale manufacturing footprints to serve diverse price points and fleet requirements across various geographies. In contrast, specialists like Braun Industries and Demers Ambulances differentiate themselves through custom engineering and advanced life support integration, targeting the highest value segments. NAFFCO, focusing on specific regional demands, represents a player archetype specializing in ruggedized vehicle options for challenging terrains, particularly in the Middle East and Africa.
| Leading Market Players |
|---|
| REV Group |
| Demers Ambulances |
| Braun Industries |
| NAFFCO |
| Crestline Ambulance |
| Life Line Emergency Vehicles |
| Medix Specialty Vehicles |
| Frazer Ltd |
| WAS |
| Others |
Cost & Logistics Intelligence
KKK-A-1822 federal specification gates ambulance supply qualification and influences price differentiation for US markets. This stringent standard ensures occupant safety but adds significant manufacturing cost.
Pricing Analysis
After-sales service and comprehensive maintenance contracts drive significant lifetime value for ambulance manufacturers. Pricing stratifies across premium, standard, and economy tiers, reflecting customization levels and certification adherence to standards like KKK-A-1822. Pricing pressure stems from the high initial cost of advanced features and complex medical device integration. Private healthcare providers exhibit lower price sensitivity for Advanced Life Support units, while public emergency services often prioritize cost-effectiveness for fleet replacements.
Supply Chain Analysis
The integration and certification of onboard medical equipment represent a critical chokepoint in the ambulance supply chain. Component dependencies include specialized chassis platforms and advanced medical electronics, sourced globally from countries like Germany for high-quality components and India for foundational parts. Single-source vulnerability for specialized medical systems poses a structural risk. Distribution runs through direct sales channels to large fleet operators and authorized dealers for smaller purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ambulance market is poised for cyclical recovery, driven by stricter emissions standards compelling fleet operators to upgrade older vehicles. This creates a consistent replacement cycle and foundational demand.
For Market Incumbents: Consolidate large-scale manufacturing footprints to serve diverse price points and fleet requirements. Invest in advanced life support integration to counter the threat of new entrants focusing on specialized niches. Deepen vertical integration for complex medical systems to mitigate supply chain risks. Prioritize R&D in all-electric powertrain development to meet future emission mandates.
For New Entrants and Emerging Players: Lead with specialized, durable ambulances for markets with challenging terrain, particularly in Africa and the Middle East. Target the non-emergency patient transport segment, optimizing vehicles for cost and specific design requirements. A go-to-market angle involves offering modular interior systems to allow for greater customization and multiple mission profiles. This addresses underserved needs in developing healthcare infrastructures.
For Investors and Strategic Acquirers: Stricter vehicle emission standards reshape the acquisition landscape, favoring companies with advanced powertrain capabilities. The essential nature of emergency services ensures long-term viability over a 5-10 year window. Investors should target specialists in advanced life support integration or ruggedized vehicle platforms. A key signal to watch is significant investment in all-electric powertrain development by established manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Electric Powertrain R&D | Prepares for future emission mandates and expands urban fleet options. |
| Develop Modular Interior Systems | Increases vehicle versatility for diverse mission profiles and customization. |
| Expand Ruggedized Vehicle Offerings | Captures demand from challenging terrains in Africa and the Middle East. |
| Secure Medical Device Integration Partnerships | Ensures compliance and enhances Advanced Life Support capabilities. |
| Scale Non-Emergency Transport Platforms | Addresses growing demand from private healthcare providers for cost-effective solutions. |
Research Approach
The analysis maps product types like Advanced Life Support and Patient Transport, each validated through primary interviews with industry stakeholders. Conversations included vehicle engineers, procurement managers from private healthcare providers, and public emergency services fleet operators. Secondary validation drew from NHTSA vehicle safety standards, EU CE marking guidelines, and national health policies. This approach triangulated bottom-up market intelligence with top-down regulatory frameworks.
Forecast outputs were consistently checked against external benchmarks and industry reports across the analysis window. The quantitative model triangulated data across product type, application, end user, deployment, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical data and projected growth drivers. Key forecast inputs included vehicle replacement cycles and emergency medical services infrastructure development rates.
Forecasts assume regulatory continuity in US NHTSA and European CE marking regimes; material policy shifts would require re-modeling. These projections reflect current assumptions regarding electric powertrain viability and global supply chain stability. Practitioners should keep alternative scenarios live as technological advancements and geopolitical conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
Air Ambulance Services Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
Chest Compressors Market
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
US EMS Billing Services Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
Global Emergency Medical Apps Market
Emergency Medical Services
Adrenal Crisis Management Market
Emergency Medical Services
Patient Transport Services Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
Emergency Medical Services Market
Emergency Medical Services
Cardiopulmonary Resuscitation Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
Europe Ambulance Services Market