
 China First Aid Market | 2026-2036
China First Aid Market Size, Share, and Industry Trends Forecast 2026-2036
China First Aid Market Outlook
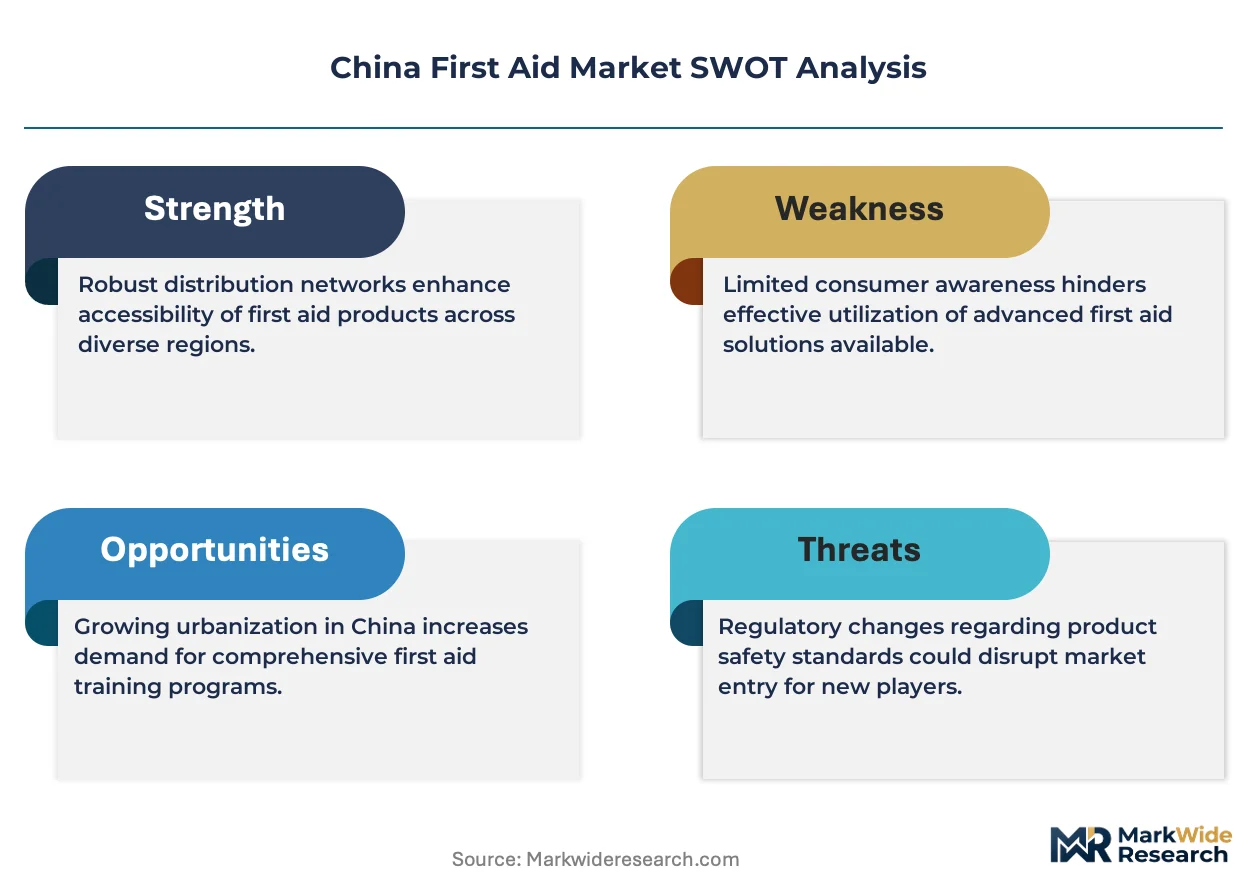
Class II medical device certification upgrades are redrawing competitive boundaries in China's first aid sector. Winner Medical Group Co. leverages vertical integration from cotton sourcing to sterilized finished goods, sustaining cost advantages against import-dependent rivals. Johnson & Johnson navigates pricing pressures through brand strength in premium adhesive bandages and advanced wound dressings.
First aid comprises sterile and non-sterile products for immediate wound management, hemorrhage control, and infection prevention, with ISO 13485-compliant manufacturing ensuring biocompatibility and sterility assurance levels. The products serve emergency intervention, home self-treatment, and occupational safety compliance across industrial and commercial settings. Bandages and dressings anchor volume demand through hospital procurement tenders, while first aid kits generate higher margins through retail channel differentiation. Online retail channels are expanding fastest among distribution segments, though pharmacies retain institutional trust for post-prescription replenishment.
NMPA medical device registration requirements and GB standard compliance for sterile products shape market access barriers and quality thresholds for domestic and imported manufacturers alike. The country's dual carbon goals are pressuring packaging material transitions across supply chains. Stakeholders must monitor provincial centralized procurement expansions and tiered hospital network standards that will determine volume allocation and margin compression trajectories.
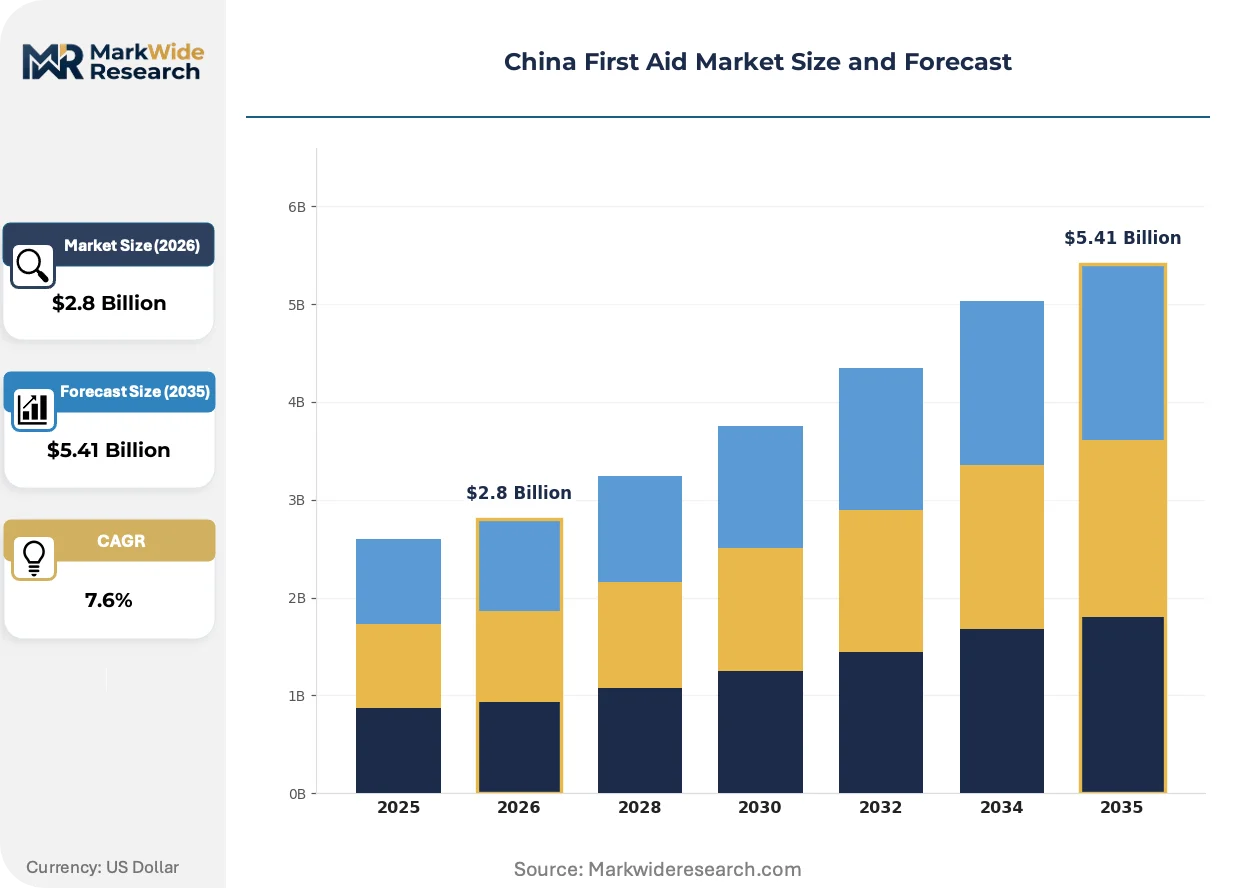
Market Dynamics
NMPA medical device classification reforms are compressing product registration timelines while provincial centralized procurement systems reshape volume allocation across China's first aid sector. Hospital networks in Shanghai and Beijing are consolidating purchasing power, forcing manufacturers to adapt certification strategies and cost structures simultaneously.
Growth Catalysts
- Emergency medicine infrastructure expansion:Tertiary hospital networks in eastern provinces are scaling trauma center capabilities, driving institutional procurement of hemorrhage control and advanced wound management products.
- NMPA Class II certification streamlining:Reduced technical documentation requirements and accelerated review pathways are shortening market access timelines for domestic sterile product manufacturers.
- Occupational safety compliance mandates:Industrial manufacturing and construction sectors face intensified workplace first aid kit requirements under revised national safety standards.
Market Restraints
- Cotton raw material cost volatility:Domestic cotton price fluctuations and import dependency for medical-grade fibers squeeze margin structures for gauze and dressing producers.
- Import concentration in advanced segments:Hydrogel and foam dressing technologies remain dominated by multinational suppliers with established NMPA registrations, limiting domestic substitution pace.
- GB standard compliance fragmentation:Provincial interpretation variations in sterile product testing protocols create redundant certification burdens for multi-region distribution.
Strategic Opportunities
- Central and western province penetration:Tier-2 and tier-3 city hospital networks remain underpenetrated for advanced wound care relative to coastal saturation levels.
- E-commerce direct-to-consumer channels:JD Health and Tmall Pharmacy platforms enable branded first aid kit bypass of traditional pharmaceutical wholesale hierarchies.
- Dual carbon packaging transition:MEE pressure on single-use plastics creates first-mover advantage for biodegradable and recyclable sterile barrier material innovators.
Industry Challenges
- Biocompatibility testing capacity bottlenecks:ISO 10993-compliant laboratory scarcity extends product validation timelines for novel material introductions.
- Provincial tender price convergence:Centralized procurement platforms force margin compression as volume commitments override premium positioning strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China First Aid Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bandages, Antiseptics, Dressings, First Aid Kits End User: Households, Healthcare Facilities, Educational Institutions, Sports Organizations Distribution Channel: Online Retail, Pharmacies, Supermarkets, Medical Supply Stores Application: Emergency Care, Home Care, Workplace Safety, Outdoor Activities |
| Companies Covered | Johnson & Johnson, Winner Medical Group Co., Yunnan Baiyao, 3M Company, Hangzhou Aosi Healthcare Co., Ltd., Suzhou Sunmed Co., Ltd., Changzhou Recoo Healthcare Co., Ltd., Hangzhou Bever Medical Devices Co., Ltd., Medtronic (China) Investment Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China First Aid Market Strategic Shifts
China's first aid sector is experiencing material science convergence with digital supply chain integration, reshaping how sterile products reach end-users. Three distinct vectors are compressing traditional competitive advantages while opening new value capture mechanisms.
Antimicrobial silver-ion and PHMB-impregnated dressings are decomposing the historical premium attached to imported advanced wound care products. Tertiary hospital procurement committees are accelerating domestic supplier qualification for these functional categories. Cost-equivalent performance is enabling volume substitution in institutional tenders previously reserved for established multinational brands.
NMPA medical device unique identification (UDI) implementation is mandating full supply chain traceability for Class II sterile products. Manufacturers must retrofit production lines with serialization infrastructure and database integration capabilities. Medium-scale domestic producers face disproportionate compliance costs relative to vertically integrated competitors with captive IT systems.
Hospital pharmacy departments are consolidating replenishment authority through digital procurement platforms that disintermediate traditional distributor relationships. Shanghai and Beijing health commission pilot programs demonstrate automated inventory management with direct manufacturer integration. Retail channel influence is compressing as institutional buyers prioritize supply security and transparent pricing over historical relationship-based sourcing.
China First Aid Market Segmentation
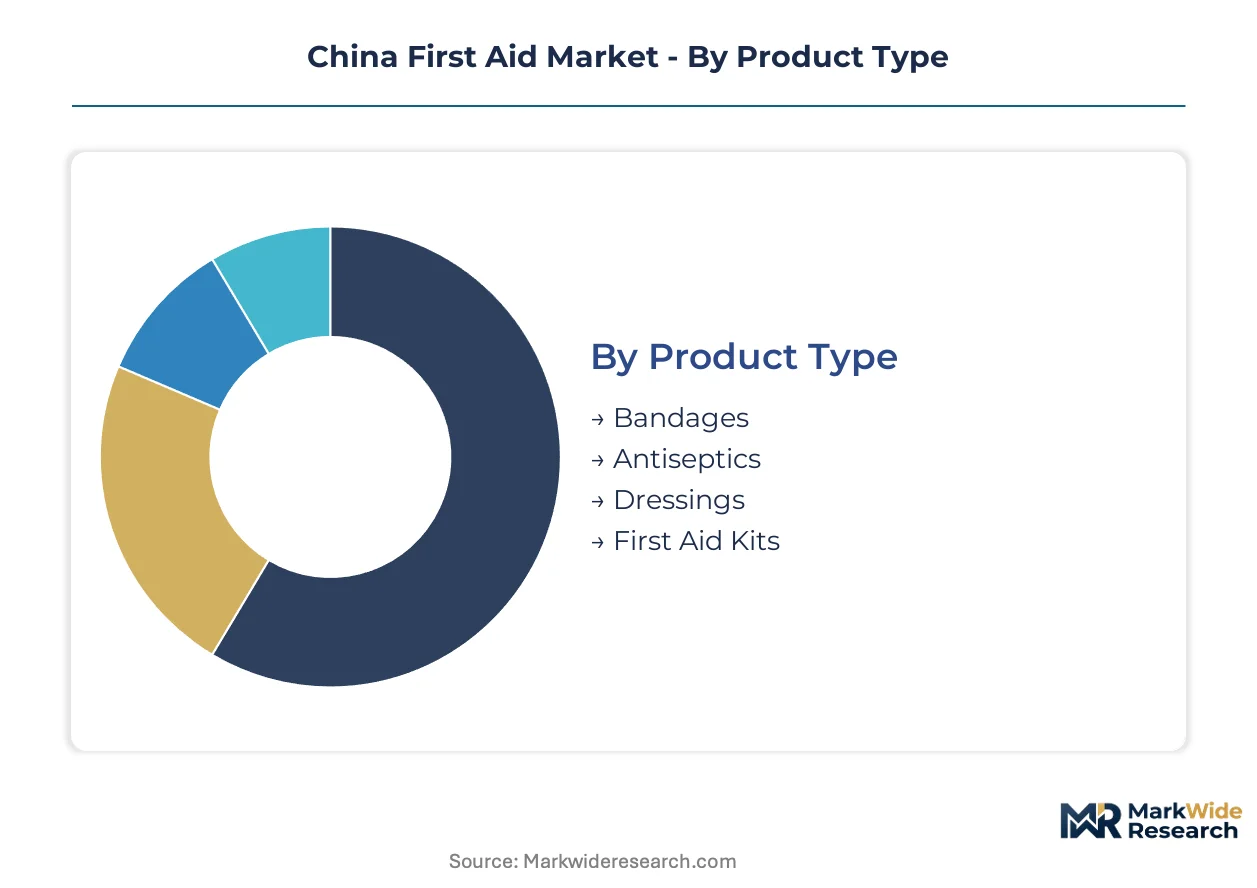
Segmentation in China's first aid market reveals how procurement authority, regulatory classification, and channel economics allocate margin capture across manufacturers. NMPA device tiers and provincial tender structures create divergent competitive dynamics within each category.
Product Type:
Substitution pressure from antimicrobial-functional alternatives is reshaping the traditional gauze-cotton hierarchy, with advanced materials displacing commodity segments in institutional procurement.
- Bandages:Adhesive strips and elastic wraps dominate household replenishment cycles. Shanghai and Beijing hospital networks consolidate tender volumes for sterile surgical variants, compressing margin structures for import-dependent suppliers.
- Antiseptics:Povidone-iodine and chlorhexidine solutions face formulation standardization under revised GB pharmacopeia requirements. Industrial workplace mandates are expanding institutional procurement beyond traditional healthcare settings.
- Dressings:Hydrogel, foam, and silver-ion impregnated variants command premium positioning in tertiary trauma centers.
- First Aid Kits:Pre-assembled configurations for occupational compliance generate higher per-unit margins than component sales.
Bandages anchor the volume base while dressings gain share at the steepest rate.
End User:
Cost tier stratification separates premium institutional procurement from price-sensitive household replenishment, with certification grade determining access to each tier.
- Healthcare Facilities:Tertiary hospital trauma centers and surgical departments drive sterile product specifications. NMPA Class II certification requirements filter supplier pools, favoring domestic manufacturers with accelerated registration timelines.
- Households:Self-treatment demand concentrates in adhesive bandages and topical antiseptics. JD Health and Tmall Pharmacy platforms are disintermediating traditional pharmaceutical wholesale channels for this segment.
- Educational Institutions:Campus safety mandates under national education bureau guidelines standardize kit configurations across primary and secondary schools.
- Sports Organizations:Professional athletic associations and fitness facility chains drive specialized hemorrhage control and cold therapy procurement.
Healthcare facilities concentrate procurement authority while households expand most quickly through e-commerce penetration.
Distribution Channel:
Geographic reach constraints favor channels with established cold-chain and sterile handling capabilities, particularly for NMPA-regulated device categories.
- Online Retail:JD Health and Tmall Pharmacy platforms enable direct manufacturer-to-consumer fulfillment, bypassing traditional pharmaceutical distribution markups. Serialization infrastructure for NMPA UDI compliance is compressing platform entry costs for certified domestic suppliers.
- Pharmacies:Hospital-affiliated and community pharmacy networks retain institutional trust for post-prescription replenishment. Provincial centralized procurement pilots are consolidating replenishment authority through digital platforms.
- Supermarkets:Mass retail channels concentrate non-sterile household consumables with limited regulatory complexity.
- Medical Supply Stores:Specialized distributors serve industrial and occupational safety compliance segments with kit customization services.
Pharmacies retain the procurement volume base while online retail climbs the fastest on direct-to-consumer platform expansion.
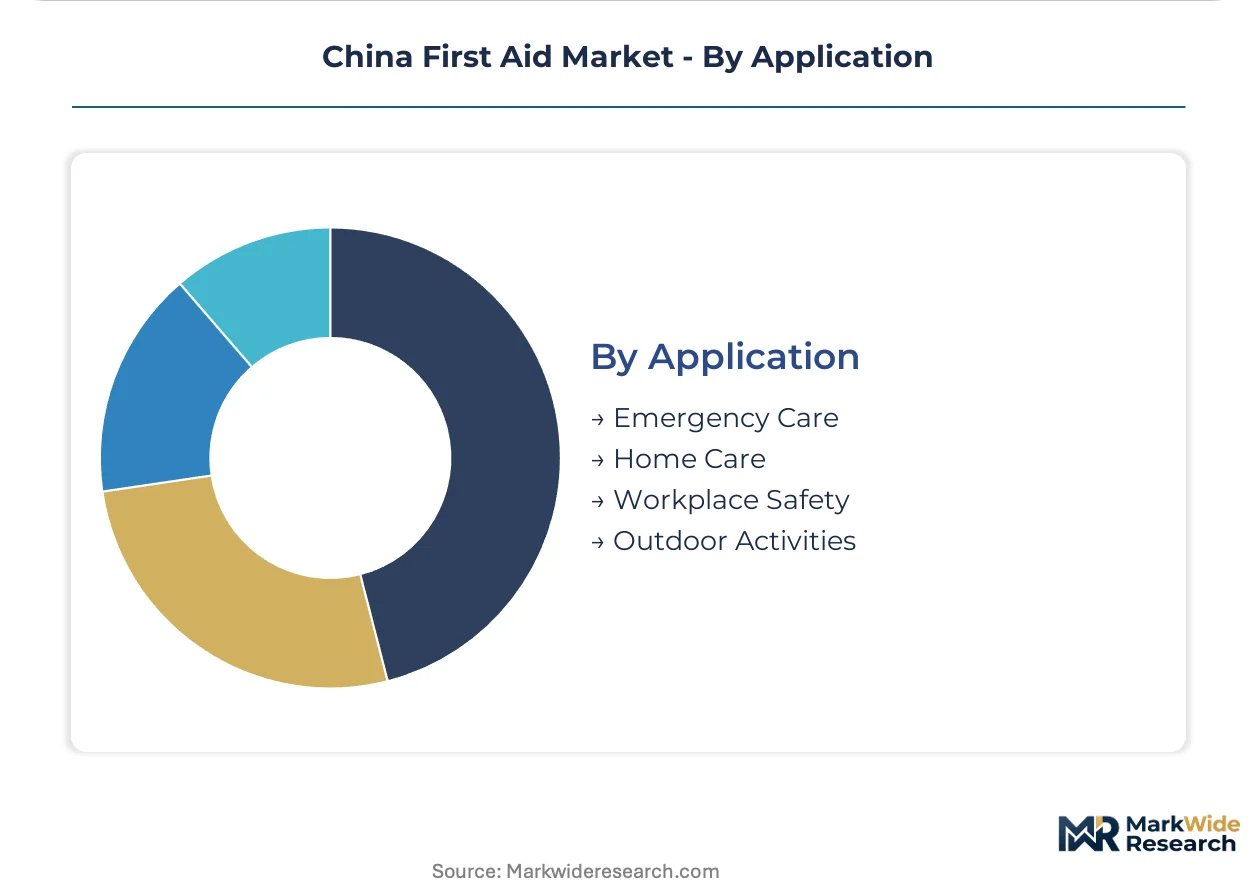
Application:
Customer type maturity separates emergency intervention segments with established procurement protocols from emerging outdoor and home care categories with less standardized purchasing.
- Emergency Care:Trauma center and pre-hospital ambulance service procurement demands ISO 13485-certified sterile products with documented biocompatibility. Hemorrhage control and airway management specifications filter supplier qualification.
- Home Care:Chronic wound management and post-surgical self-treatment drive recurring demand for advanced dressings. Aging population demographics in eastern provinces are expanding this segment's addressable base.
- Workplace Safety:Revised national occupational health mandates intensify first aid kit requirements across manufacturing and construction sectors.
- Outdoor Activities:Adventure tourism and professional expedition markets drive portable, lightweight kit configurations with extended shelf-life specifications.
Emergency care commands the procurement volume base while home care expands most quickly on demographic and self-treatment trend convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across China's first aid market. Tertiary hospital networks in coastal megacities prioritize certification grade and supply security over unit cost, while inland procurement authorities face tighter budget constraints that favor domestic substitution.
Shanghai
Shanghai's trauma center expansion drives institutional demand for ISO 13485-certified sterile dressings and hemorrhage control products. NMPA Class II registration timelines here compress through priority review pathways for manufacturers with established quality management systems. The Yangpu and Pudong medical device clusters concentrate sterile barrier manufacturing and biocompatibility testing capacity.
Beijing
Beijing's hospital network consolidation concentrates procurement authority through municipal health commission digital platforms. GB standard compliance for sterile products faces stricter municipal interpretation than national baselines, filtering supplier pools toward established registrants. The Zhongguancun life science corridor anchors UDI serialization infrastructure and regulatory consulting services.
Guangdong
Guangdong's manufacturing base generates occupational safety kit demand across electronics and automotive assembly sectors. Provincial workplace health mandates under revised national standards intensify first aid compliance requirements. The Pearl River Delta logistics hub enables cold-chain distribution of sterile products to tier-2 city hospital networks.
Jiangsu
Jiangsu's textile heritage supports medical-grade cotton processing and gauze production clusters. NMPA registration reforms accelerate domestic manufacturer qualification for institutional tenders previously reserved for imports. The Suzhou industrial park concentrates wound dressing contract manufacturing and sterilization services.
Sichuan
Sichuan's western China position creates distribution challenges that favor suppliers with provincial warehousing infrastructure. Centralized procurement pilots in Chengdu health networks test volume-based pricing mechanisms for standard first aid consumables. The Chengdu-Chongqing economic corridor expands trauma center capacity with procurement standards converging toward coastal benchmarks.
China First Aid Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across China's first aid sector. Multinational suppliers with established NMPA registrations dominate advanced wound care segments requiring hydrogel and foam technologies, while vertically integrated domestic manufacturers capture volume share in commodity gauze and adhesive bandage categories. The competitive structure stratifies into three tiers: premium importers with biocompatibility dossiers, mid-scale domestic specialists with accelerated registration capabilities, and regional fabricators serving price-sensitive institutional tenders. Dominant competitive moves include backward integration into medical-grade cotton sourcing and strategic partnerships with provincial distributors to secure centralized procurement platform access.
Among the named suppliers, Johnson & Johnson occupies a position exemplifying premium brand strength in adhesive bandages and advanced wound dressings, while Winner Medical Group Co. represents the vertically integrated domestic archetype with captive cotton sourcing through sterilized finished goods. Yunnan Baiyao anchors the traditional Chinese medicine positioning segment within institutional procurement frameworks.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Winner Medical Group Co. |
| Yunnan Baiyao |
| 3M Company |
| Hangzhou Aosi Healthcare Co., Ltd. |
| Suzhou Sunmed Co., Ltd. |
| Changzhou Recoo Healthcare Co., Ltd. |
| Hangzhou Bever Medical Devices Co., Ltd. |
| Medtronic (China) Investment Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Scale economies in sterilization infrastructure anchor cost floors across China's first aid sector, concentrating production capacity in Jiangsu and Guangdong provinces where gamma and ethylene oxide facilities achieve utilization rates above regional peers. This geographic clustering shapes both supplier pricing power and procurement negotiation leverage for hospital networks.
Pricing Analysis
NMPA Class II certification dictates the pricing tier structure across sterile product categories. Three-tier pricing structure across premium, standard, and economy levels separates imported hydrogel dressings from domestic silver-ion alternatives and commodity gauze. Price differentiation hinges on biocompatibility dossier completeness and ISO 13485 audit history. Cost compression in standard-tier adhesive bandages is intensifying because provincial centralized procurement platforms force volume commitments over premium positioning. Household consumers through JD Health exhibit highest price sensitivity; tertiary hospital trauma centers demonstrate lowest sensitivity due to supply security priorities.
Supply Chain Analysis
Inbound logistics costs from Port of Shanghai container congestion and Yangtze River delta warehousing premiums shape total delivered cost for medical-grade cotton imports. Raw material supply concentrates in Xinjiang for domestic cotton fiber, the United States for long-staple medical grades, and India for intermediate processed gauze. Finished goods production draws from Jiangsu dressing manufacturers, Guangdong sterilization contractors, and Zhejiang packaging suppliers. Single-source vulnerability persists in gamma sterilization capacity where three regional providers serve national demand. Distribution runs through provincial pharmaceutical wholesale hierarchies with hospital-affiliated pharmacies retaining replenishment authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NMPA UDI implementation is compressing traditional distributor relationships while accelerating direct manufacturer-to-hospital platform integration, creating structural disruption for mid-scale suppliers lacking serialization infrastructure.
For Market Incumbents: Compound certification advantages by accelerating NMPA Class III pathway investments before regulatory thresholds tighten. Defend against domestic antimicrobial dressing substitution by locking multi-year trauma center supply agreements. Prioritize backward integration into medical-grade cotton processing to offset raw material volatility. For New Entrants and Emerging Players: Differentiate on biodegradable sterile barrier materials ahead of MEE packaging mandates. Target Chengdu-Chongqing corridor tier-2 hospital networks where procurement standards converge toward coastal benchmarks but supplier competition remains thinner. Bypass traditional pharmaceutical wholesale through Tmall Pharmacy flagship stores with UDI-compliant serialization. For Investors and Strategic Acquirers: Domestic sterilization service providers with captive NMPA audit relationships represent priority acquisition targets. Long-term viability rests on regulatory compliance automation capabilities rather than commodity volume scale. Watch for provincial centralized procurement platform expansions as volume allocation inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class II Registration Acceleration | Compresses market access timelines for domestic sterile product manufacturers against import-dependent rivals. |
| Backward Integration into Cotton Processing | Captures margin compression from Xinjiang fiber volatility and medical-grade import dependency. |
| UDI Serialization Infrastructure Deployment | Enables direct hospital platform integration bypassing traditional pharmaceutical distribution markups. |
| Biodegradable Packaging Transition | Creates first-mover positioning under MEE dual carbon pressure on single-use sterile barriers. |
| Central and Western Province Distribution Buildout | Secures volume allocation in tier-2 city hospital networks before procurement consolidation accelerates. |
Study Parameters
The analysis maps sterile dressings, adhesive bandages, antiseptic solutions, and first aid kit configurations, each validated through hospital procurement managers, biomedical engineers, GPO contracts specialists, and NMPA regulatory consultants. Primary fieldwork combined structured interviews with secondary triangulation against NMPA registration databases, provincial tender platform disclosures, hospital procurement records, and customs trade statistics. Bottom-up product-level volume estimates and top-down sectoral expenditure benchmarks were reconciled through iterative stakeholder feedback.
Consistency checks validated projections against external hospital infrastructure expansion plans and NMPA regulatory timeline announcements. The analytical framework models product type, end-user facility tier, distribution channel, and application across the projection horizon. CAGRs were derived from segment-level demand elasticity coefficients and supply capacity expansion schedules. Forecast inputs incorporated trauma center bed capacity additions, occupational safety mandate enforcement intensity, and e-commerce penetration curves for medical device categories.
Decision-makers should treat outputs as directional under assumptions of continued NMPA classification reform implementation and stable cotton fiber import policies; material deviation would warrant model refresh. Specific risks include provincial procurement platform pricing convergence acceleration and biocompatibility testing laboratory capacity bottlenecks extending validation timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
Patient Transport Services Market
Emergency Medical Services
First Aid Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
Chest Compressors Market
Emergency Medical Services
Europe Air Ambulance Services Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
Global Ambulance Market
Emergency Medical Services
Air Ambulance Market
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
US Urgent Care Centers Market
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
Europe Ambulance Services Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
Cardiopulmonary Resuscitation Market