
 Global Fiber Reinforced Composites Market | 2026-2036
Global Fiber Reinforced Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fiber Reinforced Composites Market Intelligence
A shift from outsourced component fabrication to in-house composite manufacturing is repositioning the value chain for original equipment manufacturers. Toray Industries, Inc. leverages its leadership in high-modulus carbon fiber to serve the aerospace sector. Owens Corning sustains a large-scale production footprint for glass fiber composites used in automotive and building materials. Hexcel Corporation specializes in advanced composite materials, including honeycomb structures, for defense and commercial aircraft applications.
Fiber reinforced composites are engineered materials combining a reinforcement fiber with a polymer, ceramic, or metal matrix to achieve a high strength-to-weight ratio. Their primary purpose is replacing traditional materials like steel, with performance dictated by fiber type and manufacturing processes like pultrusion. Glass fiber variants command the largest market volume due to cost-effectiveness, while carbon fiber composites lead in performance and value. The aerospace industry drives demand for high-specification thermoset resin systems.
Regulatory frameworks like the FAA's airworthiness standards and China's GB standards for automotive parts dictate material qualification and testing protocols. Concurrently, sustainability mandates such as the EU Green Deal create pressure for improved composite recyclability and end-of-life management. Stakeholders must therefore navigate the complex trade-off between deploying higher-performance materials and addressing lifecycle and cost considerations.
Market Dynamics
The fundamental dynamic shaping the fiber reinforced composites market is the tension between extreme performance requirements and escalating lifecycle mandates. Demand from aerospace and wind energy for higher strength-to-weight ratios pulls development towards advanced, costly materials, while automotive and consumer sectors push for cost reduction and sustainability solutions like recyclability.
Growth Catalysts
- Vehicle Lightweighting Mandates:Regulatory frameworks such as the EU Green Deal and fuel efficiency standards in the United States and China compel automotive OEMs to adopt lighter materials like glass and carbon fiber composites to reduce vehicle mass and emissions.
- Renewable Energy Expansion:The wind energy sector's pursuit of higher power generation efficiency requires longer and more durable turbine blades, driving significant volume consumption of glass and carbon fiber composites.
- Aerospace Modernization:Next-generation commercial and defense aircraft programs increasingly specify composites for primary structures like fuselages and wings to improve fuel efficiency and extend operational range.
Market Restraints
- High Material and Processing Costs:The production cost of high-performance fibers, particularly aerospace-grade carbon fiber, and the capital-intensive nature of manufacturing processes like autoclave curing limit adoption in cost-sensitive industries.
- Recycling and End-of-Life Challenges:The difficulty in separating fibers from the matrix in thermoset composites creates significant end-of-life waste management and environmental concerns, hindering wider market acceptance.
- Lengthy Qualification Cycles:Stringent material qualification and airworthiness certification protocols from bodies like the FAA and EASA for aerospace applications create long lead times and high development costs, slowing innovation deployment.
Strategic Opportunities
- Thermoplastic Composites:The development of weldable, recyclable thermoplastic composites presents an opportunity to penetrate high-volume automotive markets by offering faster production cycle times compared to traditional thermosets.
- Industrial Automation:Investing in automated manufacturing technologies such as automated fiber placement (AFP) and high-speed pultrusion can lower production costs and improve part consistency, opening new industrial applications.
- Bio-Based Composites:Formulating composites with natural fibers like flax or hemp and bio-based resins provides a path to meet sustainability targets set by regulations like the EU's Circular Economy Action Plan.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of technicians and engineers with expertise in composite design, lay-up, and advanced repair techniques constrains production capacity and quality control across the industry.
- Process Standardization Gaps:The absence of universally accepted testing protocols and material data standards, despite efforts by bodies like ISO, complicates material selection and supply chain management for global OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fiber Reinforced Composites Market |
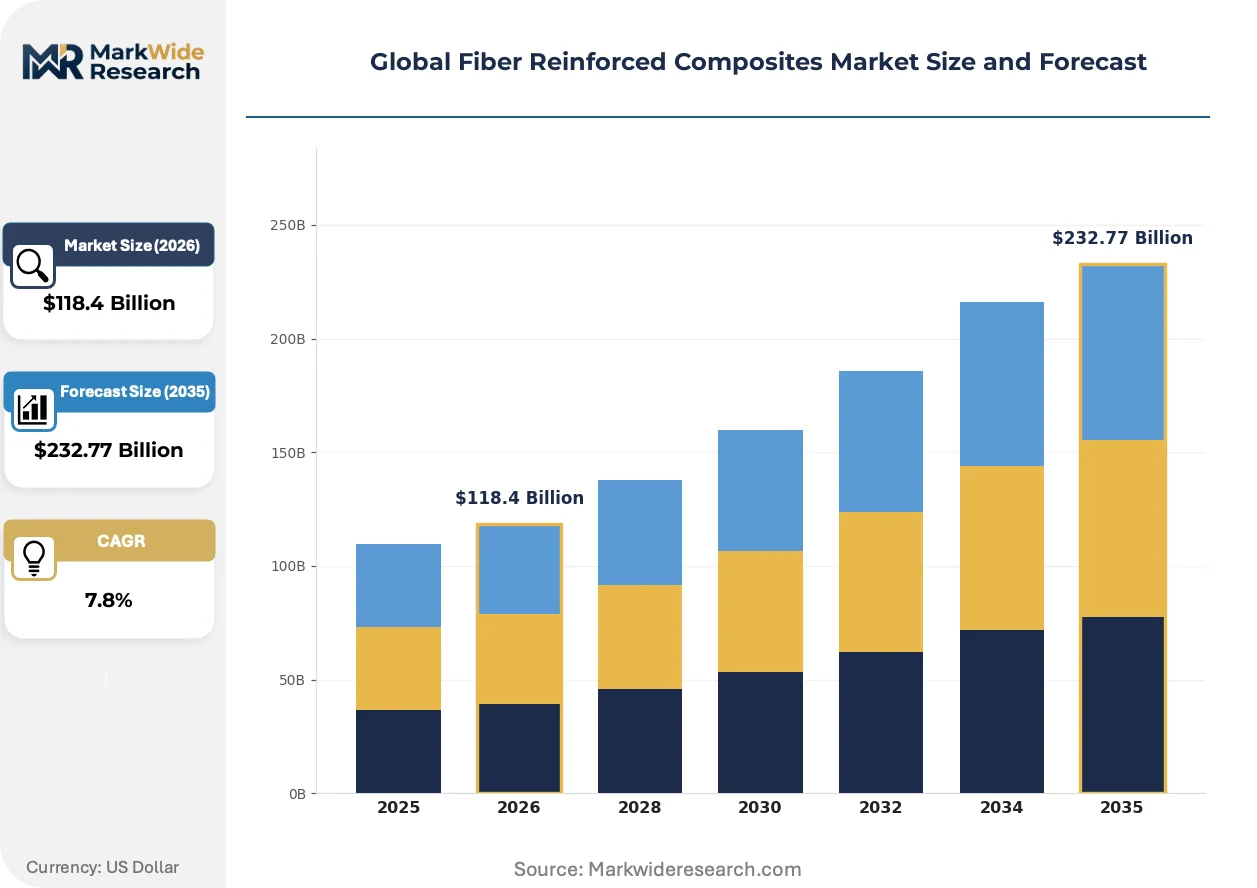
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $232.77 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Reinforcement Fiber Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Basalt Fiber Matrix Material: Thermoset Resin, Thermoplastic Resin, Ceramic Matrix, Metal Matrix End Use Industry: Aerospace, Wind Energy, Marine, Sporting Goods Manufacturing Process: Hand Lay-Up, Resin Transfer Molding, Pultrusion, Compression Molding |
| Companies Covered | Teijin Limited, Mitsubishi Chemical Holdings Corporation, Toray Industries, Inc., Jushi Group Co., Ltd., Owens Corning, Hexcel Corporation, SGL Carbon, DuPont de Nemours, Inc., Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fiber Reinforced Composites Market Strategic Shifts & Innovations
Industrialization and digitalization are transforming composite manufacturing from a specialized, labor-intensive process into a more automated, scalable, and data-driven operation. This shift is critical for meeting demand from mass-market applications and improving cost-competitiveness against traditional materials.
Automated Fiber Placement (AFP) is a robotic process that precisely lays down individual composite tows to create complex structures. The aerospace and defense sectors are the primary adopters for fabricating large components like aircraft fuselages. This advanced manufacturing technology is converging with digital twin software, allowing engineers to simulate and optimize part performance and manufacturability before committing to physical production.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is formalizing environmental disclosure requirements. This regulation forces composite manufacturers and their customers to quantify and report on lifecycle impacts, including raw material sourcing and end-of-life management. The thermoset composites segment, particularly materials using epoxy resins, is most affected, accelerating research into chemical recycling and bio-derived resin systems.
Original equipment manufacturers are altering their supply chain strategies by establishing in-house composite production capabilities rather than outsourcing component fabrication. This change disrupts the traditional tiered supplier model, giving OEMs direct control over proprietary manufacturing processes and material specifications. This trend is most prominent within Germany's automotive sector and among US-based aerospace primes seeking to secure their supply of critical airframe and engine components.
Global Fiber Reinforced Composites Market Segmentation
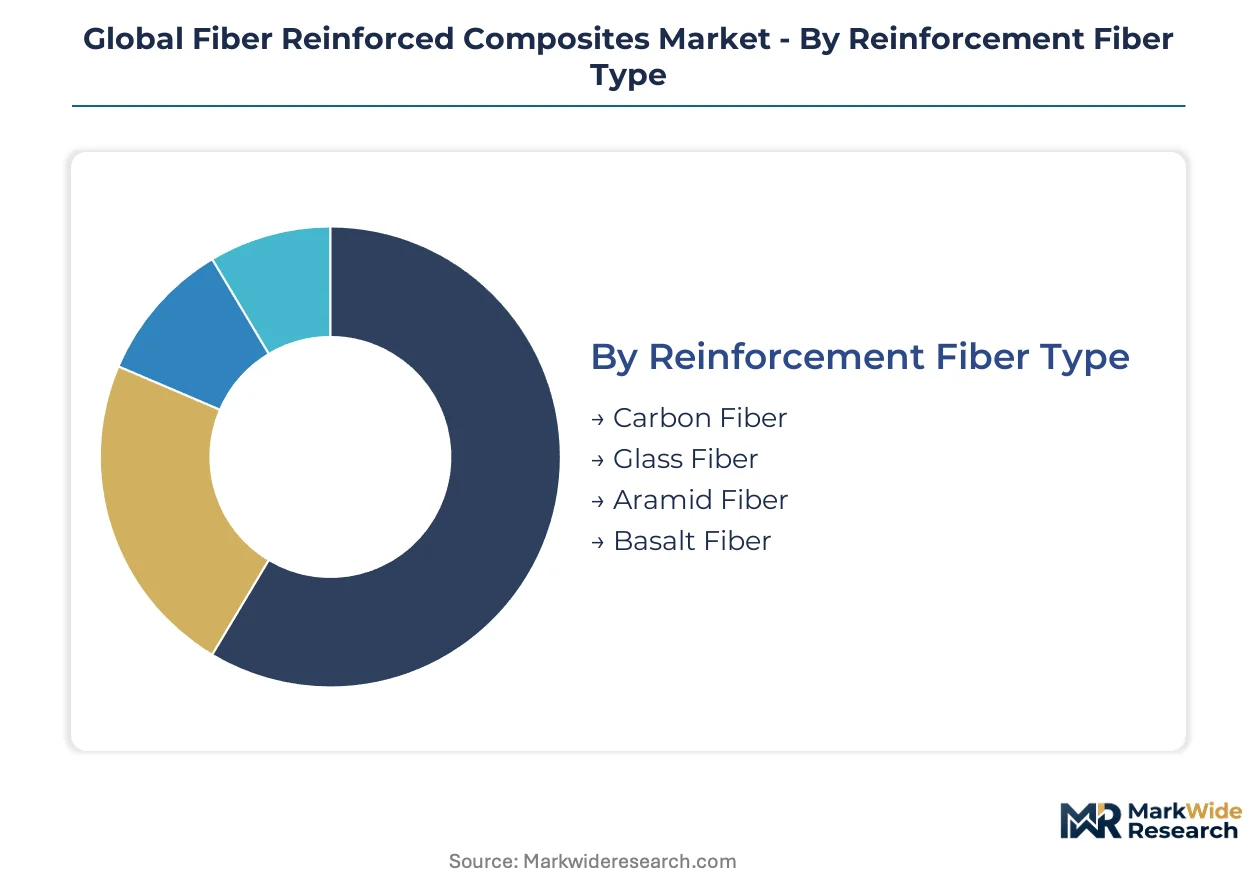
The global fiber reinforced composites market segmentation provides a granular view of material choices, processing techniques, and end-user applications. This detailed breakdown helps stakeholders understand the specific value drivers and technological requirements across diverse industry verticals. Analyzing these segments reveals areas of concentrated demand and emerging opportunities for material innovation.
Reinforcement Fiber Type:
The supply of reinforcement fibers is concentrating around specific material properties and cost structures, influencing composite market accessibility.
- Glass Fiber:These cost-effective fibers, often made from silica, alumina, and calcium oxide, provide good strength-to-weight ratios and chemical resistance. Demand for glass fiber composites is significant in the wind energy sector for manufacturing large turbine blades, and in the automotive industry for lightweight structural components, especially in China.
- Carbon Fiber:Characterized by exceptional strength, stiffness, and low density, carbon fibers are produced through the pyrolysis of organic precursors like polyacrylonitrile. The aerospace industry drives demand for high-modulus carbon fiber in primary aircraft structures, improving fuel efficiency for commercial and defense aircraft programs.
- Aramid Fiber:Known for their high tensile strength and impact resistance, aramid fibers find applications in ballistic protection and pressure vessels.
- Basalt Fiber:Produced from basalt rock, these fibers offer good thermal stability and corrosion resistance, suitable for infrastructure and construction.
Glass Fiber absorbs the bulk of installed capacity; Carbon Fiber is expanding most quickly.
Matrix Material:
Matrix material selection directly correlates with the required performance characteristics and application environment of the final composite part.
- Thermoset Resin:These resins, including epoxy, polyester, and vinyl ester, cure irreversibly to form a rigid, cross-linked polymer network, offering high strength and thermal stability. The aerospace industry extensively uses thermoset resins for their structural integrity in fuselages and wings, often requiring stringent FAA qualification.
- Thermoplastic Resin:These polymers, such as polypropylene, polyamide, and PEEK, can be repeatedly melted and reshaped, enabling faster processing and recyclability. The automotive sector explores thermoplastic composites for high-volume production of lightweight components to meet EU Green Deal emission targets.
- Ceramic Matrix:Composites using ceramic matrices offer extreme temperature resistance and high stiffness, crucial for jet engine components and thermal protection systems.
- Metal Matrix:These composites combine a metallic matrix with high-performance fibers, providing enhanced strength and wear resistance for demanding industrial applications.
Thermoset Resin dominates high-performance applications; Thermoplastic Resin shows the steepest expansion trajectory.
End Use Industry:
Demand volume from various end-use industries dictates the scale and material specifications for fiber reinforced composites.
- Aerospace:This sector utilizes advanced composites for primary and secondary structures in commercial and military aircraft, prioritizing lightweighting and extended operational life. Next-generation aircraft designs increasingly specify composite materials to improve fuel efficiency and reduce maintenance.
- Wind Energy:The renewable energy sector consumes large volumes of fiber composites for constructing longer and more efficient wind turbine blades. The global push for clean energy drives continuous innovation in composite materials for this application.
- Marine:Composites offer corrosion resistance and lightweight properties for boat hulls, decks, and other marine structures, improving vessel performance.
- Sporting Goods:High-performance composites enhance equipment such as bicycles, tennis rackets, and golf clubs, providing strength and reduced weight.
Aerospace and Wind Energy collectively drive significant composite consumption; Marine applications are gaining share fastest.
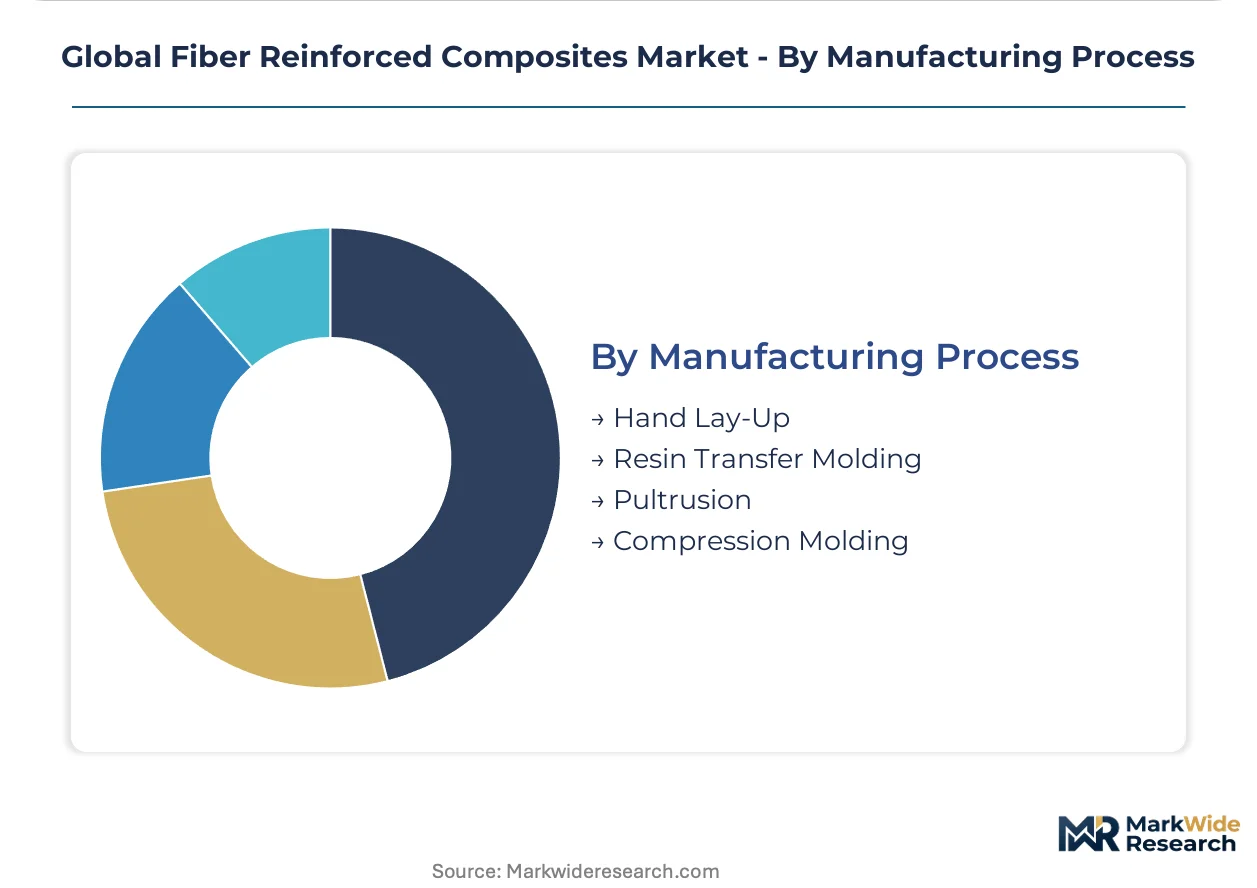
Manufacturing Process:
Manufacturing process efficiency and associated capital expenditure significantly influence the cost-effectiveness and scalability of composite part production.
- Pultrusion:This continuous manufacturing process pulls fiber reinforcements through a resin bath and heated die, producing constant cross-section profiles. Pultrusion is critical for infrastructure applications and window frames, offering high production rates and consistent quality.
- Resin Transfer Molding:RTM involves injecting liquid resin into a closed mold containing dry fiber preforms, allowing for complex geometries and good surface finish. This process is used for automotive parts and aerospace components requiring precise dimensions.
- Hand Lay-Up:A manual process where layers of fiber are placed in a mold and impregnated with resin, suitable for low-volume, large-scale structures like boat hulls.
- Compression Molding:This process uses heat and pressure to form composites from pre-impregnated materials or sheet molding compounds, ideal for high-volume automotive parts.
Pultrusion offers high throughput for continuous profiles; automated Compression Molding is climbing the fastest in adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's robust manufacturing base for glass fiber composites anchors significant regional demand, particularly for automotive and wind energy applications. The global market for fiber reinforced composites exhibits diverse growth patterns influenced by regional industrial policies and technological advancements. Regulatory frameworks across key economies accelerate material substitution, driving both volume and value expansion in specific end-use sectors.
China
Automotive lightweighting and renewable energy expansion drive substantial demand for glass and carbon fiber composites in China. The country's GB standards for automotive parts compel manufacturers to adopt advanced materials for vehicle components. Manufacturing clusters in the Yangtze River Delta actively innovate in composite production techniques for electric vehicles and wind turbine blades.
United States
Aerospace modernization and stringent fuel efficiency standards mandate the use of high-performance composites across the United States. FAA airworthiness standards dictate rigorous material qualification processes for commercial and defense aircraft. Aerospace primes in the Seattle area and automotive OEMs in Detroit are increasingly integrating composite manufacturing capabilities.
Germany
The German automotive sector's push for lightweighting and the EU Green Deal's sustainability targets fuel composite demand. The Corporate Sustainability Reporting Directive (CSRD) influences material selection towards more recyclable options. Advanced manufacturing hubs in Bavaria and Baden-Württemberg lead in thermoplastic composite development and automated production for high-volume applications.
Japan
High-modulus carbon fiber demand for aerospace and specialized industrial applications characterizes the Japanese market. METI initiatives support advanced material research and development, fostering innovation in composite technologies. Companies in the Tokyo region specialize in precision composite manufacturing and advanced material science for global markets.
France
France's strong aerospace and defense industries are major consumers of advanced fiber reinforced composites. EASA certification protocols ensure the highest safety and performance standards for aircraft components. The Toulouse aerospace cluster drives significant material consumption for next-generation commercial aircraft programs like Airbus.
Global Fiber Reinforced Composites Market Key Industry Players
In-house manufacturing integration dominates the current competitive landscape, as original equipment manufacturers seek greater control over critical material supply chains. The market structure features a tiered system, ranging from raw material suppliers to specialized composite part fabricators. Strategic archetypes include large-scale commodity producers, high-performance material specialists, and integrated component manufacturers. Dominant competitive moves involve capacity expansion, particularly in automated manufacturing, and strategic partnerships for technology development.
Specialists in high-performance materials like Toray Industries, Inc. and Hexcel Corporation serve demanding sectors such as aerospace with advanced carbon fiber and honeycomb structures. Owens Corning exemplifies a large-scale producer, sustaining a significant production footprint for glass fiber composites used in automotive and building materials. These companies anchor specific segments by leveraging proprietary material science and extensive manufacturing capabilities across diverse global markets.
| Leading Market Players |
|---|
| Teijin Limited |
| Mitsubishi Chemical Holdings Corporation |
| Toray Industries, Inc. |
| Jushi Group Co., Ltd. |
| Owens Corning |
| Hexcel Corporation |
| SGL Carbon |
| DuPont de Nemours, Inc. |
| Solvay |
| Others |
Cost & Logistics Intelligence
Global carbon fiber precursor prices, driven by energy costs, cascade through the value chain, directly influencing the final pricing tiers of high-performance composite materials. This cost structure impacts material selection across diverse end-use applications.
Pricing Analysis
Warranty and technical support bundling significantly differentiates pricing for advanced fiber reinforced composites, especially in aerospace. Contract-based long-term offtake agreements dominate for high-performance applications with stringent material qualification. Price differentiation stems from certification levels, such as FAA approval, and the volume scale of procurement. Pricing pressure intensifies in automotive and construction due to lightweighting mandates and competition. Aerospace buyers exhibit the lowest price sensitivity, while mass-market applications are highly cost-driven.
Supply Chain Analysis
Polyacrylonitrile (PAN) supply for carbon fiber production primarily rests on a few specialized producers in Japan and the United States. Epoxy resin and glass fiber raw material sourcing often draws from China and Europe. Single-source vulnerability for aerospace-grade carbon fiber represents a significant supply chain risk. Distribution typically runs through direct OEM sales for large projects and specialized distributors for smaller industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiber reinforced composites market is a consolidation play, with high capital intensity in advanced manufacturing techniques forcing out smaller, less capitalized players.
For Market Incumbents: Cement market leadership by deepening vertical integration into critical raw material production, such as carbon fiber precursors. Invest heavily in automated manufacturing technologies like Automated Fiber Placement to reduce costs and increase throughput, countering pressure from emerging Chinese competitors. Pursue strategic partnerships for advanced thermoset resin development, securing long-term supply for aerospace programs.
For New Entrants and Emerging Players: Begin with niche applications where sustainability or specific performance attributes create a market opening. Target the bio-based composites segment for construction and consumer goods, leveraging natural fibers like flax for new product development. Penetrate high-volume automotive markets by offering cost-effective thermoplastic composite solutions with faster cycle times.
For Investors and Strategic Acquirers: Distressed-cycle entries favor large material science conglomerates in Europe, driven by Corporate Sustainability Reporting Directive compliance pressures. The long-term viability of the composites market is robust, fueled by aerospace and wind energy modernization programs. Target specialty material firms with proprietary recycling technologies or advanced automated manufacturing capabilities. Watch for breakthroughs in cost-effective chemical recycling of thermosets as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Automated Manufacturing | Increases production scale for high-volume applications and lowers unit costs for automotive OEMs. |
| Backward Integration into Precursor Production | Secures critical raw material supply for carbon fiber and enhances cost control for aerospace primes. |
| Investment in Thermoplastic Composite R&D | Develops recyclable materials with faster processing, meeting EU Green Deal targets for automotive. |
| Strategic Partnership for Recycling Technology | Addresses end-of-life challenges for thermosets and improves sustainability reporting for customers. |
| Certification for Bio-Based Materials | Unlocks new market segments in construction and consumer goods, driven by environmental mandates. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a comprehensive market baseline. Primary research involved in-depth interviews with composite engineers, procurement specialists at original equipment manufacturers, R&D directors, and sustainability officers. This approach ensured bottom-up market sizing was validated against top-down industry reports.
Granularity for the market model involved segmenting by reinforcement fiber type, matrix material, end-use industry, and manufacturing process across the analysis window. The analytical framework integrated both demand-side drivers and supply-side constraints. Compound Annual Growth Rates were derived from historical trends and projected future adoption rates. Key forecast inputs included global vehicle production forecasts and wind energy capacity expansion plans.
Underlying measurement precision varies by segment; glass fiber and aerospace composites carry tighter precision than others due to established reporting. Forecasts reflect assumptions regarding future regulatory frameworks like the EU Green Deal and technological advancements in recycling. Geopolitical trade tensions and raw material supply disruptions represent key risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
North America Glass Fiber Reinforced Gypsum Market
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market
Fibers
Fiberglass Sunscreen Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
Thermoformed Fiber Market
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
PAN-Based Carbon Fibers Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
Fiberglass Mat Market
Fibers
Sisal Market
Fibers
Europe Carbon Fiber Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
Acoustical Fiber Board Market
Fibers
Global Metal Fiber Market