
 Pitch-Based Carbon Fiber Market | 2026-2036
Pitch-Based Carbon Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Pitch-Based Carbon Fiber Market Intelligence
Capital-intensity divergence between precursor synthesis and downstream composite fabrication is bifurcating competitive structures in pitch-based carbon fiber. Mitsubishi Chemical Carbon Fiber and Composites, Inc. leverages fully integrated mesophase pitch production to control feedstock quality and cost position. Nippon Graphite Fiber Co., Ltd. anchors its position through specialized high-modulus fiber grades for satellite and defense platforms. Toray Industries, Inc. competes across both PAN-based and pitch-based portfolios, using scale advantages in carbonization equipment to sustain margin pools.
Pitch-based carbon fiber is manufactured from petroleum or coal-tar derived mesophase pitch through melt-spinning, oxidative stabilization, and carbonization at temperatures exceeding 2000°C, yielding ultra-high modulus fibers with elastic modulus above 500 GPa for structural applications demanding extreme stiffness-to-weight ratios. Continuous fiber dominates aerospace qualification programs due to laminate predictability and established design allowables, while prepreg formats capture premium margins in satellite bus manufacturing where out-of-autoclave processing reduces cycle times. Discontinuous fiber segments are gaining traction in automotive brake systems and industrial heat shields where chopped fiber compounds enable complex geometries at lower conversion costs.
Japan's METI export control revisions and the US Bureau of Industry and Security licensing requirements are reshaping cross-border material flows for pitch-based carbon fiber with modulus thresholds above 350 GPa. REACH registration obligations in Europe and China's GB standards for composite structural certification are adding compliance layers that favor vertically integrated producers with in-house testing and certification capabilities. Stakeholders must monitor evolving national security classifications for advanced carbon fibers and assess captive precursor investments before qualification timelines lock in supplier relationships.
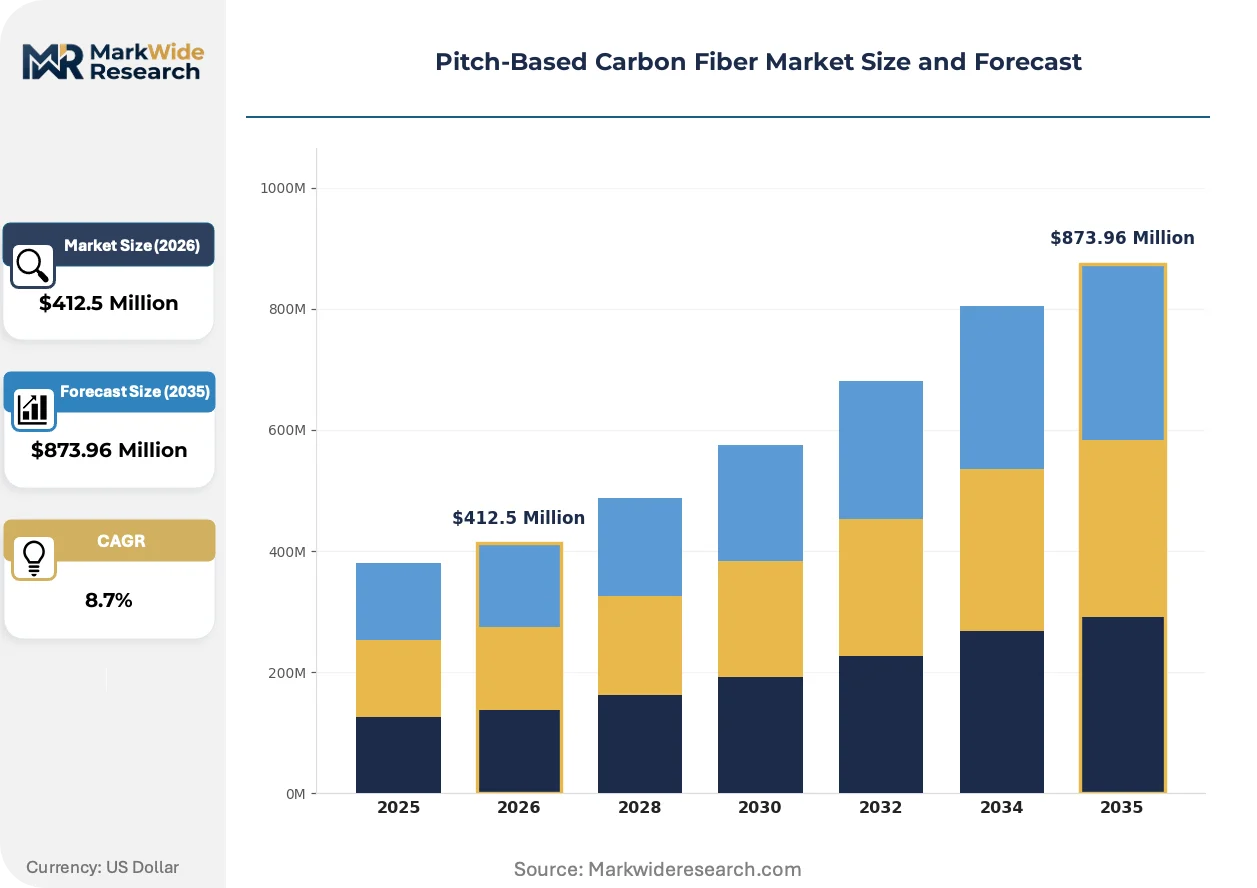
Market Dynamics
Japan's METI export controls on high-modulus pitch-based carbon fiber are fragmenting supply chains and forcing aerospace OEMs to qualify secondary suppliers or build captive precursor capacity, fundamentally restructuring competitive access to critical structural materials.
Growth Catalysts
- Wind turbine blade scaling:China's offshore wind developers are qualifying pitch-based fiber for 15MW+ turbine platforms requiring extreme stiffness-to-weight ratios for 120-meter blade spans.
- US Bureau of Industry and Security licensing:National security classifications for modulus thresholds above 350 GPa are accelerating domestic qualification programs among US aerospace contractors.
- Out-of-autoclave prepreg formats:Satellite bus manufacturers are adopting these materials to compress manufacturing cycle times for constellation deployment schedules.
Market Restraints
- Mesophase pitch feedstock concentration:Petroleum-derived precursor supply concentrates among Japanese and US petrochemical complexes, exposing buyers to single-source risk.
- Carbonization energy intensity:Process temperatures exceeding 2000°C require specialized furnace infrastructure with 18-24 month lead times for capacity expansion.
- REACH registration burdens:ECHA compliance obligations for novel fiber grades are extending European market entry timelines for non-integrated producers.
Strategic Opportunities
- Automotive brake system penetration:Chopped pitch-based fiber compounds are displacing conventional ceramic matrices in high-performance EV braking assemblies.
- India's PLI scheme for advanced materials:Domestic carbon fiber manufacturing incentives are creating qualification pathways for pitch-based suppliers in aerospace ancillary supply chains.
- Digital twin integration:Convergence of predictive modeling with composite qualification protocols is compressing OEM approval cycles for new fiber grades.
Industry Challenges
- Carbonization furnace operator scarcity:Specialized technicians capable of managing 2000°C+ thermal processing are concentrated among Japanese and US incumbent workforces.
- Multi-tier certification timelines:FAA and EASA structural material qualification protocols require 3-5 year validation cycles that lock in supplier relationships before commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pitch-Based Carbon Fiber Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Fiber, Discontinuous Fiber, Fabric, Prepreg Application: Aerospace, Automotive, Wind Energy, Sporting Goods End User: Manufacturers, Contractors, OEMs, Research Institutions Technology: Pultrusion, Filament Winding, Layup, Resin Transfer Molding |
| Companies Covered | Mitsubishi Chemical Carbon Fiber and Composites, Inc., Nippon Graphite Fiber Co., Ltd., Toray Industries, Inc., Teijin Limited, Hexcel Corporation, SGL Carbon, Kureha Corporation, Syensqo, Tasuns Composite Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pitch-Based Carbon Fiber Market Strategic Shifts & Innovations
Active material substitution and regulatory fragmentation are compressing traditional qualification paradigms while opening adjacent application spaces for pitch-based fiber formats previously excluded from mainstream composite fabrication.
Plasma-assisted oxidative stabilization is decomposing the bottleneck of conventional thermal processing for ultra-high modulus fiber production. Aerospace tier-one suppliers in Japan and the US are piloting this technology to halve stabilization cycle times. The process is decomposing capital intensity barriers that historically constrained entry by non-integrated competitors.
China's GB standards for composite structural certification are mandating traceable supply chain documentation for wind turbine blade materials. MIIT enforcement of these protocols is disqualifying uncertified imports from offshore platform projects. Domestic turbine OEMs are responding by qualifying local pitch-based fiber sources ahead of 2025 procurement windows.
Long-term offtake contracting is replacing spot purchasing for high-modulus fiber grades above 400 GPa. Satellite constellation operators are locking in 5-7 year supply agreements directly with precursor producers, bypassing traditional distributor networks. This pattern concentrates most visibly among US and European NewSpace manufacturers securing capacity for megaconstellation deployment phases.
Pitch-Based Carbon Fiber Market Segmentation
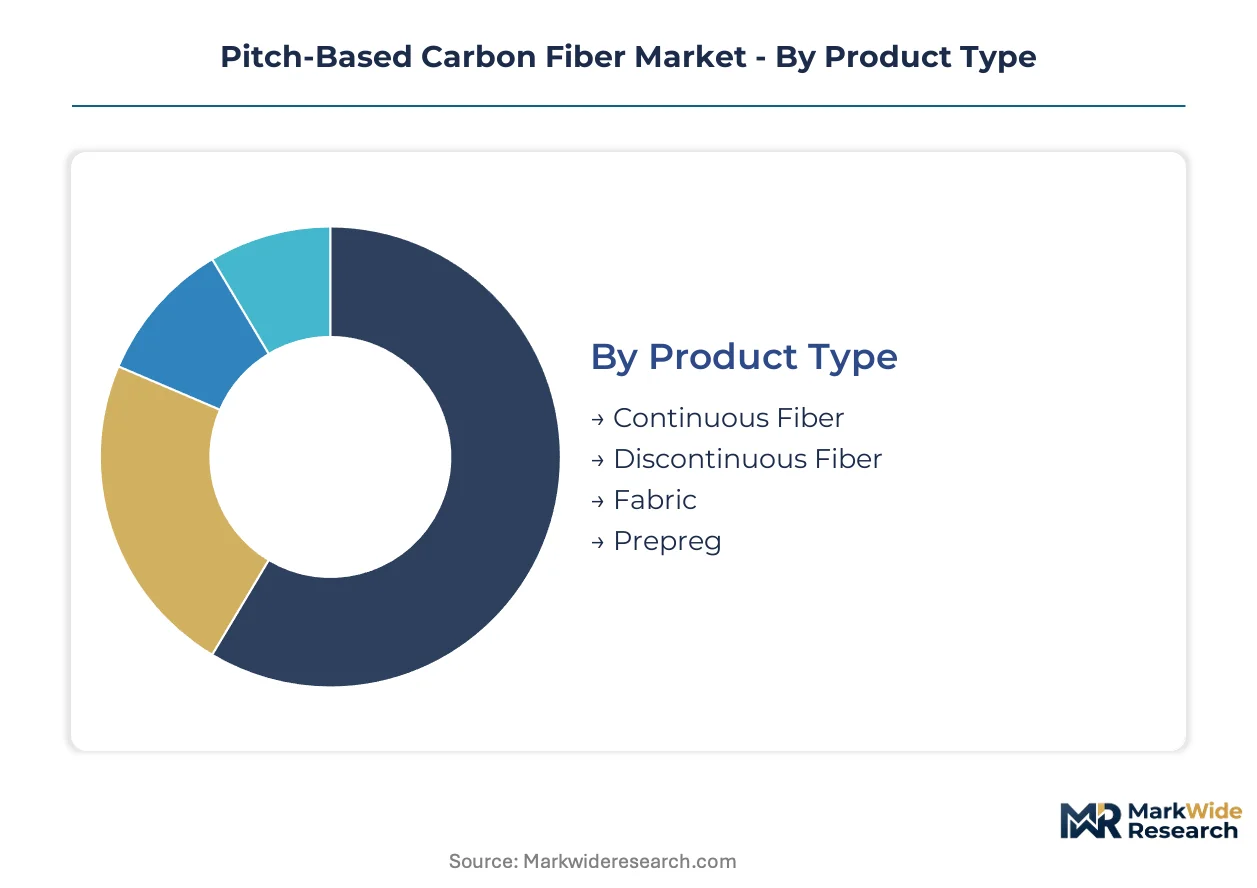
Pitch-based carbon fiber exhibits distinct performance profiles across product formats and conversion technologies, with modulus thresholds and processing economics determining competitive positioning in each segment. Understanding these structural divisions reveals where PAN-based alternatives exert substitution pressure and where pitch-based stiffness premiums command durable margins.
Product Type:
Continuous fiber faces the most acute substitution threat from high-modulus PAN variants in cost-sensitive aerospace applications, while discontinuous formats defend niche positions where chopped fiber compounds enable geometries impossible with continuous reinforcement.
- Continuous Fiber:Manufactured through melt-spinning of mesophase pitch followed by oxidative stabilization and carbonization above 2000°C, yielding elastic modulus exceeding 500 GPa. Satellite bus structures and commercial aircraft primary components in the US and Japan concentrate procurement, with FAA qualification protocols locking in supplier relationships before commercialization.
- Prepreg:Resin-impregnated fiber sheets processed via out-of-autoclave methods for constellation deployment schedules. Satellite manufacturers in Europe and North America are compressing cycle times through these formats, capturing premium margins in megaconstellation programs.
- Discontinuous Fiber:Chopped fiber compounds serving automotive brake systems and industrial heat shields where complex geometries outweigh stiffness optimization.
- Fabric:Woven textile forms for secondary structural applications and tooling fixtures where drapeability and handling convenience predominate over modulus maximization.
Continuous fiber anchors the volume base while prepreg gains share at the steepest rate.
Application:
Cost tier stratification separates aerospace qualification programs with decade-long validation cycles from emerging wind energy procurement where blade scaling demands extreme stiffness-to-weight ratios.
- Aerospace:Primary structures, satellite components, and defense platforms requiring modulus above 400 GPa. US aerospace contractors are accelerating domestic qualification programs under Bureau of Industry and Security licensing requirements for national security classified materials.
- Wind Energy:Offshore turbine blades exceeding 120-meter spans for 15MW+ platforms. China's wind developers are qualifying pitch-based fiber ahead of procurement windows, with MIIT enforcement of GB standards disqualifying uncertified imports.
- Automotive:High-performance braking assemblies and thermal management components where chopped fiber compounds displace conventional ceramic matrices.
- Sporting Goods:Premium bicycle frames and competitive equipment where modulus premiums command limited price tolerance compared to industrial applications.
Wind energy is expanding most quickly as blade scaling accelerates, while aerospace retains the highest margin concentration.
End User:
Customer type determines procurement sophistication, with OEMs leveraging long-term offtake contracting while research institutions pilot novel fiber grades ahead of qualification timelines.
- OEMs:Satellite constellation operators and aircraft manufacturers locking in 5-7 year supply agreements directly with precursor producers, bypassing traditional distributor networks for modulus grades above 400 GPa.
- Manufacturers:Composite fabricators serving tier-one aerospace and wind energy supply chains, managing carbonization furnace capacity with 18-24 month expansion lead times.
- Contractors:Installation and maintenance service providers for wind turbine and infrastructure projects with limited direct fiber procurement.
- Research Institutions:National laboratories and university programs piloting plasma-assisted oxidative stabilization and alternative precursor chemistries.
OEMs dominate procurement value while research institutions drive technology transfer most aggressively.
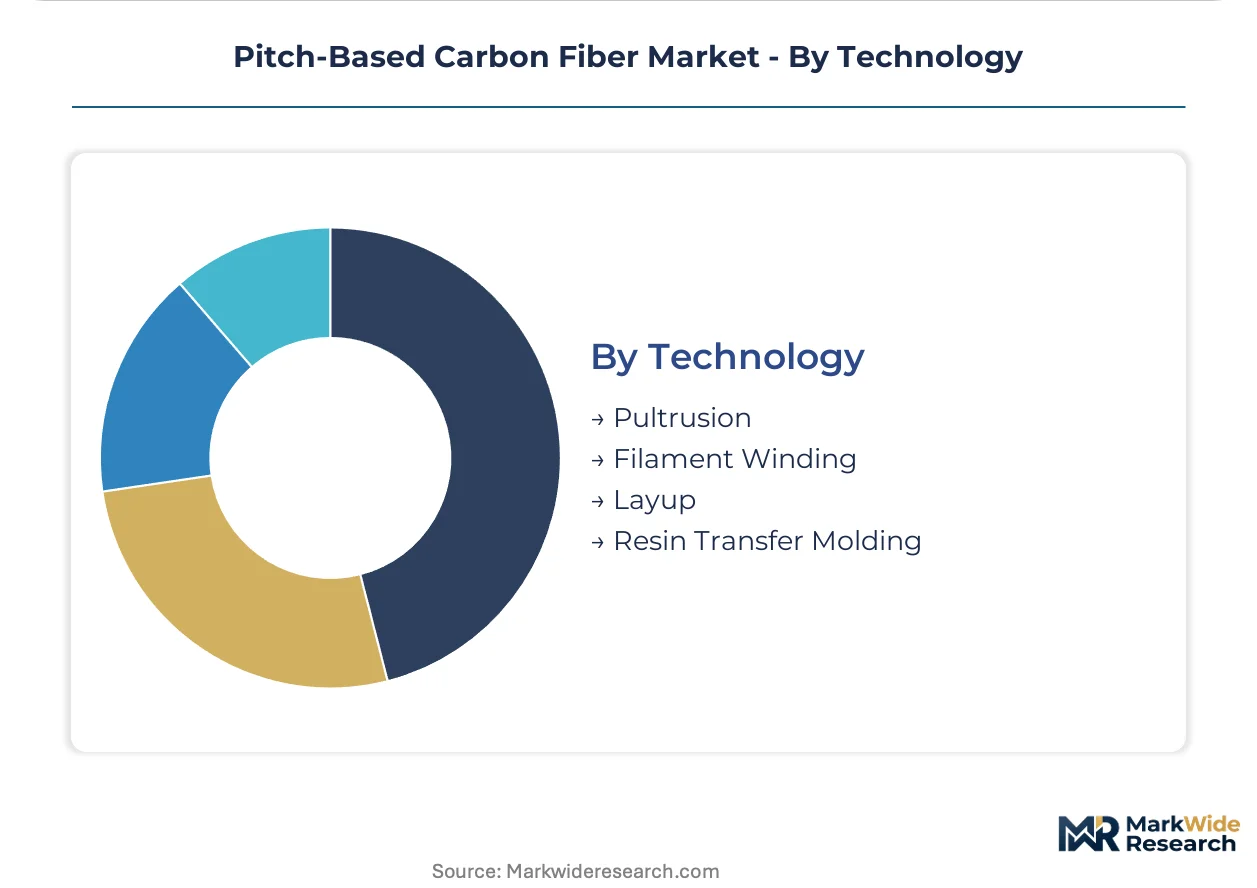
Technology:
Process maturity separates established aerospace qualification pathways from emerging manufacturing methods gaining traction in cost-sensitive segments.
- Layup:Manual or automated fiber placement for satellite bus manufacturing and aircraft primary structures, with established design allowables supporting laminate predictability.
- Filament Winding:Automated fiber deposition for pressure vessels and cylindrical structures, capturing volume in defense and energy storage applications.
- Pultrusion:Continuous profile manufacturing for structural beams and industrial components where straight fiber alignment maximizes stiffness efficiency.
- Resin Transfer Molding:Closed-mold infusion for complex geometries in automotive and industrial heat shields, enabling chopped fiber compound processing.
Layup retains the broadest qualification base while resin transfer molding climbs fastest in adjacent industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese supply chains where METI export controls restrict high-modulus fiber availability, while Chinese wind turbine OEMs leverage domestic qualification programs to compress procurement costs for offshore blade platforms.
United States
Boeing and SpaceX drive demand for satellite bus structures and commercial aircraft primary components. The Bureau of Industry and Security enforces licensing requirements for carbon fiber modulus thresholds above 350 GPa under national security frameworks. Huntsville, Alabama and Denver, Colorado host aerospace manufacturing clusters where domestic qualification programs are accelerating to reduce import dependency.
Japan
Mitsubishi and Toray anchor global supply of mesophase pitch precursors and ultra-high modulus fiber grades. METI tightened export controls in 2023, redirecting supply toward domestic aerospace and defense applications. Nagoya and Tokyo metropolitan areas concentrate carbonization furnace capacity and specialized technician workforces with 2000°C+ thermal processing expertise.
China
Goldwind and Ming Yang qualify pitch-based fiber for 15MW+ offshore turbine blades exceeding 120-meter spans. MIIT enforces GB standards for composite structural certification, disqualifying uncertified imports from procurement windows. Jiangsu and Guangdong provinces host turbine manufacturing clusters where domestic fiber sources are gaining qualification ahead of 2025 deployment schedules.
Germany
Airbus Defence and Space and satellite component suppliers source high-modulus fiber for European constellation programs. ECHA REACH registration obligations extend market entry timelines for non-integrated producers seeking European qualification. Munich and Bremen aerospace clusters manage multi-tier certification protocols through EASA structural material validation cycles.
South Korea
Hyundai Heavy Industries and domestic wind developers pilot pitch-based fiber for next-generation turbine platforms. The Ministry of Trade, Industry and Energy supports advanced materials manufacturing through industrial technology development programs. Busan-Ulsan and Daejeon-Sejong regions concentrate composite fabrication capacity serving aerospace ancillary supply chains.
Pitch-Based Carbon Fiber Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes in pitch-based carbon fiber, with integrated precursor producers commanding feedstock quality control while specialized fiber manufacturers defend niche modulus grades. The market structure concentrates among Japanese and US incumbents with captive mesophase pitch supply and established aerospace qualification histories. Three archetypes dominate: vertically integrated petrochemical-spinoff producers, specialized high-modulus fiber specialists, and diversified carbon fiber portfolio operators spanning both PAN-based and pitch-based categories. Capacity expansion and strategic partnerships represent the dominant competitive moves, with satellite constellation operators locking in long-term offtake agreements directly with precursor producers.
Within the integrated producer tier, Mitsubishi Chemical Carbon Fiber and Composites, Inc. exemplifies backward control over mesophase pitch synthesis, while Nippon Graphite Fiber Co., Ltd. occupies a specialized position serving defense and satellite platform requirements. Toray Industries, Inc. represents the diversified portfolio archetype, leveraging scale advantages across multiple carbon fiber technologies. These three Japanese entities anchor competitive dynamics through distinct feedstock strategies and customer access models.
| Leading Market Players |
|---|
| Mitsubishi Chemical Carbon Fiber and Composites, Inc. |
| Nippon Graphite Fiber Co., Ltd. |
| Toray Industries, Inc. |
| Teijin Limited |
| Hexcel Corporation |
| SGL Carbon |
| Kureha Corporation |
| Syensqo |
| Tasuns Composite Technology Co., Ltd. |
| Others |
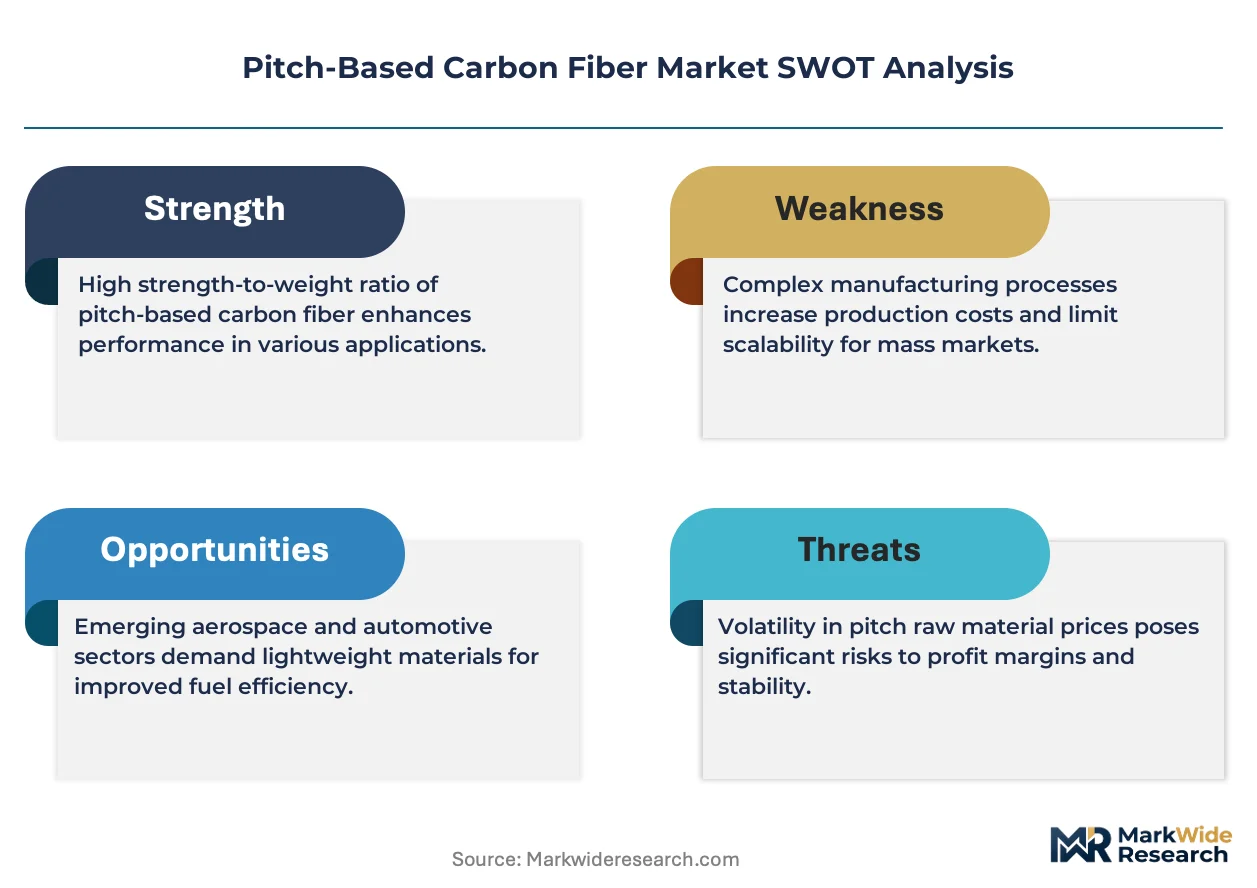
Cost & Logistics Intelligence
FAA and EASA qualification protocols gate both supplier eligibility and price differentiation simultaneously, with certification status separating premium-tier continuous fiber from standard-grade alternatives in aerospace procurement. This regulatory scaffolding concentrates pricing power among incumbent producers while forcing buyers into long-term offtake commitments that lock in cost structures before commercialization.
Pricing Analysis
Configured-to-order fiber grades command spreads of 40-60% above standard catalog pricing, with modulus thresholds above 400 GPa and out-of-autoclave prepreg formats capturing the steepest premiums. Contract-based long-term offtake dominates procurement for high-modulus grades, with price differentiation driven by certification tier and volume scale. Cost compression in standard continuous fiber intensifies as Chinese wind turbine OEMs qualify domestic sources. Satellite constellation operators show least price sensitivity, while automotive brake system buyers prioritize conversion economics over modulus optimization.
Supply Chain Analysis
Strategic stockpiling of mesophase pitch precursors prevails among Japanese and US aerospace contractors, while Chinese wind developers favor just-in-time procurement from qualifying domestic sources. Feedstock supply concentrates in Japan, the United States, and China, with petroleum-derived precursor synthesis drawing from specialized petrochemical complexes. Carbonization furnace capacity and specialized technician pools rest on concentrated geographic footprints. Single-source vulnerability in high-modulus fiber above 350 GPa intensifies under METI export controls. Distribution runs through direct OEM-producer relationships for premium grades, with distributor networks serving industrial and automotive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pitch-based carbon fiber operates as a regulatory-entrenchment defensive moat, where multi-year FAA and EASA qualification timelines create switching costs that cement incumbent positions before commercial volumes materialize.
For Market Incumbents: Consolidate backward control over mesophase pitch synthesis to defend feedstock quality advantages against emerging Chinese precursor producers. Lock in carbonization furnace capacity expansion ahead of satellite constellation deployment phases. Prioritize plasma-assisted oxidative stabilization R&D to compress cycle times and extend cost leadership.
For New Entrants and Emerging Players: Anchor in automotive brake system compounds and industrial heat shield applications where chopped fiber formats bypass aerospace qualification barriers. Target India's PLI scheme incentives for advanced materials manufacturing to establish qualification pathways before aerospace tier-one penetration. Pursue resin transfer molding partnerships with EV braking assembly suppliers as the primary go-to-market angle.
For Investors and Strategic Acquirers: METI export control tightening reshapes the acquisition landscape toward US and European assets with domestic qualification histories. Five-to-ten year viability favors specialized high-modulus fiber producers with captive precursor supply and established defense platform relationships. Monitor Bureau of Industry and Security licensing expansion as the inflection signal for strategic asset scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Mitsubishi Chemical's mesophase pitch control secures feedstock quality and cost position against petrochemical volatility. |
| Long-term Supply Agreement | Satellite constellation operators bypass distributor networks to lock in 5-7 year capacity for megaconstellation deployment. |
| Capacity Expansion | Carbonization furnace additions in Huntsville and Denver clusters reduce US aerospace import dependency under BIS licensing. |
| Joint Venture | Domestic qualification partnerships in Jiangsu and Guangdong enable Chinese turbine OEMs to meet MIIT GB standards ahead of procurement windows. |
| Technology Licensing | Plasma-assisted oxidative stabilization pilots in Japanese and US tier-one suppliers halve processing cycle times for ultra-high modulus grades. |
Research Approach
Cross-validation between primary interviews with carbonization furnace operators, aerospace procurement directors, and wind turbine blade engineers and secondary validation through customs trade data, SEC 10-K filings, and MIIT enforcement records anchors the qualitative findings. Bottom-up and top-down triangulation reconciles precursor production volumes with downstream composite fabrication capacity across the analysis window.
Sensitivity analysis around modulus threshold demand elasticity and carbonization energy cost trajectories informs the analytical framework across the projection horizon. Segmentation dimensions span product format, application tier, end-user procurement sophistication, and thermal processing technology. CAGRs derive from installed base growth in satellite constellations and offshore wind blade scaling, with plasma-assisted processing adoption curves and export control expansion scenarios as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained aerospace qualification timelines and Chinese domestic substitution rates; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as METI regulatory enforcement and Bureau of Industry and Security licensing thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Triacetate Cellulose Market
Fibers
Metal Fiber Felt Market
Fibers
Ceramic Fiber Market
Fibers
Global Electronic Fiberglass Market
Fibers
Keratin Market
Fibers
Global Concrete Fiber Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Global Fiberglass Mold Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
Global Nylon Monofilament Market
Fibers
Viscose Filament Yarn Market
Fibers
Global Fiberglass Market
Fibers
Viscose Market
Fibers
Carbon Fiber Market
Fibers
E-Glass Fiber Market
Fibers
Polytetrahydrofuran Market