
 Microfibrillated Cellulose (MFC) Market | 2026-2036
Microfibrillated Cellulose (MFC) Market Size, Share, and Industry Trends Forecast 2026-2036
Microfibrillated Cellulose (MFC) Market Foresight
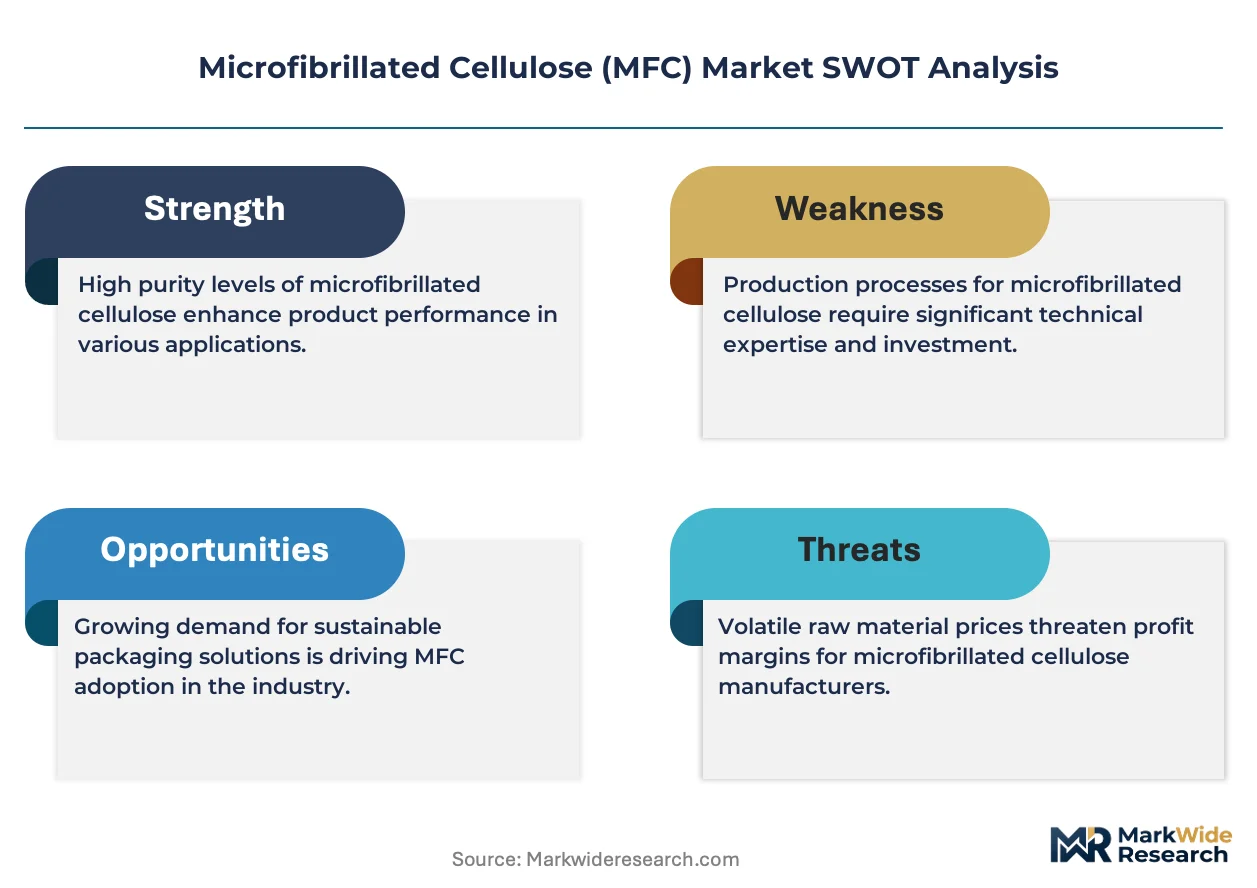
Food-grade purity certification is collapsing the gap between laboratory MFC and commercial-scale supply. CelluForce leverages its Quebec-based demonstration plant to sustain North American output for barrier coatings. Borregaard ASA anchors Scandinavian supply through its Sarpsborg biorefinery complex, while Stora Enso Oyj dominates integrated pulp-to-MFC pathways across Finnish mill networks.
Microfibrillated cellulose consists of cellulose fibrils disintegrated to diameters below 100 nanometers through mechanical shearing or enzymatic pretreatment, yielding high aspect-ratio particles with tensile strength exceeding 1 GPa and surface area above 100 m²/g. Dry MFC leads current revenue pools due to logistics efficiency and shelf stability, though wet MFC suspensions are capturing fastest growth in on-site paper mill integration where slurry-to-web addition eliminates redispersion costs. MFC composites within plastics applications concentrate margin pools where loadings above 20% w/w deliver comparable stiffness to glass fiber at reduced density.
EU REACH restrictions on microplastics and FDA food-contact substance notifications shape product development pathways and market access conditions for MFC suppliers targeting packaging and food applications. ECHA's ongoing polymer registry updates and the EU Green Deal's biobased content thresholds are forcing reformulation commitments across European converters. Stakeholders must monitor how ISO/TC 61 nanocellulose standardization timelines intersect with national biobased procurement mandates to time capacity commitments and certification investments.
Market Dynamics
EU REACH microplastic restrictions and FDA food-contact substance notifications are forcing converters to requalify barrier coatings around bio-based alternatives, compressing qualification timelines and redirecting R&D spend toward cellulose-derived solutions.
Growth Catalysts
- EU Green Deal biobased content thresholds:Packaging converters across Germany, France, and Italy face mandatory minimums for renewable feedstocks in single-use applications, accelerating MFC qualification for barrier films.
- Mechanical shearing efficiency gains:High-pressure homogenization advances have reduced energy intensity per kilogram of fibril output by enabling continuous-flow processing at industrial scale.
- Pulp mill integration models:Finnish and Swedish producers are colocating MFC production lines within existing kraft pulp facilities, eliminating transport costs for wet suspensions.
Market Restraints
- Enzymatic pretreatment input costs:Specialized cellulase enzymes required for controlled fibrillation carry price volatility tied to fermentation capacity constraints in pharmaceutical-grade bioprocessing.
- Scandinavian supply concentration:Borregaard ASA and Stora Enso Oyj control integrated pulp-to-MFC pathways, creating geographic dependency for European buyers seeking food-grade certification.
- Glass fiber substitution economics:Established thermoplastic composites with 30% glass loading maintain cost advantages in automotive structural applications where density reduction carries insufficient premium.
Strategic Opportunities
- US barrier coating penetration:FDA food-contact substance notification pathways for MFC remain underutilized relative to European regulatory maturity, creating first-mover positioning for Quebec and Maine production assets.
- ISO/TC 61 nanocellulose standardization:Anticipated publication of measurement protocols will reduce buyer qualification risk and enable specification-driven procurement across Japanese and South Korean packaging markets.
- Direct-to-mill slurry distribution:Tanker-based wet MFC logistics eliminate redispersion costs and shelf-stability concerns for paper mills in the Hamburg industrial corridor.
Industry Challenges
- Rheology control expertise gap:Formulation chemists capable of stabilizing high-concentration MFC suspensions without aggregation or gelation remain scarce across European coating houses.
- Food-grade certification timelines:EFSA novel food and food-contact assessments for enzymatically processed cellulose extend 18-24 months, delaying revenue recognition for pilot-scale producers.
- Legacy paper machine retrofit complexity:Wet-end addition systems for MFC slurry require headbox modifications and drainage table adjustments that disrupt production schedules during commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microfibrillated Cellulose (MFC) Market |
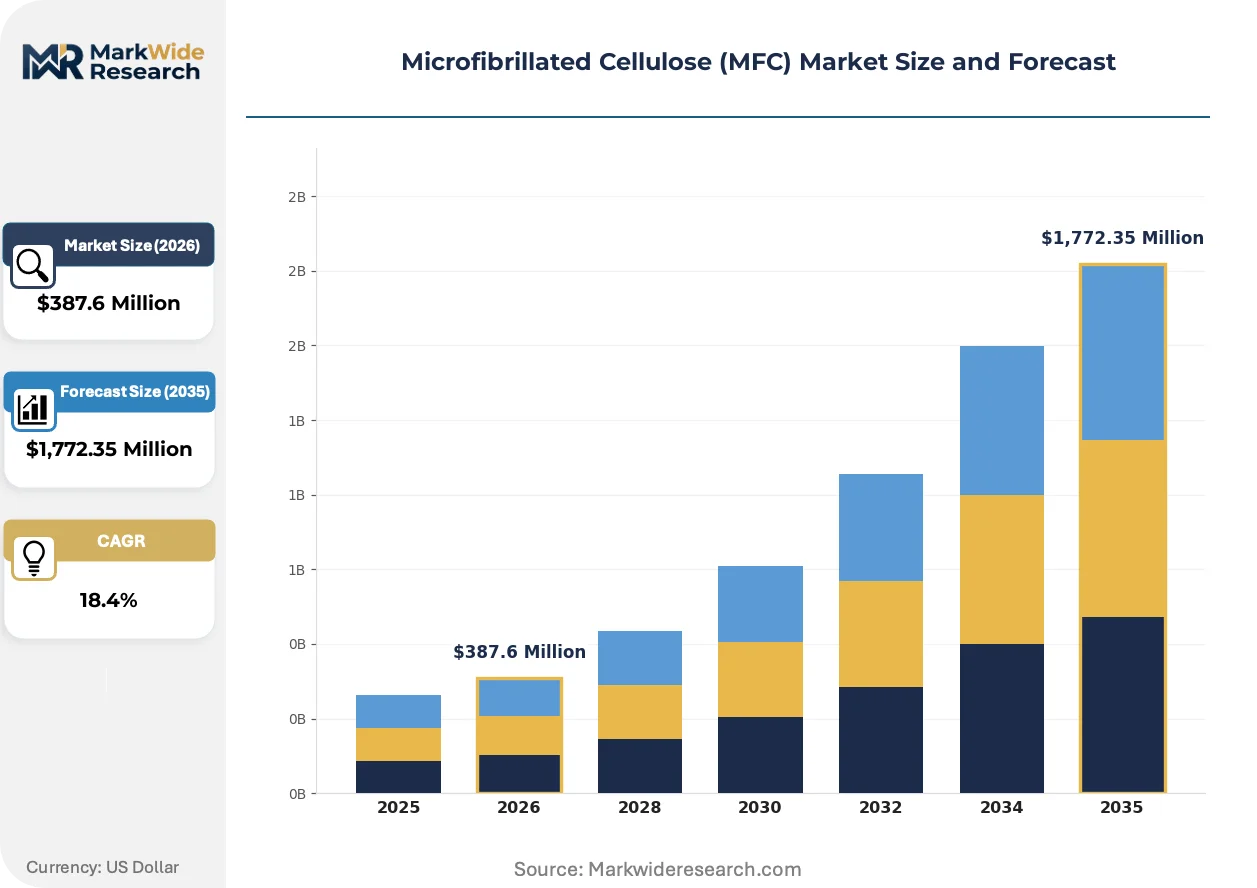
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry MFC, Wet MFC, MFC Composites, MFC Suspensions Application: Paper & Pulp, Food Industry, Coatings, Plastics End User: Packaging, Construction, Personal Care, Pharmaceuticals Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Nippon Paper Industries, Innventia AB, CelluForce, Sappi, Daicel Corporation, Borregaard ASA, FiberLean Technologies, Cellucomp Ltd, Stora Enso Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microfibrillated Cellulose (MFC) Market Shifts & Advancements
Active differentiation between dry and wet MFC processing pathways is reshaping capital deployment and logistics strategies across the value chain, with implications for regional production economics and buyer procurement models.
Enzymatic pretreatment protocols for controlled fibrillation are bifurcating the technology landscape from purely mechanical shearing approaches. Specialty paper producers in Japan and South Korea favor enzymatic routes for consistent aspect-ratio distribution in high-barrier coatings. This split is compressing equipment supplier margins in mechanical homogenization while creating premium positioning for biotechnology licensors.
REACH restrictions on intentionally added microplastics entered enforcement phase for leave-on cosmetics and are extending to packaging films through ECHA polymer registry updates. German converters near Düsseldorf industrial corridors are pre-qualifying MFC barrier layers to maintain EU market access. The regulatory pressure is accelerating substitution timelines beyond what pure cost economics would justify.
Buyer specification practices are hardening around surface area and aspect-ratio metrics rather than supplier brand or origin claims. Tier-one packaging houses in France and Italy now require ISO-compliant characterization data for every lot, displacing relationship-based procurement. This shift is most visible in pharmaceutical blister pack applications where barrier performance must be documented for FDA submissions.
Microfibrillated Cellulose (MFC) Market Segmentation
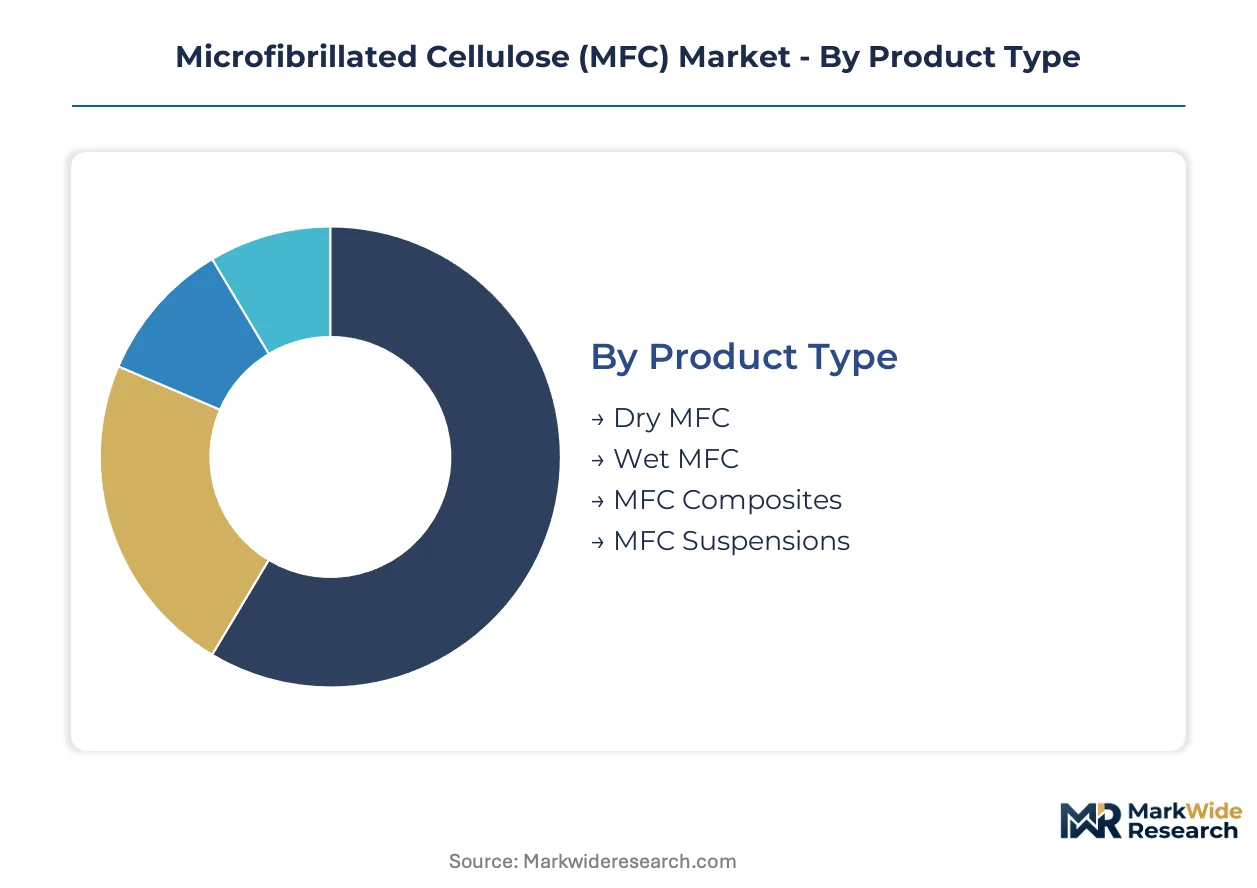
Channel configuration varies sharply across MFC product forms, with wet suspensions flowing through direct mill relationships while dry grades move through distributor networks. End-use qualification requirements further fragment procurement pathways, as food-contact certifications restrict supplier pools for packaging converters.
Product Type:
Dry MFC dominates distributor and wholesaler channels due to shelf stability and lower transport costs, while wet suspensions flow almost exclusively through direct sales to integrated pulp mills.
- Dry MFC:Spray-dried or freeze-dried fibril aggregates with moisture content below 10% enable long-haul logistics without refrigeration. German packaging converters near Düsseldorf source primarily through distributors stocking Borregaard and Stora Enso grades for barrier coating trials.
- Wet MFC:Aqueous suspensions at 2-10% solids concentration eliminate redispersion costs for paper mills but require tanker or rail delivery within 300-kilometer radii. Finnish kraft producers capture fastest adoption through colocated production lines at Sarpsborg and Kotka mill complexes.
- MFC Composites:Pre-compounded masterbatches with thermoplastic matrices move through specialty chemical distributors serving automotive and construction compounders.
- MFC Suspensions:Higher-concentration slurries at 15-20% solids for on-site dilution; direct sales predominate with technical service requirements.
By volume, Dry MFC leads. By growth pace, Wet MFC is expanding most quickly.
Application:
Margin structures diverge across applications, with pharmaceutical and food-contact coatings commanding certification premiums while paper processing runs on volume efficiency.
- Paper & Pulp:Wet-end addition for strength enhancement and surface sizing; integrated mill procurement eliminates distribution markups. Stora Enso's Finnish network anchors supply for magazine and packaging paper grades.
- Food Industry:Barrier coatings for oil and grease resistance in fast-food packaging; FDA and EFSA food-contact notifications required. CelluForce Quebec output serves North American converters awaiting regulatory pathway clarity.
- Coatings:Rheology modifiers and film-forming agents for industrial and decorative applications; distributor channels predominate with formulation technical support.
- Plastics:Reinforcement in PLA and PBS biopolymers; compounder direct relationships with minimum order thresholds.
Revenue concentration sits with Paper & Pulp. Certification complexity drives fastest expansion in Food Industry applications.
End User:
Procurement sophistication varies by end user, with pharmaceutical buyers demanding lot-specific characterization data while construction markets prioritize price and availability.
- Packaging:Tier-one European converters in France and Italy now require ISO-compliant surface area and aspect-ratio data for every lot, displacing relationship-based purchasing. ECHA polymer registry updates on microplastics accelerate MFC barrier layer qualification.
- Construction:Cement rheology modification and insulating panel applications; price-sensitive procurement through regional building material distributors.
- Personal Care:Leave-on cosmetic formulations face REACH microplastic restrictions; enzymatic MFC routes preferred for consistent fibril dimensions in Japanese and South Korean markets.
- Pharmaceuticals:Blister pack barrier films and tablet coatings; FDA submission documentation requirements restrict supplier pools to certified producers.
Packaging commands volume leadership. Pharmaceutical qualification timelines create steepest expansion trajectory for certified suppliers.
Distribution Channel:
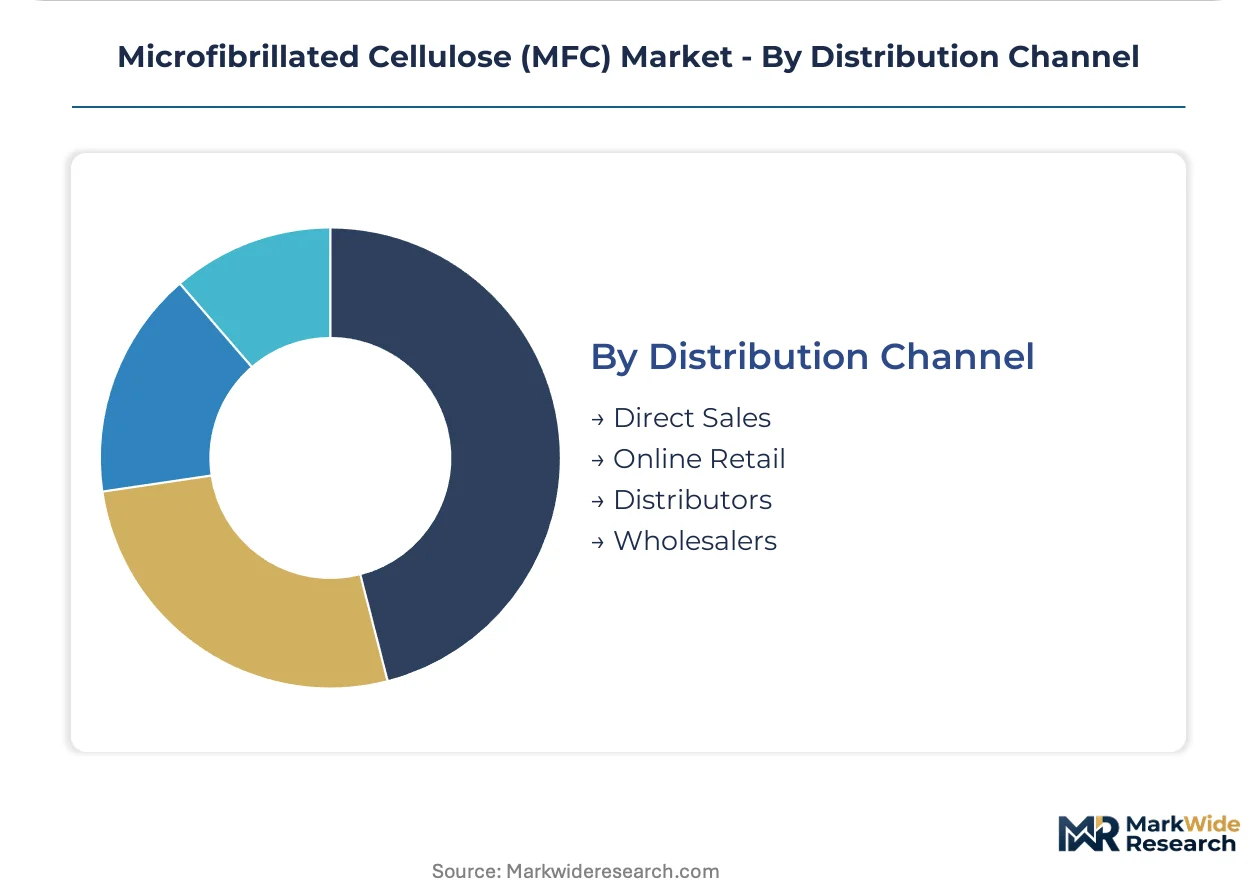
Channel selection tracks product form and buyer technical capability, with direct sales capturing complex wet suspensions and online retail emerging for sample quantities and R&D grades.
- Direct Sales:Wet MFC slurries and high-volume dry contracts; technical service engineers coordinate rheology stabilization protocols with buyer formulation teams.
- Online Retail:Kilogram-scale dry MFC for university and startup R&D limited to non-food-grade specifications.
- Distributors:Pan-European chemical distributors stock dry MFC for coatings and plastics compounders; inventory carrying costs reflected in 15-25% markups.
- Wholesalers:Construction-sector building material wholesalers for cement additive applications; lowest service intensity, price-driven selection.
Direct Sales handles majority volume. Online Retail climbs fastest as sample-to-scale purchasing patterns emerge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated pulp-to-MFC production concentrates in Nordic and German industrial corridors, while North American capacity expansion targets food-contact certification gaps. Japanese and South Korean converters drive enzymatic processing adoption for precision barrier applications.
Germany
Packaging converters near Düsseldorf and Hamburg industrial zones are pre-qualifying MFC barrier layers for EU Green Deal compliance. ECHA polymer registry updates on intentionally added microplastics accelerate substitution timelines for flexible films. Pilot production lines near Hamburg are scaling wet MFC slurry supply to paper mills across the Lower Saxony corridor.
Finland
Stora Enso's integrated kraft pulp networks anchor European wet MFC supply through colocated fibrillation lines at Kotka and other mill complexes. EU REACH restrictions on microplastics redirect R&D budgets toward bio-based barrier coatings. The Finnish forest industry's captive pulp supply eliminates transport costs for high-volume wet suspension delivery.
United States
FDA food-contact substance notification pathways for MFC remain underutilized relative to European regulatory maturity, creating positioning opportunities for Quebec-linked production assets. Maine and Vermont pulp mill retrofits are evaluating direct-to-mill slurry distribution models. North American barrier coating demand concentrates in food packaging converters serving quick-service restaurant chains.
Japan
Specialty paper producers favor enzymatic pretreatment routes for consistent fibril aspect-ratio distribution in pharmaceutical blister pack applications. METI biobased content guidelines and JIS standardization timelines shape procurement specifications for barrier films. Industrial clusters in the Kanto region around Tokyo are qualifying MFC coatings for oxygen and moisture resistance.
Norway
Borregaard ASA's Sarpsborg biorefinery complex anchors Scandinavian food-grade MFC supply through integrated softwood pulp processing. EFSA novel food assessment timelines for enzymatically processed cellulose extend qualification periods for pilot-scale entrants. The Oslofjord industrial corridor links fibrillation capacity to European packaging converter networks via short-sea shipping.
Microfibrillated Cellulose (MFC) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the MFC value chain. Integrated forest products groups with captive pulp supply dominate wet suspension economics, while specialized fibrillation technology licensors command premium positioning in enzymatic processing segments. The competitive terrain splits between scale-driven pulp mill integrators and precision-focused biotechnology specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves, with colocation agreements reducing logistics costs for high-moisture product forms.
Within the integrated pulp-to-MFC tier, Stora Enso Oyj and Borregaard ASA exemplify the Nordic model of captive fiber supply and colocated fibrillation. CelluForce occupies a position representing North American demonstration-scale production targeting food-contact certification pathways. Nippon Paper Industries and Daicel Corporation anchor Japanese supply for precision barrier applications. These named entities sit within broader archetype categories rather than representing exhaustive market coverage.
| Leading Market Players |
|---|
| Nippon Paper Industries |
| Innventia AB |
| CelluForce |
| Sappi |
| Daicel Corporation |
| Borregaard ASA |
| FiberLean Technologies |
| Cellucomp Ltd |
| Stora Enso Oyj |
| Others |
Supply & Pricing Matrix
Glass fiber substitution in automotive structural panels simultaneously redraws procurement geography toward Nordic pulp corridors and compresses margin tolerance for MFC compounders competing against established thermoplastic supply chains.
Pricing Analysis
EU REACH microplastic restrictions dictate the pricing tier structure across European packaging markets. Three-tier pricing stratifies across food-contact certified, industrial-grade, and R&D sample volumes. Certification premiums for EFSA-notified grades widen spreads as enzymatic processing costs feed into specialty barrier coatings. Paper mills in the Hamburg corridor exhibit highest price sensitivity due to direct slurry integration eliminating distributor markups.
Supply Chain Analysis
Finland and Norway anchor integrated pulp-to-MFC production through colocated fibrillation at kraft mill complexes. Softwood pulp feedstock draws from Scandinavian forest concessions with long-term harvesting rights. Single-source vulnerability concentrates in enzymatic pretreatment enzymes fermented through pharmaceutical-grade bioprocessing capacity. Distribution runs through tanker-based wet slurry delivery within 300-kilometer radii and pan-European chemical distributor networks for dry grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for rheology stabilization and formulation support expand faster than base MFC volume, creating recurring-revenue layers that deepen customer switching costs.
For Market Incumbents: Shield food-contact certification moats by accelerating EFSA novel food assessment pipelines before enzymatic processing patents expire. Vertical integration into captive cellulase fermentation capacity neutralizes input cost volatility from pharmaceutical-grade bioprocessing suppliers. For New Entrants and Emerging Players: FDA food-contact substance notification fast-tracks offer positioning leverage in North American barrier coating markets underserved relative to European regulatory maturity. Target Maine and Quebec pulp mill retrofits evaluating direct-to-mill slurry distribution. Lead with technical service partnerships that bridge rheology expertise gaps at coating houses. For Investors and Strategic Acquirers: EU Green Deal biobased content thresholds reshape the acquisition landscape toward integrated pulp-to-MFC assets with captive fiber supply. Long-term viability hinges on colocation economics and certification pipeline depth rather than standalone fibrillation technology. Watch ISO/TC 61 nanocellulose standardization publication as inflection signal for specification-driven procurement adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Colocated fibrillation lines at Finnish kraft mills eliminate wet slurry transport costs. |
| Backward Integration | Captive softwood pulp supply secures feedstock access for food-grade MFC output. |
| Regulatory Certification | EFSA novel food assessments open pharmaceutical blister pack barrier film markets. |
| Joint Venture | Pulp mill partnerships share retrofit capital for wet-end addition system deployment. |
| Technology Licensing | Enzymatic pretreatment protocols command premiums in Japanese precision coating segments. |
Research Methodology
A standing panel of fibrillation plant managers, packaging converter procurement leads, coating house formulation chemists, and pulp mill technical directors provided ongoing calibration across primary interview rounds. Secondary validation drew from ECHA polymer registry filings, EU Green Deal implementation trackers, FDA food-contact substance notification databases, and SEC disclosures from listed forest products groups. Bottom-up volume builds and top-down macro constraint checks ensured triangulation integrity.
Consistency checks against external benchmarks validated projections across the modeling period. Segmentation dimensions spanned product form, application end-use, and regional regulatory cluster. CAGRs derived from slope analysis of fitted adoption curves with inflection adjustments for standardization milestones. Industry-specific inputs included enzymatic processing efficiency trajectories and pulp mill integration capex cycles.
Underlying assumptions cover REACH enforcement continuity and biobased procurement mandate adoption, with deviation risk concentrated in EFSA assessment timeline extensions and cellulase fermentation capacity constraints. Recalibration cycles align with material shifts in polymer registry updates and ISO standardization publication schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
Polytetrahydrofuran Market
Fibers
Viscose Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
North America Glass Fiber Reinforced Gypsum Market
Fibers
Fiberglass Cloth Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Metal Fiber Felt Market
Fibers
Global Basalt Fiber Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
Thermoformed Fiber Market
Fibers
Global Bicomponent Fiber Market
Fibers
E-Glass Fiber Market
Fibers
High Temperature Superconducting Fibers Market
Fibers
Citrus Pulp Fiber Market
Fibers
Artificial Muscle Fibers Market